
 Mining and Oil & Gas Fasteners Market | 2026-2036
Mining and Oil & Gas Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Mining and Oil & Gas Fasteners Market Analytics
Australia is tilting toward expanded fastener capacity to service Pilbara iron ore expansions and Queensland coal maintenance schedules. Elgin Fastener Group LLC anchors North American production through integrated forging and threading operations for oilfield bolting. MW Industries, Inc. dominates precision cold-heading capacity serving downhole tool assemblers. American Fastener Technologies Corporation specializes in exotic alloy fasteners meeting NACE MR0175 sour service specifications.
Mining and Oil & Gas Fasteners are mechanical joining elements manufactured to ASTM, API, or ISO dimensional and strength grades, typically from carbon steel, stainless steel, or nickel alloys through hot forging, cold heading, or machining processes, designed to resist vibration, corrosion, and extreme mechanical loads in extraction and processing equipment. Their primary purpose is maintaining structural integrity of drilling rigs, haul trucks, processing vessels, and pipeline infrastructure under cyclic stress and environmental exposure. Bolts and alloy material grades command premium positioning due to fatigue-life requirements in subsea blowout preventer stacks and crusher mill lining systems. Stainless steel fasteners for corrosive processing environments represent the fastest-growing material category as brine and sulfide exposure intensifies.
API 20E and API 20F govern alloy and carbon steel bolting for wellhead and Christmas tree applications, while ASTM A193 and ASTM A320 govern pressure vessel and low-temperature service hardware, collectively mandating traceable heat treatment and mechanical testing that elevates supplier qualification barriers. OSHA 1910 subpart O and MSHA 30 CFR Part 56 impose equipment guarding and machinery maintenance standards that drive scheduled fastener replacement programs at surface mines and drilling pads. Stakeholders must monitor API specification revisions and carbon border adjustment mechanisms to calibrate sourcing strategies and alloy grade portfolios.
Market Dynamics
API 20E compliance mandates are compressing supplier qualification timelines while simultaneously elevating material certification costs, forcing procurement teams to consolidate vendor relationships around heat-treatment-capable manufacturers with integrated metallurgical testing.
Growth Catalysts
- Offshore Brazil exploration:Deepwater drilling contractors are expanding fastener procurement for subsea blowout preventer stacks as pre-salt field development accelerates.
- API 20E Bolting Specification:Tightened alloy certification requirements are locking in premium-grade suppliers and displacing uncertified competitors from wellhead applications.
- Permian Basin rig density:Sustained well completion rates in West Texas and southeastern New Mexico are driving replacement cycles for high-stress connection hardware.
Market Restraints
- Nickel alloy price volatility:Inconel and Monel feedstock cost swings compress margin predictability for sour service fastener producers.
- Heat treatment capacity concentration:North American vacuum furnace availability clusters in Ohio and Pennsylvania, creating geographic supply risk for time-critical oilfield orders.
- ASTM A320 L7M substitution ceiling:Low-temperature carbon steel bolting faces performance limits in Arctic LNG applications that superduplex stainless can address but at 4x cost.
Strategic Opportunities
- Western Australia Pilbara expansion:Rio Tinto and BHP iron ore capacity additions are generating demand for haul truck and crusher mill lining fasteners with 50,000-hour fatigue life specifications.
- CCUS infrastructure:Carbon capture wellhead retrofits require sour service compliant bolting that exceeds legacy API 6A pressure ratings.
- Digital thread integration:Blockchain-enabled material traceability from melt to installation is emerging as a procurement differentiator for supermajor drilling contractors.
Industry Challenges
- Metallurgical technician scarcity:Vacuum heat treatment operation and mechanical testing interpretation skills are aging out of the workforce faster than apprenticeship programs replenish them.
- NACE MR0175/ISO 15156 certification lag:Third-party sour service qualification timelines extend 14-18 weeks, delaying contract execution for urgent replacement orders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining and Oil & Gas Fasteners Market |
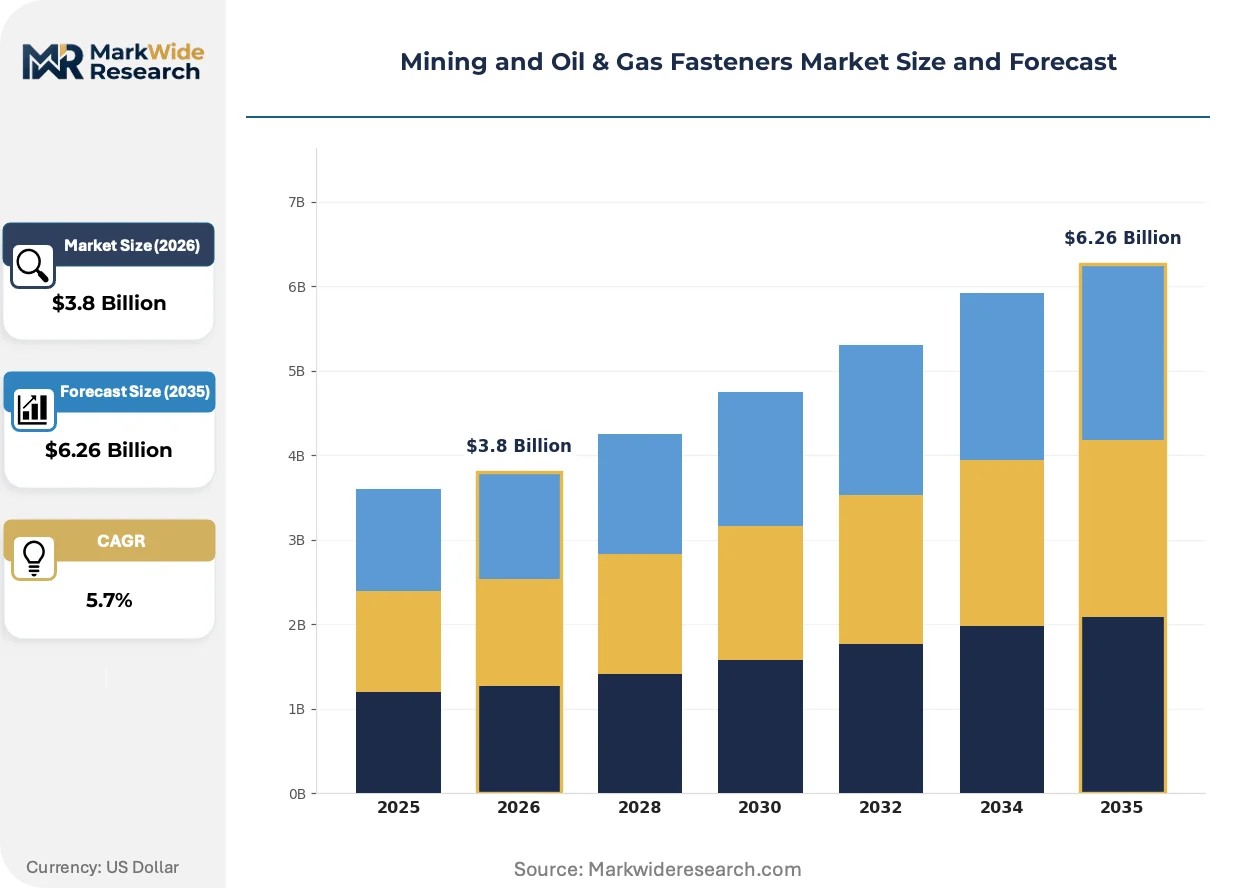
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Anchors Application: Drilling, Construction, Equipment Assembly, Maintenance Material: Steel, Stainless Steel, Alloy, Plastic End User: Mining Companies, Oil Producers, Service Contractors, Others |
| Companies Covered | Hague Fasteners Limited, Elgin Fastener Group LLC, National Bolt & Nut Corporation, LSP Holding (UK) LTD, MW Industries, Inc., American Fastener Technologies Corporation, Master Bolt, LLC, Dokka Fasteners A S, STANLEY Engineered Fastening, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining and Oil & Gas Fasteners Market Evolving Landscape
Additive manufacturing of nickel superalloy fasteners is collapsing traditional forging lead times for complex subsea connector geometries. Cold spray deposition is eliminating machining waste in downhole tool assembly. Procurement digitization is compressing supplier discovery cycles from months to weeks.
Cold spray solid-state deposition is collapsing conventional machining and welding steps for Inconel 718 downhole housing fasteners. Directional drilling contractors in the Permian Basin are adopting additively manufactured thread forms that withstand 30,000 psi burst pressures. This compression of manufacturing steps is reducing material waste by 60 percent while enabling lot sizes below 50 units.
OSHA 1910 subpart O machinery guarding mandates are accelerating scheduled fastener replacement programs at surface mining operations. The enforcement priority on crusher and conveyor maintenance is forcing mine operators to document torque specifications and replacement intervals. Appalachian coal producers are responding by integrating RFID-tagged bolting into preventive maintenance software.
Drilling contractors are unbundling fastener supply from rig OEM maintenance contracts and sourcing directly through API-licensed distributors. This disintermediation is compressing price discovery cycles and exposing incumbent rig builders to margin pressure on spare parts. The shift is most visible in the Gulf of Mexico, where independent offshore contractors now specify bolting separately from BOP stack procurement.
Mining and Oil & Gas Fasteners Market Segmentation
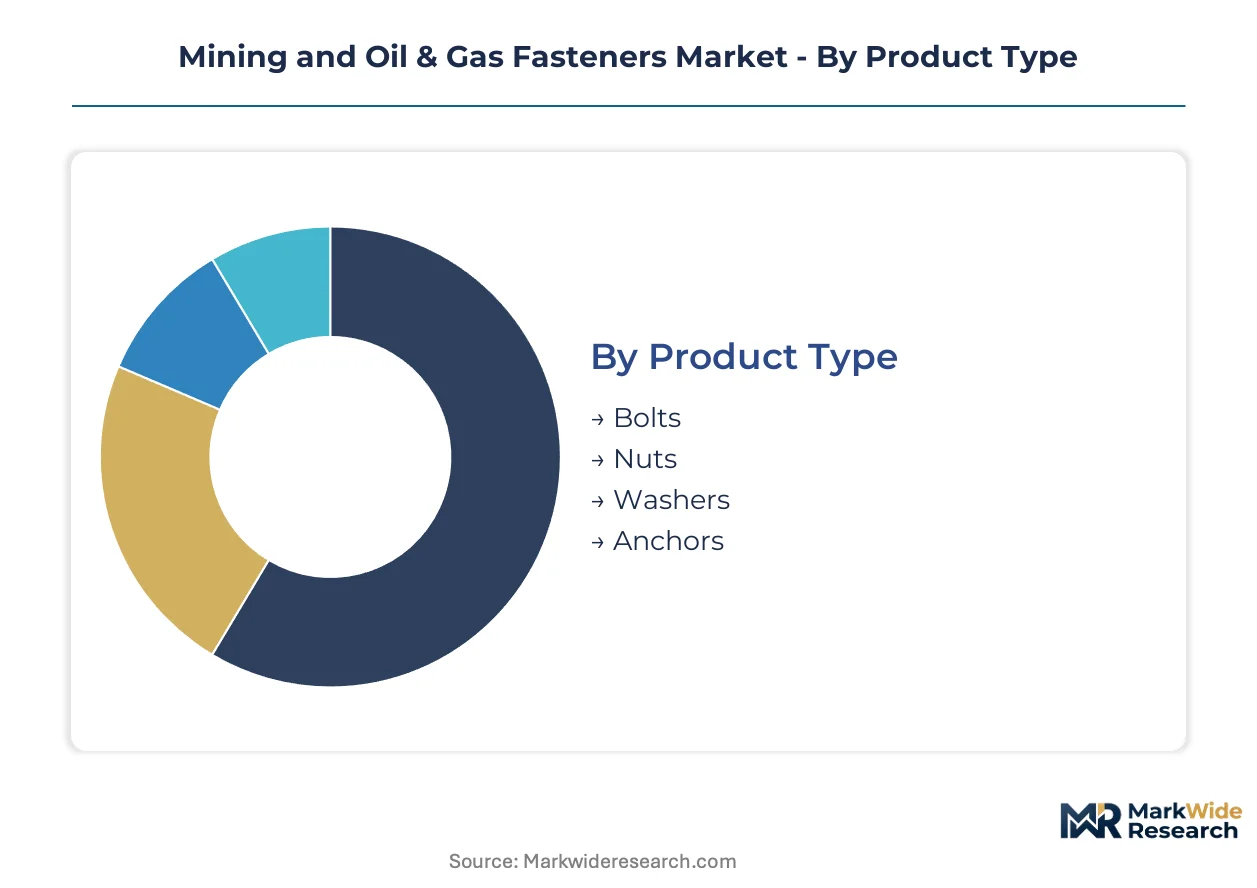
Fastener procurement in extraction industries splits across load-bearing specifications, environmental exposure severity, and replacement cycle predictability. Each segmentation dimension carries distinct margin structures and supplier qualification barriers.
Product Type:
Application intensity and failure consequence severity separate these hardware categories by cost tier and certification depth.
- Bolts:Threaded fasteners manufactured to ASTM A193, API 20E, and API 20F specifications dominate high-stress wellhead and subsea blowout preventer installations. Demand concentrates in Permian Basin drilling contractors sourcing alloy grades with full material traceability for Christmas tree assemblies.
- Nuts:Hex and heavy-hex configurations paired with stud bolts in pressure vessel flanges require matched strength grades and documented proof load testing. Pilbara iron ore expansions are driving procurement of fatigue-rated nut-bolt combinations for haul truck chassis.
- Washers:Hardened flat and lock washers distribute clamping loads in vibrating crusher mill environments.
- Anchors:Expansion and adhesive anchors secure processing equipment to concrete foundations at surface mining operations.
Bolts hold installed capacity. Washers are rotating up the share rankings as maintenance programs standardize complete fastener system replacement.
Application:
Operational phase determines specification stringency and procurement urgency across the asset lifecycle.
- Drilling:Rotary table and mast connection hardware faces cyclic tension-compression loading that mandates ultrasonic testing and magnetic particle inspection. Deepwater pre-salt fields offshore Brazil are expanding sour service bolting procurement for subsea BOP stacks exposed to high-pressure hydrogen sulfide environments.
- Construction:Temporary and permanent structural bolting for processing plants and pipeline compressor stations follows AWS D1.1 and AISC 360 specifications. Queensland coal infrastructure maintenance schedules are sustaining demand for galvanized structural assemblies.
- Equipment Assembly:OEM line-fit fasteners for crushers, conveyors, and drilling rigs ship with torque specification documentation.
- Maintenance:Scheduled replacement programs driven by OSHA 1910 machinery guarding enforcement prioritize RFID-tagged bolting with documented installation intervals.
Drilling commands specification premiums. Maintenance is climbing the fastest as predictive analytics compress replacement cycles.
Material:
Corrosion resistance and mechanical strength requirements stratify feedstock selection by exposure environment.
- Steel:Carbon and low-alloy grades governed by ASTM A320 and ASTM A194 specifications serve general pressure vessel and structural applications where cost sensitivity dominates. Permian Basin rig contractors specify L7 and L43 grades for standard wellhead bolting without sour service exposure.
- Stainless Steel:Austenitic and duplex grades meeting NACE MR0175/ISO 15156 resist chloride and sulfide stress cracking in brine processing and offshore environments. This category is expanding most quickly as produced water handling intensifies corrosion exposure across shale plays.
- Alloy:Inconel, Monel, and superduplex grades withstand extreme temperature and pressure in subsea and geothermal applications.
- Plastic:Composite and polymer fasteners provide electrical isolation and chemical resistance in specific downhole tool assemblies.
Steel holds installed capacity. Stainless steel is rotating up the share rankings as environmental regulations tighten discharge standards.
End User:
Procurement sophistication and technical specification ownership vary sharply across buyer categories.
- Mining Companies:Integrated iron ore and coal operators specify fatigue-life ratings for mobile equipment fasteners and enforce preventive maintenance documentation under MSHA 30 CFR Part 56. Western Australia Pilbara operators are consolidating supplier relationships around heat-treatment-capable manufacturers with integrated metallurgical testing.
- Oil Producers:Supermajor and independent upstream companies mandate API license status and material traceability blockchain integration for wellhead bolting. Gulf of Mexico operators increasingly specify fasteners separately from rig OEM maintenance contracts.
- Service Contractors:Drilling and completion service companies procure replacement hardware under time-critical logistics requirements.
- Others:Pipeline operators, refining companies, and carbon capture project developers complete the demand base.
Mining companies hold installed capacity. Service contractors are rotating up the share rankings as disintermediation from OEM supply chains accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Brazil and Australia prioritize subsea and mining fatigue specifications respectively, while the United States concentrates on Permian Basin replacement cycles and API certification compliance.
Brazil
Deepwater pre-salt field development is accelerating fastener procurement for subsea blowout preventer stacks. ANP regulatory oversight mandates full material traceability for wellhead bolting in high-pressure hydrogen sulfide environments. Rio de Janeiro serves as the procurement hub where drilling contractors consolidate sour service alloy orders.
Australia
Pilbara iron ore expansions are driving demand for haul truck and crusher mill lining fasteners with extended fatigue-life ratings. Western Australia's Department of Mines, Industry Regulation and Safety enforces equipment maintenance documentation under mining safety regulations. Perth-based distributors are integrating heat-treatment capabilities to service Queensland coal maintenance schedules.
United States
Permian Basin rig density sustains replacement cycles for high-stress connection hardware across West Texas and southeastern New Mexico. OSHA machinery guarding enforcement under 1910 subpart O is accelerating scheduled fastener replacement programs at surface operations. Houston functions as the primary logistics cluster where API-licensed distributors serve Gulf of Mexico offshore contractors.
Norway
North Sea subsea infrastructure maintenance is expanding procurement of superduplex stainless bolting for corrosive deepwater environments. Petroleum Safety Authority regulations mandate documented torque specifications and replacement intervals for critical connection hardware. Stavanger anchors the supplier ecosystem serving Equinor and independent offshore operators.
China
Domestic shale gas development in Sichuan Basin is increasing demand for sour service compliant bolting meeting NACE specifications. MIIT standards for petroleum equipment certification are tightening supplier qualification requirements. Chengdu-Chongqing industrial corridor is attracting heat-treatment investment to serve southwestern drilling contractors.
Mining and Oil & Gas Fasteners Market Competitive Landscape
Capability concentration sits with heat-treatment-integrated specialists; scale advantage sits with cold-heading precision manufacturers. The market structures around three tiers: API-licensed alloy bolting specialists, high-volume carbon steel producers, and regional maintenance distributors. Two dominant competitive moves are consolidating vendor relationships around metallurgical testing capabilities and expanding vacuum furnace capacity in shale-adjacent geographies.
Among North American fabricators, Elgin Fastener Group LLC and MW Industries, Inc. exemplify divergent strategic positions. Elgin anchors integrated forging and threading operations for oilfield bolting. MW Industries occupies the precision cold-heading tier serving downhole tool assemblers. American Fastener Technologies Corporation represents the specialty alloy segment with NACE sour service positioning. European presence includes Hague Fasteners Limited and LSP Holding (UK) LTD, while Dokka Fasteners A S anchors Nordic supply relationships.
| Leading Market Players |
|---|
| Hague Fasteners Limited |
| Elgin Fastener Group LLC |
| National Bolt & Nut Corporation |
| LSP Holding (UK) LTD |
| MW Industries, Inc. |
| American Fastener Technologies Corporation |
| Master Bolt, LLC |
| Dokka Fasteners A S |
| STANLEY Engineered Fastening |
| Others |
Value Network & Pricing Analysis
Houston-Stavanger freight corridors for subsea alloy bolting are compressing delivery premiums as vacuum heat treatment capacity clusters in Ohio and Pennsylvania, forcing procurement teams to absorb geographic risk premiums or consolidate around metallurgical testing-integrated suppliers with documented API 20E traceability.
Pricing Analysis
Long-term offtake contracts dominate API 20E-certified alloy bolting for wellhead applications, while spot procurement serves urgent replacement cycles in Permian Basin drilling operations. Price differentiation hinges on NACE MR0175 sour service certification and full material traceability from melt to installation. Cost compression in carbon steel structural grades is intensifying because Brazilian and Australian mining contractors are standardizing complete fastener system replacements. Junior drilling contractors exhibit highest price sensitivity, while supermajor upstream companies prioritize certification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for precision cold-heading rests with MW Industries and Elgin Fastener Group in the United States, while European heat-treatment capacity clusters around Hague Fasteners and Dokka Fasteners in the UK and Norway. Feedstock draws from nickel alloy suppliers in the United States and specialty steel mills in Germany and Japan. Single-source vulnerability concentrates in North American vacuum furnace availability for time-critical oilfield orders. Distribution runs through API-licensed distributors serving drilling contractors directly, bypassing traditional rig OEM maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
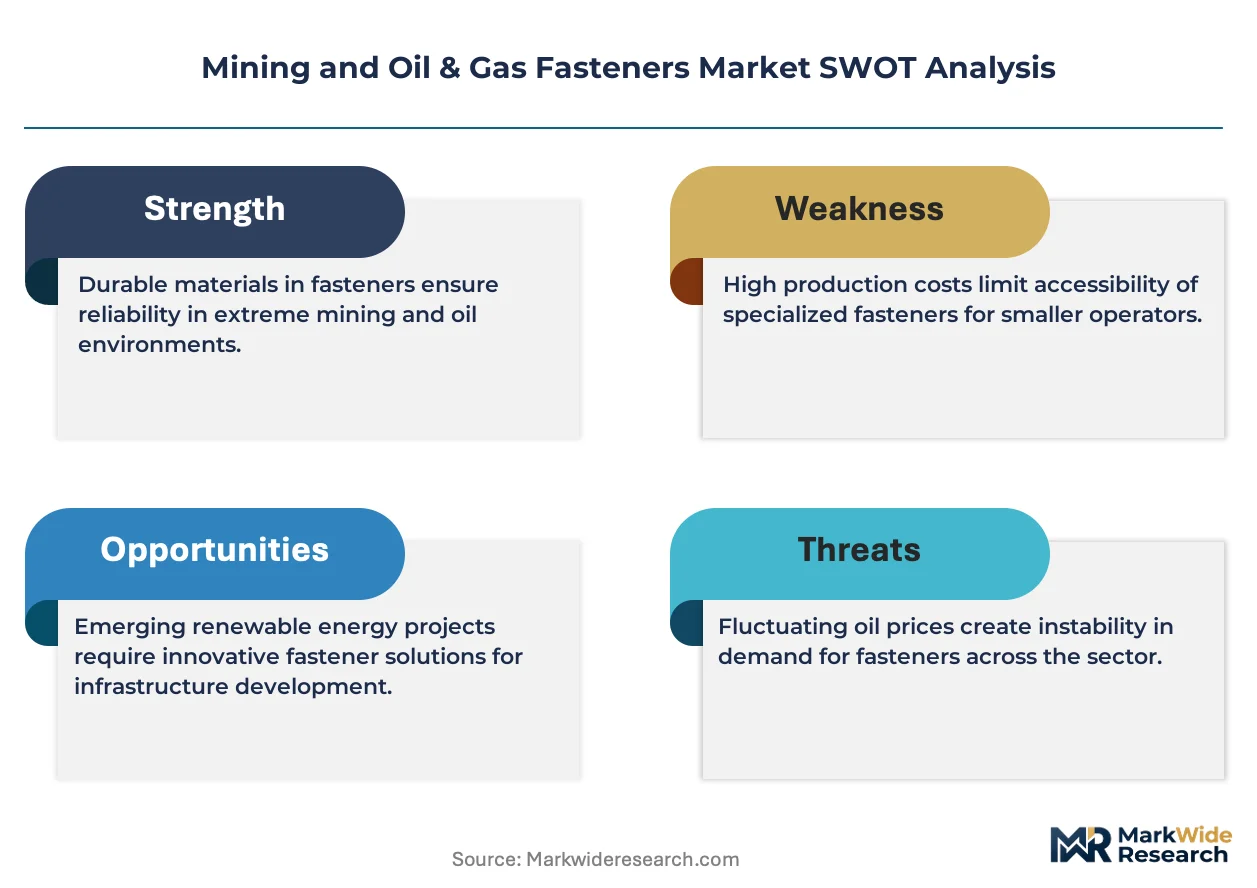
API 20E compliance mandates and blockchain-enabled material traceability are compressing supplier qualification timelines while simultaneously elevating material certification barriers, creating a high-growth disruption window for heat-treatment-integrated specialists.
For Market Incumbents: Build metallurgical testing moats by acquiring vacuum heat treatment facilities in shale-adjacent geographies like Texas and New Mexico to reduce logistics risk from Ohio-Pennsylvania capacity concentration. Expand NACE MR0175 certification capabilities to displace uncertified competitors from sour service procurement. Threat substitution comes from additive manufacturing of nickel superalloy fasteners collapsing traditional forging lead times for complex subsea geometries. For New Entrants and Emerging Players: Western Australia Pilbara iron ore maintenance schedules represent the most penetrable entry point, where Rio Tinto and BHP are consolidating supplier relationships around fatigue-rated nut-bolt combinations for haul truck chassis. CCUS infrastructure retrofits in North America offer second-mover advantage for sour service compliant bolting exceeding legacy API 6A pressure ratings. Go-to-market leverage centers on blockchain-enabled material traceability as a procurement differentiator for supermajor drilling contractors. For Investors and Strategic Acquirers: Heat-treatment-capable mid-cap specialists with integrated API licensing and geographic proximity to Permian Basin or Pilbara demand clusters offer prime acquisition targets. Long-term viability frames around 5-10 year replacement cycle compression as predictive analytics and OSHA machinery guarding enforcement accelerate scheduled fastener programs. Signal to watch is NACE certification timeline compression from current 14-18 week delays, indicating supply responsiveness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Furnace Capacity Expansion | Reduces geographic supply risk for time-critical oilfield orders from Permian Basin contractors. |
| API 20E Certification Investment | Locks in premium-grade supplier status as ANP and Petroleum Safety Authority tighten traceability mandates. |
| Blockchain Traceability Integration | Enables procurement differentiation for Equinor and independent offshore operators in North Sea subsea maintenance. |
| Sour Service Capability Buildout | Captures CCUS wellhead retrofit demand exceeding legacy pressure ratings in carbon capture infrastructure. |
| Direct Distribution Channel | Disintermediates rig OEM maintenance contracts as Gulf of Mexico contractors unbundle fastener specification. |
Research Methodology
Initial hypotheses were tested against primary input from drilling contractor procurement managers, vacuum heat treatment operations directors, mining maintenance supervisors, and API certification auditors and refined through secondary validation against SEC filings from fastener manufacturers, ANP regulatory bulletins, OSHA enforcement data, and customs trade records for nickel alloy imports. Bottom-up demand modeling from rig count and well completion data triangulated with top-down market sizing from industrial fastener trade associations.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling segmentation by product type, application phase, material grade, and end-user procurement sophistication. CAGRs derived from regression analysis against exploration capital expenditure cycles and replacement interval compression trends. Industry-specific inputs included MSHA 30 CFR Part 56 maintenance documentation requirements and API specification revision timelines.
Practitioners should monitor nickel alloy price volatility, NACE certification queue lengths, and carbon border adjustment mechanism developments for early signals of forecast revision. Quarterly review of rig count trajectories in Permian Basin and pre-salt licensing rounds offshore Brazil is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil Well Cement Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Frac Tree Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Asia-Pacific Oilfield Services Market