
 Global Bio Compatible Battery Market | 2026-2036
Global Bio Compatible Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Compatible Battery Market Intelligence
The rising prominence of wearable technology over traditional consumer electronics is realigning the market's end-use portfolio. Medtronic plc leverages its deep expertise in implantable devices to lead in high-reliability applications. Murata Manufacturing Co. Ltd. specializes in miniaturized power sources for a broad range of electronic applications. Jenax Inc. competes by focusing on flexible battery designs for next-generation wearables.
Bio compatible batteries are power sources engineered from non-toxic, biologically inert materials designed for safe operation within or in close contact with the human body. These devices often utilize specific electrolytes and encapsulation methods to prevent leakage and ensure patient safety. Within product types, lithium-ion chemistries dominate due to their energy density, while solid-state batteries represent the fastest-growing category. The form factor segment sees a clear distinction between rigid batteries for implants and flexible designs for wearable technology.
Regulatory oversight from bodies like the US FDA and the European Medicines Agency under the Medical Device Regulation (MDR) is critical. These frameworks mandate rigorous testing for cytotoxicity and long-term stability, directly influencing material selection and design. Additionally, standards like ISO 10993 provide a recognized framework for evaluating the biological safety of medical devices. A key strategic decision for manufacturers involves balancing the high cost of advanced biocompatible materials against performance requirements.
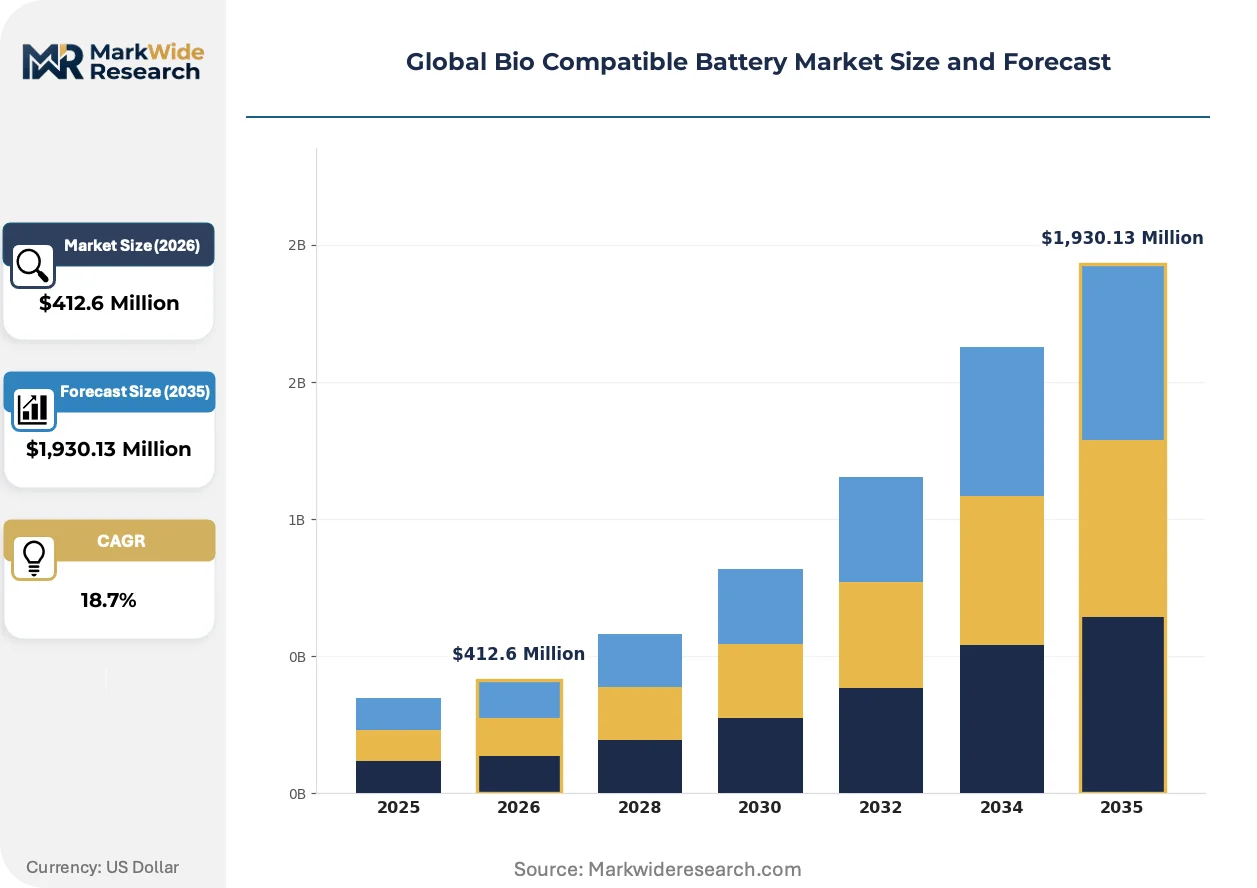
Market Dynamics
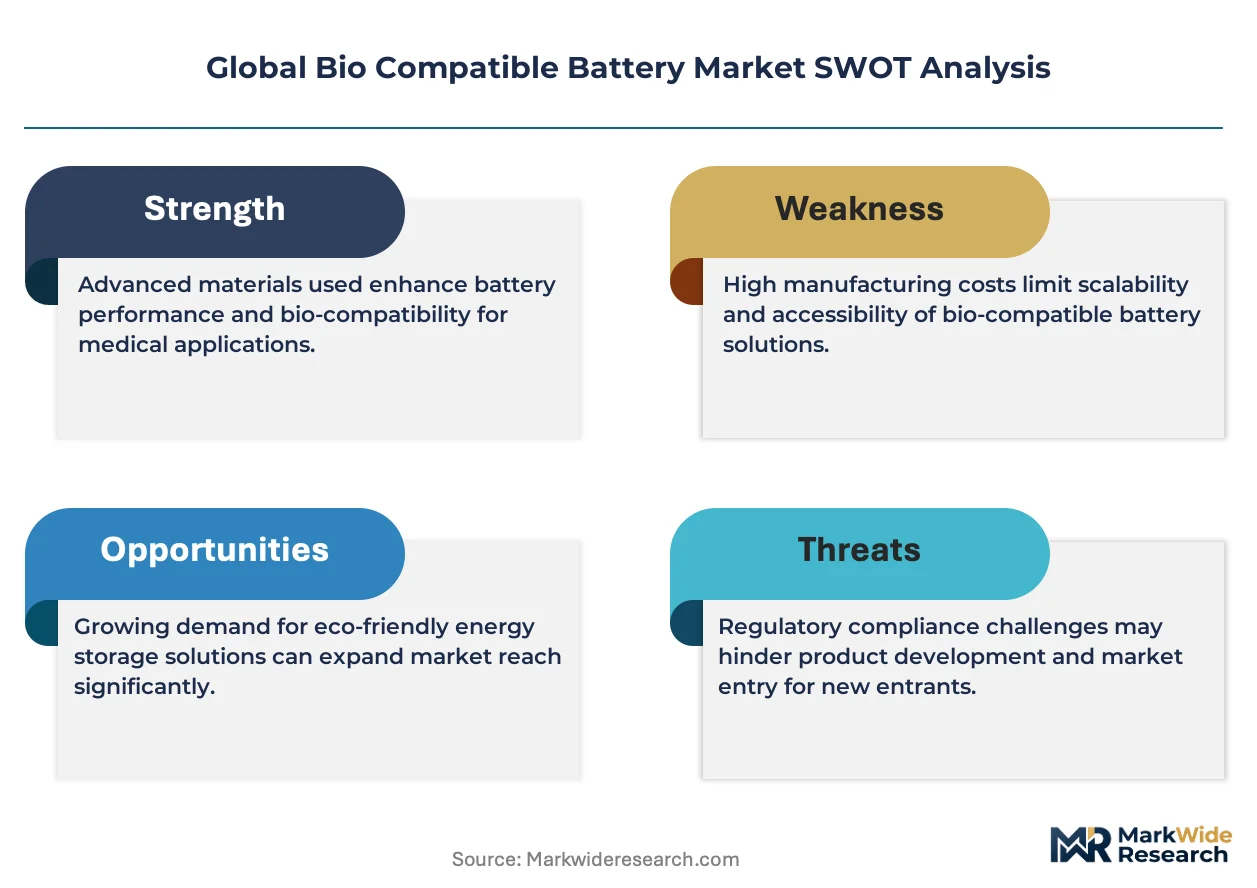
The central dynamic shaping the market is the tension between the escalating performance requirements for miniaturized medical electronics and the increasingly stringent safety and material mandates from regulators. This forces a direct trade-off between energy density and biocompatibility, defining the core engineering challenge.
Growth Catalysts
- Implantable Device Expansion:The proliferation of advanced implantable medical devices, including cardiac pacemakers, neurostimulators, and drug delivery pumps, creates a foundational demand for highly reliable, long-life biocompatible power sources.
- Wearable Technology Miniaturization:Advances in flexible electronics and miniaturization for wearable health monitors and smart textiles necessitate the development of conformable, skin-safe batteries that can be integrated seamlessly.
- Regulatory Frameworks:The enforcement of standards like ISO 10993 and the EU's Medical Device Regulation (MDR) compels manufacturers to use certified biocompatible materials, thereby expanding the market for compliant battery chemistries and encapsulation.
Market Restraints
- Material Cost Structure:The high cost of medical-grade raw materials, such as specialized polymers, non-toxic electrolytes, and inert metallic casings, makes biocompatible batteries significantly more expensive than their consumer-grade counterparts.
- Energy Density Limitations:A fundamental trade-off exists where materials selected for maximum biocompatibility and safety, like those in solid-state designs, often exhibit lower energy density than conventional lithium-ion chemistries.
- Supply Chain Concentration:The supply of ultra-pure materials required for biocompatible battery production is concentrated among a small number of specialized chemical and material suppliers, posing a risk of bottlenecks and price volatility.
Strategic Opportunities
- Biodegradable Power Sources:Research into transient electronics using biodegradable materials like silk, magnesium, and zinc opens opportunities for temporary medical implants and ingestible sensors that dissolve after use, eliminating removal surgeries.
- Smart Textiles Integration:The emerging field of e-textiles for continuous health monitoring presents a significant white-space opportunity for flexible, washable, and skin-friendly batteries designed for integration into clothing.
- Emerging Market Healthcare:Increasing healthcare investments in Southeast Asian and Latin American countries provide an opportunity to introduce advanced battery-powered medical devices to previously underpenetrated markets.
Industry Challenges
- Certification Timelines:Navigating the lengthy and costly validation and certification pathways, such as the premarket approval (PMA) process with the US FDA, can significantly delay the commercialization of new battery technologies. -
- System Integration Complexity:Ensuring reliable electrical and mechanical integration of flexible batteries with delicate wearable electronics and sensors without compromising performance or patient safety remains a key engineering hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Compatible Battery Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Solid State, Lithium Polymer Form Factor: Flexible, Rigid, Cylindrical, Planar End User: Medical Devices, Wearable Technology, Implants, Consumer Electronics Technology: Thin Film, Microbial Fuel Cells, Electrochemical Systems, Nanotechnology |
| Companies Covered | Murata Manufacturing Co. Ltd., Stora Enso Oyj, Jenax Inc., Medtronic plc, Integer Holdings Corporation, BeFC Bioenzymatic Fuel Cells, Ultralife Corporation, Boston Scientific Corporation, Ilika plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Compatible Battery Market Strategic Shifts & Innovations
The convergence of material science and micro-fabrication is defining the industry's innovation trajectory. This is driven by the dual, and often conflicting, demands of high-energy implantable devices and flexible, skin-contact wearables, pushing development toward novel chemistries and form factors.
Solid-state battery technology provides enhanced safety by eliminating flammable liquid electrolytes, a critical risk factor in medical applications. Medical device manufacturers, particularly for Class III implants, are actively evaluating these chemistries for next-generation designs. This solid-state architecture is absorbing the design constraints previously imposed by liquid electrolytes, enabling more compact and anatomically conformal device shapes.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance on component suppliers. This directly impacts battery makers, who must now provide extensive data on long-term material stability and leachability. Implantable device categories are most affected, forcing battery producers to invest in lifecycle testing protocols to ensure their products meet the new compliance thresholds.
Medical device OEMs are modifying their buying behavior, shifting from sourcing discrete batteries to procuring integrated power management subsystems. This disrupts the traditional component-supplier model, creating an advantage for vendors capable of co-designing the battery with its associated charging and safety circuits. This trend is most pronounced in the competitive remote patient monitoring and advanced diagnostics sectors in Germany and Japan.
Global Bio Compatible Battery Market Segmentation
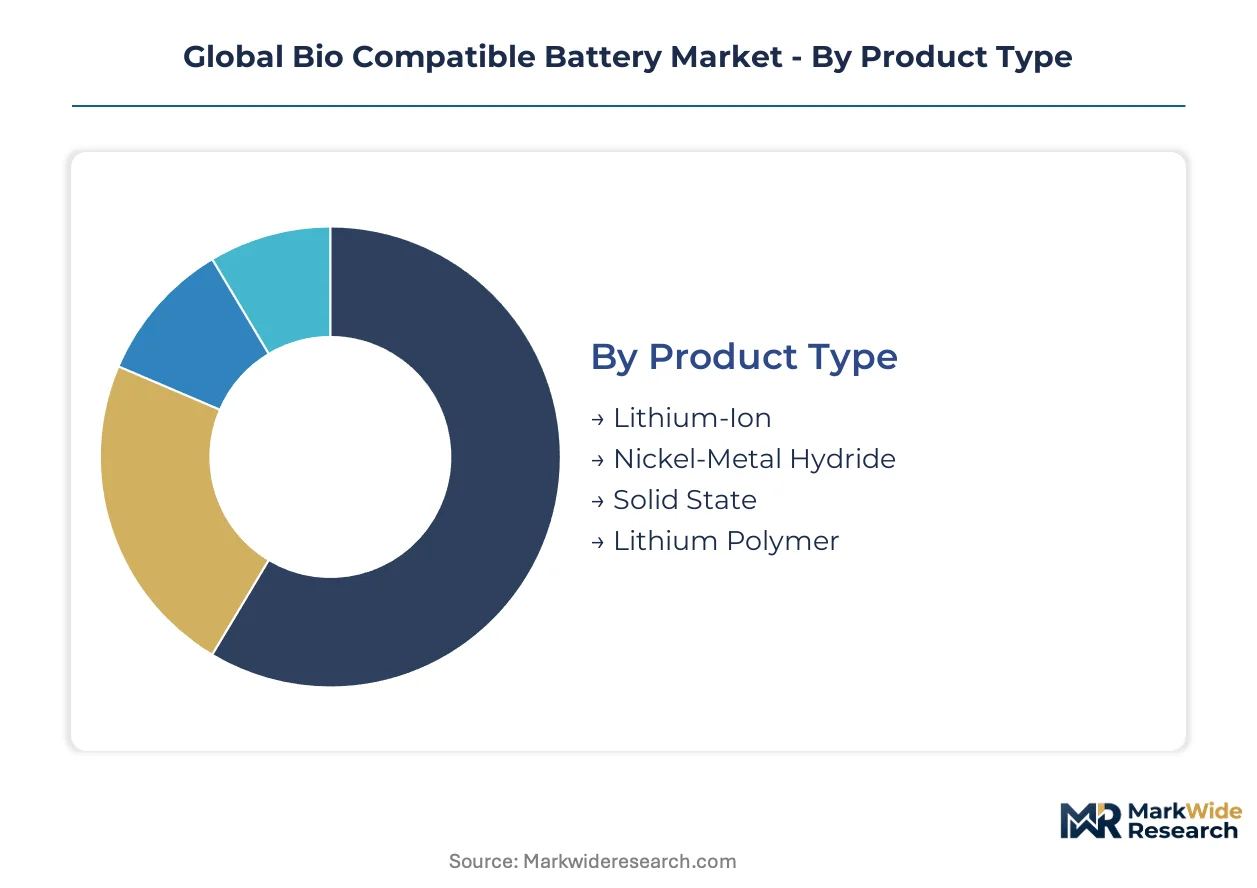
Understanding the distinct segments within the global biocompatible battery market provides clarity on where innovation and investment are most critical. These categorizations highlight the varied technical demands and regulatory pathways influencing product development and market penetration across diverse applications.
Product Type:
The market's product type segmentation reveals a clear distinction between established, high-volume chemistries and emerging, premium solutions. Each chemistry offers specific advantages for different medical applications.
- Lithium-Ion:These batteries utilize lithium compounds as their primary active materials, offering high energy density and a long cycle life. Demand concentrates in advanced implantable devices like pacemakers and defibrillators, where sustained power and reliability are paramount.
- Solid State:This technology employs solid electrodes and solid electrolytes, eliminating flammable liquid components for enhanced safety and stability. Medical device manufacturers, particularly for Class III implants, evaluate solid-state solutions for compact, anatomically conformal designs.
- Nickel-Metal Hydride:These rechargeable batteries offer a balance of energy density and safety, finding application in certain portable medical equipment.
- Lithium Polymer:Characterized by a polymer electrolyte, these batteries allow for flexible and thin form factors, suitable for some wearable health monitors.
Mature deployment sits with Lithium-Ion. Newer deployment is concentrated in Solid State, which represents the fastest-growing trajectory.
Form Factor:
The form factor segmentation highlights how physical design adapts to diverse integration requirements, from rigid implants to conformable wearables. Design flexibility directly influences patient comfort and device functionality.
- Flexible:These batteries are designed to bend and conform to irregular surfaces, often incorporating thin-film technologies. Wearable health monitors and smart textiles in Europe and Japan drive demand for these adaptable power sources.
- Rigid:Encapsulated in robust, often hermetically sealed casings, these batteries prioritize durability and protection for internal components. Implantable medical devices, such as neurostimulators, rely on rigid designs for long-term in-body operation.
- Cylindrical:This traditional form factor offers reliable performance and is used in a range of medical diagnostic tools.
- Planar:Flat and thin, planar batteries are integrated into compact devices where space is a significant constraint.
Established product integration often relies on Rigid form factors. Advancements in miniaturized electronics increasingly favor Flexible designs for next-generation products.
End User:
The end-user segmentation illustrates the diverse applications driving demand for biocompatible power solutions, each with unique performance and regulatory requirements. Material selection and design considerations vary significantly across these user groups.
- Medical Devices:This broad category includes a wide array of diagnostic, therapeutic, and monitoring equipment used in clinical settings and at home. Regulatory frameworks from the US FDA and Europe's EMA mandate rigorous testing for all components, including batteries, within these devices.
- Wearable Technology:Devices worn on the body for continuous health monitoring, fitness tracking, and other applications fall into this segment. Miniaturization and skin-safe materials are critical for battery integration into these consumer-facing health solutions.
- Implants:Devices surgically placed inside the human body for extended periods, such as cardiac pacemakers and cochlear implants, belong to this segment. Long-term biocompatibility, energy density, and reliability are paramount for these life-critical applications.
- Consumer Electronics:While a smaller portion of the biocompatible market, this segment includes devices where skin contact or proximity necessitates non-toxic components, even if not strictly medical.
High-reliability applications primarily target Medical Devices. Emerging health-focused innovations increasingly serve Wearable Technology.
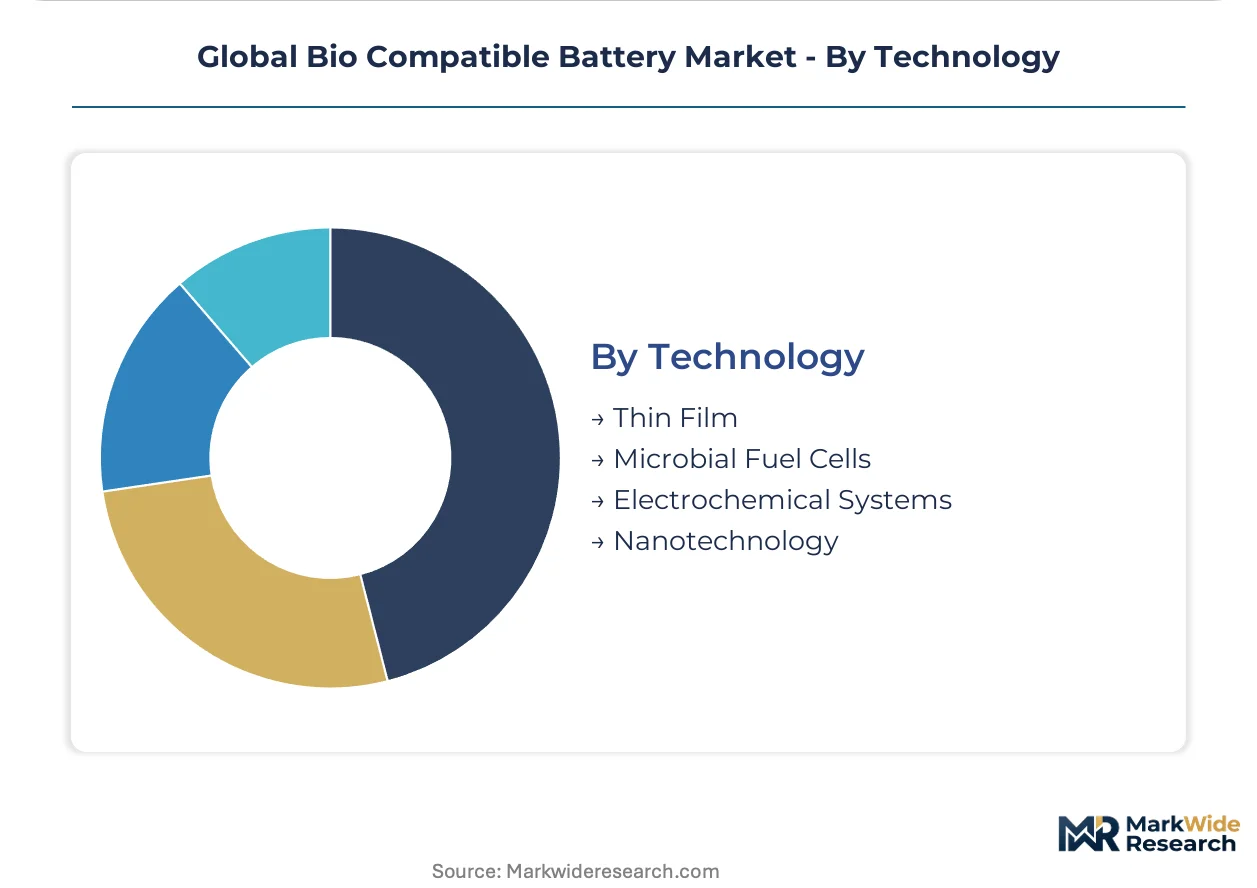
Technology:
The technology segmentation showcases the underlying scientific principles and engineering approaches employed in developing biocompatible power sources. Material science and micro-fabrication advancements are central to these innovations.
- Thin Film:This technology involves depositing very thin layers of active materials onto a substrate, enabling ultra-small and flexible battery designs. Miniaturization for smart textiles and ingestible sensors drives development in this area.
- Electrochemical Systems:These systems convert chemical energy into electrical energy through redox reactions, forming the fundamental basis for most battery chemistries. Research efforts focus on optimizing electrode materials and electrolytes for enhanced biocompatibility and energy density.
- Microbial Fuel Cells:These bio-electrochemical devices harness the metabolic activity of microorganisms to generate electricity, offering potential for self-powering biodegradable implants.
- Nanotechnology:The application of nanoscale materials and structures aims to improve battery performance, such as increasing surface area for better ion transport and reducing overall device size.
Established battery principles reside within Electrochemical Systems. Future advancements in transient electronics are increasingly exploring Microbial Fuel Cells.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical technology zones, like Germany's 'Medical Valley EMN' cluster, drive regional demand for biocompatible batteries. These concentrated innovation ecosystems foster collaboration between research institutions and manufacturers. Such zones accelerate advanced implantable and wearable device adoption.
Germany
Germany's robust medical device industry demands high-reliability biocompatible batteries for its sophisticated implants. The EU's Medical Device Regulation (MDR) influences material selection and certification for these components. The 'Medical Valley EMN' cluster, centered around Erlangen, fosters medical technology innovation.
Japan
Japan's focus on miniaturized medical electronics and an aging population fuels demand for compact, long-lasting power sources. The PMDA enforces strict safety and performance standards for all medical components. Advanced R&D in medical devices concentrates in the Kansai region, driving battery integration solutions.
United States
The United States represents a substantial market for implantable medical devices and rapidly adopting wearable health technologies. The US FDA's rigorous premarket approval (PMA) process ensures biocompatibility and long-term reliability for critical components. Major medical device clusters in Boston and Minneapolis lead next-generation power source development.
China
China's expanding domestic healthcare market and government initiatives to localize medical technology production increase demand for biocompatible batteries. The NMPA establishes safety and quality standards for medical device components. Key manufacturing zones in the Yangtze River Delta attract significant investment in advanced medical device production.
India
India's growing healthcare expenditure and emphasis on accessible medical devices generate demand for cost-effective biocompatible battery solutions. The CDSCO regulates the quality and safety of medical devices and their power sources. Bengaluru and Hyderabad are emerging as key innovation centers for medical technology development.
Global Bio Compatible Battery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the biocompatible battery market. This landscape remains fragmented, characterized by players with distinct expertise in materials, chemistry, or form factor. Key strategic archetypes include material science innovators, medical device integrators, and flexible power solution providers. Companies frequently pursue strategic partnerships for technology co-development and portfolio diversification into new form factors, aiming to capture emerging opportunities in wearables and advanced implants.
Among leading innovators, Medtronic plc represents a key player in high-reliability implantable device power solutions, leveraging its deep expertise. Murata Manufacturing Co. Ltd., a Japanese entity, anchors the market for miniaturized power sources across a broad range of electronic applications, including medical. Jenax Inc., a Korean firm, exemplifies specialization in flexible battery designs tailored for next-generation wearables. These companies collectively demonstrate the diverse approaches to developing and integrating biocompatible battery technologies, balancing energy density with stringent safety requirements for their respective market segments.
| Leading Market Players |
|---|
| Murata Manufacturing Co. Ltd. |
| Stora Enso Oyj |
| Jenax Inc. |
| Medtronic plc |
| Integer Holdings Corporation |
| BeFC Bioenzymatic Fuel Cells |
| Ultralife Corporation |
| Boston Scientific Corporation |
| Ilika plc |
| Others |
Cost & Logistics Intelligence
Medical device OEMs, especially those producing Class III implants, drive a contract-based pricing model for biocompatible batteries. This reflects the deep co-development and stringent regulatory requirements for these critical components.
Pricing Analysis
Premium pricing for biocompatible batteries is often commanded by suppliers offering rapid prototyping and certified components with short lead times. The dominant pricing model is value-based, reflecting the critical safety and performance requirements for medical applications. Price differentiation stems from the certification level, such as US FDA Class III approval, and the degree of customization for specific device integration. Pricing pressure intensifies for standard-grade components due to increased competition, while implantable device manufacturers are least price-sensitive.
Supply Chain Analysis
Specialized engineering talent availability in Germany and Japan significantly influences the supply chain for advanced biocompatible battery manufacturing. The supply of ultra-pure medical-grade raw materials, including specialized polymers and non-toxic electrolytes, concentrates in a few specialized chemical suppliers. This creates single-source vulnerability, a key supply chain risk. Distribution runs through direct sales channels to medical device OEMs and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biocompatible battery market is fundamentally a cost-of-compliance story, where stringent regulations like Europe's Medical Device Regulation (MDR) create a significant barrier-to-entry moat for compliant manufacturers. This regulatory environment ensures high safety standards but also demands substantial investment.
For Market Incumbents: Anchor existing market share by deepening co-development partnerships with leading medical device OEMs in high-value segments like Class III implants. Invest in advanced materials R&D, particularly for solid-state chemistries, to counter emerging flexible battery technologies. Certification investment for new chemistries under US FDA and EMA frameworks reinforces a strong competitive advantage against less established players. Diversify geographic manufacturing footprints to mitigate supply chain concentration risks.
For New Entrants and Emerging Players: Europe's Medical Device Regulation (MDR) in the EU opens a window for specialized new entrants focusing on compliant, innovative flexible battery designs. Target the rapidly expanding wearable technology segment in Japan and Germany, which demands miniaturized and conformable power sources. A go-to-market angle involves offering integrated power management subsystems, co-designed with smaller OEMs. Focus on biodegradable power sources for temporary medical implants, a significant white-space opportunity.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with deep pockets and a long-term vision for this critical medical component market. Long-term viability over the next decade is strong, driven by implantable device expansion and wearable health technology. Identify acquisition targets that possess unique intellectual property in solid-state or flexible battery chemistries. A key signal to watch is the successful commercialization of a new Class III implant powered by a novel biocompatible battery.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Materials R&D | Secures next-generation performance in energy density and biocompatibility for Medtronic plc. |
| Certification Pathway Investment | Ensures compliance with US FDA and EU MDR, protecting market access for Murata Manufacturing Co. Ltd. |
| Integrated Power Subsystem Development | Addresses OEM demand for co-designed charging and safety circuits, benefiting Jenax Inc. |
| Geographic Manufacturing Diversification | Mitigates supply chain risks from material concentration in specialized regions. |
| Biodegradable Battery Research | Positions for future transient medical implants, opening new application areas. |
Research Approach
Multi-period observation of medical device approvals and material science patents anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with biomedical engineers, regulatory affairs specialists, medical device procurement managers, and materials scientists. Secondary validation utilized US FDA filings, European Medicines Agency (EMA) submissions, and ISO 10993 standards documentation. This approach enabled comprehensive bottom-up and top-down triangulation.
An input-output matrix modeled market dynamics across the analysis window, integrating various segmentation dimensions. These included product type, form factor, end-user, technology, and regional regulatory compliance. Compound annual growth rates were derived by projecting demand drivers like implantable device expansion and wearable technology miniaturization. Key forecast inputs included medical device R&D spending and material cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and material availability. Geopolitical shifts impacting supply chains or unexpected breakthroughs in energy harvesting technologies warrant pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
VRLA Batteries Market
Batteries
Nickel Cadmium Battery Market
Batteries
South America Consumer Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Submarine Batteries Market
Batteries
Low Temperature Battery Market
Batteries
East Africa Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Tubular GEL Battery Market
Batteries
N-Type Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Breathing Battery Market
Batteries
Wide Temperature Battery Market
Batteries
Nanicl Battery Market
Batteries
Power Battery Cells Market
Batteries
Battery Cases Market