
 North America Next Generation Computing Market | 2026-2036
North America Next Generation Computing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Next Generation Computing Market Insights
The US National Quantum Initiative is recalibrating procurement priorities across federal agencies and defense contractors. Microsoft Corporation leverages its Azure Quantum platform to anchor hybrid cloud deployments for government workloads. NVIDIA Corporation dominates specialized silicon for AI training clusters, while IBM Corporation sustains leadership in superconducting quantum processor roadmaps.
Next generation computing encompasses architectures that transcend classical von Neumann limitations through quantum superposition, neuromorphic spike-based processing, or photonic information transfer, operating at cryogenic temperatures or leveraging memristive crossbar arrays to solve optimization and machine learning problems intractable to conventional systems. Cloud computing solutions currently capture the largest revenue share as enterprises prioritize operational flexibility over capital-intensive on-premises installations. Quantum computers represent the fastest-expanding product category, though neuromorphic chips are narrowing the gap in edge-AI inference applications where power constraints dominate design requirements.
The US Department of Energy and NIST enforce standards for quantum cryptography and post-quantum migration timelines, while Canada's NRC coordinates federal research funding with commercialization pathways. Mexico's telecommunications regulator shapes data residency requirements that influence cross-border cloud deployment architectures. Stakeholders must weigh sovereign compute strategies against interoperability standards as national security classifications fragment procurement criteria across the trilateral region.
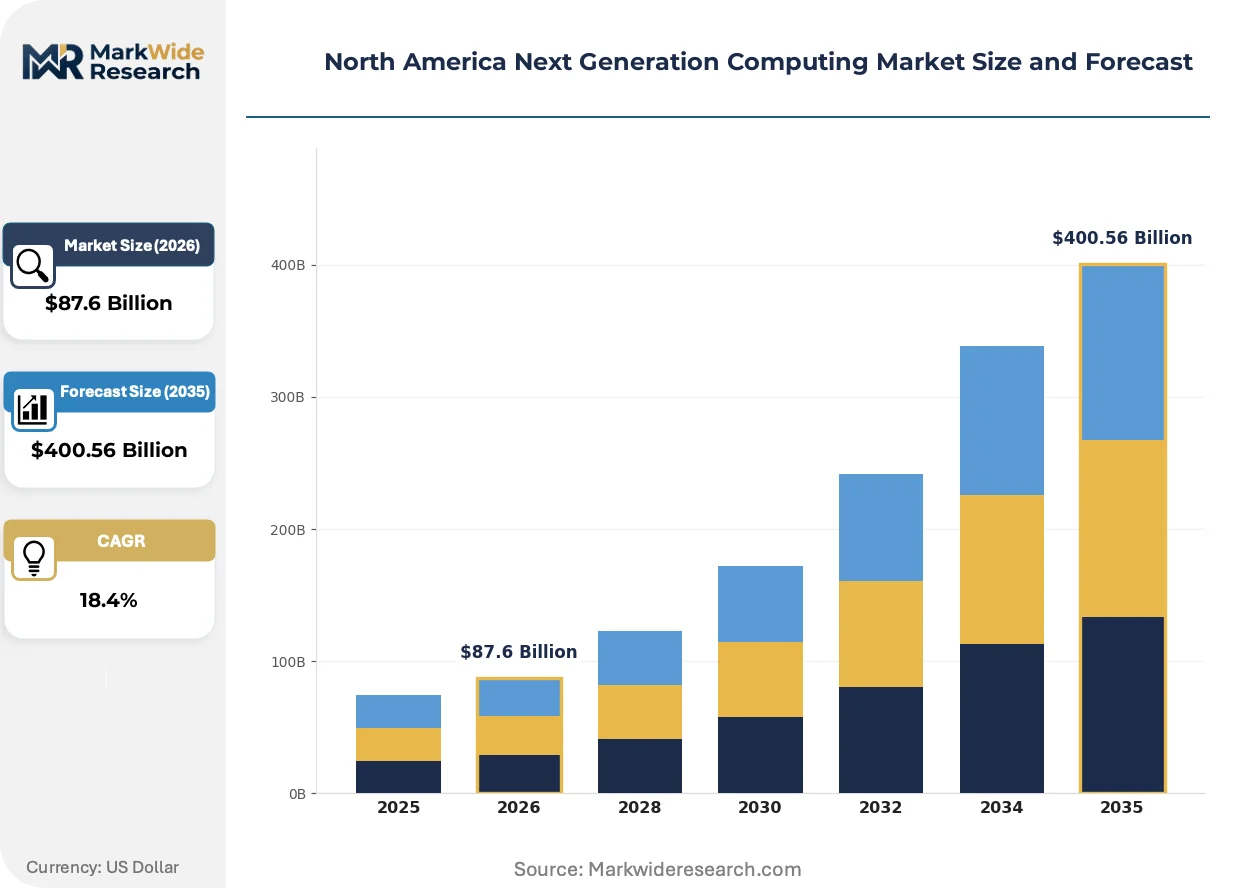
Market Dynamics
The US National Quantum Initiative Act is recalibrating federal procurement priorities, forcing defense contractors and national laboratories to accelerate post-quantum cryptography migration timelines while redirecting R&D budgets toward domestic quantum processor fabrication.
Growth Catalysts
- Cryogenic control electronics:Advances in dilution refrigerator interfacing are reducing qubit error rates. National Institute of Standards and Technology certification protocols are validating commercial quantum systems for federal workloads.
- Financial services optimization:Derivatives pricing and portfolio risk simulation now deploy hybrid quantum-classical algorithms. Major banks are establishing dedicated quantum research divisions in New York and Toronto.
- Neuromorphic edge deployment:Spike-based neural networks are displacing GPU inference in power-constrained environments. Autonomous vehicle perception stacks in Michigan and California are piloting Intel and IBM neuromorphic silicon.
Market Restraints
- Helium-3 supply concentration:Cryogenic cooling systems depend on isotope supplies concentrated in Russia and Qatar. Geopolitical friction is extending procurement lead times for dilution refrigerator manufacturers.
- Superconducting qubit coherence limits:Current transmon architectures face fundamental decoherence barriers below 100 microseconds. Error correction overhead demands physical-to-logical qubit ratios exceeding 1,000:1.
- Export control fragmentation:US Bureau of Industry and Security quantum computing controls diverge from Canadian and Mexican regulatory frameworks. Cross-border cloud access to quantum hardware requires jurisdiction-specific compliance architectures.
Strategic Opportunities
- Mexico data residency arbitrage:Federal Telecommunications Institute requirements are incentivizing quantum-safe cloud infrastructure deployment in Querétaro and Guadalajara. Nearshoring enterprises seek low-latency access to US quantum networks.
- Photonic quantum interconnects:Silicon photonics is converging with trapped-ion architectures to enable modular quantum processors. Canadian research institutes in Waterloo and Vancouver are commercializing chip-to-chip optical linking.
- Post-quantum cryptography mandates:NIST standardization of lattice-based algorithms is creating replacement demand across federal, financial, and healthcare sectors. Migration services represent a discrete revenue vertical.
Industry Challenges
- Cryogenic engineering talent scarcity:The specialized skill set spanning quantum mechanics, microwave engineering, and dilution refrigerator operation is concentrated at fewer than twelve North American academic programs. Workforce pipeline constraints are delaying system deployment timelines.
- Legacy cryptographic infrastructure:Financial services and healthcare providers maintain decades-old public-key infrastructure that cannot migrate instantaneously. Hybrid transition architectures introduce operational complexity and temporary vulnerability windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Next Generation Computing Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quantum Computers, Neuromorphic Chips, Optical Processors, Cloud Computing Solutions Technology: Artificial Intelligence, Machine Learning, Blockchain, Augmented Reality End User: Enterprises, Educational Institutions, Research Organizations, Government Agencies Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google, IBM Corporation, NVIDIA Corporation, Intel Corporation, Hewlett Packard Enterprise, Oracle Corporation, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Next Generation Computing Market Trends and Innovations
Quantum error correction hardware is advancing from theoretical constructs to engineered subsystems, while neuromorphic architectures are escaping research laboratories into production edge environments. These shifts are compressing development cycles and fragmenting supplier hierarchies.
Superconducting quantum processors are integrating cryogenic CMOS control electronics directly on the qubit chip. IBM and Rigetti are shipping systems with on-chip multiplexing that reduces room-temperature wiring density. This integration is collapsing the traditional separation between quantum and classical control domains, forcing subsystem suppliers to consolidate or specialize.
The US Department of Energy is enforcing quantum cryptography procurement standards across national laboratories and their contractor networks. NIST post-quantum algorithm finalization is triggering mandatory inventory and replacement schedules for existing public-key infrastructure. Defense contractors in Maryland and California are restructuring supply chains to source quantum-resistant components exclusively from domestic or allied fabrication facilities.
Enterprise buyers are unbundling quantum computing access from cloud platform subscriptions. Financial services firms in Manhattan and Chicago are negotiating direct quantum hardware time-sharing agreements with specialized providers, bypassing general-purpose cloud intermediaries. This disintermediation is most pronounced among quantitative hedge funds and derivatives clearing operations with sufficient internal quantum software expertise.
North America Next Generation Computing Market Segmentation
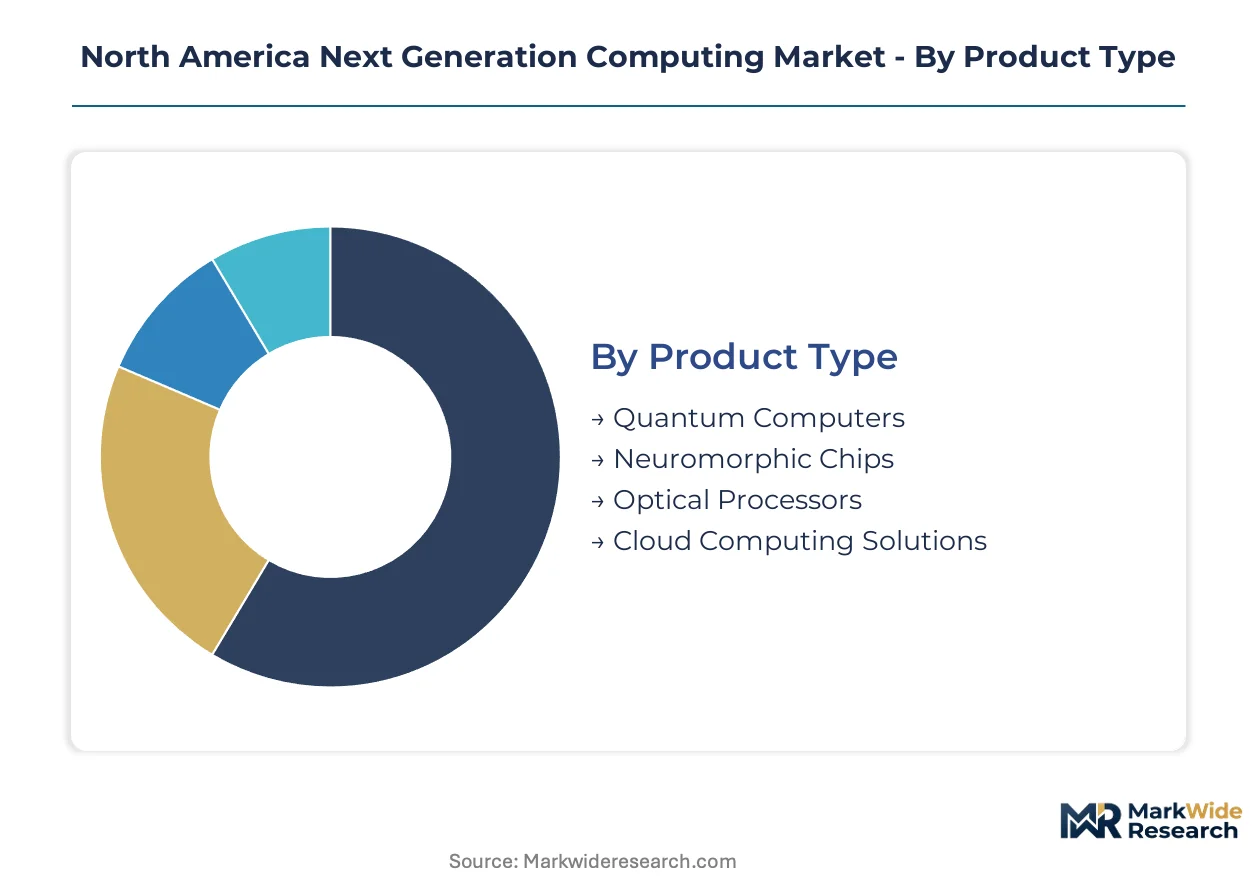
Next generation computing architectures demand granular segmentation to capture divergent commercialization timelines across quantum, neuromorphic, and photonic platforms. Procurement patterns vary sharply between capital-intensive on-premises installations and flexible cloud consumption models.
Product Type:
Standalone quantum systems require cryogenic infrastructure and specialized facilities, while neuromorphic and optical processors embed more readily into existing server architectures.
- Quantum Computers:Superconducting and trapped-ion architectures operate at millikelvin temperatures, demanding dedicated facilities. Federal agencies and national laboratories in the United States anchor procurement volumes through the National Quantum Initiative. Error correction overhead and coherence limitations constrain commercial deployment beyond specialized optimization workloads.
- Cloud Computing Solutions:Hybrid quantum-classical orchestration platforms abstract hardware complexity for enterprise developers. Financial services firms in Manhattan and Toronto prioritize operational flexibility over capital-intensive ownership, driving subscription revenue concentration.
- Neuromorphic Chips:Spike-based analog processors embed into edge-AI inference pipelines where power constraints dominate. Intel and IBM silicon pilots in Michigan autonomous vehicle stacks demonstrate production readiness.
- Optical Processors:Silicon photonic interconnects enable modular quantum processor scaling. Canadian research institutes in Waterloo commercialize chip-to-chip optical linking for trapped-ion systems.
Cloud computing solutions lead volumes today; quantum computers are gaining share fastest.
Technology:
Cost tiers separate foundational infrastructure investments from application-layer software deployments.
- Artificial Intelligence:Training clusters consume specialized AI accelerators from NVIDIA and cloud GPU instances. Enterprise demand concentrates in financial services risk modeling and pharmaceutical molecular simulation.
- Machine Learning:Classical ML pipelines integrate with quantum kernels for hybrid optimization. Quantitative hedge funds in Chicago deploy variational algorithms for portfolio construction.
- Blockchain:Post-quantum cryptographic signatures protect distributed ledger integrity. NIST lattice-based standards drive replacement demand across federal and financial infrastructure.
- Augmented Reality:Neuromorphic edge processors enable low-latency spatial computing. Power-constrained AR headsets in California pilot spike-based neural networks for real-time scene understanding.
Artificial Intelligence leads volumes today; blockchain is climbing the fastest as post-quantum migration mandates accelerate.
End User:
Customer type determines procurement sophistication, from standardized cloud subscriptions to custom quantum hardware development agreements.
- Government Agencies:The US Department of Energy and NIST enforce quantum cryptography procurement standards across national laboratories and defense contractors. Sovereign compute requirements prioritize domestic fabrication and allied supply chains.
- Enterprises:Financial services firms unbundle quantum access from general cloud platforms, negotiating direct hardware time-sharing. Derivatives clearing operations in Manhattan bypass intermediaries for lower-latency queue priority.
- Research Organizations:Academic consortia access quantum systems through NSF and DOE facility allocations. Canada's NRC coordinates federal funding with commercialization pathways for Waterloo and Vancouver institutes.
- Educational Institutions:University quantum curricula expand through IBM Quantum Network and AWS Braket educational credits. Workforce pipeline development addresses cryogenic engineering talent scarcity.
Government agencies lead volumes today; enterprises are expanding most quickly as financial services optimization matures.
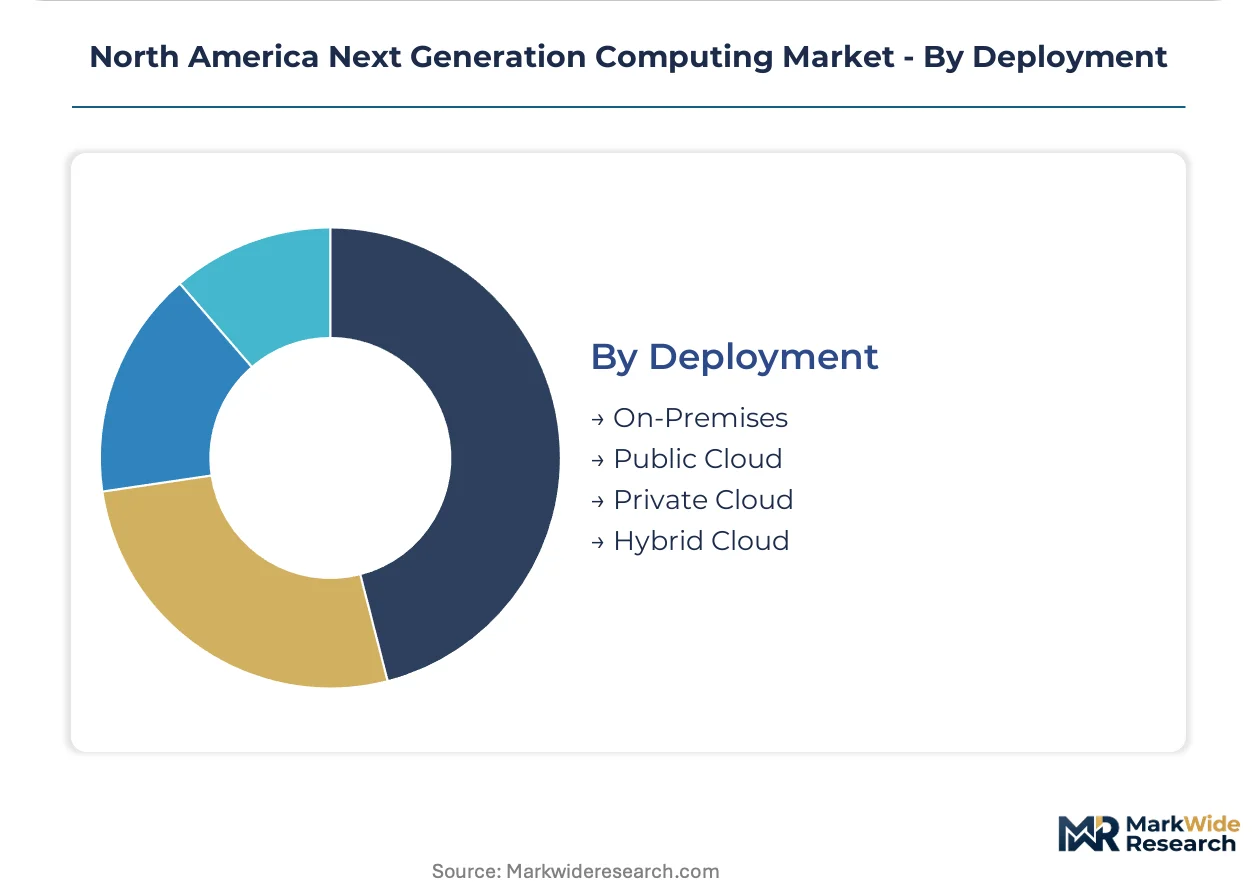
Deployment:
Volume concentration favors public cloud for experimental workloads, while production systems migrate toward hybrid architectures.
- Public Cloud:Azure Quantum and AWS Braket democratize access to diverse quantum hardware backends. Mexico's Federal Telecommunications Institute data residency requirements are incentivizing quantum-safe infrastructure deployment in Querétaro.
- Hybrid Cloud:Orchestration layers route classical preprocessing to on-premises infrastructure while delegating quantum kernels to cloud hardware. Financial services firms maintain sensitive data locally while accessing remote qubit resources.
- Private Cloud:Dedicated quantum hardware installations serve classified federal workloads. Defense contractors in Maryland source exclusively from domestic or allied fabrication facilities.
- On-Premises:Capital-intensive dilution refrigerator systems anchor national laboratory facilities. Helium-3 supply concentration from Russia and Qatar extends procurement lead times for cryogenic infrastructure.
Public cloud leads volumes today; hybrid cloud shows the steepest expansion trajectory as enterprises balance flexibility with data sovereignty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American next generation computing industry traces its commercial origins to federally funded research at Bell Labs and MIT Lincoln Laboratory during the 1960s, with subsequent scaling through DARPA programs and the emergence of Silicon Valley semiconductor fabrication clusters.
United States
Federal quantum computing procurement through the Department of Energy and NIST anchors domestic demand for superconducting systems. The National Quantum Initiative Act mandates post-quantum cryptography migration across defense contractor networks. Maryland and California host concentrated defense-industrial clusters where contractors restructure supply chains toward allied-sourced quantum-resistant components.
Canada
Neuromorphic chip research commercialization drives specialized demand, with the National Research Council coordinating federal funding pathways. Health Canada and PMRA influence technology transfer protocols for cryogenic medical applications. Waterloo and Vancouver institutes concentrate photonic quantum interconnect development, commercializing chip-to-chip optical linking for trapped-ion architectures.
Mexico
Cloud infrastructure deployment accelerates as nearshoring enterprises seek low-latency quantum network access. The Federal Telecommunications Institute enforces data residency requirements shaping cross-border deployment architectures. Querétaro and Guadalajara emerge as quantum-safe infrastructure hubs, incentivized by federal telecommunications regulation and proximity to US fiber networks.
Texas
Energy sector optimization workloads attract quantum computing pilot programs for grid simulation and reservoir modeling. State-level research partnerships with federal laboratories accelerate cryogenic engineering workforce development. Austin and Houston metropolitan clusters concentrate hybrid cloud orchestration development for oil and gas supercomputing applications.
New York Metro
Financial services quantum adoption concentrates in Manhattan derivatives clearing operations and quantitative hedge funds. State banking regulators coordinate with federal agencies on post-quantum cryptography compliance timelines. The metropolitan cluster hosts dedicated quantum research divisions at major banks, bypassing general-purpose cloud intermediaries for direct hardware access.
North America Next Generation Computing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the cryogenic systems and specialized silicon layers, while cloud orchestration platforms compete on developer ecosystem breadth. The vendor base separates into three strategic archetypes: hyperscale cloud operators with quantum service layers, specialized quantum hardware fabricators, and neuromorphic silicon designers. Dominant competitive moves include direct hardware time-sharing agreements that disintermediate general-purpose cloud platforms, and vertical consolidation of cryogenic control electronics onto qubit chips.
Within the hyperscale cloud operator tier, Amazon Web Services and Microsoft Corporation exemplify platform-centric positioning, anchoring hybrid quantum-classical orchestration services. IBM Corporation occupies a distinctive archetype spanning both cloud access and proprietary superconducting hardware roadmaps. NVIDIA Corporation represents the specialized silicon vector, with its dominance in AI training accelerators extending into neuromorphic and photonic co-processor development.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| IBM Corporation |
| NVIDIA Corporation |
| Intel Corporation |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
On-chip cryogenic CMOS integration is collapsing the traditional separation between quantum and classical control domains, simultaneously compressing subsystem supplier margins and concentrating procurement power among vertically integrated hardware fabricators. This technological transition forces specialized component vendors to absorb cost compression while federal domestic-content mandates reshape sourcing economics across the trilateral region.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the North American next generation computing landscape. Premium tiers command substantial markups for NIST-certified quantum systems with validated post-quantum cryptography compliance, while standard cloud subscription tiers compete on developer ecosystem breadth. Price differentiation hinges on certification grade and volume scale, with financial services clearing operations showing lowest price sensitivity due to latency-critical workloads. Cost compression in neuromorphic edge processors is intensifying because Intel and IBM are driving production-scale silicon economics.
Supply Chain Analysis
US National Quantum Initiative domestic-content requirements are redirecting procurement toward allied-sourced quantum-resistant components and domestic superconducting fabrication facilities. Supply concentration centers on the United States for superconducting qubit systems, Canada for photonic interconnect development, and Taiwan for advanced CMOS control electronics. Raw material dependencies draw from Russia and Qatar for helium-3 isotope supplies, South Korea for specialized semiconductor substrates, and Japan for cryogenic microwave components. Single-source vulnerability in helium-3 procurement extends lead times for dilution refrigerator manufacturers. Distribution runs through direct hardware time-sharing agreements that disintermediate general-purpose cloud platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America next generation computing market represents a late-cycle quality story as federal procurement prioritizes NIST-certified systems with domestic fabrication provenance over commodity cloud access. Enterprise demand is shifting toward premium specifications that bundle quantum-safe cryptography validation with sovereign compute guarantees.
For Market Incumbents: Deploy cryogenic control electronics integration as the primary defensive lever. IBM and Rigetti are already shipping systems with on-chip multiplexing that reduces room-temperature wiring density, forcing subsystem suppliers to consolidate or exit. Incumbents must secure domestic fabrication partnerships to satisfy Department of Energy procurement standards while accelerating post-quantum cryptography certification timelines to maintain federal wallet share against emerging trapped-ion competitors.
For New Entrants and Emerging Players: Mid-tier financial services firms with sufficient internal quantum software expertise but insufficient capital for direct hardware ownership represent the most penetrable buyer archetype. These quantitative hedge funds and regional derivatives operations seek lower-latency queue priority without general-purpose cloud intermediation. Neuromorphic edge-AI inference for autonomous vehicle perception stacks in Michigan and California offers a second white-space target where power constraints dominate design requirements.
For Investors and Strategic Acquirers: Roll-up economics work for cryogenic engineering talent aggregators because workforce pipeline constraints are delaying system deployment timelines across fewer than twelve North American academic programs. Platform consolidation around specialized quantum hardware fabricators with trapped-ion or photonic roadmaps offers superior long-term viability compared to pure-play cloud orchestration layers. Watch for NIST post-quantum algorithm standardization completion as the signal indicating replacement demand acceleration across federal, financial, and healthcare infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic CMOS Integration | IBM and Rigetti systems with on-chip multiplexing collapse classical-quantum control separation, forcing supplier consolidation. |
| Post-Quantum Cryptography Certification | NIST lattice-based standards trigger mandatory inventory replacement schedules across defense contractor networks. |
| Direct Hardware Time-Sharing Agreements | Manhattan derivatives clearing operations bypass Azure Quantum intermediaries for lower-latency queue priority. |
| Domestic Fabrication Partnerships | Department of Energy procurement standards require allied-sourced quantum-resistant components exclusively. |
| Neuromorphic Edge Production Scaling | Intel and IBM silicon pilots in Michigan autonomous vehicle stacks demonstrate power-constrained inference readiness. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down federal funding and cloud capex tracking forms the analytical core of this study. Primary interviews with quantum hardware engineering leads, federal procurement officers at the Department of Energy, financial services risk technology executives, cryogenic systems plant managers, and academic research consortium directors combined with secondary validation from SEC hyperscaler filings, NIST standardization documentation, NSF facility allocation records, and Canadian NRC funding disclosure databases. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Input-output matrices map quantum processor shipments, cloud subscription volumes, and neuromorphic silicon wafer starts against end-use consumption patterns across the projection horizon. Segmentation dimensions modeled include product architecture, deployment model, end-user sophistication tier, and regional regulatory framework. CAGRs derive from slope analysis of technology adoption curves calibrated against federal procurement acceleration timelines and helium-3 supply constraint scenarios. Cryogenic engineering talent pipeline data and post-quantum cryptography migration schedules provide industry-specific forecast anchors.
Underlying measurement precision varies by segment; quantum computer shipments carry tighter precision than neuromorphic edge deployment estimates due to concentrated federal procurement visibility. Forecasts reflect documented assumptions regarding National Quantum Initiative funding continuity, NIST standardization adherence timelines, and helium-3 supply geopolitics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Next Generation Processors Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
Global Hybrid Intelligence Market
Emerging and Next Generation Technologies
Asia-Pacific MPU Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Transparent Electronics Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
In-Mold Electronics (IME) Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market