
 Global Travel Vaccines Market | 2026-2036
Global Travel Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Travel Vaccines Market Foresight
WHO prequalification is collapsing the supplier base for yellow fever and Japanese encephalitis vaccines, forcing smaller manufacturers to exit or partner. GlaxoSmithKline plc leverages its established cold-chain infrastructure to dominate tropical disease portfolios across Sub-Saharan Africa and Latin America. Sanofi SA anchors its position through integrated R&D and manufacturing for rabies and typhoid combinations. Pfizer Inc. competes by extending its mRNA platform into travel-relevant indications beyond COVID-19.
Travel vaccines are biologic preparations containing attenuated pathogens, purified subunits, or synthetic antigens formulated to induce active immunity against region-specific infectious diseases prior to departure; stability requirements typically mandate 2-8°C storage with validated cold-chain logistics from manufacture to point of administration. Their primary purpose is preventing morbidity in temporary visitors to endemic zones while reducing importation risk into non-endemic home countries. Inactivated vaccines occupy the largest revenue pool due to established safety profiles and broad prescriber familiarity, while mRNA formats represent the fastest-expanding segment as platform adaptability shortens development timelines for emerging threats. Distribution through specialized travel clinics captures premium pricing and patient compliance advantages over retail pharmacy channels.
FDA batch release testing, EMA GMP inspections, and WHO prequalification standards collectively determine which manufacturers can supply government procurement programs and international health certificates. These frameworks shape demand by restricting valid vaccine sources to certified producers while mandating specific potency thresholds and documentation for border entry requirements. Stakeholders must monitor regulatory divergence between FDA and EMA approaches to accelerated approval pathways for platform-based travel vaccines.
Market Dynamics
WHO prequalification standards are compressing the supplier base for tropical disease vaccines, forcing consolidation among manufacturers while simultaneously tightening potency thresholds that determine which products qualify for government procurement and international health certificates.
Growth Catalysts
- Corporate Travel Health Mandates:Multinational firms in mining, oil and gas, and consulting sectors are expanding pre-departure immunization requirements for expatriate assignments, creating institutional demand pools independent of leisure travel cycles.
- EMA Accelerated Assessment Pathways:The European Medicines Agency's adaptive licensing frameworks for platform-based vaccines are shortening development timelines for emerging travel-relevant indications.
- Southeast Asia Outbound Surge:Accelerating tourism departures from Vietnam, Thailand, and Indonesia are concentrating demand for Japanese encephalitis and typhoid immunizations in regional travel clinic networks.
Market Restraints
- Cold-Chain Infrastructure Deficits:Last-mile refrigeration gaps in Sub-Saharan Africa and rural Latin America limit distribution reach for thermolabile mRNA formulations, constraining addressable market expansion.
- Serum Institute Concentration:Heavy reliance on Indian bulk antigen suppliers creates single-source vulnerability for yellow fever and rabies vaccines, amplifying supply disruption risk during export restriction episodes.
- FDA Lot Release Bottlenecks:Extended batch testing timelines for imported travel vaccines create inventory gaps at US travel clinics during peak seasonality windows.
Strategic Opportunities
- Philippines Travel Clinic Expansion:Underpenetrated archipelago geography with 7,000+ islands presents whitespace for point-of-care immunization hubs serving outbound healthcare workers and seafarer populations.
- Heat-Stable Formulation Development:Lyophilization and novel excipient technologies enabling ambient-temperature distribution would unlock last-mile access in tropical climates without reliable refrigeration.
- Digital Health Certificate Integration:WHO Digital Documentation of COVID-19 Certificates framework extension to yellow fever and other travel vaccines creates interoperability standards for border automation.
Industry Challenges
- Stability Testing Expertise Scarcity:Qualified personnel for accelerated and real-time stability studies per ICH Q1A guidelines are concentrated at established manufacturers, constraining new entrant scale-up.
- Multivalent Formulation Complexity:Combining antigens for typhoid, hepatitis A, and polio without interference effects requires sophisticated adjuvant engineering that extends development timelines.
- Legacy Cold-Chain Asset Stranding:Existing 2-8°C infrastructure investments face obsolescence risk if heat-stable platforms achieve regulatory acceptance, complicating capital deployment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Travel Vaccines Market |
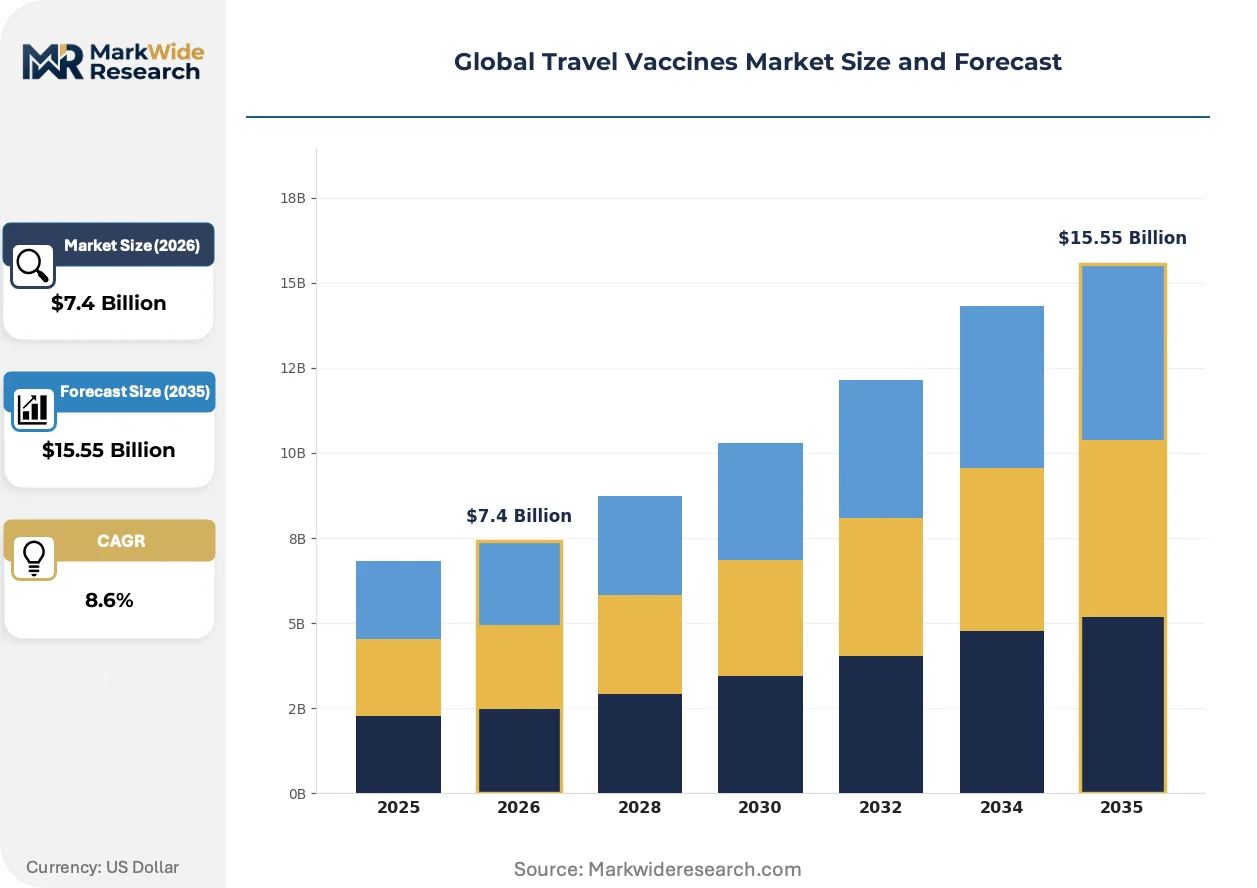
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Conjugate, Toxoid, mRNA Traveler Profile: Leisure Tourists, Business Travelers, Adventure Seekers, Expatriates, Students, Diplomats Disease Targeted: Hepatitis A, Typhoid, Yellow Fever, Rabies, Japanese Encephalitis, Meningococcal Disease Distribution Channel: Healthcare Clinics, Travel Clinics, Pharmacies, Online Pharmacies, Occupational Health Centers, Vaccination Camps |
| Companies Covered | Abbott Laboratories, Merck & Co. Inc., GlaxoSmithKline plc, CSL Ltd, Valneva SE, Pfizer Inc., AstraZeneca plc, Bavarian Nordic AS, Sanofi SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Travel Vaccines Market Shifts & Advancements
Platform adaptability is compressing development cycles for emerging pathogens while regulatory convergence around digital documentation is reshaping distribution and verification workflows across international travel corridors.
Microneedle array patches for intradermal delivery are miniaturizing administration infrastructure, eliminating sharps waste and refrigeration requirements at point-of-use. Travel clinics in Australia and Singapore are piloting self-administered booster applications, reducing nurse time per patient. This format is miniaturizing the physical footprint required for immunization services, enabling deployment in airport kiosks and hotel concierge stations.
The FDA's Project NextGen initiative for pandemic preparedness is creating regulatory infrastructure adaptable to travel-relevant RNA viruses. Manufacturing quality agreements and inspection harmonization protocols are reducing redundant facility audits for multi-jurisdictional suppliers. Tropical disease vaccine developers with US commercial ambitions are prioritizing FDA master file submissions ahead of WHO prequalification to secure premium pricing in North American travel health networks.
Employer-funded travel health programs are displacing out-of-pocket clinic visits as the dominant payment mechanism for business travel immunizations. Third-party administrators are consolidating procurement for multinational accounts, compressing price negotiation cycles and favoring suppliers with multi-product portfolios. This concentration is most visible in German and Swiss corporate travel programs, where integrated occupational health providers bundle pre-departure medical services under single contracts.
Global Travel Vaccines Market Segmentation
Segmentation in travel vaccines reveals how formulation technology, traveler risk profiles, and distribution infrastructure allocate margin pools across distinct commercial battlegrounds. Manufacturers must align R&D investment with the intersection of disease geography and channel economics to capture sustainable returns.
Vaccine Type:
Margin concentration tracks stability requirements and manufacturing complexity, with thermolabile formats commanding premium pricing where cold-chain infrastructure justifies the cost.
- Inactivated:Heat-killed whole pathogens or split virion preparations deliver established safety profiles that dominate prescriber preference in corporate health programs. Demand concentrates in German and Swiss occupational health networks where liability sensitivity favors decades of clinical precedent over novel platforms.
- mRNA:Synthetic nucleic acid sequences encoding pathogen antigens enable rapid reformulation for emerging threats, though 2-8°C storage requirements restrict deployment to urban travel clinic corridors with validated refrigeration. Southeast Asian outbound hubs in Bangkok and Singapore are rotating up the share rankings as platform adaptability shortens response timelines for variant emergence.
- Live Attenuated:Weakened pathogen strains induce robust cellular immunity with single-dose convenience for yellow fever and oral typhoid administration.
- Subunit:Purified protein or polysaccharide components reduce reactogenicity while maintaining immunogenicity for hepatitis B and Japanese encephalitis indications.
- Conjugate:Polysaccharide-protein linkages enhance T-cell dependent responses in pediatric and immunocompromised traveler populations.
- Toxoid:Formalin-inactivated exotoxins provide durable protection against diphtheria and tetanus as routine boosters for extended expatriate assignments.
Inactivated formats hold installed capacity across legacy manufacturing networks. mRNA is climbing the fastest as regulatory pathways mature for tropical disease applications.
Traveler Profile:
Volume distribution diverges sharply between price-insensitive institutional procurement and discretionary leisure spending sensitive to economic cycles.
- Business Travelers:Employer-funded immunization programs bundle pre-departure medical services under single contracts with occupational health providers, creating predictable demand independent of tourism seasonality. German and Swiss corporate travel programs concentrate procurement through third-party administrators, compressing price negotiation cycles and favoring suppliers with multi-product portfolios.
- Expatriates:Extended overseas assignments require comprehensive multi-disease protocols including rabies pre-exposure and Japanese encephalitis series, generating higher per-capita revenue than single-dose tourist vaccinations. Mining and oil sector deployments in Sub-Saharan Africa and rural Latin America drive institutional demand for heat-stable formulations where last-mile refrigeration remains unreliable.
- Leisure Tourists:Self-pay clinic visits for destination-specific requirements concentrate in pre-departure windows tied to booking patterns.
- Adventure Seekers:Remote itinerary risk profiles elevate demand for rabies and meningococcal coverage beyond standard tourist protocols.
- Students:University-mandated meningococcal and hepatitis A series create seasonal demand spikes aligned with academic calendars.
- Diplomats:Government procurement programs prioritize WHO-prequalified sources for official travel immunization documentation.
Business traveler contracts anchor volume commitments through multi-year corporate agreements. Expatriate programming is gaining share fastest as multinational firms expand duty-of-care obligations.
Disease Targeted:
Regulatory certification requirements and endemic geography determine which indications support premium pricing versus commodity competition.
- Yellow Fever:WHO International Health Regulations mandate valid vaccination certificates for entry into endemic zones, creating non-discretionary demand with document verification infrastructure at border control points. Brazilian and Nigerian national control programs concentrate procurement through prequalified manufacturer lists, restricting supplier access.
- Japanese Encephalitis:Rural agricultural exposure risk in Southeast Asian rice-growing regions drives demand from long-stay travelers and expatriates, with inactivated Vero cell-derived formulations displacing live attenuated alternatives in safety-sensitive markets. Vietnam and Thailand outbound acceleration is rotating up regional clinic network investment.
- Hepatitis A:Food and waterborne transmission risk sustures steady demand across all traveler categories with established combination packaging.
- Typhoid:Oral live attenuated and injectable polysaccharide formats compete on convenience versus durability of protection.
- Rabies:Pre-exposure prophylaxis for veterinary and wildlife workers commands premium pricing in occupational health channels.
- Meningococcal Disease:Hajj pilgrimage requirements and university matriculation mandates create concentrated seasonal demand.
Yellow fever certification infrastructure locks in incumbent suppliers. Japanese encephalitis is expanding most quickly as regional tourism corridors mature.
Distribution Channel:
Channel selection determines reimbursement mechanics, patient compliance capture, and the physical footprint required for service delivery.
- Travel Clinics:Specialized pre-departure consultation bundles immunization with destination risk assessment and prophylactic medication dispensing, commanding 40-60% price premiums over retail pharmacy alternatives. Australian and Singapore pilot programs for microneedle self-administration are reducing nurse time requirements and enabling airport kiosk deployment.
- Occupational Health Centers:Integrated corporate contracts consolidate procurement for multinational accounts with standardized protocols across global office networks. German and Swiss integrated providers bundle pre-departure services under single contracts, displacing fragmented clinic visits.
- Healthcare Clinics:General practitioner networks handle routine boosters and catch-up schedules for established patients.
- Pharmacies:Retail accessibility supports last-minute tourist demand with limited consultation depth.
- Online Pharmacies:Digital booking platforms aggregate appointment scheduling across clinic networks for price comparison.
- Vaccination Camps:Mass administration events for pilgrimage and corporate mobilization achieve economies of scale in single-location deployment.
Travel clinic specialization holds premium pricing power through bundled service models. Occupational health integration is climbing fastest as employer-funded programs displace out-of-pocket payment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement programs and international health certificate requirements are redrawing geographic demand patterns across the travel vaccines landscape. WHO prequalification standards and national immunization schedules now determine which manufacturers can access institutional contracts in each jurisdiction.
United States
Employer-funded corporate travel health programs in mining and consulting sectors drive institutional demand through occupational health networks. FDA lot release testing creates seasonal bottlenecks at peak travel windows, compressing inventory availability. Travel clinic concentration in Houston and Denver serves energy sector expatriate deployments to Sub-Saharan Africa.
Germany
Integrated occupational health providers bundle pre-departure immunization services under single contracts with multinational firms. EMA accelerated assessment pathways for platform-based vaccines shorten development timelines for emerging indications. Munich and Frankfurt clinic networks anchor corporate procurement consolidation across Central European business corridors.
Switzerland
Pharmaceutical headquarters clustering generates specialized travel health demand from executive and research staff rotations. Swissmedic maintains stringent batch release protocols that align with WHO prequalification standards for international certificate validity. Basel and Zurich occupational health centers serve as procurement hubs for global corporate accounts.
Vietnam
Accelerating outbound tourism and healthcare worker emigration concentrate demand for Japanese encephalitis and typhoid immunizations. National Expanded Program on Immunization infrastructure provides distribution backbone for travel-relevant vaccines. Ho Chi Minh City and Hanoi travel clinic networks are expanding capacity to serve regional departure corridors.
Australia
Microneedle patch pilot programs for self-administered boosters are reducing nurse time requirements in specialized travel clinics. TGA alignment with WHO digital certificate frameworks enables interoperability with international border verification systems. Sydney and Melbourne airport kiosk deployments are testing point-of-care immunization without traditional clinical infrastructure.
Global Travel Vaccines Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established cold-chain infrastructure and tropical disease portfolios. Consolidation pressure from WHO prequalification standards is compressing the supplier base for yellow fever and Japanese encephalitis vaccines. Three archetypes dominate: legacy vaccine manufacturers with installed capacity, mRNA platform specialists extending indications, and regional bulk antigen suppliers. Competitive moves center on manufacturing partnerships to secure prequalification status and heat-stable formulation development to unlock last-mile access.
Within the diversified pharmaceutical tier, GlaxoSmithKline plc and Sanofi SA exemplify incumbents leveraging integrated R&D and manufacturing networks. Pfizer Inc. represents the platform-extension archetype, applying mRNA capabilities beyond pandemic applications. Among specialized European developers, Valneva SE and Bavarian Nordic AS occupy positions focused on travel-relevant tropical disease indications.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Merck & Co. Inc. |
| GlaxoSmithKline plc |
| CSL Ltd |
| Valneva SE |
| Pfizer Inc. |
| AstraZeneca plc |
| Bavarian Nordic AS |
| Sanofi SA |
| Others |
Supply & Pricing Matrix
WHO prequalification standards gate both supplier qualification and price differentiation simultaneously, restricting government procurement eligibility to certified manufacturers while creating tiered pricing spreads between prequalified and non-prequalified product sources. Certification compliance costs concentrate pricing power among incumbents with established quality management systems, while buyers face limited substitution options for international health certificate requirements.
Pricing Analysis
Certification level (WHO-prequalified versus non-prequalified) creates the primary spread across product tiers, with FDA-grade and EMA-inspected formats commanding 25-40% premiums over regional alternatives in corporate procurement channels. Three-tier pricing structure separates premium prequalified vaccines from standard nationally-registered formats and economy-tier bulk antigen supplies. Pricing pressure stems from third-party administrator consolidation in German and Swiss corporate travel programs, compressing negotiation margins for multi-product portfolios. Leisure tourists at retail pharmacies exhibit highest price sensitivity, while mining and oil sector expatriate programs demonstrate lowest sensitivity due to duty-of-care liability frameworks.
Supply Chain Analysis
Strategic stockpiling preferences dominate over just-in-time approaches for thermolabile formulations, with national immunization programs and travel clinic networks maintaining 3-6 month safety buffers against cold-chain disruption. Manufacturing concentrates in India for bulk antigens, Belgium and France for finished formulation, and Singapore for regional distribution hubs. Production draws from Vero cell substrates, purified polysaccharides, and synthetic mRNA templates as primary inputs. Single-source vulnerability amplifies disruption risk during Indian export restriction episodes. Distribution runs through validated cold-chain logistics networks with temperature monitoring from manufacture to point-of-administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified personnel for ICH Q1A stability studies represent the critical capability gap constraining new entrant scale-up, with incumbent manufacturers capturing disproportionate returns on scarce technical expertise.
For Market Incumbents: Compound manufacturing partnerships with Indian bulk antigen suppliers to secure prequalification status for yellow fever and Japanese encephalitis portfolios. Add lyophilization capacity in Singapore or Switzerland to develop heat-stable formulations before obsolescence risk materializes for existing 2-8°C infrastructure. mRNA platform specialists extending into tropical diseases pose the primary substitution threat requiring accelerated combination vaccine development. For New Entrants and Emerging Players: FDA master file submission fast-tracks offer the most viable entry path for tropical disease developers seeking premium pricing in North American travel health networks. Philippines travel clinic expansion presents underpenetrated whitespace across 7,000+ islands serving outbound healthcare workers and seafarer populations. Microneedle array patch technology enables airport kiosk deployment without traditional clinical infrastructure investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across mRNA platform manufacturing as cold-chain infrastructure requirements expand addressable market reach. Platform-technology developers with WHO prequalification pathways offer strongest 5-10 year viability given regulatory barrier sustainability. Watch for heat-stable formulation regulatory acceptance as inflection indicator for legacy cold-chain asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Opens government procurement and international certificate eligibility for tropical disease portfolios. |
| Heat-Stable Formulation Development | Lyophilization unlocks last-mile access in Sub-Saharan Africa and rural Latin America without refrigeration. |
| Corporate Travel Health Contracting | Third-party administrator consolidation in Germany and Switzerland compresses price cycles for multi-product suppliers. |
| Microneedle Patch Pilot Programs | Self-administered boosters reduce nurse time and enable airport kiosk deployment in Australia and Singapore. |
| Digital Health Certificate Integration | WHO framework extension to yellow fever creates interoperability standards for border automation infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at vaccine manufacturers, travel clinic medical directors, corporate occupational health managers, and national immunization program officers and refined through secondary validation. Sources included WHO prequalification databases, FDA lot release records, EMA GMP inspection reports, and national procurement tender documents. Bottom-up demand modeling across traveler profiles and disease targets triangulated with top-down market sizing from manufacturer revenue disclosures.
Variance decomposition across the projection horizon isolates volume drivers (outbound tourism acceleration, corporate travel mandates) from price drivers (certification tier spreads, channel premium capture). Segmentation dimensions modeled include vaccine type, traveler profile, disease indication, and distribution channel. CAGRs derive from logistic diffusion curves for platform adoption and epidemiological risk mapping for endemic disease exposure. Forecast inputs incorporate WHO International Health Regulations enforcement intensity and EMA accelerated assessment pathway maturation.
Underlying assumptions cover sustained cold-chain infrastructure investment, stable WHO prequalification standards, and continued corporate duty-of-care expansion, with deviation risk concentrated in export restriction episodes from Indian bulk suppliers and heat-stable formulation regulatory breakthroughs. Revision becomes warranted when microneedle patch self-administration achieves regulatory acceptance for primary series indication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Anti-Inflammatory Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Long-Acting Insulin Market