
 North America Enterprise Biometrics Market | 2026-2036
North America Enterprise Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Enterprise Biometrics Market Insights
Subscription-based and as-a-service financing is fragmenting the competitive landscape for enterprise biometric deployments across North America. HID Global Corporation leverages its installed base in physical access control to extend recurring revenue streams. IDEMIA anchors large-scale government credentialing programs through long-term service contracts rather than hardware sales. Thales Group competes by integrating biometric modules into broader digital identity platforms, reducing upfront capital barriers for mid-market buyers.
North America Enterprise Biometrics encompasses automated identity verification systems that capture, process, and match unique physiological or behavioral characteristics—fingerprint minutiae patterns, facial geometry vectors, iris texture codes, or voiceprint frequencies—against enrolled templates to authenticate individuals with false acceptance rates typically below 0.001 percent in enterprise-grade implementations. These systems serve commercial and institutional security applications where password-based authentication proves insufficient against credential theft and synthetic identity fraud. Facial recognition captures the fastest growth trajectory among technology segments, driven by contactless deployment advantages and algorithmic accuracy gains from deep learning architectures. The corporate sector end-user category generates the deepest margin pools, as enterprises prioritize seamless workforce authentication integrated with zero-trust network architectures.
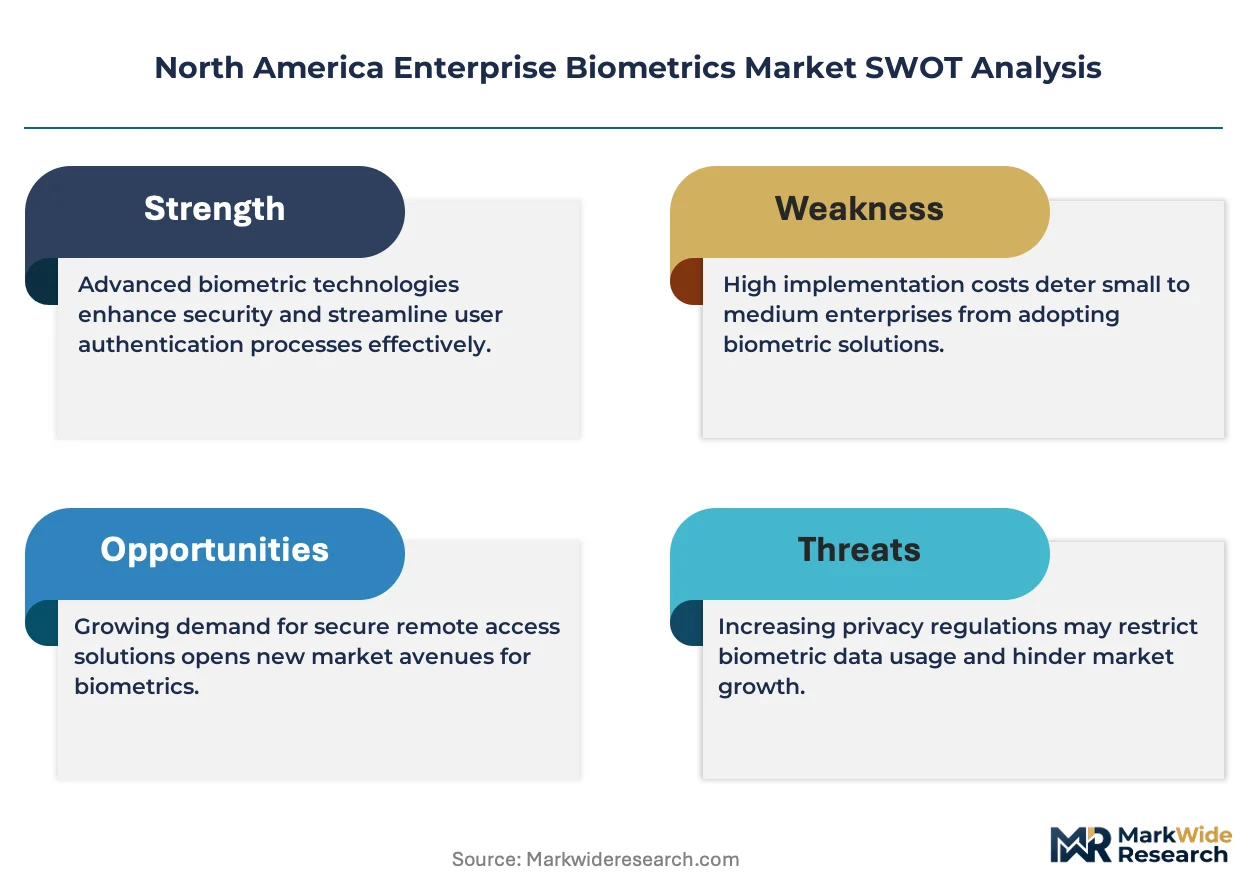
FDA guidance on biometric-enabled medical device access, NIST SP 800-63 digital identity guidelines, and state-level frameworks such as Illinois BIPA and Texas CUBI collectively shape product development roadmaps and liability exposure for vendors operating across United States jurisdictions. Canadian federal procurement under the Directive on Security Management mandates certified biometric interoperability, creating a dual-compliance burden for cross-border solution providers. Stakeholders must monitor the divergence between permissive federal procurement standards and restrictive state privacy enforcement to calibrate geographic deployment strategies and feature roadmaps.
Market Dynamics
Deep learning architectures are collapsing the performance gap between contactless facial recognition and legacy fingerprint systems, forcing vendors to reprice hardware portfolios and accelerate software-centric service transitions.
Growth Catalysts
- Illinois BIPA enforcement:Private right of action provisions are compelling financial services firms to upgrade consent-management infrastructure, creating replacement demand for compliant biometric platforms.
- Zero-trust network mandates:Federal agencies are binding physical access control to logical identity verification, driving converged procurement of multimodal biometric suites.
- Deep learning inference:Edge-optimized neural networks are reducing false acceptance rates below enterprise thresholds without specialized hardware, expanding addressable mid-market accounts.
Market Restraints
- Algorithm training data concentration:High-quality facial geometry datasets cluster with three commercial providers, creating vendor lock-in and royalty escalation risk for second-tier integrators.
- Texas CUBI notification requirements:Mandatory disclosure protocols are extending sales cycles by four to eight weeks for multi-state deployments.
- Silicon supply fragility:Specialized image signal processors for iris cameras concentrate with Taiwan-based foundries, exposing lead time volatility.
Strategic Opportunities
- Canadian federal credentialing:The Directive on Security Management is mandating certified interoperability, opening service contracts for cross-border compliance specialists.
- Voiceprint-behavioral fusion:Converging speaker recognition with keystroke dynamics is creating passwordless authentication for remote workforce segments.
- State-level privacy fragmentation:Divergent enforcement between California, Illinois, and Texas is creating demand for modular policy engines that localize consent workflows.
Industry Challenges
- Biometric template migration:Legacy fingerprint databases use proprietary minutiae formats that resist interoperability with modern facial recognition platforms, forcing expensive re-enrollment campaigns.
- NIST SP 800-63-3 certification timelines:Identity assurance level validations are extending product launch windows by nine to fourteen months for vendors seeking federal eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Enterprise Biometrics Market |
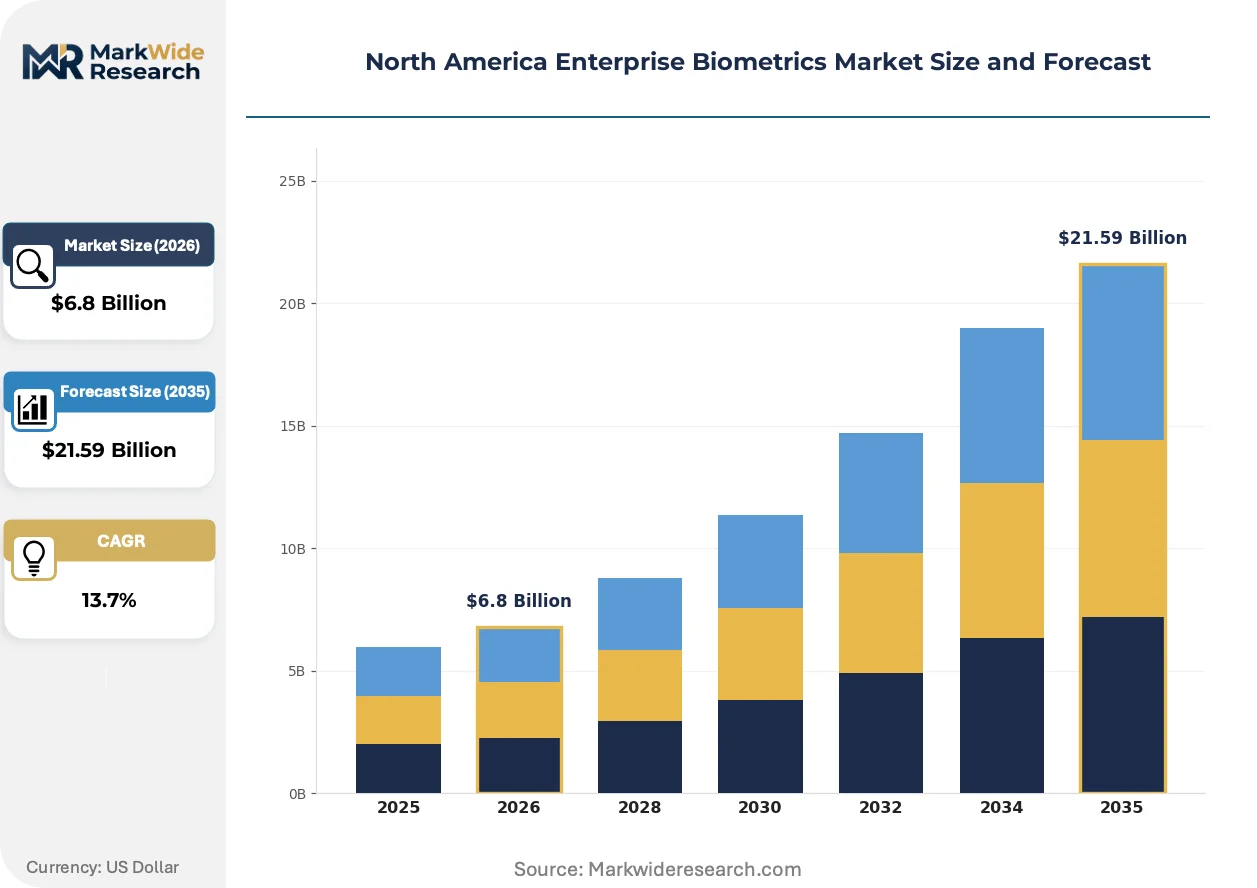
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Access Control, Time & Attendance, Financial Services, Law Enforcement End User: Government Agencies, Healthcare Providers, Educational Institutions, Corporate Sector Deployment: On-Premises, Cloud-Based, Hybrid, Embedded |
| Companies Covered | Fulcrum Biometrics, Inc., Aware, Inc., Bayometric LLC, HID Global Corporation, Veridium Ltd., M2SYS Technologies, IDEMIA, Thales Group, Innovatrics, s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Enterprise Biometrics Market Trends and Innovations
Algorithmic commoditization is compressing hardware margins while elevating software and service layers as primary value capture mechanisms. Vendors are repositioning around continuous authentication and identity proofing rather than point-in-time matching.
Contactless facial recognition is collapsing the installed base advantage of fingerprint-dominant access control systems. Corporate security departments are adopting camera-based authentication for lobby entry and workstation unlock at replacement rates exceeding prior forecasts. The technology is collapsing capital expenditure requirements for multimodal deployments by eliminating dedicated sensor hardware.
NIST SP 800-63 digital identity guidelines are tightening liveness detection requirements for federal contractors. Vendors must integrate presentation attack detection into facial recognition pipelines to maintain procurement eligibility. Defense and intelligence agency suppliers are absorbing the highest compliance burden, passing certification costs through to program budgets.
Enterprise buyers are unbundling biometric authentication from monolithic physical access contracts. Security operations teams are procuring facial recognition APIs through cloud marketplaces and integrating via zero-trust orchestration layers. This pattern is most visible among technology sector headquarters in California, where DevOps-oriented procurement teams favor consumption-based pricing over perpetual licenses.
North America Enterprise Biometrics Market Segmentation
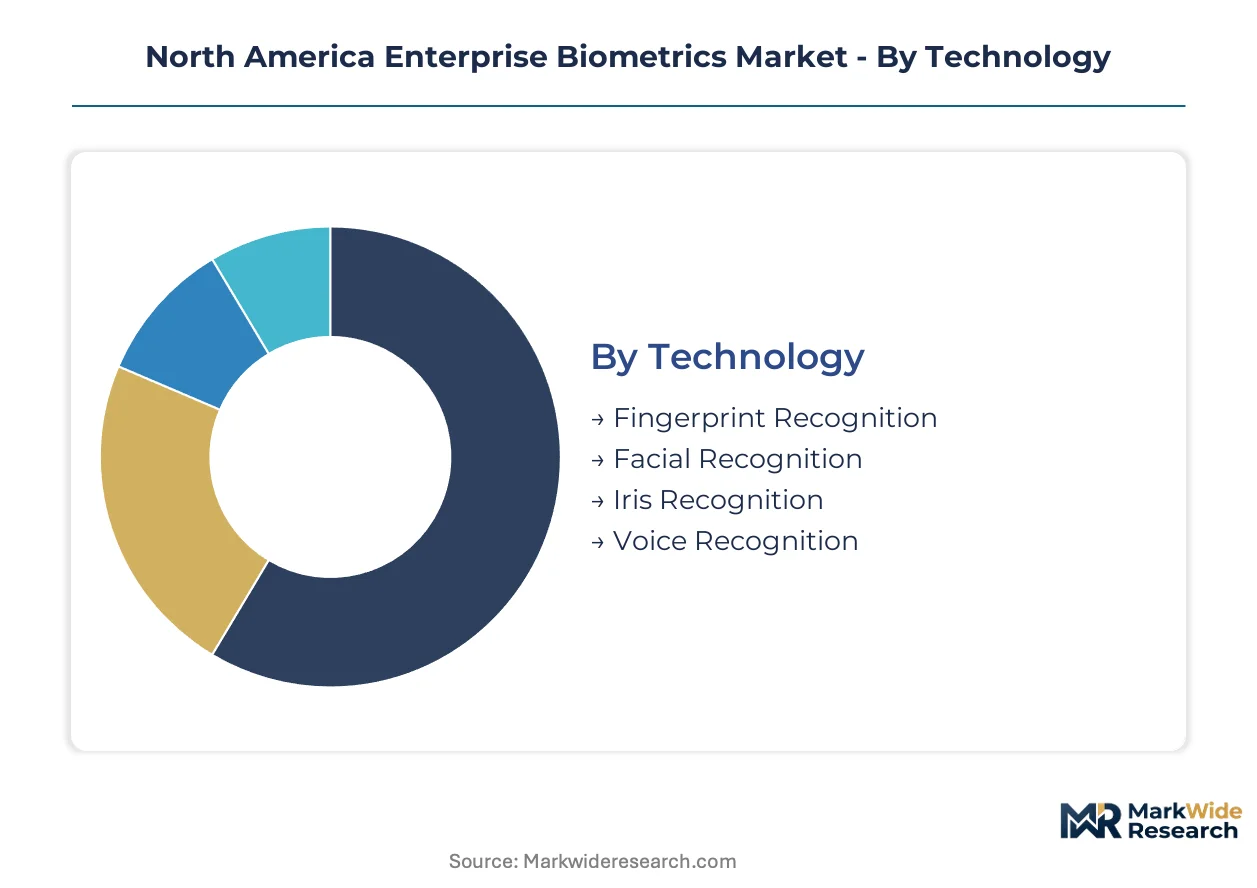
Enterprise biometric procurement in North America fragments across four structural dimensions that determine pricing architecture, compliance burden, and vendor selection criteria. Technology choice dictates hardware versus software margin profiles, while deployment models reshape capital expenditure patterns across federal and commercial accounts.
Technology:
Mature fingerprint systems anchor installed base maintenance revenue, while emerging modalities capture replacement cycles and greenfield expansion.
- Fingerprint Recognition:Minutiae-based matching against enrolled templates delivers sub-0.001% false acceptance rates in enterprise implementations. Federal agencies and financial services firms in Texas and New York concentrate replacement demand where legacy systems face Illinois BIPA consent-management retrofit requirements.
- Facial Recognition:Deep learning architectures processing facial geometry vectors enable contactless authentication without dedicated sensor hardware. Corporate headquarters in California and federal zero-trust mandates drive fastest adoption, collapsing capital barriers for mid-market buyers previously priced out of multimodal deployments.
- Iris Recognition:Texture-code matching from near-infrared imaging serves high-assurance defense and intelligence applications with specialized hardware requirements.
- Voice Recognition:Speaker recognition systems processing voiceprint frequencies support remote workforce authentication and call center fraud prevention.
Fingerprint recognition handles the majority of throughput; facial recognition is climbing the fastest on share.
Application:
Cost tier stratification separates mission-critical federal deployments from commercial workforce management implementations.
- Access Control:Converged physical-logical authentication binds building entry to network session verification under zero-trust architectures. Federal agency mandates and corporate headquarters in California, Texas, and New York drive procurement of multimodal suites with liveness detection compliance.
- Financial Services:Fraud prevention applications authenticate high-value transactions and account recovery against synthetic identity attacks. Illinois BIPA enforcement compels consent-management infrastructure upgrades across banking and insurance operations.
- Time & Attendance:Workforce verification systems replace badge-based clock-in with biometric proof-of-presence for payroll integrity.
- Law Enforcement:Mobile and fixed-station identification supports field booking and investigative matching against enrolled databases.
Access control absorbs the largest program budgets; financial services is expanding most quickly as BIPA litigation accelerates platform replacement.
End User:
Customer type determines procurement channel—federal contracts through certified vendors versus commercial self-service cloud marketplace acquisition.
- Government Agencies:Federal and state entities mandate NIST SP 800-63-3 certification with extended validation timelines. Defense and intelligence suppliers absorb highest compliance burden for liveness detection and presentation attack detection integration.
- Corporate Sector:Enterprise security operations teams unbundle authentication from monolithic access contracts, procuring facial recognition APIs through cloud marketplaces with consumption-based pricing. Technology sector headquarters in California favor DevOps-oriented procurement over perpetual licenses.
- Healthcare Providers:FDA guidance on biometric-enabled medical device access shapes product development roadmaps for patient verification and clinician authentication.
- Educational Institutions:Campus security and student services applications drive demand for cost-optimized deployments with simplified enrollment workflows.
Government agencies dominate certified procurement volume; corporate sector is gaining share fastest through cloud marketplace disruption.
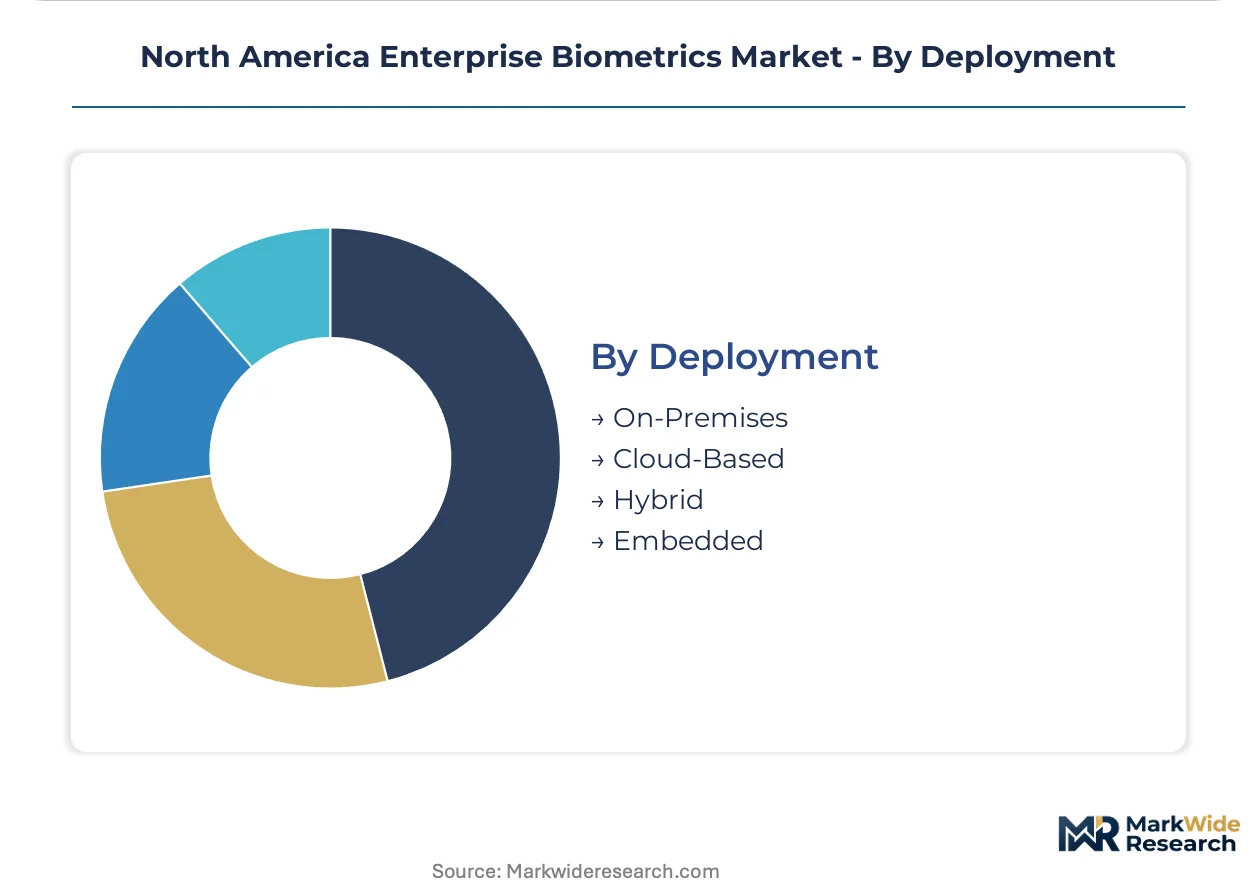
Deployment:
Supply concentration in cloud infrastructure versus edge hardware reshapes vendor margin capture and buyer total cost of ownership.
- Cloud-Based:API-delivered biometric matching eliminates on-site infrastructure, enabling mid-market buyers to access enterprise-grade accuracy without capital expenditure. DevOps-oriented procurement teams in California technology headquarters favor consumption-based pricing models.
- On-Premises:Dedicated hardware deployments retain preference for federal agencies and regulated industries with data residency requirements. NIST certification timelines extend product launch windows by nine to fourteen months for vendors seeking federal eligibility.
- Hybrid:Split architectures process enrollment on-premises with matching in cloud environments, balancing latency and scalability requirements.
- Embedded:Biometric modules integrated into endpoint devices support workstation unlock and mobile authentication without network dependency.
On-premises retains the largest installed base; cloud-based is expanding most quickly as marketplace procurement patterns consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American enterprise biometrics market operates with net service exports to other regions, as Canadian and U.S. vendors supply credentialing platforms abroad while importing specialized iris imaging sensors from Asian manufacturing clusters. Cross-border procurement flows concentrate between federal agencies and defense contractors spanning both countries.
United States
Federal zero-trust mandates and Illinois BIPA litigation are accelerating multimodal biometric procurement across financial services and government sectors. NIST SP 800-63-3 certification requirements extend vendor launch timelines by nine to fourteen months for federal eligibility. Corporate headquarters in California, Texas, and New York are unbundling authentication from legacy access contracts, favoring cloud marketplace acquisition over perpetual licenses.
Canada
The Directive on Security Management mandates certified biometric interoperability for federal procurement, creating compliance demand for cross-border solution providers. Health Canada guidance shapes medical device access applications in healthcare settings. Ontario and Quebec host the densest concentration of government credentialing programs and financial services fraud prevention deployments.
Mexico
Financial sector modernization is expanding biometric authentication for digital banking and remittance verification. The country's national data protection authority enforces consent frameworks for biometric data collection. Mexico City anchors enterprise demand from multinational corporate headquarters and banking operations requiring North American compliance alignment.
North America Enterprise Biometrics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithm modules and sensor hardware. The vendor base stratifies across three tiers: multinational conglomerates with defense credentials, mid-scale specialists in government credentialing, and cloud-native entrants targeting DevOps procurement teams. Competitive positioning depends on NIST certification status, federal contract eligibility, and API-first architecture. Dominant moves include portfolio diversification into adjacent identity verification services and geographic expansion through Canadian federal procurement channels.
Among the named participants, HID Global Corporation and IDEMIA occupy positions within the platform integrator tier, exemplifying vendors with established physical access control installed bases extending into recurring service revenue. Thales Group represents the multinational conglomerate archetype with defense and aerospace credentialing heritage. Aware, Inc. and Innovatrics, s.r.o. sit within the component specialist category, supplying algorithmic engines and biometric middleware to systems integrators rather than end-user deployments.
| Leading Market Players |
|---|
| Fulcrum Biometrics, Inc. |
| Aware, Inc. |
| Bayometric LLC |
| HID Global Corporation |
| Veridium Ltd. |
| M2SYS Technologies |
| IDEMIA |
| Thales Group |
| Innovatrics, s.r.o. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwan-based foundries for specialized image signal processors creates simultaneous pricing volatility in iris recognition hardware and supply chain fragility across North American enterprise biometric deployments. This concentration forces tiered pricing spreads between NIST-certified federal systems and mid-market facial recognition platforms while compressing margins for second-tier integrators locked into royalty-bearing algorithm licenses.
Pricing Analysis
Federal agency buyers anchor the premium tier through NIST SP 800-63-3 certified multimodal suites with liveness detection, while DevOps-oriented technology firms in California drive consumption-based API pricing at the mid-market. Price differentiation rests on certification grade and after-sales service bundling, with federal contractors absorbing nine-to-fourteen-month validation costs. Cost compression in cloud-delivered facial recognition is intensifying because deep learning inference eliminates dedicated sensor hardware. Corporate security teams exhibit highest price sensitivity, whereas defense and intelligence agencies prioritize assurance over unit economics.
Supply Chain Analysis
Contract manufacturing for iris camera modules concentrates with Taiwan-based foundries and select South Korean electronics manufacturing service providers. Component sourcing draws from China for optical sensors, Taiwan for image signal processors, and the United States for NIST-certified algorithm engines. Single-source vulnerability in near-infrared imaging chips exposes lead time volatility for high-assurance deployments. Distribution runs through certified systems integrators for federal accounts and cloud marketplaces for commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep learning commoditization of facial recognition algorithms is collapsing hardware margins and forcing vendor repositioning toward continuous authentication services. Illinois BIPA private right of action provisions and Texas CUBI notification requirements create simultaneous compliance burden and replacement demand across financial services.
For Market Incumbents: Build switching-cost moats through biometric template migration services that bridge legacy fingerprint databases with modern facial recognition platforms. Deepen federal contract eligibility by accelerating NIST SP 800-63-3 certification pipelines ahead of zero-trust mandate expansion. Threat from cloud-native API entrants demands channel control through zero-trust orchestration layer partnerships.
For New Entrants and Emerging Players: Mid-market commercial accounts in Texas and New York outside federal certification requirements represent the most penetrable entry point for edge-optimized facial recognition without specialized hardware. Canadian federal credentialing programs under the Directive on Security Management offer cross-border compliance specialization gaps. Voiceprint-behavioral fusion for remote workforce authentication provides a differentiated go-to-market angle against established physical access incumbents.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors algorithm specialists with NIST certification momentum over hardware-heavy legacy vendors. Long-term viability hinges on software-centric recurring revenue models displacing perpetual license dependence. Acquisition targets should demonstrate federal contract eligibility and API-first architecture. Watch Illinois BIPA settlement volumes as an inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NIST Certification Acceleration | Shortens federal procurement eligibility timelines against zero-trust mandate expansion. |
| API-First Platform Integration | Captures DevOps-oriented procurement teams through cloud marketplace consumption models. |
| Biometric Template Migration Services | Creates recurring revenue from legacy fingerprint database interoperability challenges. |
| Canadian Federal Credentialing Expansion | Opens cross-border service contracts under Directive on Security Management mandates. |
| Voiceprint-Behavioral Fusion Development | Addresses passwordless authentication demand for remote workforce segments. |
Research Methodology
The analysis maps fingerprint recognition, facial recognition, iris recognition, and voice recognition technology segments, each validated through biometric systems engineers, federal procurement officers, corporate security operations directors, and cloud marketplace integration specialists. Primary interviews combined with secondary validation from NIST certification databases, FDA guidance documents, state-level BIPA and CUBI enforcement records, and federal procurement disclosures. Bottom-up vendor revenue triangulation against top-down addressable market sizing anchored segmentation outputs.
Forecast assumptions held fixed the current NIST SP 800-63-3 certification timeline structure and Illinois BIPA enforcement intensity while varying deep learning inference cost curves and cloud marketplace adoption rates across the projection horizon. Segmentation dimensions modeled include technology modality, deployment architecture, end-user sector, and application criticality tier. CAGRs derived from logistic diffusion curves fitted to federal mandate implementation schedules and commercial replacement cycle patterns, with algorithm commoditization velocity and state privacy law divergence as key sensitivity inputs.
Practitioners should monitor NIST SP 800-63 revision schedules, Illinois BIPA litigation settlement trends, and Taiwan semiconductor foundry capacity allocation for early signals of forecast deviation. Quarterly review of federal zero-trust procurement award flows and cloud marketplace biometric API transaction volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
IRIS Biometrics Market
Biometrics & Identity Management
Iris Recognition Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market