
 Europe Decentralized Identity Market | 2026-2036
Europe Decentralized Identity Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Decentralized Identity Market Insights
European digital identity infrastructure is rebalancing toward sovereign credential architectures. Microsoft Corporation leverages its cloud-native stack to anchor enterprise deployments across Frankfurt and Amsterdam data zones. IBM Corporation sustains deep integration with legacy banking cores, while Thales Group dominates hardware security module supply for government-grade issuance. Validated ID, SL specializes in qualified electronic signature interoperability under eIDAS tiers.
Decentralized identity denotes a trust architecture where individuals control credential presentation through cryptographic key pairs without centralized identity providers. The stack combines blockchain anchoring, W3C Decentralized Identifiers, and zero-knowledge proof circuits to verify attributes without exposing underlying data. Self-Sovereign Identity protocols are capturing the fastest expansion as banks seek to offload KYC liability, while Zero-Knowledge Proofs command premium engineering margins due to scarce protocol talent. Secure Access Management applications lead current deployment value, though Digital Onboarding is narrowing the gap as neobanks scale across the eurozone.
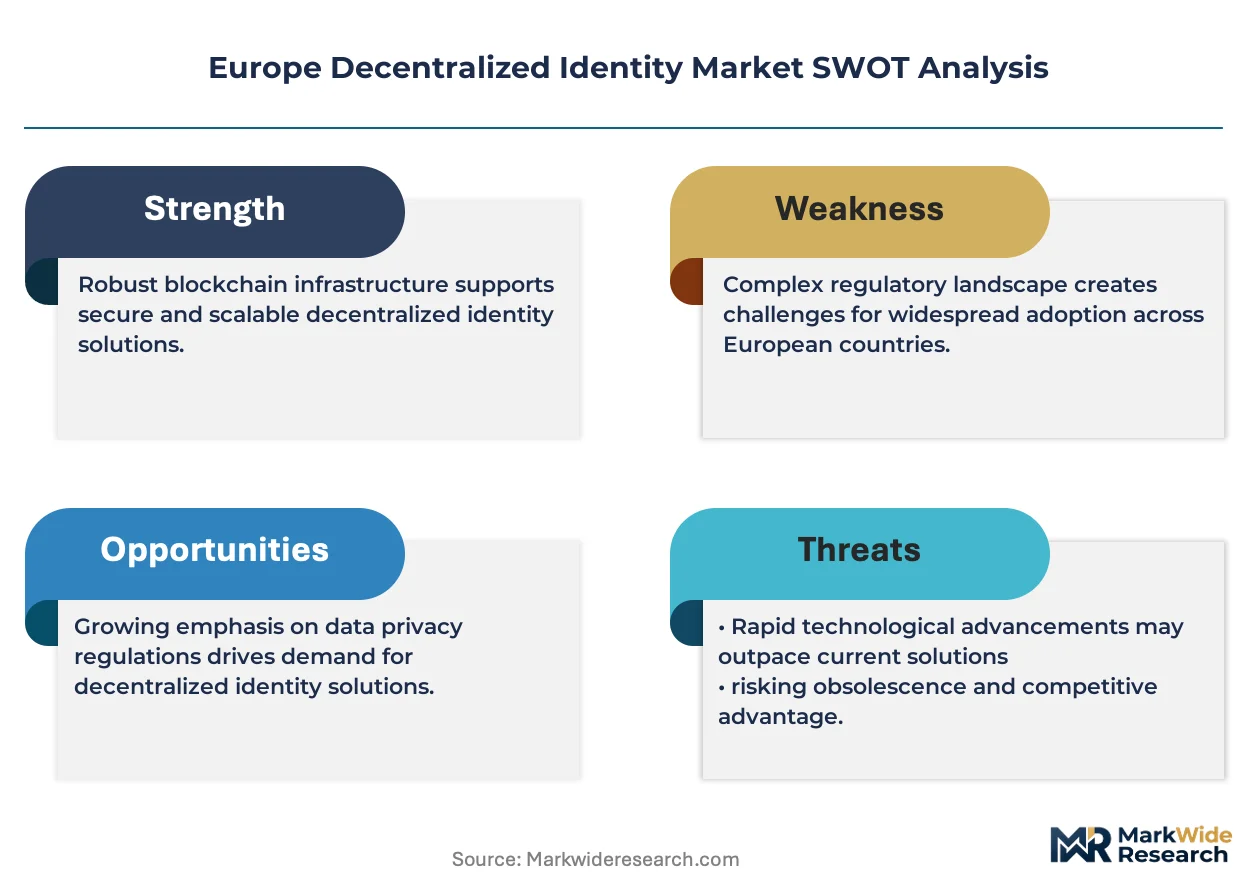
EMA, EFSA, and the EU AI Act collectively shape product standards for identity systems processing biometric or health-adjacent attributes. GDPR enforcement by CNIL and national data protection authorities constrains cross-border credential federation, forcing vendors to localize verification nodes. Stakeholders must monitor whether the European Digital Identity Wallet framework mandates open-source protocol disclosure, which would reshape competitive moats for proprietary stack holders.
Market Dynamics
European banking consortia are offloading KYC liability onto self-sovereign identity protocols, compressing vendor selection cycles and forcing infrastructure localization under GDPR node requirements.
Growth Catalysts
- EU AI Act compliance mandates:Biometric verification systems processing health-adjacent attributes must embed explainable AI audit trails, pulling demand for zero-knowledge proof circuits.
- Neobank digital onboarding pipelines:Amsterdam and Frankfurt data zones are expanding credential issuance capacity to serve eurozone retail banking expansion.
- eIDAS 2.0 wallet interoperability:Qualified electronic signature tiers are standardizing cross-border credential federation between Dutch and Nordic banking corridors.
Market Restraints
- Protocol talent scarcity:Zero-knowledge proof engineering commands premium margins, constraining deployment velocity for mid-tier financial institutions.
- Hardware security module concentration:Government-grade issuance capacity clusters with Thales Group manufacturing footprints, creating single-source risk.
- Cross-border credential friction:CNIL and national data protection authorities enforce divergent localization standards, fragmenting verification node architectures.
Strategic Opportunities
- Swiss and Austrian private banking:Wealth management clients demand sovereign credential architectures for cross-border asset verification.
- Healthcare credential portability:EMA pharmacovigilance requirements are creating demand for patient-controlled clinical trial identity.
- Industrial IoT device attestation:CE marking for connected manufacturing equipment is converging with decentralized identifier anchoring.
Industry Challenges
- Legacy core banking integration:IBM-sustained mainframe architectures resist API-native credential verification, extending deployment timelines.
- GDPR node localization capex:Verification infrastructure must replicate across Frankfurt, Amsterdam, and Nordic zones, multiplying fixed cost bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Decentralized Identity Market |
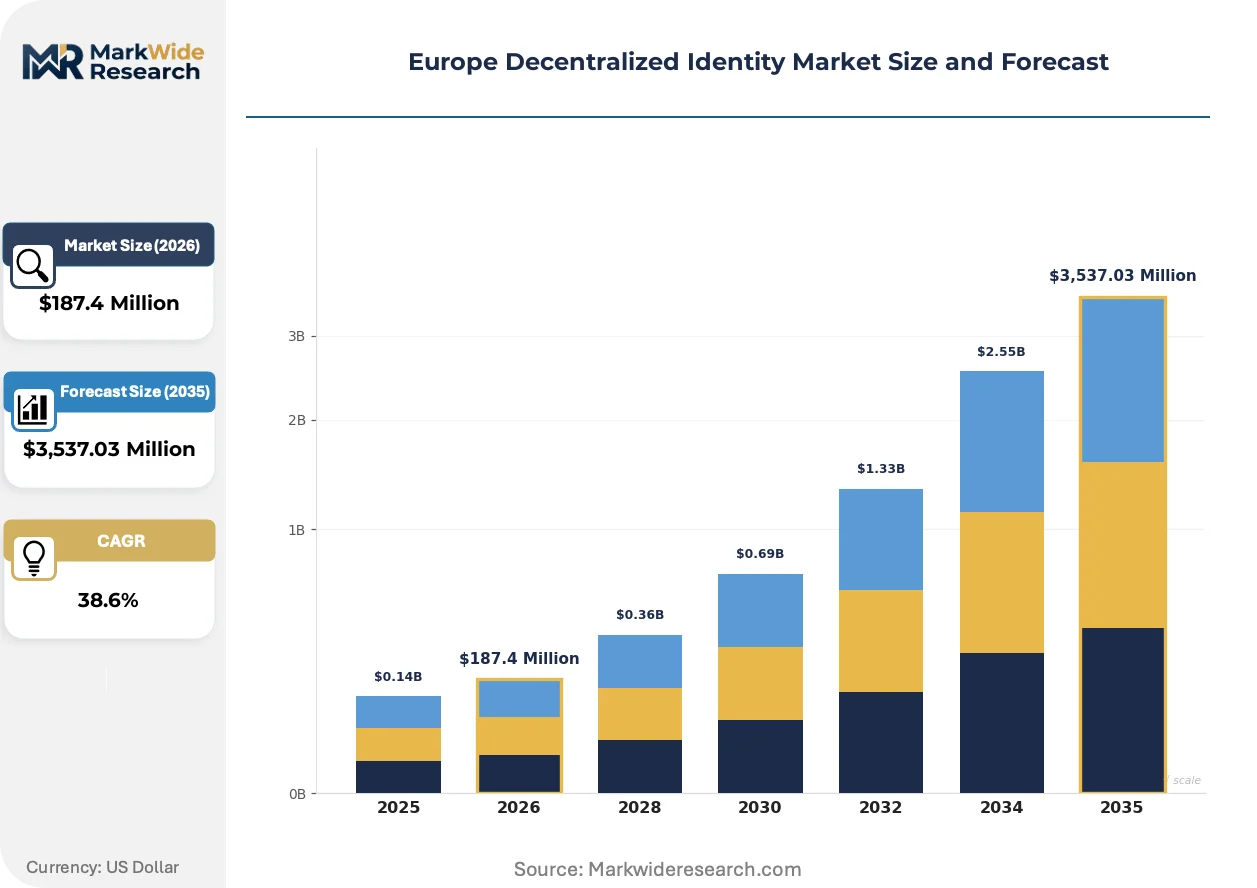
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Self-Sovereign Identity, Zero-Knowledge Proofs, Decentralized Identifiers Application: Digital Onboarding, E-Government Services, Secure Access Management, Identity Verification End User: Financial Institutions, Healthcare Providers, Educational Organizations, Government Agencies Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | Accenture PLC, Microsoft Corporation, Ping Identity Holding Corp., Avast Software s.r.o., Nuggets Ltd, R3 LLC, Validated ID, SL, Thales Group, IBM Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Decentralized Identity Market Trends and Innovations
Protocol standardization and regulatory mandate alignment are compressing vendor differentiation windows across European identity infrastructure deployments.
W3C Decentralized Identifiers combined with blockchain anchoring is automating credential revocation and status checking for financial institutions. Dutch and German banks are deploying these stacks at production scale within eighteen-month windows. This compression is automating vendor consolidation as proprietary protocol moats face open-source disclosure requirements.
EMA guidance on AI-driven identity verification for clinical trial participants is mandating algorithmic transparency documentation. Pharmaceutical sponsors must now embed explainability layers into biometric matching systems. Nordic CROs are responding by pre-qualifying vendors against draft EMA technical standards ahead of formal adoption.
Neobank procurement teams are unbundling identity verification from core banking platform contracts. Monzo-style challengers are sourcing credential verification through API-native specialists rather than incumbent bundled offerings. This pattern concentrates in UK and Netherlands markets where regulatory sandboxes accelerated licensing velocity.
Europe Decentralized Identity Market Segmentation
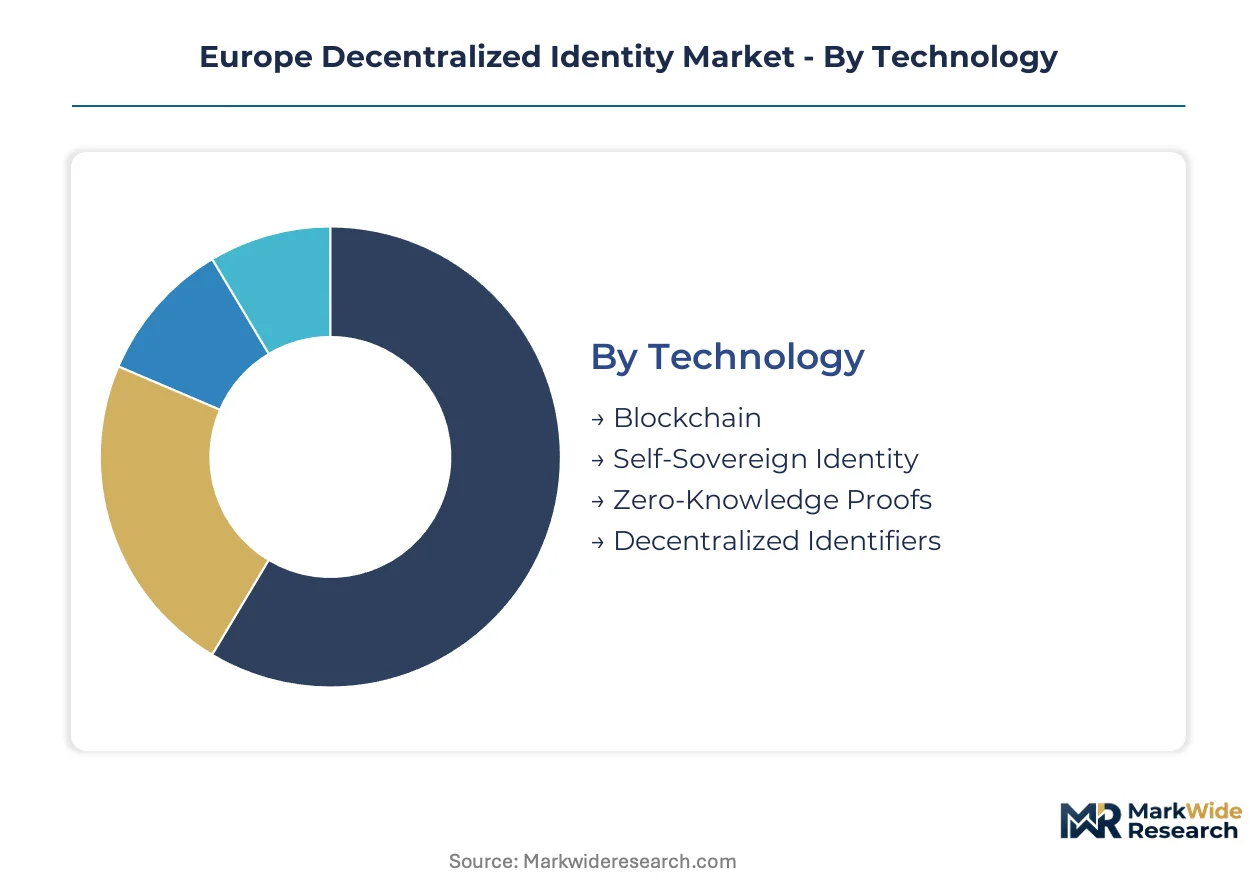
Segmentation in European decentralized identity reveals how regulatory pressure and infrastructure economics split demand across credential architectures. Technology choices determine compliance posture under eIDAS 2.0, while deployment models reflect GDPR node localization requirements.
Technology:
Volume deployments favor established ledger architectures, while premium engineering concentrates in privacy-preserving proof systems where talent scarcity protects margins.
- Blockchain:Anchors credential revocation registries across Dutch and German banking corridors. Frankfurt data zones process the highest transaction volumes for eurozone retail onboarding pipelines.
- Self-Sovereign Identity:Protocols enabling individuals to control credential presentation through cryptographic key pairs without centralized providers. French and German financial institutions are expanding SSI deployments to offload KYC liability under EU AI Act biometric processing rules.
- Zero-Knowledge Proofs:Mathematical circuits verifying attributes without exposing underlying data. Premium engineering margins reflect scarce protocol talent across Amsterdam and Zurich clusters.
- Decentralized Identifiers:W3C-standardized persistent identifiers resolving to public keys without centralized registries. Nordic government pilots are standardizing DID methods for cross-border credential federation.
Today's leader: Blockchain. Tomorrow's challenger: Zero-Knowledge Proofs.
Application:
Secure access management absorbs mature deployment spend, while digital onboarding captures expanding neobank procurement cycles.
- Digital Onboarding:Automated identity verification for account opening without physical document presentation. Amsterdam and Frankfurt data zones are expanding credential issuance capacity to serve eurozone retail banking expansion.
- E-Government Services:Citizen-facing credential issuance for tax, benefits, and licensing interactions. Dutch and Nordic digital wallet interoperability pilots are standardizing qualified electronic signature tiers.
- Secure Access Management:Enterprise authentication replacing password-based systems with cryptographic credential verification. German automotive and industrial conglomerates dominate current deployment value.
- Identity Verification:Attribute matching against authoritative sources without centralized identity provider intermediation. EMA pharmacovigilance requirements are creating demand for patient-controlled clinical trial identity verification.
Secure Access Management holds current deployment value. Digital Onboarding is climbing the fastest as neobanks scale procurement.
End User:
Financial institutions drive procurement volume, while healthcare providers represent the steepest expansion trajectory under EMA guidance.
- Financial Institutions:Banks, insurers, and payment processors implementing credential verification for regulatory compliance. German and French institutions are compressing vendor selection cycles under GDPR node localization mandates.
- Healthcare Providers:Hospitals, clinics, and research organizations managing patient identity for clinical continuity. Nordic CROs are pre-qualifying vendors against draft EMA technical standards for AI-driven identity verification.
- Educational Organizations:Universities and credentialing bodies issuing verifiable academic records. Swiss and Austrian institutions are piloting sovereign credential architectures for cross-border diploma recognition.
- Government Agencies:National and subnational authorities deploying citizen identity infrastructure. eIDAS 2.0 wallet interoperability mandates are accelerating procurement across Dutch and Nordic corridors.
Financial Institutions anchor current demand. Healthcare Providers are gaining share fastest under EMA algorithmic transparency requirements.
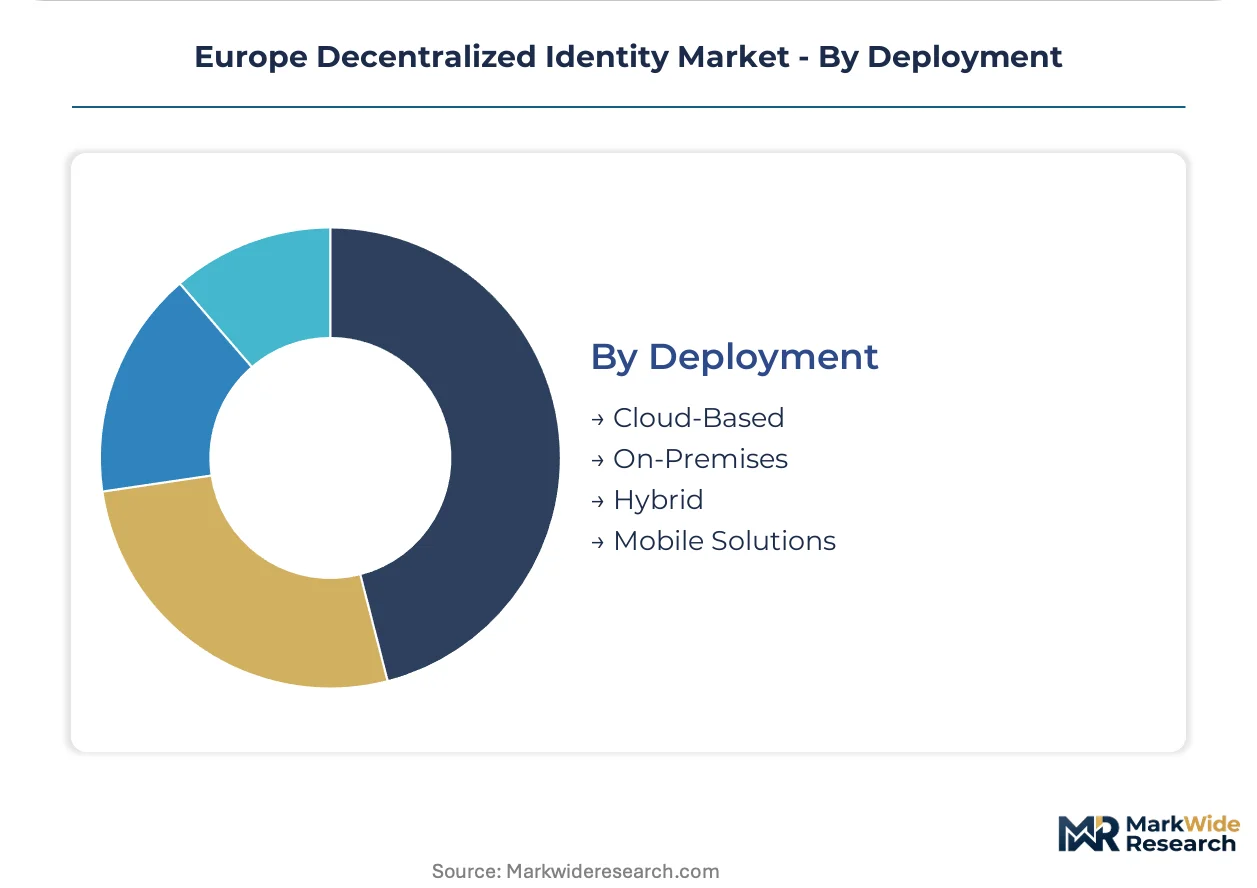
Deployment:
Cloud-based architectures dominate neobank procurement, while hybrid models capture regulated institutions navigating GDPR node fragmentation.
- Cloud-Based:Fully managed credential verification infrastructure without on-premises hardware. Microsoft cloud-native stacks anchor enterprise deployments across Frankfurt and Amsterdam data zones.
- On-Premises:Self-hosted verification nodes with direct hardware security module integration. Thales Group manufacturing footprints concentrate government-grade issuance capacity for French and German agencies.
- Hybrid:Split architectures with sensitive operations on-premises and scalable verification in cloud zones. GDPR enforcement by CNIL and national data protection authorities is fragmenting verification node architectures toward hybrid models.
- Mobile Solutions:Smartphone-native credential storage and presentation through secure enclaves. European Digital Identity Wallet framework pilots are standardizing mobile-first issuance protocols.
Cloud-Based leads neobank procurement. Hybrid is emerging as the regulated institutional default under divergent localization standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France are compressing vendor selection cycles under divergent GDPR enforcement postures, while the Netherlands and Nordic corridors standardize cross-border credential federation protocols ahead of eIDAS 2.0 mandates.
Germany
Frankfurt data zones anchor the highest transaction volumes for blockchain-anchored credential revocation registries. KBA and BSI technical standards are mandating hardware security module integration for government-grade issuance. Bavarian automotive conglomerates dominate enterprise authentication deployments, while Berlin-Brandenburg hosts the densest cluster of neobank credential verification pipelines.
France
CNIL enforcement is fragmenting verification node architectures toward hybrid cloud-on-premises splits. The EU AI Act biometric processing rules are accelerating self-sovereign identity procurement by Paris-based retail banks. Île-de-France concentrates qualified electronic signature interoperability pilots under eIDAS qualified tier standards.
Netherlands
Amsterdam data zones are expanding credential issuance capacity to serve eurozone retail banking expansion. Dutch digital wallet interoperability pilots are standardizing cross-border federation with Nordic corridors. Randstad banking consortia are unbundling identity verification from core platform contracts, sourcing through API-native specialists.
Sweden
Nordic CROs are pre-qualifying vendors against draft EMA technical standards for AI-driven clinical trial identity verification. Stockholm anchors patient-controlled healthcare credential portability pilots under EMA pharmacovigilance guidance. Swedish government agencies are standardizing W3C Decentralized Identifier methods for cross-border federation with Dutch counterparts.
Switzerland
Zurich and Geneva private banking clusters are demanding sovereign credential architectures for cross-border asset verification. Swissmedic guidance on clinical trial participant identity is converging with EMA algorithmic transparency requirements. Swiss universities are piloting verifiable academic records for cross-border diploma recognition under sovereign credential frameworks.
Europe Decentralized Identity Market Competitive Landscape
German and French producers anchor the regulated institutional tier; Netherlands and UK specialists hold the neobank API-native segment. The vendor base splits between consolidated cloud-native stacks and fragmented protocol engineering boutiques. Three archetypes dominate: legacy-integrated systems vendors, hardware security module manufacturers, and zero-knowledge proof engineering specialists. Competitive moves concentrate on strategic partnerships for GDPR node localization and technology licensing for eIDAS 2.0 wallet interoperability.
Within the legacy-integrated tier, IBM Corporation and Microsoft Corporation exemplify divergent approaches to cloud-native deployment across Frankfurt and Amsterdam zones. Thales Group occupies the hardware security manufacturing position for government-grade issuance capacity. Validated ID, SL represents the qualified electronic signature specialization archetype under eIDAS tier frameworks.
| Leading Market Players |
|---|
| Accenture PLC |
| Microsoft Corporation |
| Ping Identity Holding Corp. |
| Avast Software s.r.o. |
| Nuggets Ltd |
| R3 LLC |
| Validated ID, SL |
| Thales Group |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Specialized semiconductor pricing indices for secure enclave chips cascade through hardware security module manufacturing into tiered credential verification service tiers. Frankfurt and Amsterdam data zone expansion costs feed directly into cloud-native deployment pricing, while Thales Group manufacturing concentration shapes government-grade issuance premiums across French and German procurement cycles.
Pricing Analysis
Distributor margins on hardware security modules compress SaaS-tiered pricing for cloud-native verification services. Pricing stratifies across government-grade qualified signature tiers, enterprise authentication bundles, and neobank API-per-transaction models. Cost compression in mid-tier financial institution deployments stems from protocol talent scarcity forcing vendor consolidation. Neobank procurement teams exhibit highest price sensitivity, while Swiss private banking clients absorb premium sovereign credential architectures without volume negotiation.
Supply Chain Analysis
Dual-sourcing requirements for hardware security modules mandate Thales Group qualification alongside Dutch and German alternative suppliers. Supply chains draw from Taiwan semiconductor foundries for secure enclave chips, French precision manufacturing for cryptographic processors, and Nordic firmware development clusters. Single-source vulnerability concentrates in government-grade issuance capacity. Distribution runs through systems integrators serving Frankfurt and Amsterdam data zones, with API-native specialists bypassing traditional channel layers for neobank direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European decentralized identity rests on zero-knowledge proof engineering premiums and GDPR node localization forcing hybrid deployment upgrades. Protocol standardization under eIDAS 2.0 compresses vendor differentiation windows, concentrating returns with stack-integrated incumbents and specialized cryptography boutiques.
For Market Incumbents: Anchor cloud-native verification capacity across Frankfurt and Amsterdam data zones to capture neobank procurement unbundling from core banking platforms. Defend against API-native specialist encroachment by embedding qualified electronic signature interoperability directly into Microsoft and IBM enterprise stacks. Certification investment in EMA algorithmic transparency documentation protects pharmaceutical vertical expansion against emerging zero-knowledge proof boutiques. For New Entrants and Emerging Players: eIDAS 2.0 wallet interoperability mandates in the Netherlands and Nordic corridors open a window for API-native credential verification specialists. Healthcare credential portability under EMA pharmacovigilance guidance represents the most penetrable segment, with Nordic CROs pre-qualifying vendors ahead of formal standards adoption. Go-to-market positioning as zero-knowledge proof engineering boutiques commands premium margins unavailable to generalized authentication providers. For Investors and Strategic Acquirers: Asymmetric upside sits with zero-knowledge proof engineering specialists possessing scarce protocol talent and EMA pre-qualification status. Long-term viability across the analysis window favors acquisition targets with hybrid deployment capabilities spanning cloud-native scalability and on-premises hardware security module integration. The signal to watch is European Digital Identity Wallet framework open-source disclosure mandates, which would reshape competitive moats for proprietary stack holders.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR Node Localization Partnership | Hybrid deployment capabilities satisfy CNIL fragmentation requirements across French and German verification architectures. |
| Zero-Knowledge Proof Talent Acquisition | Protocol engineering scarcity protects premium margins in Amsterdam and Zurich cryptography clusters. |
| eIDAS 2.0 Wallet Interoperability Certification | Cross-border credential federation unlocks Dutch-Nordic banking corridor procurement cycles. |
| EMA Algorithmic Transparency Pre-Qualification | Clinical trial identity verification positions vendors ahead of formal pharmaceutical sponsor mandates. |
| Hardware Security Module Dual-Source Qualification | Mitigates Thales Group concentration risk for government-grade issuance capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at neobank challengers, regulatory affairs leads at French and German financial institutions, platform engineers at cloud infrastructure providers, and procurement officers at Nordic CROs with secondary validation against eIDAS 2.0 regulatory filings, EMA draft technical standards, GDPR enforcement decisions by CNIL and national data protection authorities, and hyperscaler data zone expansion disclosures. Bottom-up credential verification transaction modeling and top-down infrastructure investment flow analysis provided cross-check triangulation.
Historical reference periods anchored the projection horizon to observed deployment cycles across Dutch and German banking corridors, with modeled segmentation spanning self-sovereign identity protocols versus blockchain-anchored revocation registries, cloud-native versus hybrid deployment architectures, and financial institution versus healthcare provider end-use verticals. CAGRs derived from credential issuance capacity expansion rates and neobank procurement velocity indicators, with algorithmic transparency requirements and hardware security module manufacturing constraints as industry-specific forecast inputs.
Revisions become necessary when EMA finalizes algorithmic transparency standards, when European Digital Identity Wallet framework mandates open-source protocol disclosure, or when GDPR enforcement diverges further across national data protection authorities. Deviation in zero-knowledge proof engineering talent availability or hardware security module manufacturing capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Global Authentication Services Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Software Market
Biometrics & Identity Management
Global Biometric Card Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
ID Verification Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Global Authentication and Brand Protection Market
Biometrics & Identity Management
Identity Theft Protection Services Market
Biometrics & Identity Management
Biometric Smart Cards Market
Biometrics & Identity Management
Global Mobile User Authentication Market