
 Asia-Pacific MPU Market | 2026-2036
Asia-Pacific MPU Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific MPU Market Insights
China's dual carbon goals from MEE are shifting procurement criteria toward energy-efficient fabrication across the Asia-Pacific MPU supply chain. TSMC leverages its foundry scale to dominate advanced node production in Taiwan. Samsung Electronics Co., Ltd. anchors memory-integrated logic strategies through South Korean fabrication complexes. MediaTek Inc. specializes in cost-optimized mobile processor designs for mid-tier OEMs.
A microprocessor unit executes sequential digital instructions through integrated arithmetic logic, control units, and register arrays fabricated at nanometer-scale process nodes such as 5nm or 3nm. These devices serve as the central computation engine in systems ranging from smartphones to industrial controllers. Microprocessor segments lead value generation due to premium pricing on sub-7nm architectures, while FPGA applications in telecommunications infrastructure represent the fastest-growing demand pool. Automotive Systems deployment is displacing Consumer Electronics as the primary volume driver across the Asia-Pacific MPU landscape.
Japan's METI semiconductor revitalization framework, South Korea's K-Semiconductor Belt incentives, and China's GB standards on integrated circuit quality collectively shape market access and capital allocation decisions. Taiwan's NSTC oversight of strategic technology exports further constrains cross-border equipment flows. Stakeholders must monitor how subsidy reciprocity rules and export control harmonization alter foundry expansion timelines across the region.
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is creating supply-side bottlenecks that reshape procurement timelines across the Asia-Pacific MPU landscape. Automotive OEMs now compete with data center operators for advanced node allocation.
Growth Catalysts
- Automotive Electronics Mandates:China's MIIT efficiency standards and dual carbon goals from MEE compel domestic OEMs to source high-performance MPUs for electric powertrain controllers and ADAS modules.
- Japan's METI Semiconductor Revitalization:Subsidy frameworks for domestic fabrication facilities attract capital toward advanced packaging and specialty logic production.
- 5nm Process Maturation:Yield improvements at leading foundries reduce unit costs for smartphone SoCs and edge AI accelerators, expanding addressable volume in mid-tier consumer devices.
Market Restraints
- EUV Lithography Equipment Concentration:Single-source dependency for extreme ultraviolet scanners constrains capacity expansion timelines regardless of capital availability.
- Silicon Wafer Input Volatility:300mm prime wafer supply tightens when memory makers crowd out logic buyers during DRAM pricing upswings.
- Cross-Border Export Controls:Taiwan's NSTC oversight of strategic technology flows fragments equipment procurement across national boundaries.
Strategic Opportunities
- Southeast Asia Backend Assembly:Malaysia and Vietnam develop advanced packaging corridors to capture value from wafer-level integration demand.
- Chiplets and Heterogeneous Integration:Die disaggregation enables fabless designers to mix process nodes within single packages, reducing reliance on bleeding-edge monolithic yields.
- South Korea's K-Semiconductor Belt:Tax incentives and infrastructure commitments attract foreign equipment vendors to co-locate near Samsung and SK Hynix fabrication clusters.
Industry Challenges
- Specialized Process Engineering Talent:Shortages of 3nm GAA transistor designers and yield optimization specialists extend product qualification cycles.
- Legacy Node Dependency:Automotive and industrial controllers require 28nm-40nm capacity that foundries deprioritize for advanced node economics, creating allocation conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific MPU Market |
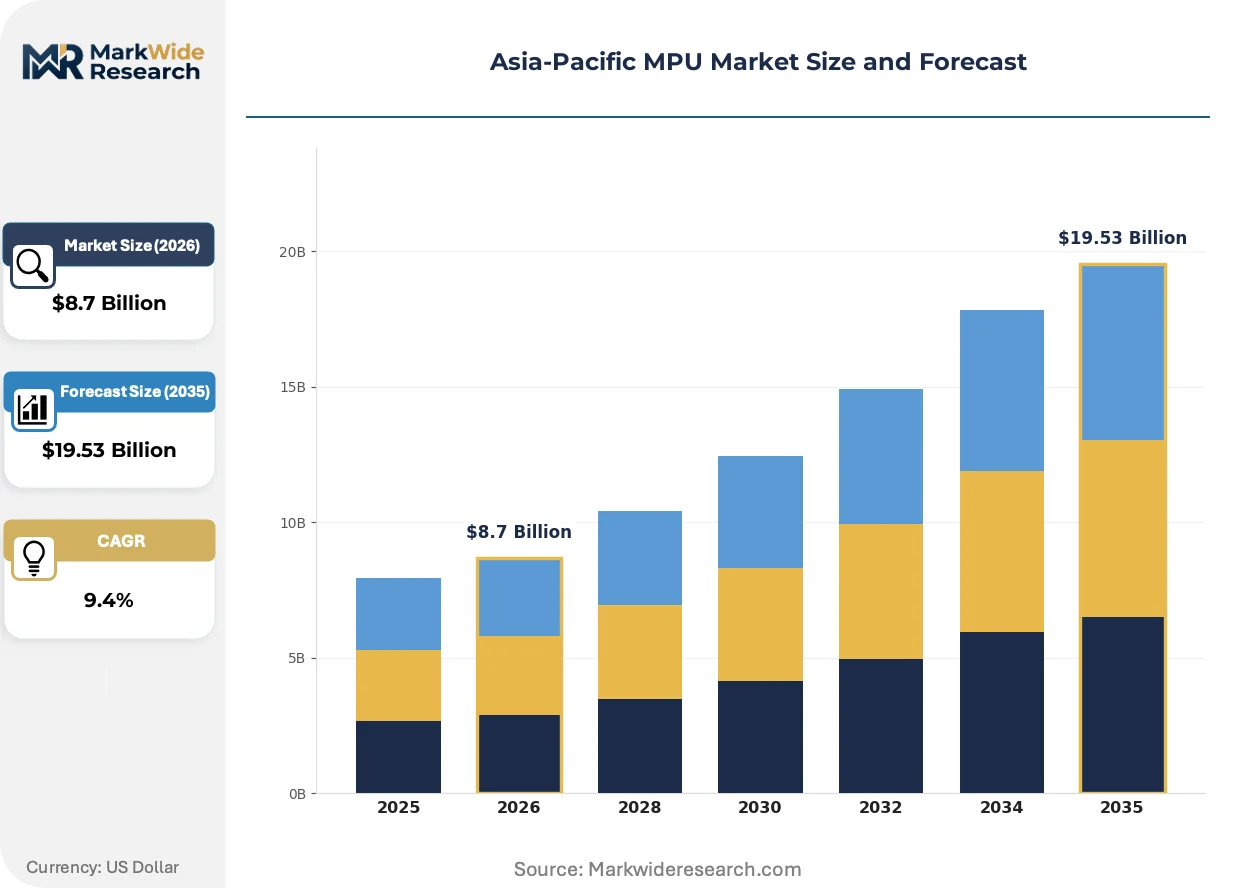
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontroller, Microprocessor, DSP, FPGA Application: Consumer Electronics, Automotive Systems, Industrial Automation, Telecommunications End User: Consumers, OEMs, System Integrators, Government Agencies Technology: Embedded Systems, VLSI, IoT Devices, Cloud Computing |
| Companies Covered | Intel Corporation, TSMC, SK Hynix Inc., Nvidia, Samsung Electronics Co., Ltd., Qualcomm Technologies, Advanced Micro Devices, Sony, MediaTek Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific MPU Market Trends and Innovations
Three forces reshape the Asia-Pacific MPU competitive landscape: process node bifurcation between leading-edge and mature platforms, regulatory fragmentation of equipment flows, and automotive demand cycles decoupling from consumer electronics seasonality.
Gate-all-around transistor architecture is electrifying power efficiency benchmarks for mobile and data center processors. Samsung Foundry and TSMC deploy GAA at 3nm and 2nm nodes to serve AI training chip designers and flagship smartphone OEMs. This geometry transition compresses voltage scaling headroom and forces EDA tool vendors to retool parasitic extraction workflows.
China's GB standards on integrated circuit quality and reliability tighten qualification protocols for automotive-grade MPUs. Domestic foundries must demonstrate zero-defect traceability to supply electric vehicle inverters and battery management systems. Foreign suppliers face parallel audits under MIIT certification and MEE environmental compliance, duplicating compliance overhead.
Automotive OEMs now negotiate direct allocation agreements with foundries, bypassing traditional distributor channels. Tier-1 semiconductor suppliers lose volume commitment leverage as BYD, Toyota, and Hyundai establish captive procurement offices in Hsinchu and Seoul. This disintermediation concentrates in China and South Korea, where vertical integration between vehicle brands and chip designers accelerates fastest.
Asia-Pacific MPU Market Segmentation
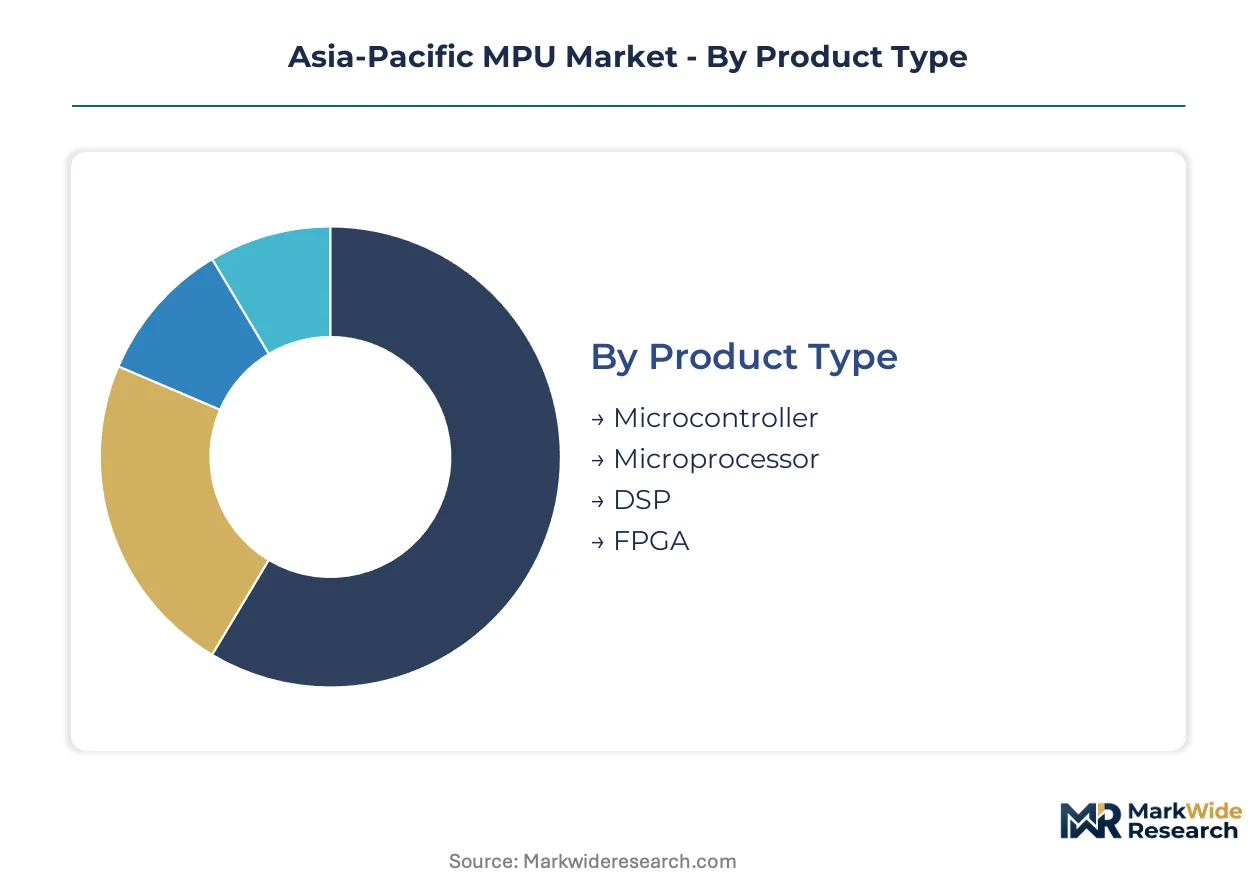
Segmentation reveals how MPU procurement priorities diverge across buyer types in Asia-Pacific. Automotive OEMs prioritize thermal resilience and qualification protocols. Consumer electronics brands chase die shrinks for power efficiency. Government buyers impose localization mandates that reshape supplier eligibility.
Product Type:
Cost tiers separate hobbyist-grade components from mission-critical silicon in this category.
- Microprocessor:Central processing units integrate arithmetic logic, control units, and register arrays at nanometer-scale nodes such as 5nm or 3nm. Data center operators in Taiwan and South Korea dominate procurement for AI training accelerators, though yield constraints at 2nm GAA nodes extend lead times.
- Microcontroller:Self-contained systems-on-chip embed processor cores with memory and peripherals on single dies. China's electric vehicle OEMs now source automotive-grade MCUs under MIIT efficiency mandates for powertrain controllers and battery management systems.
- DSP:Specialized architectures execute multiply-accumulate operations for signal processing workloads. Baseband processors in 5G infrastructure deployments across Japan and South Korea drive volume.
- FPGA:Field-programmable gate arrays enable post-fabrication logic reconfiguration for prototyping and low-volume production. Telecommunications infrastructure in Southeast Asia represents expanding demand as network operators trial open RAN architectures.
Microprocessor leads volumes today; FPGA is gaining share fastest.
Application:
End-use maturity determines whether buyers accept legacy nodes or demand bleeding-edge fabrication.
- Automotive Systems:Electric powertrain controllers, ADAS modules, and domain controllers require AEC-Q100 qualification and zero-defect traceability. BYD, Toyota, and Hyundai now maintain captive procurement offices in Hsinchu and Seoul to secure direct foundry allocation.
- Consumer Electronics:Smartphones, tablets, and wearables prioritize die shrinks for battery life extension. Mid-tier OEMs in China source cost-optimized designs from fabless houses as 5nm yields mature and unit economics improve.
- Industrial Automation:Programmable logic controllers and motion control systems demand 10-15 year supply continuity. Japanese machine tool builders face allocation conflicts as foundries deprioritize 28nm-40nm capacity for advanced node economics.
- Telecommunications:Base stations, routers, and optical transport equipment mix merchant silicon with custom ASICs. South Korea's K-Semiconductor Belt tax incentives attract foreign equipment vendors to co-locate near Samsung fabrication clusters serving this vertical.
Consumer Electronics retains installed base dominance; Automotive Systems climbs the fastest.
End User:
Procurement authority concentrates differently across direct consumers versus institutional buyers.
- OEMs:Original equipment manufacturers specify MPUs for integration into finished products. Automotive OEMs in China negotiate direct allocation agreements with foundries, bypassing traditional distributor channels.
- System Integrators:Third-party assemblers combine subsystems for industrial and infrastructure deployments. Malaysia and Vietnam backend assembly corridors capture value from wafer-level integration demand.
- Consumers:Individual purchasers acquire MPUs through retail channels for personal computing and gaming. Volume concentrates in replacement cycles for desktop and laptop platforms.
- Government Agencies:Public sector buyers impose localization and security certification requirements. China's GB standards on integrated circuit quality tighten qualification protocols for suppliers to state-owned vehicle and telecom operators.
OEMs lead volumes today; Government Agencies are expanding procurement most quickly.
Technology:
Integration depth separates edge-deployable silicon from datacenter-scale compute.
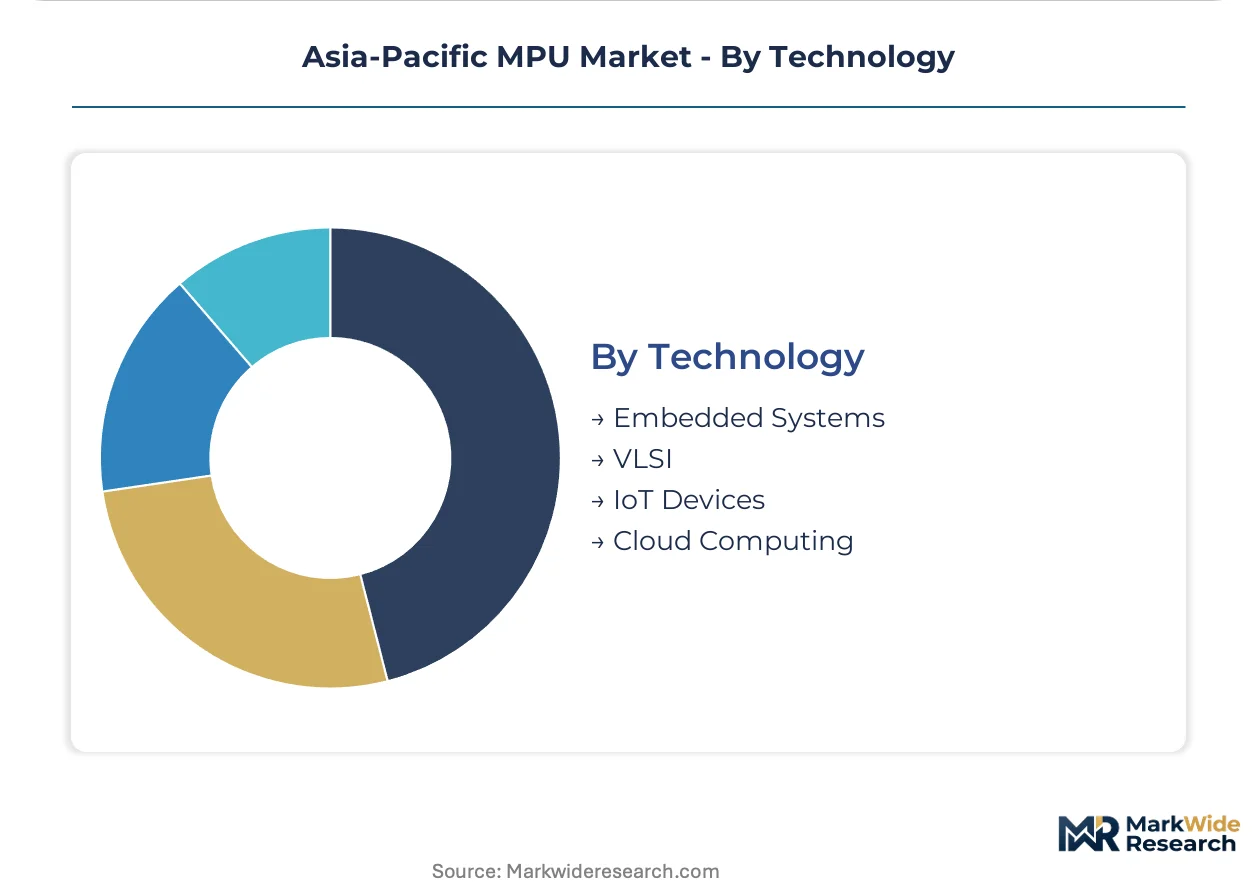
- VLSI:Very-large-scale integration compresses millions of transistors onto single dies for maximum performance density. TSMC's foundry scale dominates advanced node production for flagship smartphone SoCs and AI accelerators.
- Embedded Systems:Dedicated computing resources within larger mechanical or electrical systems. Industrial controllers across Asia-Pacific require real-time deterministic response with extended temperature ranges.
- IoT Devices:Network-connected sensors and actuators with constrained power budgets. Smart home and smart city deployments in Southeast Asia drive microcontroller integration at 40nm and above.
- Cloud Computing:Hyperscale datacenter infrastructure for distributed processing and storage. South Korean and Japanese operators compete for advanced node allocation against automotive buyers.
VLSI leads volumes today; Embedded Systems is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication scaled first in Japan during the 1970s, then migrated to Taiwan and South Korea through government-backed industrial policy. Foundry concentration now defines regional supply architecture across Asia-Pacific.
China
Electric vehicle OEMs BYD and NIO source high-performance MPUs for powertrain controllers and battery management systems under MIIT efficiency mandates. The country's dual carbon goals from MEE compel domestic foundries to demonstrate zero-defect traceability for automotive-grade silicon. Yangtze River Delta clusters in Shanghai and Wuxi concentrate advanced packaging investments targeting wafer-level integration.
Taiwan
Data center operators and AI chip designers compete with automotive buyers for 3nm and 2nm node allocation at leading foundries. NSTC oversight of strategic technology exports constrains cross-border equipment flows to mainland facilities. Hsinchu Science Park anchors the region's most concentrated advanced logic production, with captive procurement offices from Hyundai and Toyota establishing direct allocation channels.
South Korea
Memory-integrated logic strategies dominate as Samsung and SK Hynix fabrication complexes serve 5G baseband and AI accelerator demand. K-Semiconductor Belt tax incentives attract foreign equipment vendors to co-locate near Pyeongtaek and Yongin clusters. Seoul-based fabless houses specialize in cost-optimized mobile processor designs for mid-tier Chinese OEMs.
Japan
Machine tool builders and industrial automation OEMs face allocation conflicts for 28nm-40nm legacy nodes as foundries prioritize advanced geometries. METI semiconductor revitalization subsidies redirect capital toward domestic advanced packaging and specialty logic production. Kyushu and Tohoku regions concentrate automotive-grade MCU qualification facilities under tightened AEC-Q100 protocols.
Southeast Asia
Malaysia and Vietnam backend assembly corridors capture value from heterogeneous integration demand as chiplet architectures proliferate. Open RAN infrastructure trials across Indonesia and Thailand expand FPGA procurement for telecommunications prototyping. Penang and Ho Chi Minh City industrial zones develop advanced packaging capacity to serve Singapore-based fabless design houses.
Asia-Pacific MPU Market Competitive Landscape
Premium-margin players sit above commodity-margin players across process node specialization, with advanced foundry capacity commanding pricing power over legacy node fabricators. The vendor base stratifies into three tiers: integrated device manufacturers with captive fabrication, pure-play foundries at leading-edge nodes, and fabless design houses optimizing for cost-sensitive volume segments. Capacity expansion and strategic technology licensing represent the dominant competitive moves as equipment constraints limit organic growth.
Within the integrated device manufacturer tier, Intel Corporation and Samsung Electronics Co., Ltd. occupy positions spanning design through fabrication, exemplifying vertical control over supply security for automotive and data center OEMs. TSMC anchors the pure-play foundry archetype, representing scale-driven concentration of advanced node production that attracts direct allocation agreements from flagship smartphone and AI chip designers.
| Leading Market Players |
|---|
| Intel Corporation |
| TSMC |
| SK Hynix Inc. |
| Nvidia |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies |
| Advanced Micro Devices |
| Sony |
| MediaTek Inc. |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM captive procurement offices in Hsinchu and Seoul command direct allocation agreements that compress traditional distributor margins and shift pricing power toward foundries with advanced node capacity. This buyer concentration enables TSMC and Samsung to enforce premium pricing on 3nm GAA production while legacy node fabricators face cost compression from capacity oversupply.
Pricing Analysis
Three-tier pricing structure across automotive-grade, enterprise-grade, and consumer-grade silicon separates qualification-intensive automotive MPUs from commodity smartphone SoCs. Price differentiation hinges on AEC-Q100 certification tier and wafer-level integration complexity. Margins are tightening at mature nodes as Chinese foundries add 28nm capacity faster than industrial demand absorbs it. Consumer electronics brands exhibit highest price sensitivity, while automotive OEMs accept premium positioning for zero-defect traceability.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong coordinate hub-and-spoke logistics for Southeast Asian backend assembly corridors. Front-end fabrication concentrates in Taiwan, South Korea, and Japan. EUV lithography equipment and 300mm prime wafers constitute critical input dependencies. Single-source vulnerability for ASML scanners creates equipment procurement bottlenecks that extend lead times regardless of capital availability. Distribution runs through direct foundry allocation agreements that disintermediate traditional semiconductor distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific MPU market functions as a stable compounder anchored by automotive electronics mandates from China's MIIT that sustain structural demand growth across economic cycles.
For Market Incumbents: To counter disintermediation by automotive OEM captive procurement offices, TSMC and Samsung should deepen foundry-distributor partnerships in Southeast Asian backend corridors while accelerating 2nm GAA yield maturation to defend premium positioning. Certification investment in AEC-Q100 automotive protocols represents a critical lever for margin protection against Chinese foundry competition. For New Entrants and Emerging Players: Cloud marketplace routes for FPGA intellectual property licensing offer lower-friction entry than capital-intensive fabrication. Malaysia and Vietnam backend assembly corridors present the most penetrable geography for advanced packaging specialization. A fabless design house targeting open RAN telecommunications infrastructure can capture prototyping demand before merchant silicon commoditization. For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, seeking captive supply security through vertical integration into chip design. The market supports long-term viability for specialty logic fabricators with established automotive qualification protocols. Foundry utilization rates at 3nm nodes serve as the critical signal to watch for inflection in pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Node Capacity Expansion | TSMC's 2nm GAA ramp secures allocation agreements from AI chip designers and flagship smartphone OEMs. |
| Automotive Qualification Investment | AEC-Q100 certification enables supply contracts with BYD and Toyota for powertrain controllers. |
| Backend Assembly Localization | Malaysia's Penang corridor captures heterogeneous integration demand from Singapore fabless houses. |
| Memory-Logic Integration Strategy | Samsung's Pyeongtaek complexes serve 5G baseband demand through South Korea's K-Semiconductor Belt. |
| Direct Allocation Agreement Negotiation | Hyundai's Seoul procurement office bypasses distributors to secure 3nm automotive MPU supply. |
Research Methodology
Direct dialogue with foundry operations executives, automotive Tier 1 procurement directors, fabless design house CTOs, and semiconductor equipment vendor sales engineers grounded the qualitative foundation. Secondary validation drew from MIIT efficiency standard filings, METI subsidy disclosure documents, Taiwan NSTC export control registers, and customs data on lithography equipment imports. Bottom-up wafer shipment aggregation and top-down OEM demand modeling were triangulated to reconcile volume estimates.
Bottom-up modeling traced MPU procurement through automotive OEM platform roadmaps, consumer electronics brand product cycles, and telecommunications infrastructure deployment schedules. Segmentation dimensions included product architecture, application vertical, end-user procurement authority, and technology integration depth. CAGRs were derived from foundry capacity expansion timelines and node-specific yield maturation curves. Forecast inputs incorporated EUV scanner delivery schedules and automotive electronics mandate compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for gate-all-around transistor architecture would alter the outlook if yield improvements stall or design costs escalate. Forecasts reflect documented assumptions on foundry utilization, automotive qualification timelines, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Nanopatterning Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
1550nm LiDAR Pulsed Fiber Laser Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market