
 GCC Food Service Market | 2026-2036
GCC Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Food Service Market Analytics
Plant-based protein formulations are consolidating their position as a cost-competitive alternative to imported beef and poultry across GCC commercial kitchens. Alamar Foods Company leverages its vertically integrated supply chain to control protein sourcing costs across Saudi Arabia and Kuwait. Americana Restaurants International PLC anchors its competitive position through deep franchise relationships with global QSR brands operating in Riyadh and Jeddah. Herfy Food Service Company specializes in localized menu engineering that reduces dependence on temperature-sensitive dairy imports.
GCC food service encompasses the commercial preparation, delivery, and sale of prepared meals through institutional, quick-service, and full-service channels, operating under halal certification requirements and cold-chain integrity standards between 0°C and 4°C for perishable components. Full-Service Restaurants and Fast Casual segments capture the dominant share of value, with Fast Casual recording the fastest expansion as young adult demographics in Riyadh and Doha prioritize speed and experiential dining. Online Ordering and Delivery channels now command disproportionate margin attention as platform economics and last-mile logistics reshape operator profitability across the Gulf states.
Saudi Food and Drug Authority (SFDA) halal certification protocols and UAE Ministry of Climate Change and Environment food safety frameworks govern product standards, import clearances, and kitchen audit frequencies for all commercial operators. Municipal health departments in Doha, Manama, and Muscat enforce parallel inspection regimes that elevate compliance costs for smaller independent outlets. Stakeholders must monitor evolving subsidy policies on domestic agriculture and aquaculture that could redirect procurement patterns for proteins and fresh produce across the six Gulf monarchies.
Market Dynamics
Platform economics and last-mile logistics are compressing operator margins across the Gulf states, forcing commercial kitchens to restructure procurement and fulfillment workflows around aggregator-dependent demand patterns.
Growth Catalysts
- Tourism procurement intensity:Dubai and Abu Dhabi emirates are driving institutional food service contracts as hotel and resort dining operations expand outsourced partnerships.
- SFDA HACCP enforcement:Saudi Arabia's compressed compliance timelines for commercial kitchens are accelerating professionalization of independent outlets.
- Plant-based protein cost parity:Formulated alternatives to imported beef and poultry are reducing protein procurement costs for institutional buyers.
Market Restraints
- Temperature-sensitive dairy dependence:Cold-chain requirements between 0°C and 4°C elevate spoilage risk and logistics costs for operators lacking captive distribution.
- Import concentration for fresh produce:GCC domestic agriculture subsidies remain insufficient to displace procurement from external suppliers.
- Municipal inspection fragmentation:Doha, Manama, and Muscat operate parallel health audit regimes that multiply compliance burdens for multi-city operators.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:Food service procurement professionalization lags behind Saudi Arabia and UAE, creating first-mover positioning for contract specialists.
- Aggregator channel integration:Online ordering platforms enable dark kitchen and cloud kitchen expansion without real estate-heavy front-of-house investments.
- Aquaculture subsidy tailwinds:Evolving domestic fish farming incentives across the six Gulf monarchies could redirect protein sourcing patterns.
Industry Challenges
- Halal certification timeline compression:SFDA protocols and UAE Ministry of Climate Change and Environment frameworks require frequent kitchen audits that strain quality assurance staffing.
- Cold-chain capex intensity:Perishable component handling mandates refrigerated transport and storage investments that disadvantage smaller independent outlets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Food Service Market |
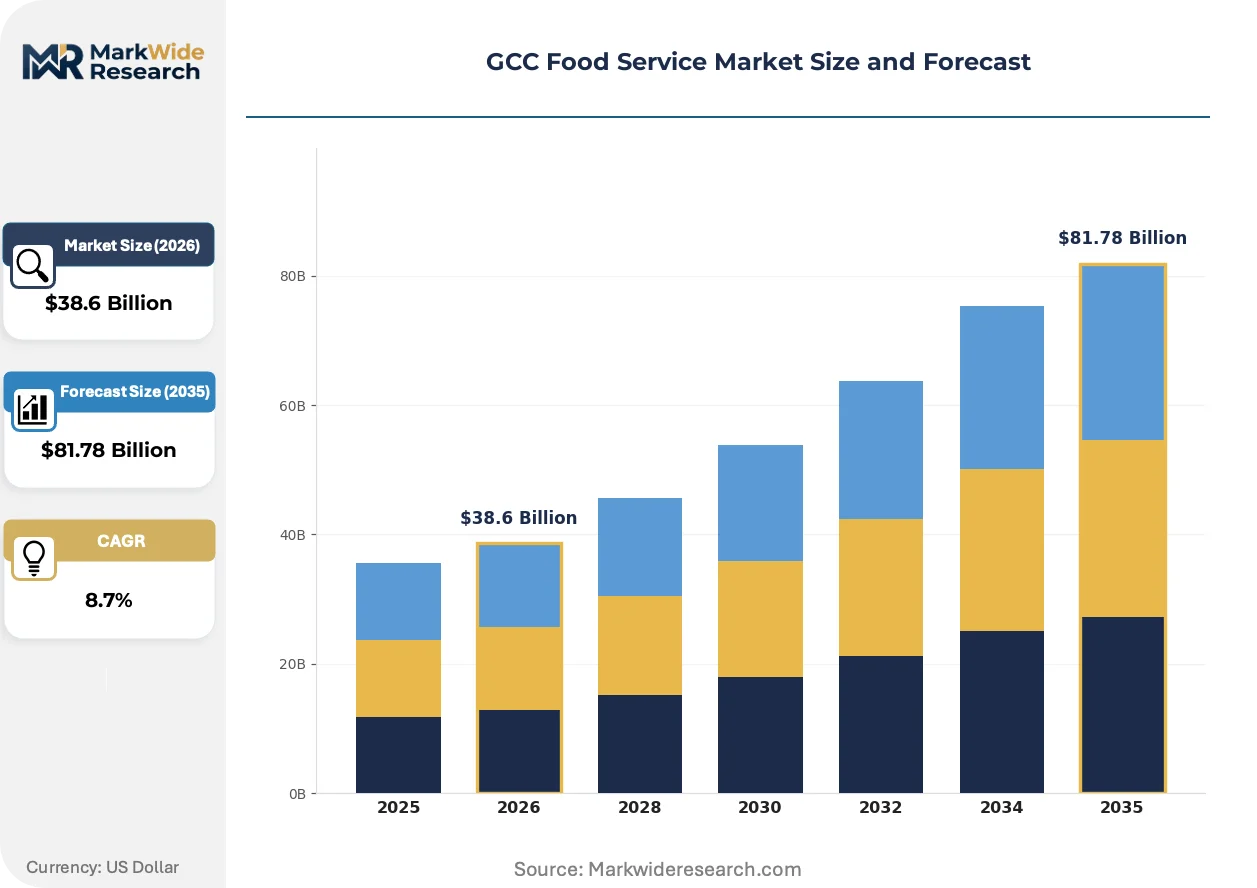
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Casual, Cafés, Food Trucks Customer Type: Families, Young Adults, Business Professionals, Tourists Distribution Channel: Dine-In, Takeout, Delivery, Online Ordering Cuisine Type: Middle Eastern, Asian, Western, Fast Food |
| Companies Covered | Alamar Foods Company, Kudu Company For Food And Catering, ALBAIK Food Systems Company SA, Riyadh International Catering Corporation, MH Alshaya Co WLL, Americana Restaurants International PLC, Herfy Food Service Company, The Sultan Center, Al Tazaj Fakeih, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Food Service Market Evolving Landscape
Digital ordering infrastructure and protein formulation science are restructuring how Gulf commercial kitchens source, prepare, and deliver meals to institutional and consumer segments.
Cloud kitchen infrastructure is decentralizing food service production geography across Riyadh and Jeddah. Real estate developers are retrofitting industrial zones with shared prep facilities for multiple virtual brands. This distributed model compresses capital requirements for market entry while fragmenting traditional full-service restaurant concentration.
UAE Ministry of Climate Change and Environment food safety frameworks are tightening cold-chain documentation requirements for cross-emirate deliveries. Commercial operators must now maintain continuous temperature logging for perishable shipments. Fast-casual chains operating Dubai-Abu Dhabi routes are responding by consolidating supplier relationships with integrated logistics providers.
Young adult demographics in Doha and Riyadh are prioritizing speed and experiential dining over traditional full-service formats. Fast-casual concepts are displacing conventional quick-service in high-traffic retail locations. This preference shift is most visible in mall and airport food courts where seating turnover directly impacts unit economics.
GCC Food Service Market Segmentation
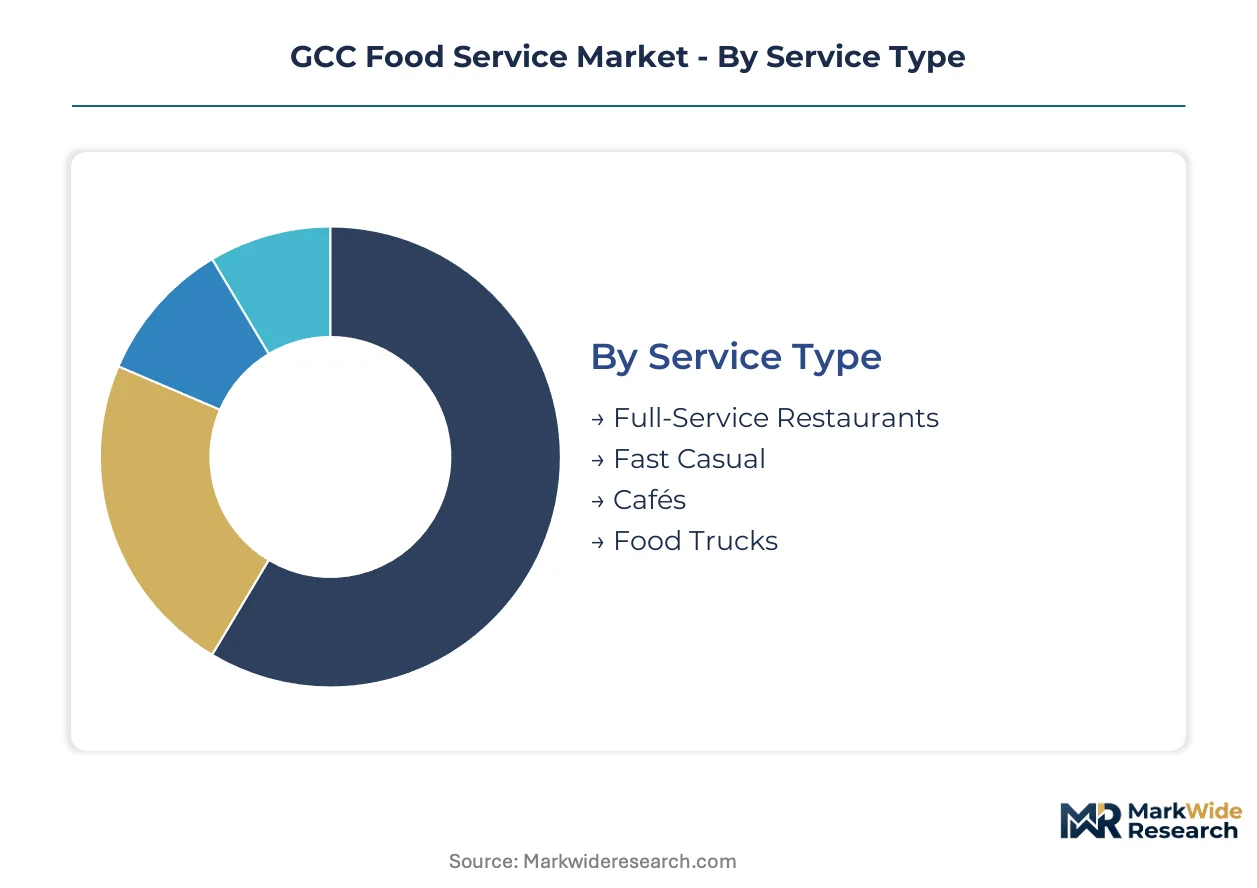
GCC food service segmentation reveals divergent margin profiles across service formats and customer cohorts. Channel economics and cuisine positioning determine capital efficiency and repeat purchase frequency for operators across the six Gulf monarchies.
Service Type:
Volume throughput dominates Fast Casual economics while Full-Service Restaurants command premium pricing through experiential positioning.
- Full-Service Restaurants:Table-service formats with extended dining durations capture celebration occasions and business entertainment spend in Riyadh and Dubai hotel districts. SFDA HACCP compliance timelines compress margin structures for independent operators lacking dedicated quality assurance staffing.
- Fast Casual:Counter-service models with fresh preparation visibility are displacing conventional quick-service in Doha and Riyadh mall locations. Young adult demographics prioritize speed and menu customization, driving seating turnover advantages in high-rent retail footprints.
- Cafés:Beverage-forward formats with limited food menus concentrate in Abu Dhabi and Jeddah professional districts.
- Food Trucks:Mobile kitchen units exploit event licensing and lower municipal compliance burdens in Kuwait and Bahrain.
Today's leader: Full-Service Restaurants. Tomorrow's challenger: Fast Casual.
Customer Type:
Demographic targeting shapes menu engineering and location strategy across the Gulf states.
- Families:Multi-generational dining occasions demand halal-certified kitchens with dedicated children's menu sections and prayer facility proximity in Saudi Arabia and UAE residential zones.
- Young Adults:Single-person and peer-group occasions concentrate in Riyadh and Doha entertainment districts, favoring shareable formats and Instagram-optimized presentation.
- Business Professionals:Corporate catering and lunch-hour occasions prioritize speed and dietary accommodation in Dubai International Financial Centre and King Abdullah Financial District.
- Tourists:Seasonal demand spikes in Dubai and Abu Dhabi hotel corridors require multilingual service protocols and international payment system integration.
Business Professionals anchor weekday revenue stability. Young Adults are gaining share fastest through aggregator platform dependency.
Distribution Channel:
Channel mix determines real estate intensity and labor allocation for Gulf operators.
- Dine-In:Front-of-house service with seating infrastructure commands premium pricing in full-service formats across Jeddah and Manama waterfront locations.
- Takeout:Counter collection without seating reduces rent burden and expands catchment radius for established brands in Muscat and Doha.
- Delivery:Third-party logistics dependency compresses margins through aggregator commission structures while extending reach beyond traditional trade areas.
- Online Ordering:Direct digital channels enable customer data capture and margin recovery from platform intermediation in UAE and Saudi Arabia.
Dine-In retains margin leadership. Online Ordering represents the steepest expansion trajectory.
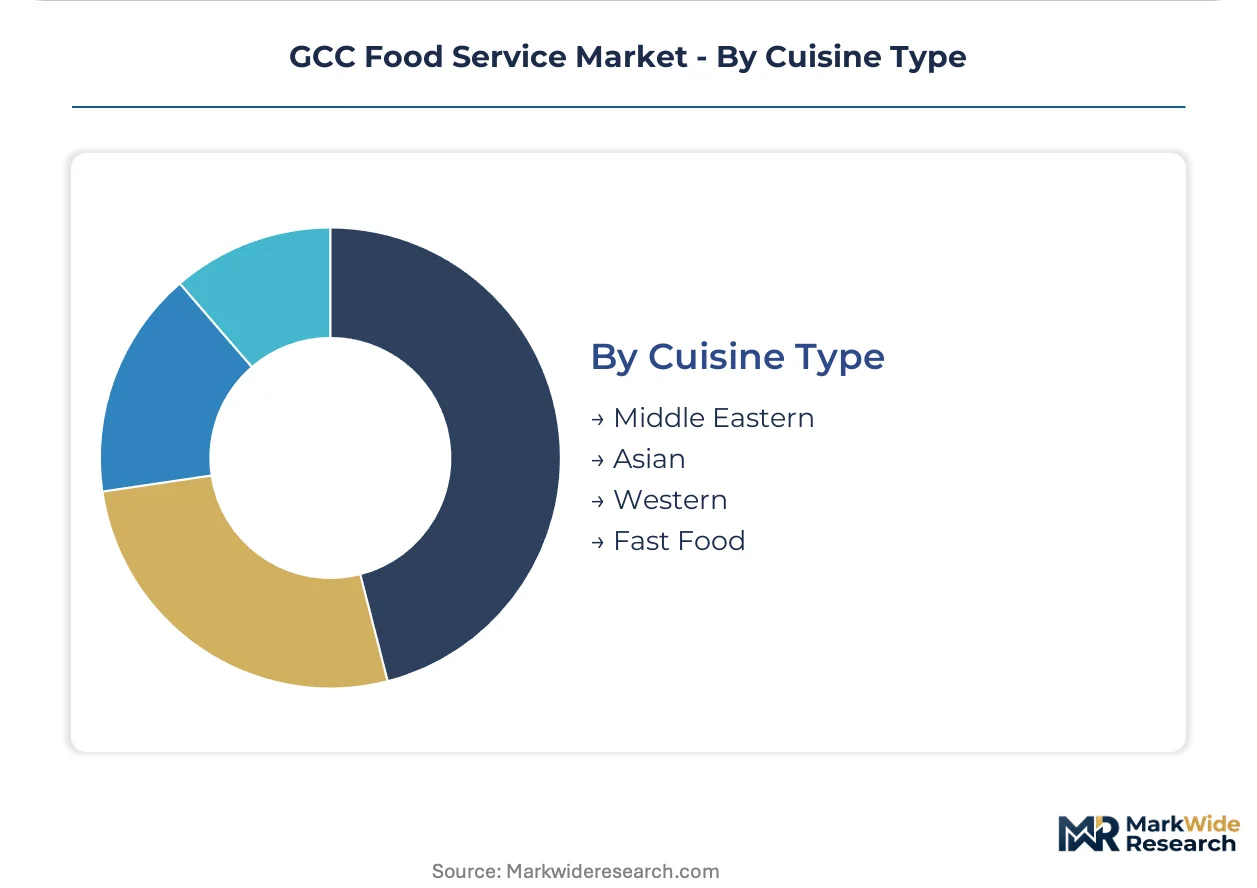
Cuisine Type:
Cuisine positioning governs supply chain complexity and import dependency for GCC kitchens.
- Middle Eastern:Regional formats leveraging local protein and produce sourcing achieve shortest supply chains and strongest halal certification alignment across all six Gulf monarchies.
- Asian:Specialized ingredient import requirements and wok-trained kitchen labor create capability barriers for authentic positioning in Riyadh and Dubai.
- Western:Burger and steakhouse formats face plant-based protein displacement pressure as cost parity with imported beef improves.
- Fast Food:Standardized QSR formats with frozen supply chains dominate highway and airport locations through Americana Restaurants and Alamar Foods franchise networks.
Middle Eastern formats dominate localization advantage. Asian cuisine climbs fastest through young adult demand for experiential variety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors procurement intensity across the GCC food service landscape. Hotel and resort dining operations in the emirate are expanding outsourced partnerships with institutional caterers. Saudi Arabia's municipal health inspectorates are compressing HACCP compliance timelines for commercial kitchens nationwide.
Saudi Arabia
Riyadh and Jeddah are driving fast-casual format expansion as young adult demographics prioritize speed and experiential dining. The Saudi Food and Drug Authority enforces stricter halal certification protocols and compressed kitchen audit frequencies. Cloud kitchen infrastructure is decentralizing production geography across industrial zones in Riyadh, with real estate developers retrofitting shared prep facilities for multiple virtual brands.
United Arab Emirates
Dubai and Abu Dhabi emirates concentrate tourism-driven food service procurement through hotel corridor contracts. The UAE Ministry of Climate Change and Environment mandates continuous temperature logging for cross-emirate perishable shipments. Fast-casual chains operating Dubai-Abu Dhabi routes are consolidating supplier relationships with integrated logistics providers to meet documentation requirements.
Qatar
Doha's entertainment districts are attracting fast-casual concepts targeting young adult peer-group dining occasions. Municipal health departments operate parallel inspection regimes that elevate compliance costs for multi-city operators. Mall and airport food courts in Doha are witnessing seating turnover optimization as operators adapt to preference shifts away from traditional full-service formats.
Kuwait
Kuwait City commercial zones show underpenetration in food service procurement professionalization relative to Saudi Arabia and UAE. The country's municipal health authorities enforce cold-chain integrity standards between 0°C and 4°C for perishable components. Independent outlets in Kuwait City lack captive distribution networks, elevating spoilage risk and logistics costs for temperature-sensitive dairy imports.
Bahrain
Manama waterfront locations retain dine-in margin leadership through front-of-house service infrastructure. Bahrain's municipal inspection frameworks parallel Doha and Muscat regimes, multiplying compliance burdens for regional operators. Food truck operators exploit event licensing and lower municipal compliance burdens in Manama, creating mobile kitchen alternatives to fixed-location establishments.
GCC Food Service Market Competitive Landscape
Global franchise networks compete with regional champions across halal-certified menu engineering and captive supply chain control. The vendor base spans vertically integrated protein sourcers, franchise-heavy QSR operators, and localized menu specialists. Three archetypes dominate: integrated supply chain controllers, deep franchise relationship holders, and regional cuisine adaptation specialists. Competitive moves concentrate on backward integration into protein sourcing and aggregator channel integration for dark kitchen expansion.
Within the integrated supply tier, Alamar Foods Company and Herfy Food Service Company exemplify divergent approaches to procurement cost management. Alamar Foods leverages vertically integrated supply chain structures to control protein sourcing costs across multiple Gulf monarchies. Herfy Food Service occupies a position emphasizing localized menu engineering that reduces import dependency for temperature-sensitive inputs. Americana Restaurants International PLC anchors the franchise-heavy vector through established relationships with global QSR brands operating in Riyadh and Jeddah.
| Leading Market Players |
|---|
| Alamar Foods Company |
| Kudu Company For Food And Catering |
| ALBAIK Food Systems Company SA |
| Riyadh International Catering Corporation |
| MH Alshaya Co WLL |
| Americana Restaurants International PLC |
| Herfy Food Service Company |
| The Sultan Center |
| Al Tazaj Fakeih |
| Others |
Value Network & Pricing Analysis
Halal certification tiering bifurcates GCC food service procurement, with SFDA-audited premium kitchens commanding 15-20% price premiums over municipal-compliant standard outlets while both tiers grapple with identical cold-chain logistics burdens. This divergence manifests in supply chain configurations where premium operators absorb captive distribution investments to protect margin integrity, whereas economy-tier outlets remain exposed to third-party logistics markups.
Pricing Analysis
Input-cost pass-through from imported protein and temperature-sensitive dairy dominates GCC food service pricing dynamics. Three-tier pricing structure across premium halal-certified, standard municipal-compliant, and economy aggregator-dependent levels reflects certification grade and captive cold-chain investment. Pricing pressure stems from aggregator commission compression, which now absorbs 20-30% of digital order value. Institutional buyers in Saudi Arabia and UAE hotel corridors exhibit lowest price sensitivity due to procurement professionalization, while independent outlets in Kuwait and Bahrain face acute margin vulnerability.
Supply Chain Analysis
Freight cost escalation across Red Sea and Arabian Sea corridors is restructuring protein sourcing patterns for GCC commercial kitchens. Supply concentrates in Brazil, Australia, and India for beef and poultry imports, with domestic aquaculture in Saudi Arabia and UAE gaining subsidy-driven traction. Raw material dependencies include frozen protein blocks, temperature-controlled dairy, and specialized halal slaughter certification documentation. Single-source vulnerability runs through Jebel Ali and Dammam port concentration for cold-chain clearance. Distribution runs through integrated logistics providers with continuous temperature logging capability for cross-emirate compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC food service arbitrage opportunity concentrates in Kuwait and Bahrain, where municipal inspection fragmentation elevates compliance costs 25-40% above Saudi Arabia and UAE benchmarks for equivalent operational scale.
For Market Incumbents: Deploy backward integration into protein sourcing to offset import cost volatility from Red Sea freight disruptions. Alamar Foods-style captive supply chain control protects margin structures against aggregator commission compression. SFDA audit frequency acceleration threatens quality assurance staffing ratios for operators lacking automated compliance documentation systems. For New Entrants and Emerging Players: Cloud kitchen infrastructure offers the lowest-capital route into Riyadh and Jeddah food service without front-of-house real estate exposure. Kuwait City and Manama present underpenetrated procurement professionalization gaps versus Saudi Arabia and UAE saturation. Dark kitchen aggregation through shared industrial zone facilities enables multi-brand virtual portfolio economics. For Investors and Strategic Acquirers: Consolidation pressure builds where municipal inspection fragmentation multiplies compliance burdens across Doha, Manama, and Muscat for regional operators. Five-to-ten year viability favors vertically integrated protein controllers with halal certification captive capabilities. Watch SFDA subsidy redirection toward domestic aquaculture as inflection signal for import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Aggregator Channel Integration | Dark kitchen expansion bypasses real estate-heavy front-of-house investments in Dubai and Riyadh. |
| Backward Integration into Protein Sourcing | Captive supply chains insulate margins from Red Sea freight volatility and import concentration. |
| Cloud Kitchen Infrastructure Deployment | Shared industrial zone facilities fragment production geography while compressing capital requirements. |
| Halal Certification Automation Investment | SFDA audit timeline compression demands quality assurance staffing efficiency through documentation systems. |
| Domestic Aquaculture Subsidy Capture | Saudi Arabia and UAE fish farming incentives redirect protein procurement from external suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with food service procurement directors, commercial kitchen operations managers, cold-chain logistics providers, municipal health inspectors, and aggregator platform strategists with secondary validation. Customs and trade data, SFDA regulatory filings, hotel procurement contract disclosures, and GCC agricultural subsidy records anchored bottom-up volume estimates against top-down macroeconomic triangulation.
Segment-weighting across service type, customer cohort, distribution channel, and cuisine positioning drove analytical framework construction over the projection horizon. Modeled dimensions included fast-casual versus full-service format economics, institutional versus consumer demand patterns, dine-in versus digital channel mix, and Middle Eastern versus Western versus Asian cuisine supply chain complexity. CAGRs derived from elasticity-adjusted demand curves incorporating tourism arrival projections and protein import cost trajectories.
Regulatory enforcement acceleration, subsidy redirection toward domestic agriculture, and aggregator commission structure volatility are the dominant revision risks to forecast assumptions. A model refresh is warranted upon material change in SFDA halal certification protocol stringency or Red Sea logistics corridor stability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Shaker Bottles Market
Food Service
New Zealand Foodservice Market
Food Service
United States Quick Service Restaurants Market
Food Service
Commercial Tableware Services Market
Food Service
Wok Market
Food Service
Meal Kit Delivery Services Market
Food Service
Nigeria Food Service Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
North America Cafes & Bars Market
Food Service
Limited-Service Restaurants Market
Food Service
China Inflight Catering Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Global Online Food Ordering Market
Food Service
India Inflight Catering Market
Food Service
Asia-Pacific Online Grocery Delivery Market