
 Mexico Foodservice Market | 2026-2036
Mexico Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Foodservice Market Outlook
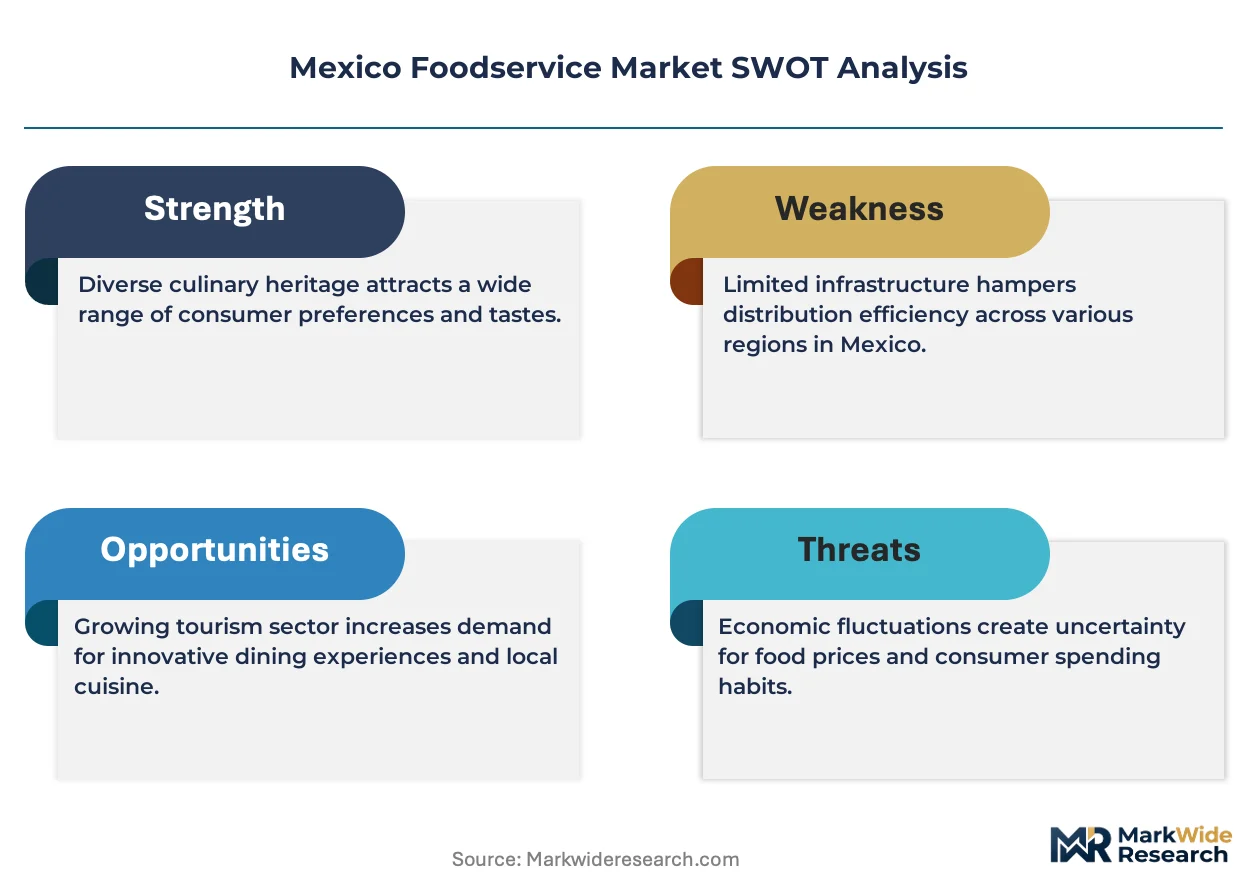
Consolidation among institutional and corporate catering buyers is realigning procurement patterns across Mexico's foodservice landscape. Alsea, S.A.B. de C.V. anchors its position through multi-brand portfolio management spanning quick-service and casual dining formats. Restaurant Brands International Inc. leverages its Tim Hortons and Burger King banners to compete in breakfast and all-day dining segments. Grupo Gigante sustains geographic dominance through its Vips and Toks banners, which occupy prime retail-adjacent locations in major metropolitan corridors.
Foodservice encompasses the commercial preparation, assembly, and delivery of ready-to-consume meals outside residential kitchens, operating through centralized supply chains with cold-chain integrity requirements and standardized portion controls designed for volume throughput. Fast food and casual dining formats lead the product type landscape, with delivery and takeaway service models capturing disproportionate growth as digital ordering platforms reshape consumer access patterns. Family and corporate customer segments concentrate margin pools, while Mexican cuisine anchors volume demand even as Asian and American formats expand in urban centers.
PROFECO enforces consumer protection standards that govern pricing transparency and service quality claims across Mexican foodservice establishments, while COFEPRIS regulates food safety protocols and nutritional labeling compliance that operators must integrate into menu engineering and supplier qualification processes. Stakeholders must monitor how evolving municipal zoning regulations and labor law adjustments in states like Nuevo León and Jalisco reshape unit economics and expansion feasibility across Mexico's regionally fragmented foodservice terrain.
Market Dynamics
Quick-service restaurant chains are deploying cloud-native point-of-sale systems across secondary Mexican cities, compressing order-to-kitchen latency and enabling real-time inventory synchronization with centralized distribution centers.
Growth Catalysts
- Urban Middle-Class Expansion:Households in Mexico City, Guadalajara, and Monterrey are diversifying dining occasions beyond traditional meal times, creating incremental daypart revenue pools for operators.
- PROFECO Transparency Mandates:Consumer protection standards governing pricing disclosure are accelerating digital menu board adoption and standardized portion documentation across franchise networks.
- Cold-Chain Infrastructure:Refrigerated logistics networks reaching secondary municipalities are enabling frozen protein and dairy distribution with integrity guarantees previously limited to major corridors.
Market Restraints
- Input Cost Volatility:Corn tortilla and cooking oil prices fluctuate with commodity futures traded on Chicago and domestic spot markets, squeezing margin predictability for masa-dependent formats.
- Labor Concentration Risk:Nuevo León and Jalisco wage pressure from manufacturing competition is elevating restaurant operator payroll costs above national averages.
- Substitution Threat:Meal kit delivery services and dark kitchen aggregators are capturing occasion-based demand previously served by casual dining establishments.
Strategic Opportunities
- Secondary City Penetration:Querétaro, Mérida, and León exhibit underpenetrated quick-service density relative to disposable income growth, offering first-mover positioning for multi-brand operators.
- COFEPRIS Nutrition Labeling:Front-of-package warning label requirements are creating competitive differentiation for operators reformulating menus ahead of compliance deadlines.
- Aggregator Convergence:Integration between native restaurant apps and third-party delivery platforms is modularizing fulfillment infrastructure, lowering capital barriers to omnichannel service.
Industry Challenges
- Kitchen Automation Talent Gap:Equipment programming and IoT maintenance skills are scarce in Mexican technical institutes, forcing operators into vendor-dependent service contracts.
- Municipal Zoning Friction:Local land-use boards in high-traffic districts impose extended approval timelines for drive-through modifications and outdoor seating expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Foodservice Market |
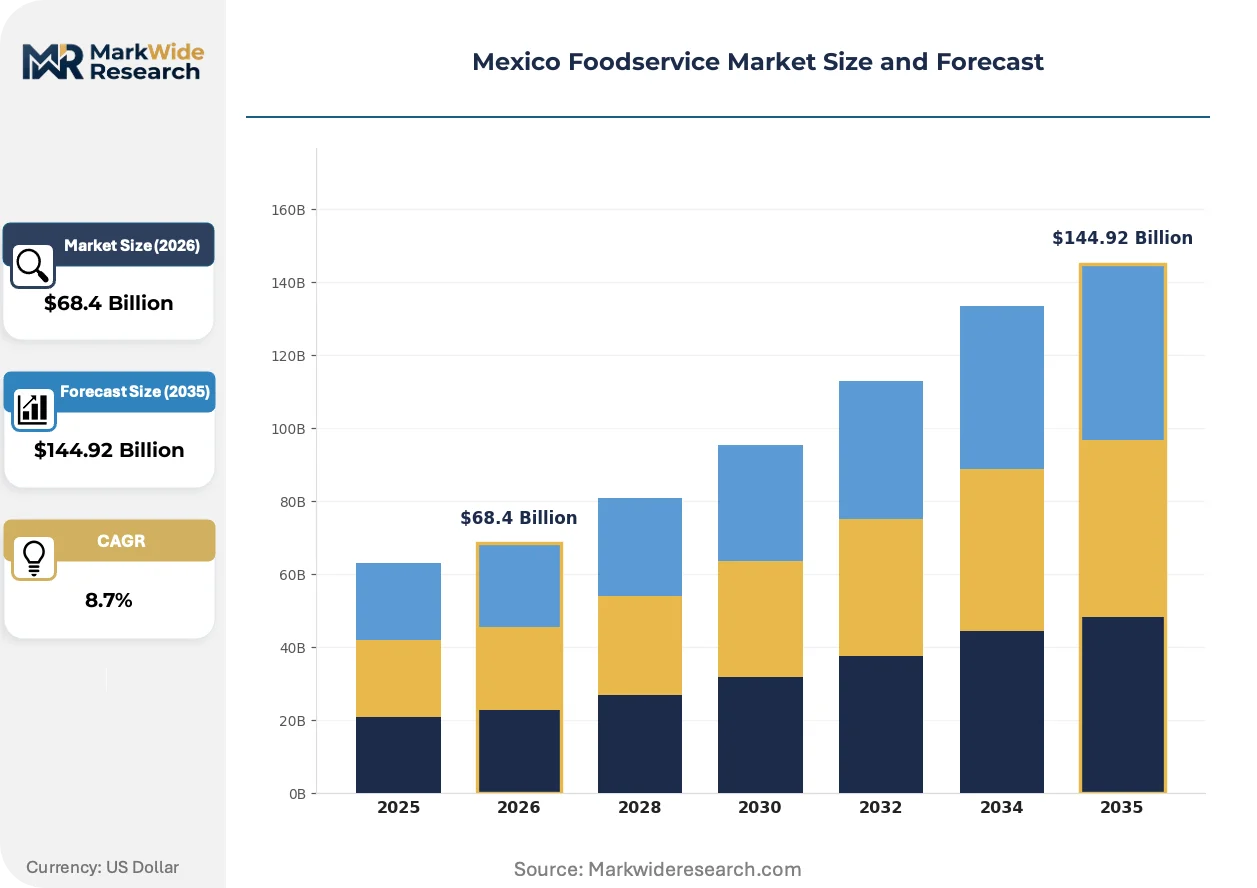
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Food, Casual Dining, Fine Dining, Food Trucks Customer Type: Families, Singles, Tourists, Corporates Service Model: Dine-in, Takeaway, Delivery, Catering Cuisine Type: Mexican, Italian, Asian, American |
| Companies Covered | Restaurant Brands International Inc., Grupo Gigante, Alsea, S.A.B. de C.V., Toks, Grupo Caliente, Yum! Brands Inc., Wendy's International, Inc., Vips, Arcos Dorados Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Foodservice Market Strategic Shifts
Digital ordering infrastructure is compressing the path between consumer intent and kitchen production, while regulatory transparency mandates and shifting meal occasions are restructuring how operators configure physical formats and labor deployment.
Kitchen display systems integrated with predictive analytics are modularizing back-of-house workflow sequencing. Mid-sized casual dining chains in Guadalajara and Monterrey are adopting these platforms fastest, replacing ticket-based coordination with screen-driven prep queues. This compression of kitchen communication latency is enabling smaller footprints without throughput sacrifice.
PROFECO's evolving pricing transparency standards are forcing menu engineering revisions across franchise systems. Operators must now display unit pricing with tax-inclusive totals, eliminating the practice of presenting pre-tax base prices. Quick-service formats with high transaction velocity face the steepest compliance recalibration, retraining counter staff and reprogramming register logic.
All-day breakfast and snacking occasions are displacing traditional lunch-dinner concentration in urban consumption patterns. Young professionals in Mexico City's central business district are purchasing single-item orders across extended hours, forcing operators to reconfigure labor schedules and ingredient holding protocols. Family-oriented suburban locations retain conventional peak structures, creating bifurcated operational templates within single-brand networks.
Mexico Foodservice Market Segmentation
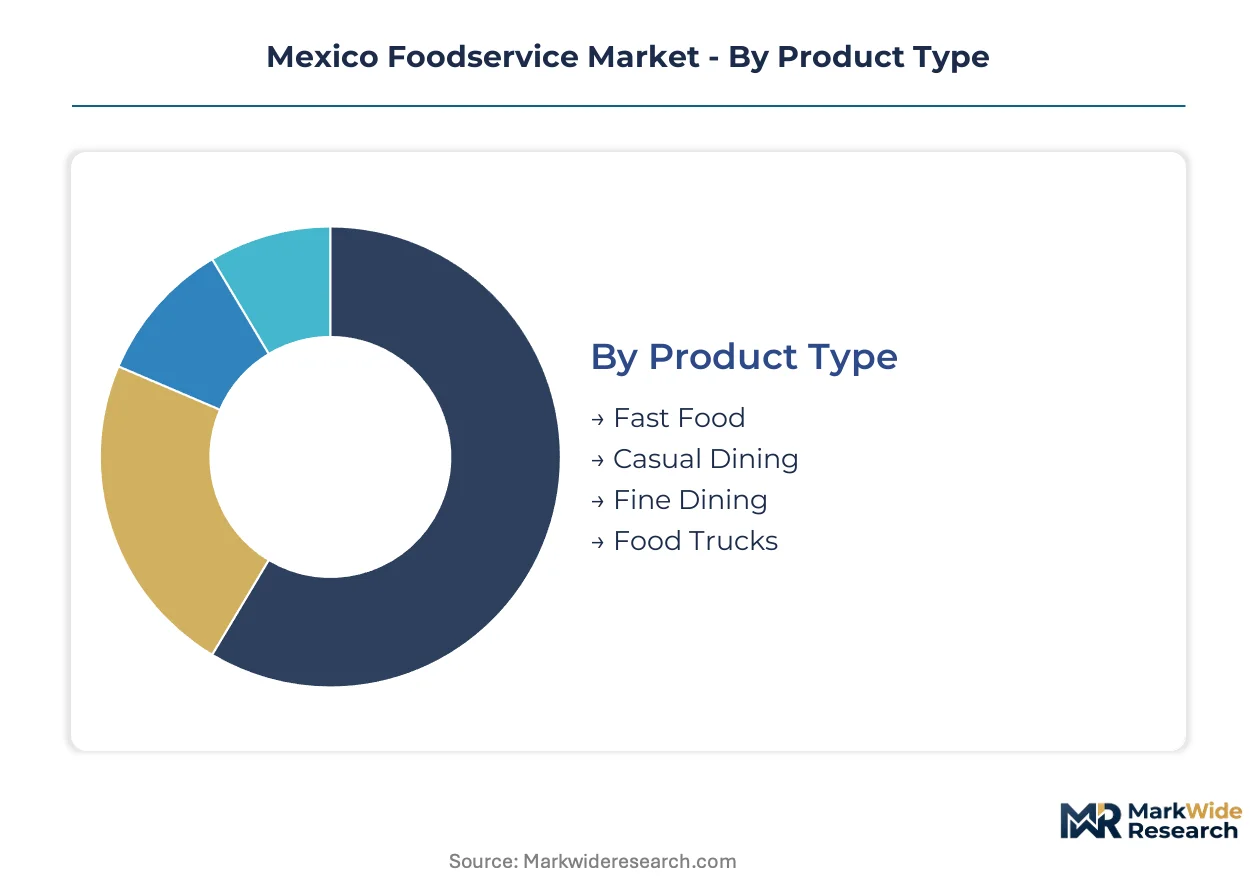
Segmentation reveals how distinct operational models and consumer occasions fragment revenue pools across Mexico's foodservice terrain. Format configuration, service velocity, and cuisine positioning determine margin architecture and capital requirements for operators.
Product Type:
Standalone formats operate with dedicated real estate and fixed cost bases, while embedded systems integrate into retail or transport hubs with variable throughput economics.
- Fast Food:High-velocity formats with standardized menu boards and drive-through infrastructure dominate transaction counts in Mexico City and Monterrey corridors. PROFECO's pricing transparency mandates are accelerating digital menu board adoption across franchise networks to display tax-inclusive totals.
- Casual Dining:Full-service establishments with moderate price points and extended dwell times concentrate in suburban shopping districts and entertainment clusters. Guadalajara's middle-class households sustain peak weekend occupancy rates that justify larger floorplates and specialized kitchen equipment.
- Fine Dining:Chef-driven concepts with premium ingredient sourcing and wine program investments occupy limited slots in Polanco and Roma Norte districts.
- Food Trucks:Mobile units with commissary kitchen dependencies exploit municipal event permits and high-footfall zones without fixed lease commitments.
Fast Food leads volumes today; Food Trucks are gaining share fastest.
Customer Type:
Cost tiers separate occasion-based spenders from routine purchasers, with frequency and average ticket diverging sharply across household structures.
- Families:Multi-cover parties with children's menu requirements and weekend occasion concentration drive volume in suburban casual dining locations. Nuevo León operators report Saturday lunch peaks that exceed weekday dinner averages by significant multiples.
- Singles:Solo diners with snacking and convenience-driven purchase patterns favor quick-service counters and delivery aggregators in dense urban districts.
- Tourists:Seasonal demand concentrated in Cancún, Los Cabos, and Centro Histórico corridors exhibits high price elasticity and cuisine experimentation.
- Corporates:Contracted catering and business entertainment accounts with negotiated pricing and invoice-based settlement concentrate procurement decisions among institutional buyers.
Families anchor revenue stability; Singles are expanding most quickly.
Service Model:
Application context determines labor deployment and real estate configuration, with off-premise formats compressing front-of-house requirements.
- Dine-in:Traditional table service with fixed seating capacity and full front-of-house staffing remains margin-diluted in high-rent districts but defensible in experience-positioned concepts.
- Takeaway:Counter-based pickup with dedicated packaging stations and queue management systems captures commuter demand in transit-adjacent locations.
- Delivery:Third-party aggregator and native app fulfillment with ghost kitchen infrastructure is displacing casual dining occasions among young professionals in Mexico City's central business district.
- Catering:Large-format production with advance-order scheduling and transport logistics serves corporate events and institutional clients with volume-based pricing.
Dine-in retains the largest revenue base; Delivery is climbing the fastest.
Cuisine Type:
Geographic origin shapes supply chain requirements and labor skill profiles, with authenticity claims demanding specialized ingredient sourcing.
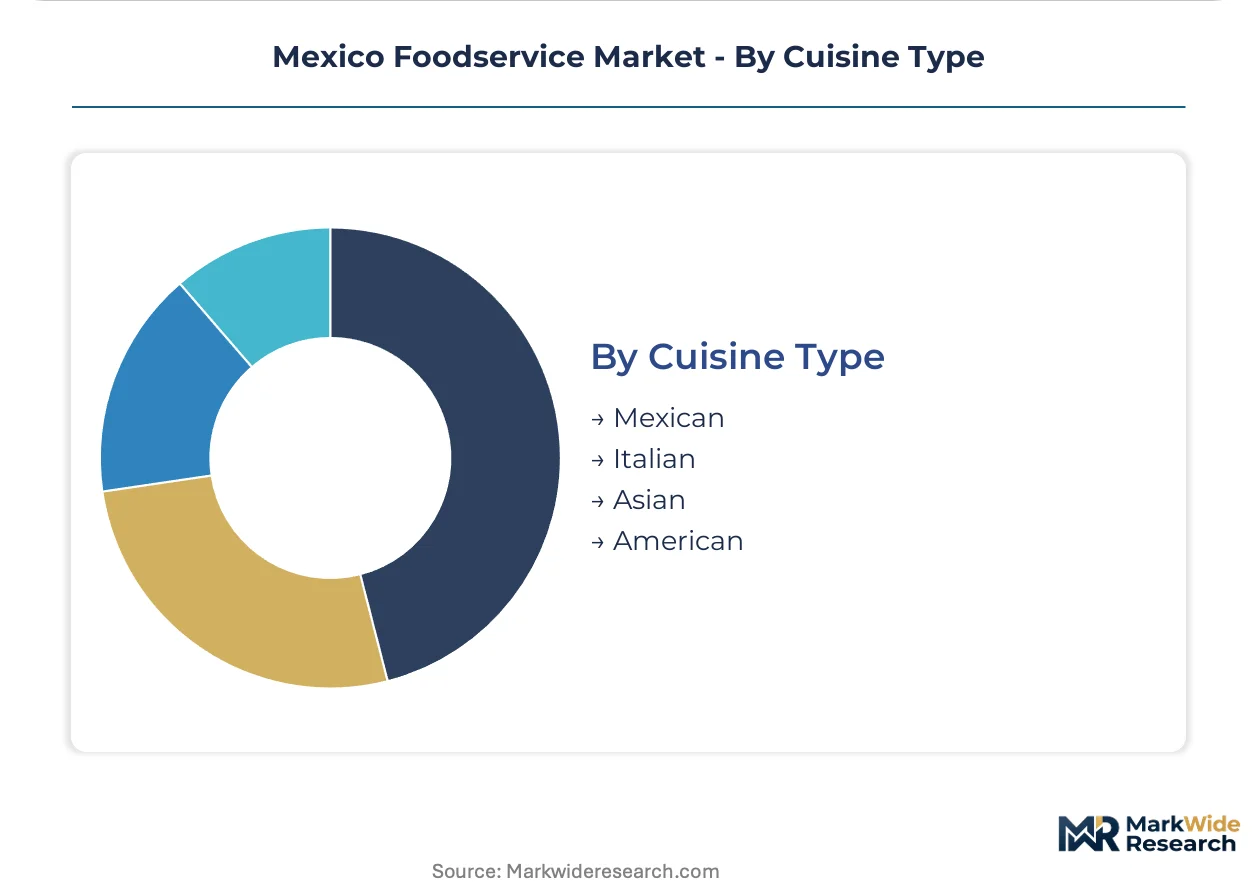
- Mexican:Tortilla production, mole preparation, and regional specialty formats anchor volume demand with domestic supply chain advantages and cultural preference durability across all income tiers.
- Italian:Pizza and pasta concepts with imported cheese and equipment dependencies concentrate in metropolitan corridors with international exposure and premium positioning tolerance.
- Asian:Sushi, ramen, and stir-fry formats with specialized ventilation and skilled wok or knife-work requirements expand in affluent districts of Mexico City and Monterrey.
- American:Burger and barbecue formats with standardized protein sourcing and fryer-centric kitchens replicate efficiently through franchise systems in secondary cities.
Mexican cuisine dominates transaction volumes; Asian formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Secondary Mexican cities exhibit faster quick-service penetration rates than saturated primary metros, while regulatory enforcement intensity varies sharply across state jurisdictions. PROFECO's federal mandates create baseline compliance floors, but municipal implementation timelines diverge significantly.
Mexico City Metro
Urban middle-class households are diversifying dining occasions across extended dayparts, creating incremental revenue pools for operators. PROFECO's pricing transparency mandates accelerate digital menu board adoption across franchise networks. The central business district sees delivery aggregators displacing casual dining occasions among young professionals.
Nuevo León
Manufacturing sector wage competition elevates restaurant operator payroll costs above national averages, squeezing unit economics. State-level labor law adjustments reshape expansion feasibility for multi-brand operators. Monterrey's suburban shopping districts sustain peak weekend occupancy rates that justify larger casual dining floorplates.
Jalisco
Guadalajara's middle-class households concentrate margin pools in family-oriented formats with children's menu requirements. Municipal zoning regulations impose extended approval timelines for drive-through modifications in high-traffic districts. The metropolitan corridor anchors volume demand for Mexican cuisine with domestic supply chain advantages.
Bajío Region
Querétaro and León exhibit underpenetrated quick-service density relative to disposable income growth. Cold-chain infrastructure expansion enables frozen protein distribution with integrity guarantees previously limited to major corridors. First-mover positioning opportunities exist for multi-brand operators seeking geographic diversification.
Yucatán Peninsula
Tourist demand concentrated in Cancún and Mérida exhibits high price elasticity and cuisine experimentation. Seasonal demand patterns create operational complexity for operators managing year-round fixed costs. Mérida's underpenetrated quick-service landscape offers expansion potential as disposable income growth outpaces national averages.
Mexico Foodservice Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Mexico's foodservice terrain, creating a tiered structure where scale advantages clash with agility benefits. The vendor base clusters around multi-brand portfolio managers, single-format specialists, and regional franchise aggregators. Strategic archetypes include centralized procurement platforms, format-specific operators, and retail-adjacent location specialists. Dominant competitive moves encompass portfolio diversification through banner acquisition and geographic expansion into secondary municipalities.
Within the multi-brand portfolio tier, Alsea, S.A.B. de C.V. and Restaurant Brands International Inc. occupy positions exemplifying centralized procurement and format diversification strategies. Grupo Gigante anchors the retail-adjacent location archetype through its Vips and Toks banners. These three entities represent distinct competitive positioning approaches: Alsea exemplifies multi-brand management spanning quick-service and casual dining, Restaurant Brands International leverages breakfast and all-day dining segment competition, and Grupo Gigante sustains geographic dominance through prime retail corridor positioning.
| Leading Market Players |
|---|
| Restaurant Brands International Inc. |
| Grupo Gigante |
| Alsea, S.A.B. de C.V. |
| Toks |
| Grupo Caliente |
| Yum! Brands Inc. |
| Wendy's International, Inc. |
| Vips |
| Arcos Dorados Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Multi-brand franchise operators concentrate procurement decisions across Mexico's foodservice landscape, anchoring contract-based pricing structures that tie menu costs to commodity futures and cold-chain logistics tariffs. This buyer-architecture compresses margin buffers for independent operators while rewarding scale players with volume-based protein and dairy sourcing terms.
Pricing Analysis
Capacity additions in Querétaro and León are reshaping price floors for quick-service formats entering secondary municipalities. Three-tier pricing structure across premium, standard, and economy levels separates chef-driven concepts in Polanco from suburban family formats and value-positioned drive-throughs. Pricing pressure stems from wage competition with Nuevo León manufacturing, elevating payroll costs above national benchmarks. Economy-tier operators exhibit highest price sensitivity, while fine dining concepts in Mexico City's Roma Norte district maintain inelastic demand.
Supply Chain Analysis
Regional distribution centers in Guadalajara and Monterrey anchor hub-and-spoke patterns that extend refrigerated logistics into Mérida and Cancún corridors. Mexico's domestic tortilla production and U.S. protein imports form the backbone of ingredient sourcing, with Asian specialty formats drawing from South Korean and Japanese supply channels. Single-source vulnerability concentrates in imported cheese and equipment dependencies for Italian and Asian cuisine concepts. Distribution runs through Alsea and Grupo Gigante's centralized procurement platforms, with last-mile aggregator partnerships modularizing fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's foodservice market represents a late-cycle quality story as urban middle-class households shift occasion-based spending toward experience-positioned formats with transparent sourcing claims and COFEPRIS-compliant nutrition profiles.
For Market Incumbents: Acquire commissary kitchen infrastructure in underpenetrated Bajío corridors to preempt dark kitchen aggregators capturing delivery occasions. Consolidate supplier relationships around PROFECO-compliant transparency documentation, while embedding IoT-enabled inventory systems to compress cold-chain waste. Labor concentration risk in Nuevo León demands automation investment in back-of-house workflow sequencing.
For New Entrants and Emerging Players: The mid-market price-point gap between Toks family formats and premium chef-driven concepts offers white-space positioning for fast-casual Mexican cuisine with regional specialty menus. Target Mérida's underpenetrated quick-service density where disposable income growth outpaces national averages. Launch through native app-aggregator hybrid models that minimize front-of-house capital requirements.
For Investors and Strategic Acquirers: Diversified conglomerates with retail-adjacent real estate portfolios are the most active acquirers in this space, seeking banner additions that leverage existing location networks. Five-to-ten-year viability hinges on regulatory compliance infrastructure and secondary-city distribution reach. Watch COFEPRIS enforcement intensity across Jalisco and Nuevo León as an inflection indicator for margin compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary City Expansion | Querétaro and León offer first-mover positioning ahead of cold-chain saturation. |
| Menu Reformulation Program | COFEPRIS front-of-package compliance creates differentiation against laggard competitors. |
| Aggregator Platform Integration | Native app partnerships with Rappi and Uber Eats lower omnichannel capital barriers. |
| Kitchen Automation Deployment | Predictive analytics platforms compress labor schedules in Guadalajara and Monterrey. |
| Commissary Network Buildout | Centralized production supports food truck and ghost kitchen formats in Cancún corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with multi-brand portfolio executives, municipal zoning officers in Jalisco and Nuevo León, cold-chain logistics operators, and PROFECO compliance specialists with secondary validation. SEC filings from Alsea and Restaurant Brands International, COFEPRIS regulatory bulletins, customs trade data on protein imports, and municipal permit databases anchored the data foundation. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical quick-service penetration patterns across Mexico City, Guadalajara, and Monterrey metro corridors. The analytical framework segmented by format type, service model, cuisine origin, and customer occasion across the modeling period, with CAGRs derived from disposable income elasticity coefficients and daypart diversification trends. Forecast inputs incorporated cold-chain infrastructure buildout timelines and municipal zoning approval velocity in high-traffic districts.
Caveats apply where PROFECO pricing transparency enforcement intensity or commodity futures volatility in corn and cooking oil markets could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Breakfast Takeout Market
Food Service
Singapore Food Service Market
Food Service
Asia-Pacific and Middle-East Inflight Catering Market
Food Service
United States Foodservice Market
Food Service
United States Food Truck Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Global Digital Grocery Market
Food Service
Shaker Bottles Market
Food Service
Global Online Food Delivery Services Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Commercial Sink Market
Food Service
Brazil Foodservice Market
Food Service
Food Service Dairy Products Market
Food Service
Food Service Market
Food Service
Germany Foodservice Market
Food Service
Portable Buffet and Drop-In Ranges Market