
 New Zealand Bathroom Products Market | 2026-2036
New Zealand Bathroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Bathroom Products Market Insights
Licensed plumber availability across New Zealand is redrawing installation capacity and project timelines. Reece leverages its branch network to control distribution reach into regional centers. GWA Group Limited anchors local manufacturing of vitreous china sanitaryware. Kohler Co. competes through imported premium lines targeting Auckland and Wellington renovation segments.
New Zealand bathroom products encompass sanitary fixtures, tapware, bathing enclosures, and allied accessories engineered for water delivery, waste removal, and hygiene maintenance in residential and non-residential buildings. Ceramic vitrification at temperatures exceeding 1,200°C produces non-porous surfaces meeting sanitation durability standards. Showers and faucets capture margin concentration as consumers prioritize water-efficient retrofit solutions. Ceramic dominates material value due to established local production and builder specification familiarity. Hospitality end-user demand is accelerating fastest, driven by Auckland and Queenstown accommodation upgrades.
New Zealand's Building Code clause G12/AS1 mandates maximum flow rates for sanitary fixtures, enforced by local territorial authorities during consent approval. WaterMark certification administered by the country's plumbing regulator governs product legality for installation. The Commerce Commission monitors supplier conduct under fair trading provisions. Stakeholders must track consent processing delays and WaterMark scope expansion as determinants of product launch viability.
Market Dynamics
Water efficiency mandates under New Zealand's Building Code clause G12/AS1 are compressing fixture specifications toward low-flow models, while Auckland's construction concentration strains licensed plumber availability and reshapes installation capacity across the North Island.
Growth Catalysts
- Building Code amendments:Tighter water consumption thresholds under G12/AS1 are mandating maximum flow rates for sanitary fixtures, forcing specification upgrades across new residential builds.
- Hospitality accommodation upgrades:Auckland and Queenstown hotel renovation cycles are accelerating demand for premium bathing enclosures and designer tapware.
- Ceramic vitrification advances:Local production of vitreous china at temperatures exceeding 1,200°C yields non-porous surfaces that meet sanitation durability standards for commercial installations.
Market Restraints
- Licensed plumber scarcity:Territorial authority consent processing delays and qualified installer shortages are extending project timelines and capping installation throughput.
- WaterMark certification friction:Scope expansion by the country's plumbing regulator adds compliance layers that slow product launch viability for imported lines.
- Import dependency for premium segments:High-end fixture specifications rely on overseas supply chains, exposing distributors to freight cost volatility and currency fluctuation.
Strategic Opportunities
- Regional center distribution gaps:Branch network expansion into secondary North Island cities captures underserved renovation demand outside Auckland and Wellington.
- Water-efficient retrofit acceleration:Consumer prioritization of shower and faucet upgrades for conservation compliance opens replacement cycle compression.
- Smart fixture convergence:Integration of sensor-activated tapware with building management systems creates specification pull from commercial developers.
Industry Challenges
- WaterMark compliance timeline compression:Certification scope expansion requires manufacturers to recertify existing product lines, draining technical resources.
- Legacy plumbing infrastructure mismatch:Low-flow fixture installation in older Wellington and Christchurch housing stock demands costly pipework modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Bathroom Products Market |
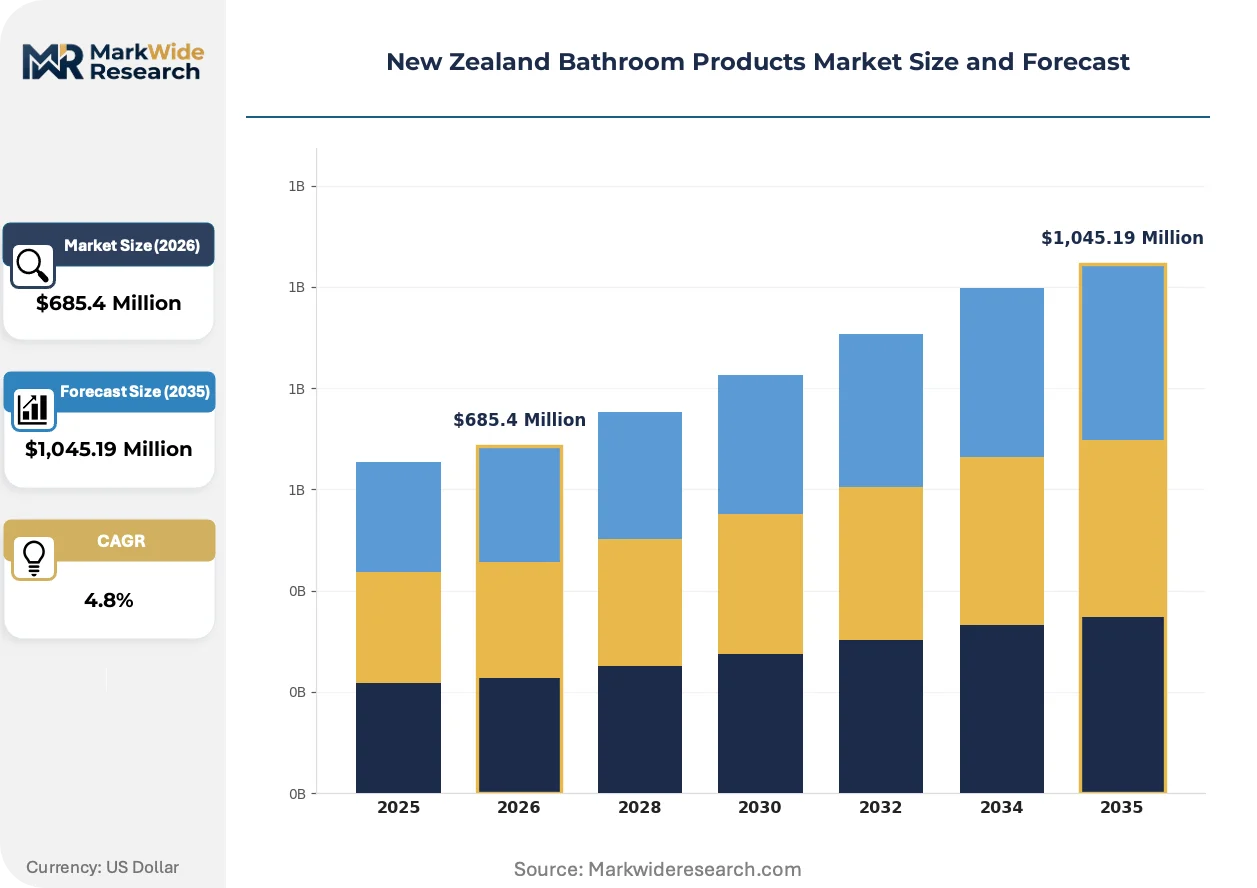
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bathtubs, Showers, Faucets, Toilets Material: Ceramic, Acrylic, Glass, Stainless Steel End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online Retail, Home Improvement Stores, Specialty Shops, Distributors |
| Companies Covered | Atherna Bathrooms, Felton Industries Ltd, Foreno Tapware, GWA Group Limited, Heirloom International Ltd., Kohler Co., NZ Glass, Robertson Bathware, Reece, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Bathroom Products Market Trends and Innovations
Digital specification tools and sensor-activated water delivery systems are compressing traditional procurement cycles and redefining hygiene maintenance standards across New Zealand's residential and commercial build environments.
Thermostatic mixing valve technology is miniaturizing. These precision temperature control devices prevent scalding in multi-residential and aged-care facilities. Auckland developers are specifying compact integrated units at accelerating rates. The technology is miniaturizing mechanical components into single-cartridge designs that reduce wall cavity depth requirements and enable slimmer shower enclosure profiles.
New Zealand's Building Code clause G12/AS1 mandates maximum flow rates for sanitary fixtures, enforced by territorial authorities during consent approval. The regulation compresses allowable water consumption thresholds for showers, taps, and toilets. Residential builders are responding by pre-specifying WaterMark-certified low-flow models to avoid consent rejection.
Builder procurement patterns are fragmenting across digital channels. Traditional merchant branch relationships face displacement from online specification platforms that aggregate product data and certification documentation. Auckland residential developers are piloting direct-to-site fulfillment models that bypass conventional distribution tiers.
New Zealand Bathroom Products Market Segmentation
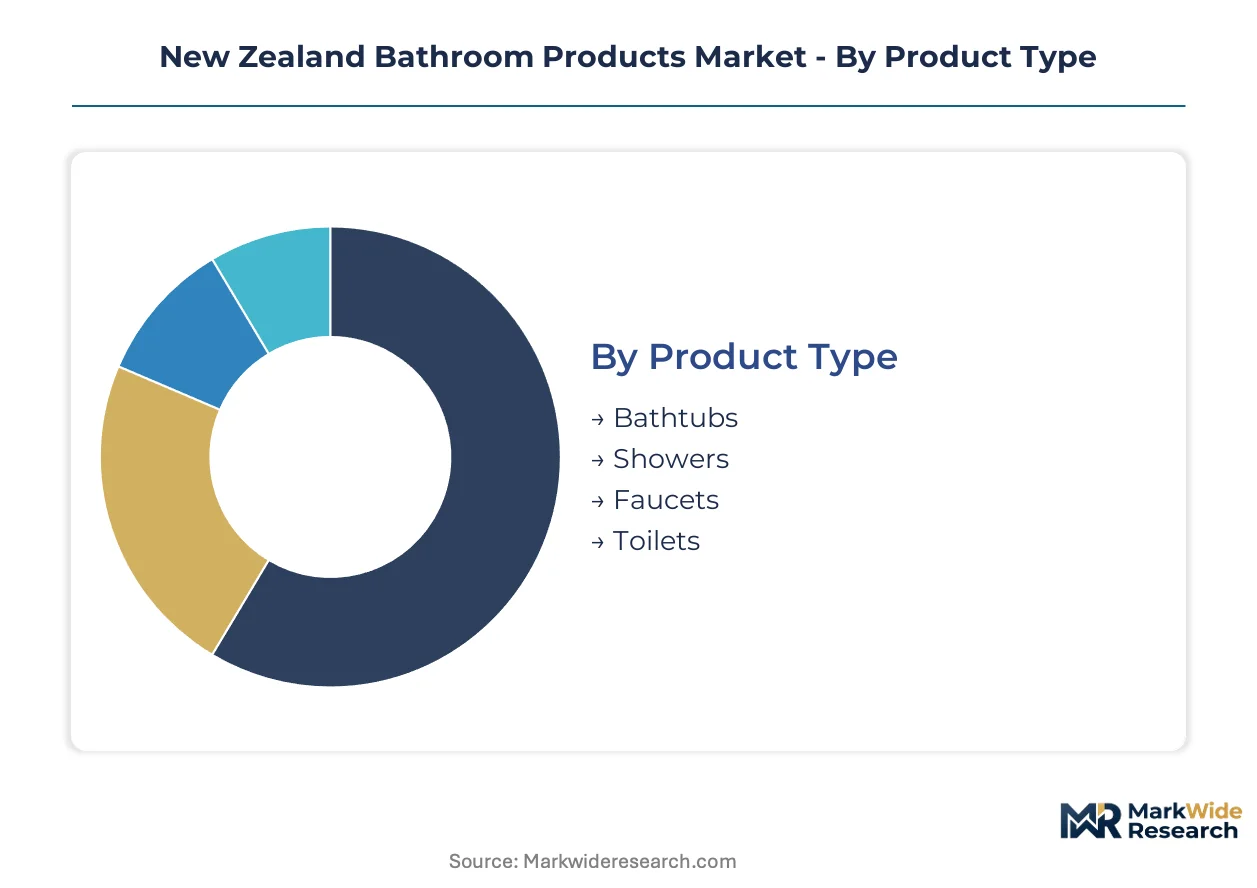
Product specifications across New Zealand bathroom fixtures fragment along water efficiency grades, material durability requirements, and installation complexity tiers. Builder procurement patterns concentrate margin capture in segments that align with Building Code G12/AS1 compliance and territorial authority consent pathways.
Product Type:
Margin pools concentrate in water delivery fixtures where efficiency certification commands specification premiums and replacement cycles compress.
- Showers:Enclosure systems integrate thermostatic mixing valves and low-flow restrictors to meet G12/AS1 maximum flow mandates. Auckland residential developers pre-specify WaterMark-certified units to accelerate consent approval timelines and avoid territorial authority rejection.
- Faucets:Tapware dominates retrofit demand as consumers prioritize visible water-efficient upgrades with immediate utility bill impact. Sensor-activated models gain traction in Queenstown hospitality renovations where hygiene maintenance standards are tightening.
- Toilets:Vitreous china sanitaryware anchors local manufacturing through GWA Group Limited's domestic kilns firing above 1,200°C.
- Bathtubs:Freestanding acrylic and cast-iron units serve premium renovation segments in Wellington heritage housing stock.
The dominant share belongs to showers, while faucets are closing the gap fastest through accelerated replacement demand.
Material:
Cost tier stratification separates specification-grade ceramics from economy acrylic alternatives in builder tender documents.
- Ceramic:Vitrified surfaces fired at extreme temperatures yield non-porous sanitation durability that satisfies commercial installation standards. Local production capacity at GWA Group Limited's facilities insulates this segment from freight volatility affecting imported alternatives.
- Acrylic:Lightweight polymer formulations reduce structural load requirements in multi-residential construction. Christchurch rebuild activity favors acrylic bathing enclosures for rapid installation timelines where plumber scarcity extends project schedules.
- Glass:Tempered safety glazing dominates frameless shower enclosure specifications across Auckland premium residential towers.
- Stainless Steel:Corrosion-resistant tapware bodies serve coastal North Island markets with elevated salinity exposure.
Ceramic retains the largest specification volume, though acrylic is expanding most quickly through cost-sensitive multi-residential penetration.
End User:
Application context dictates compliance intensity, with commercial installations facing stricter WaterMark enforcement than residential owner-occupier projects.
- Residential:Owner-occupied housing drives replacement cycle demand as aging Wellington and Christchurch stock requires fixture upgrades to meet modern efficiency thresholds. Renovation spending concentrates in Auckland's established suburbs where land values justify premium bathroom investments.
- Hospitality:Hotel renovation cycles in Auckland and Queenstown accelerate specification of designer tapware and premium bathing enclosures. International visitor volume recovery post-pandemic triggers accommodation upgrade investments with compressed procurement timelines.
- Commercial:Office and retail fit-outs prioritize sensor-activated fixtures for water conservation compliance and reduced maintenance labor.
- Healthcare:Aged-care facilities specify thermostatic mixing valves to prevent scalding in vulnerable occupant environments.
Residential commands the dominant revenue position, yet hospitality is gaining share fastest through concentrated geographic upgrade activity.
Distribution Channel:
Customer type fragmentation separates trade-focused merchant relationships from direct consumer procurement through digital platforms.
- Home Improvement Stores:Branch networks controlled by Reece anchor trade access to WaterMark-certified inventory across North Island population centers. Licensed plumber purchasing patterns concentrate here due to immediate availability and account credit terms.
- Online Retail:Digital specification platforms aggregate certification documentation and enable direct-to-site fulfillment models. Auckland residential developers pilot bypassing conventional distribution tiers to compress procurement cycles.
- Distributors:Regional wholesalers serve secondary cities outside Auckland and Wellington where branch network density thins.
- Specialty Shops:Boutique showrooms target renovation segments seeking imported premium lines from Kohler Co. and comparable international suppliers.
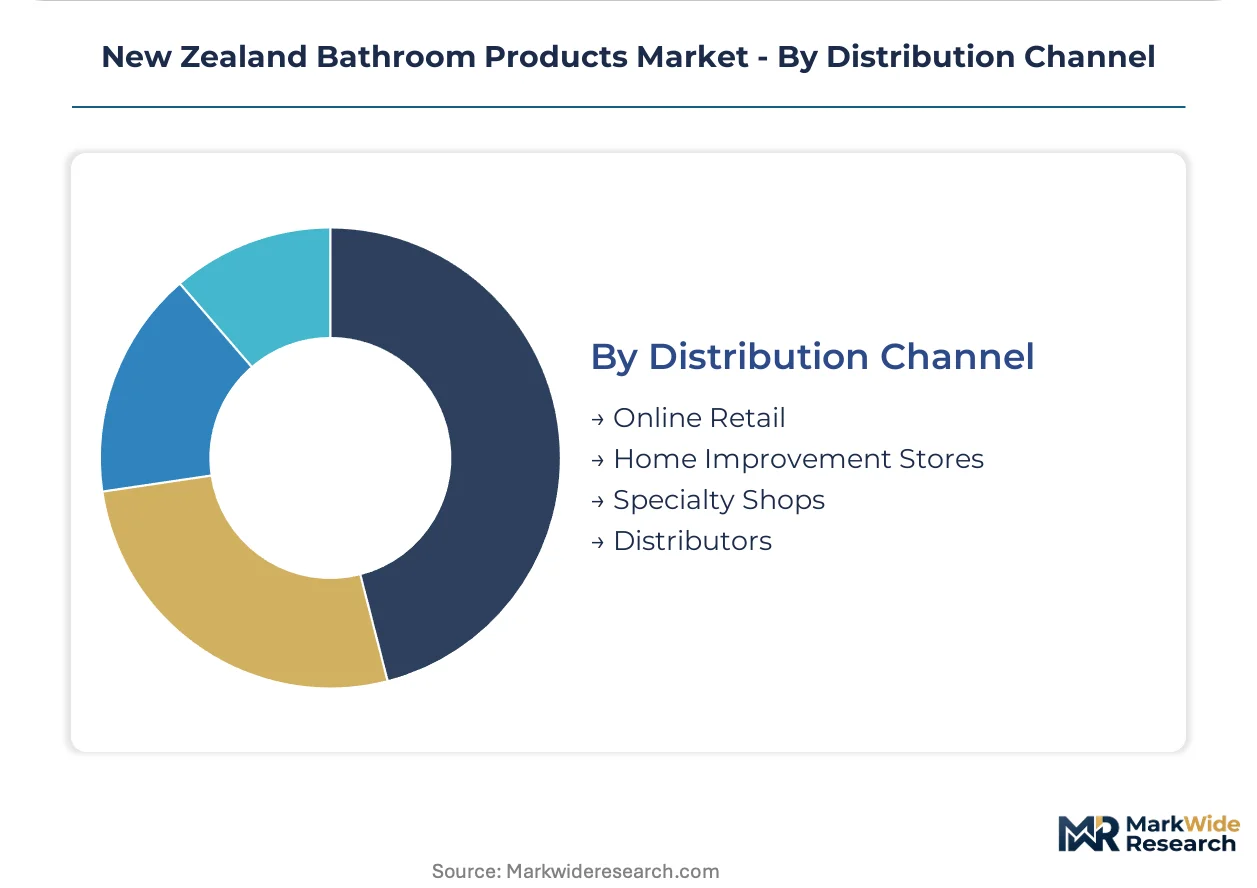
Home improvement stores hold the largest trade volume, while online retail is climbing the fastest through builder procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland commands specification premiums that secondary North Island cities cannot match, while Wellington's heritage housing stock demands specialized retrofit solutions unavailable in Christchurch's rebuild-focused market.
Auckland
Residential tower construction and hospitality renovation cycles concentrate demand for premium bathing enclosures and designer tapware. Building Code clause G12/AS1 enforcement by Auckland Council accelerates WaterMark-certified fixture specifications. The central business district and fringe suburbs anchor procurement volume for imported premium lines.
Wellington
Heritage housing stock built before 1940 requires costly pipework modifications to accommodate low-flow fixtures. Territorial authority consent processing delays extend project timelines for renovation contractors. The inner-city and hillside suburbs concentrate specification activity for thermostatic mixing valves in aged-care conversions.
Christchurch
Post-earthquake rebuild activity favors rapid-installation acrylic bathing enclosures over ceramic alternatives. Plumber scarcity compresses project schedules and redirects demand toward simplified installation systems. The central city and eastern suburbs concentrate multi-residential construction with standardized fixture specifications.
Queenstown
International visitor volume recovery triggers accelerated hotel renovation cycles with compressed procurement timelines. Hygiene maintenance standards in hospitality applications drive sensor-activated tapware specifications. The town center and Frankton corridor anchor accommodation upgrade investments.
Hamilton
Regional population growth expands residential construction beyond Auckland's orbit, creating distribution gaps for WaterMark-certified inventory. Branch network thinning elevates procurement costs for licensed plumbers. The central city and northern growth corridors concentrate new build activity with mid-tier fixture specifications.
New Zealand Bathroom Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium design houses competing against scale-driven distributors for specification control. The market structures around three tiers: national distributors with branch network density, local manufacturers with vitreous china firing capabilities, and import-focused specialists serving renovation segments. Dominant competitive moves include branch network expansion into regional centers and digital procurement platform deployment to compress traditional merchant relationships.
Among Australia-based parent companies with New Zealand operations, GWA Group Limited and Reece occupy positions that exemplify the manufacturing-versus-distribution archetype split. Kohler Co. represents the import-specialist tier targeting premium renovation demand in Auckland and Wellington.
| Leading Market Players |
|---|
| Atherna Bathrooms |
| Felton Industries Ltd |
| Foreno Tapware |
| GWA Group Limited |
| Heirloom International Ltd. |
| Kohler Co. |
| NZ Glass |
| Robertson Bathware |
| Reece |
| Others |
Pricing and Supply Chain Analysis
Project-based contracting with territorial authority consent timelines locks in both WaterMark-certified supply access and fixture price visibility for residential developers across Auckland and Wellington. This structure ties procurement cycles to building code enforcement rhythms, compressing margin negotiation windows when plumber scarcity accelerates installation scheduling.
Pricing Analysis
The customization-premium spread between configured-to-order vitreous china and standard acrylic enclosures runs wide across New Zealand's renovation segments. Three-tier pricing structure across premium, standard, and economy levels separates WaterMark-certified imports from locally fired ceramics and basic merchant-grade alternatives. Cost compression in mid-tier acrylic bathing enclosures is intensifying because Christchurch rebuild activity favors rapid-installation systems over specification-grade ceramics. Owner-occupier renovators in Wellington heritage zones show lowest price sensitivity, while multi-residential developers in Hamilton prioritize economy-grade fixtures to offset distribution cost premiums from branch network thinning.
Supply Chain Analysis
China and Australia anchor vitreous china and ceramic raw material supply for New Zealand's bathroom products market. Local manufacturing draws from Australian-sourced clay formulations and Chinese-engineered kiln components, with finished goods distribution resting on Reece's North Island branch density. Single-source vulnerability concentrates in thermostatic mixing valve cartridges imported from European precision manufacturers. Distribution runs through merchant branch networks for trade access, with direct-to-site fulfillment piloting in Auckland residential towers to compress procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand's bathroom products market sits at a high-growth inflection as Building Code clause G12/AS1 amendments force specification upgrades toward low-flow fixtures, compressing replacement cycles and opening margin pools for certified suppliers.
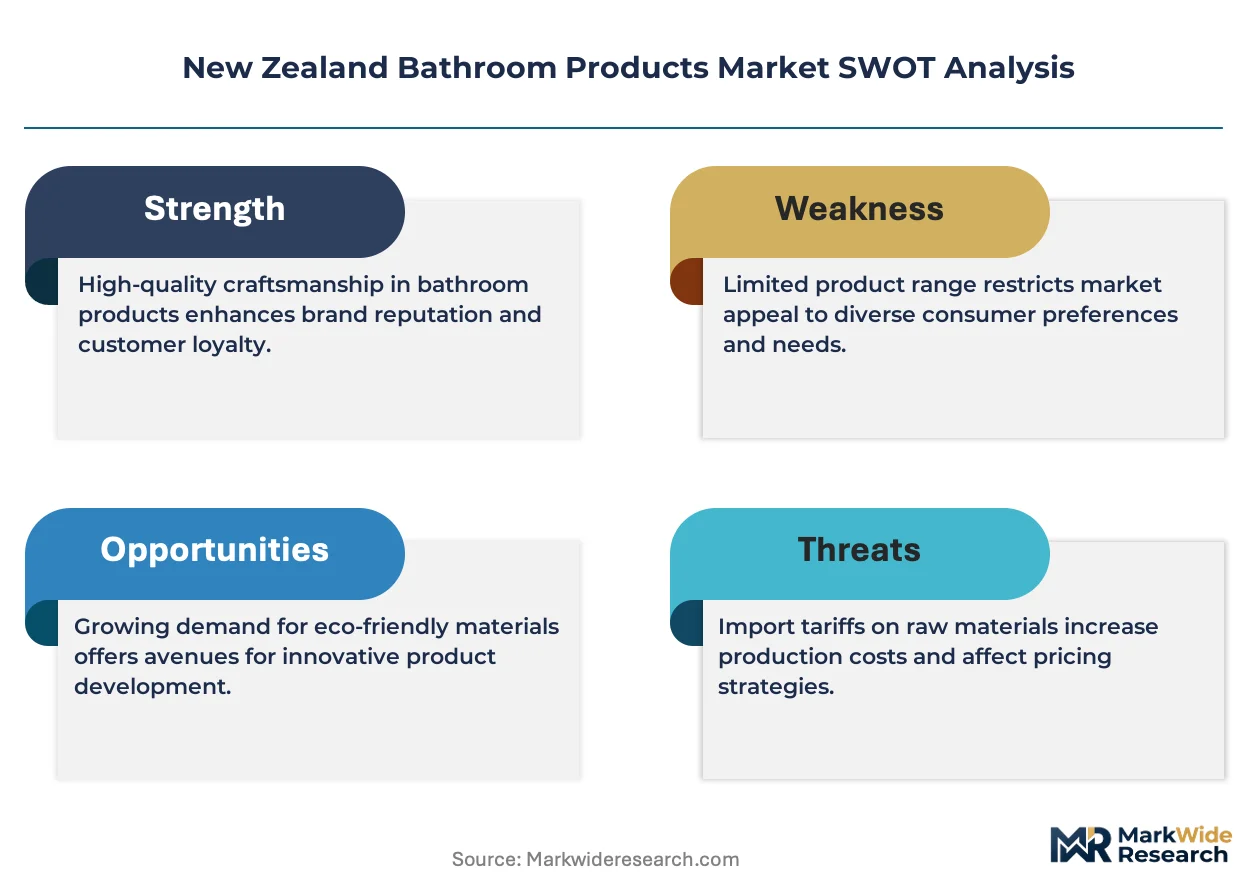
For Market Incumbents: Compound branch network control in regional North Island centers where licensed plumber purchasing patterns concentrate, while accelerating WaterMark recertification investments to preempt regulatory scope expansion. Threat from digital procurement platforms displacing traditional merchant relationships demands defensive platform deployment. Vertical integration into thermostatic mixing valve sourcing reduces European cartridge dependency. For New Entrants and Emerging Players: WaterMark certification fast-track through third-party testing partnerships opens specification access in Queenstown hospitality renovations where compressed procurement timelines favor agile suppliers. Underpenetrated Hamilton distribution gaps offer white-space capture as population growth outpaces branch network expansion. Target sensor-activated tapware for commercial office fit-outs where hygiene maintenance standards tighten fastest. For Investors and Strategic Acquirers: Regional distributors with territorial authority relationship depth represent acquisition targets with durable competitive moats. Long-term viability hinges on regulatory compliance infrastructure rather than pure scale, positioning certified inventory specialists for sustained margin capture. Monitor consent processing velocity at Auckland Council as inflection indicator for specification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| WaterMark Certification Acceleration | Preemptive recertification under G12/AS1 scope expansion secures product launch viability ahead of territorial authority enforcement tightening. |
| Regional Branch Network Expansion | Hamilton and secondary North Island city presence captures underserved renovation demand outside Auckland-Wellington corridor concentration. |
| Digital Procurement Platform Deployment | Direct-to-site fulfillment pilots bypass conventional distribution tiers and compress procurement cycles for Auckland residential developers. |
| Sensor-Activated Tapware Integration | Building management system convergence creates specification pull from commercial developers prioritizing hygiene maintenance automation. |
| Backward Integration into Ceramic Supply | GWA Group Limited's domestic kiln capacity insulates against freight volatility affecting imported vitreous china alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from licensed plumbers, residential developers, territorial authority consent officers, and hospitality procurement managers and refined through secondary validation. Licensed plumbers provided installation capacity and fixture specification preferences. Residential developers detailed procurement cycle compression and digital platform piloting. Territorial authority consent officers clarified G12/AS1 enforcement variability. Secondary sources included Building Code compliance databases, WaterMark certification registers, territorial authority consent processing records, and trade publication procurement trend analysis. Bottom-up segment sizing triangulated against top-down construction pipeline value estimates.
Variance-decomposition framing separated volume growth from mix-shift effects across product type, material grade, end-user application, and distribution channel dimensions. Modeling spanned the analysis window with CAGRs derived from construction consent flow projections and replacement cycle compression assumptions. Industry-specific inputs incorporated WaterMark certification timeline data, plumber licensing registry trends, and hospitality accommodation upgrade pipeline tracking.
Decision-makers should treat outputs as directional under stable Building Code amendment schedules and consistent territorial authority enforcement; material deviation in consent processing velocity or regulatory scope expansion would warrant model refresh. Recalibration cycles align with material shifts in G12/AS1 interpretation, WaterMark scope decisions, and Auckland construction pipeline revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market