
 Asia Pacific Bath Fitting Market | 2026-2036
Asia Pacific Bath Fitting Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Bath Fitting Market Outlook
Luxury hospitality developers are redrawing procurement priorities across the Asia Pacific bath fitting landscape, shifting specification authority from cost-driven contractors to design-led asset managers. Jaquar leverages its Indian manufacturing scale to dominate mid-premium hospitality projects across the subcontinent. TOTO sustains technology leadership in sensor-integrated fixtures for Japan's aging-accessibility retrofit wave. Kohler anchors premium positioning through controlled distribution in China's designated free-trade zones.
Asia Pacific bath fittings encompass valves, spouts, diverters, and mounting hardware engineered to deliver tempered water flow at pressures between 0.1 and 1.0 MPa, primarily serving residential hygiene, commercial sanitation, and institutional healthcare environments. Brass material grades command margin pools in India's organized retail channel where BIS-marked alloys attract tariff advantages over unverified imports. Faucet assemblies lead volume across Southeast Asian residential construction, while shower systems represent the fastest-growing product type as Vietnamese and Indonesian developers specify thermostatic mixing valves for new condominium stock.
Japan's Ministry of Economy, Trade and Industry enforces JIS standards on lead-free brass formulations, compelling regional suppliers to reformulate casting processes for cross-border eligibility. China's State Administration for Market Regulation coordinates GB standard updates on water-efficiency ratings, directly influencing product line rationalization decisions by domestic manufacturers. India's Bureau of Indian Standards mandates ISI certification for brass and stainless steel fittings entering government-procured institutional projects. Stakeholders must monitor divergence between national certification regimes as fragmentation in technical requirements reshapes regional supply chain configuration and factory location strategy.
Market Dynamics
Japan's METI lead-free brass mandates are forcing casting process reformulation across Asia Pacific suppliers, while China's SAMR water-efficiency GB standards trigger product line rationalization and factory relocation decisions throughout the regional supply base.
Growth Catalysts
- China's tier-two residential completions:New housing stock in Chengdu, Xi'an, and Wuhan outpaces saturated tier-one markets, generating concentrated faucet and shower system demand from developers seeking cost-competitive specifications.
- BIS certification tariff advantages:India's Bureau of Indian Standards marking creates procurement preference for compliant brass alloys in government-procured institutional healthcare and sanitation projects.
- Thermostatic mixing valve adoption:Vietnamese and Indonesian condominium developers specify precision temperature control systems as differentiated amenities in mid-premium residential towers.
Market Restraints
- Copper-zinc alloy input volatility:Brass material costs fluctuate with London Metal Exchange pricing, compressing margin pools for mid-tier manufacturers without long-term smelter contracts.
- Cross-border certification fragmentation:Divergent JIS, GB, and BIS technical requirements force parallel inventory stocking and duplicate testing expenditures for multi-market suppliers.
- Plastic polymer substitution in economy segments:Polypropylene and ABS injection-molded fittings capture price-sensitive rural residential demand in Indonesia and Philippines.
Strategic Opportunities
- India's organized retail channel expansion:Branded bath fitting penetration remains below levels seen in China, creating whitespace for certified alloy suppliers in metro and tier-two city home improvement stores.
- Sensor-integrated fixture convergence:Touchless activation technology from Japan's aging-accessibility retrofit market is migrating into Southeast Asian hospitality specifications.
- PLI scheme manufacturing incentives:India's production-linked incentive framework for domestic component sourcing reduces landed cost for export-oriented brass foundry operations.
Industry Challenges
- Multi-standard compliance engineering:Product development teams must simultaneously satisfy JIS lead-content limits, GB water-efficiency ratings, and BIS alloy composition rules, extending certification timelines.
- Legacy distributor inventory systems:Traditional wholesale channels in Thailand and Malaysia lack real-time specification tracking, creating order-fulfillment mismatches with project-driven contractor demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Bath Fitting Market |
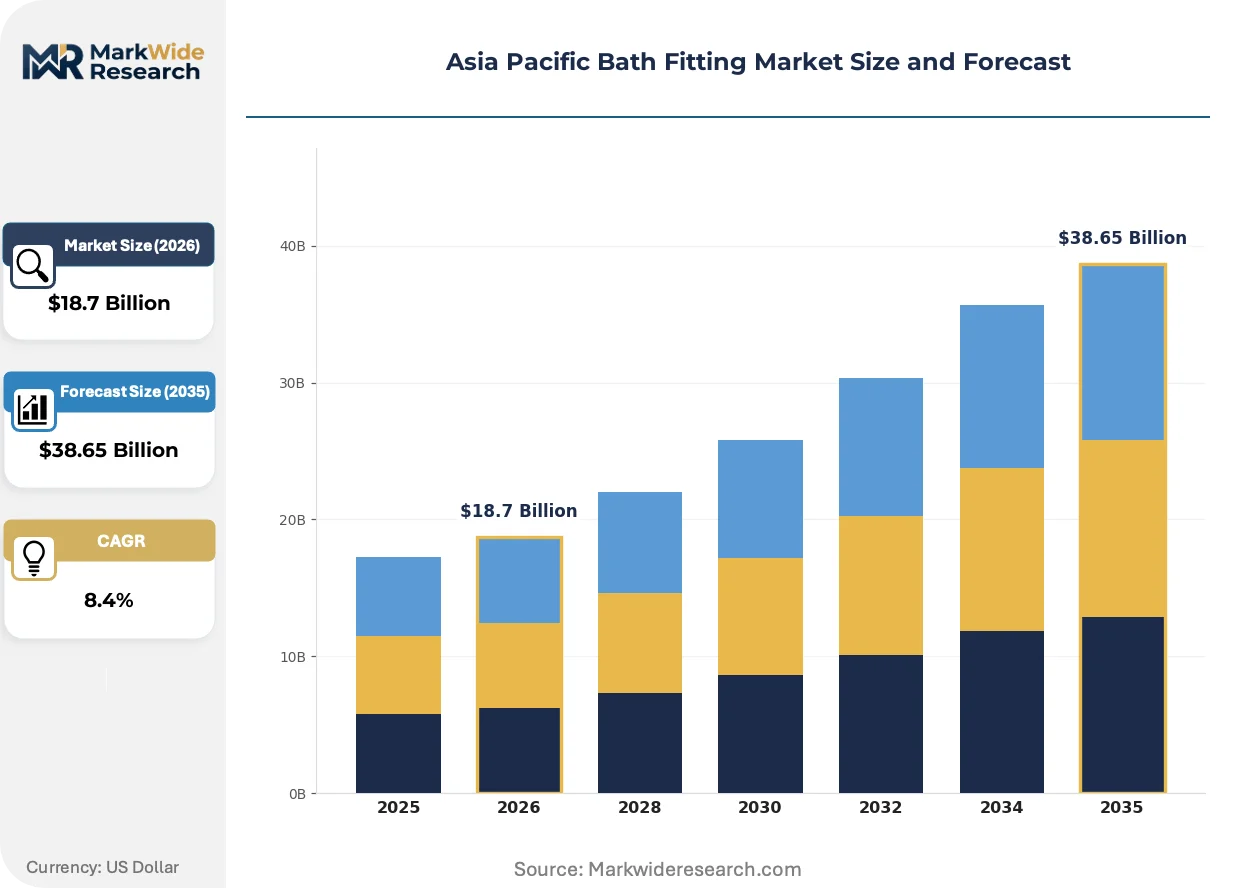
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Showers, Bathtubs, Accessories Material: Brass, Stainless Steel, Plastic, Ceramic End User: Residential, Commercial, Institutional, Industrial Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Cera Sanitaryware, Jaquar, H & R Johnson, Parryware, American Standard, TOTO, LIXIL, GROHE, Kohler, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Bath Fitting Market Strategic Shifts
Digital flow control systems and additive manufacturing processes are compressing development cycles for precision valve components, while regulatory pressure on material composition accelerates process innovation across the regional supplier base.
Thermostatic cartridge technology is miniaturizing. Precision wax-element and bimetal sensors now fit within standard 35mm valve bodies, enabling retrofittable temperature control in existing plumbing infrastructure. Japanese bathroom renovation contractors specify these compact units for aging-in-place accessibility retrofits. The technology is miniaturizing cost structures for premium shower system manufacturers, allowing them to hit mid-market price points without sacrificing performance certification.
China's SAMR coordinates GB standard updates on water-efficiency ratings annually, directly influencing domestic manufacturer product line decisions. The regulations mandate flow-rate labeling that exposes performance variation between brands. Export-oriented foundries in Guangdong and Zhejiang now engineer dual-SKU production lines—one configuration for domestic GB compliance, another for BIS or JIS export markets.
Asset managers at luxury hospitality developers now retain direct specification authority, displacing contractor-driven procurement. Design-led briefs from Bangkok and Singapore hotel operators prioritize sensor-integrated fixtures and finish-matched accessory suites. This concentration of decision-making compresses supplier negotiation cycles and rewards manufacturers with integrated design consultation capabilities.
Asia Pacific Bath Fitting Market Segmentation
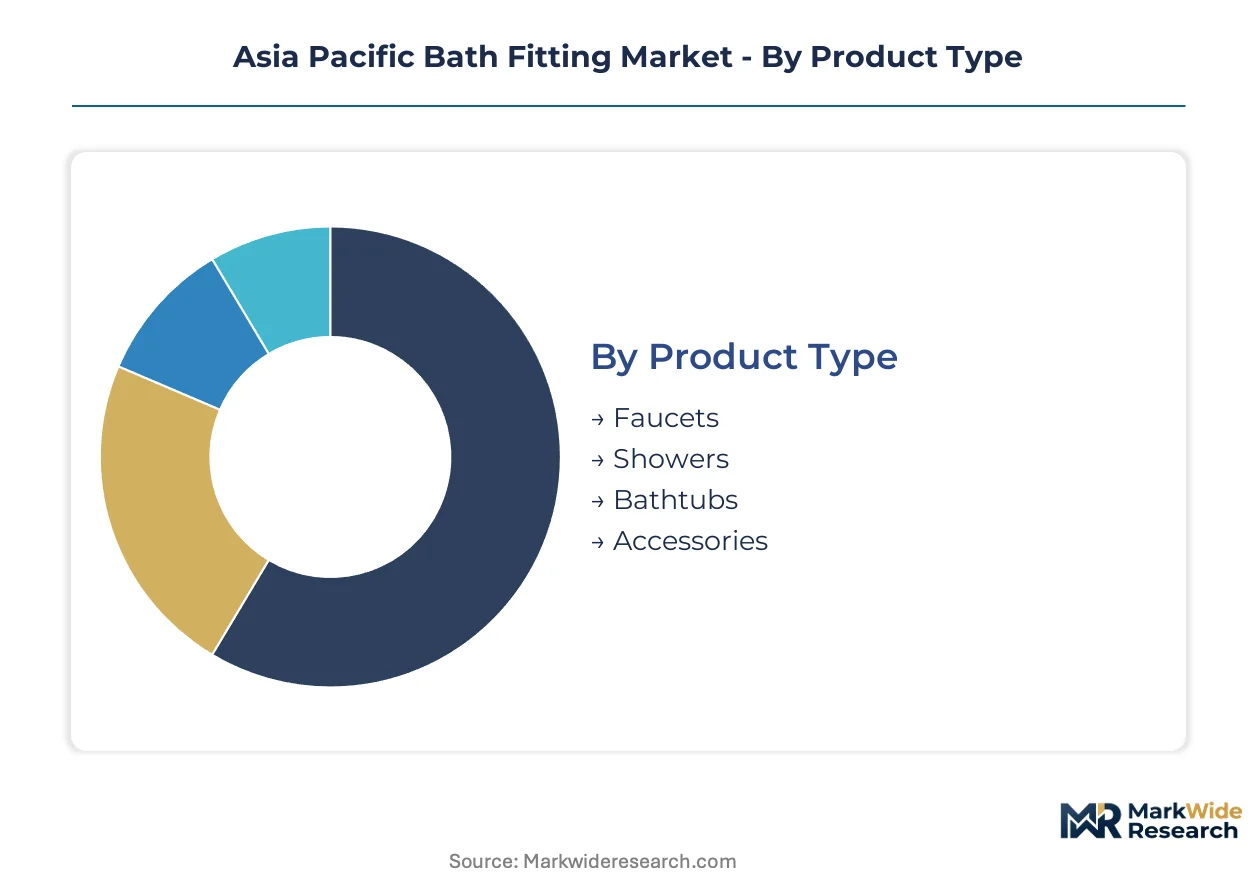
Segmentation in Asia Pacific bath fittings reveals how regulatory divergence and construction cycle timing create distinct margin pools across product categories and material grades. Procurement patterns bifurcate between specification-driven hospitality projects and price-sensitive residential developer bulk purchasing.
Product Type:
Japan's METI lead-free mandates and China's SAMR water-efficiency GB standards force divergent engineering specifications across each product category, compressing development timelines for multi-market portfolios.
- Faucets:Valve assemblies incorporating ceramic disc cartridges deliver tempered water flow at pressures between 0.1 and 1.0 MPa. Demand concentrates in China's tier-two cities where Chengdu, Xi'an, and Wuhan residential completions outpace saturated tier-one markets, driven by developer procurement seeking cost-competitive specifications without sacrificing BIS or GB certification compliance.
- Showers:Thermostatic mixing systems with precision wax-element sensors now fit within standard 35mm valve bodies, enabling retrofittable temperature control. Vietnamese and Indonesian condominium developers specify these as differentiated amenities in mid-premium residential towers, accelerating specification migration from Japan's aging-accessibility retrofit market into Southeast Asian hospitality projects.
- Bathtubs:Acrylic and enameled steel units serve replacement demand in Japan's renovation contractor channel.
- Accessories:Towel bars, robe hooks, and soap dispensers complete finish-matched specification suites for Bangkok and Singapore luxury hotel operators.
Faucets handle the majority of throughput; showers are gaining share fastest as thermostatic technology miniaturization hits mid-market price points.
Material:
Cost tier stratification separates certified alloy suppliers from polymer substitution threats in economy segments.
- Brass:Copper-zinc alloys with BIS-marked composition attract tariff advantages in India's government-procured institutional healthcare and sanitation projects. London Metal Exchange pricing volatility compresses margin pools for mid-tier manufacturers without long-term smelter contracts, forcing backward integration into captive foundry operations.
- Stainless Steel:AISI 304 and 316 grades dominate food-service and healthcare institutional specifications where corrosion resistance mandates override first-cost considerations. India's organized retail channel expansion creates whitespace for certified suppliers in metro and tier-two city home improvement stores.
- Plastic:Polypropylene and ABS injection-molded fittings capture price-sensitive rural residential demand in Indonesia and Philippines, displacing metal alloys in economy segments.
- Ceramic:Vitreous china and porcelain components serve specialized basin and accessory applications with premium finish requirements.
Brass commands the dominant share of value; stainless steel is climbing the fastest as BIS certification procurement preferences expand.
End User:
Application-driven specification authority determines pricing power and design consultation requirements.
- Residential:New housing stock across China's tier-two cities and Southeast Asian condominium developments generates volume demand for faucet and shower system bundles. Developer procurement teams prioritize GB-compliant water-efficiency ratings to satisfy SAMR labeling mandates.
- Commercial:Luxury hospitality asset managers in Bangkok and Singapore now retain direct specification authority, displacing contractor-driven procurement with design-led briefs prioritizing sensor-integrated fixtures and finish-matched accessory suites.
- Institutional:India's BIS certification creates procurement preference for brass and stainless steel fittings entering government-procured healthcare and sanitation infrastructure.
- Industrial:Heavy-duty valve assemblies serve manufacturing facility washdown and process water applications with durability specifications exceeding residential grades.
Residential absorbs the greatest volume; commercial is expanding most quickly as hospitality specification authority concentrates with design-led asset managers.
Distribution Channel:
Customer type and geography determine channel efficiency and inventory carrying requirements.
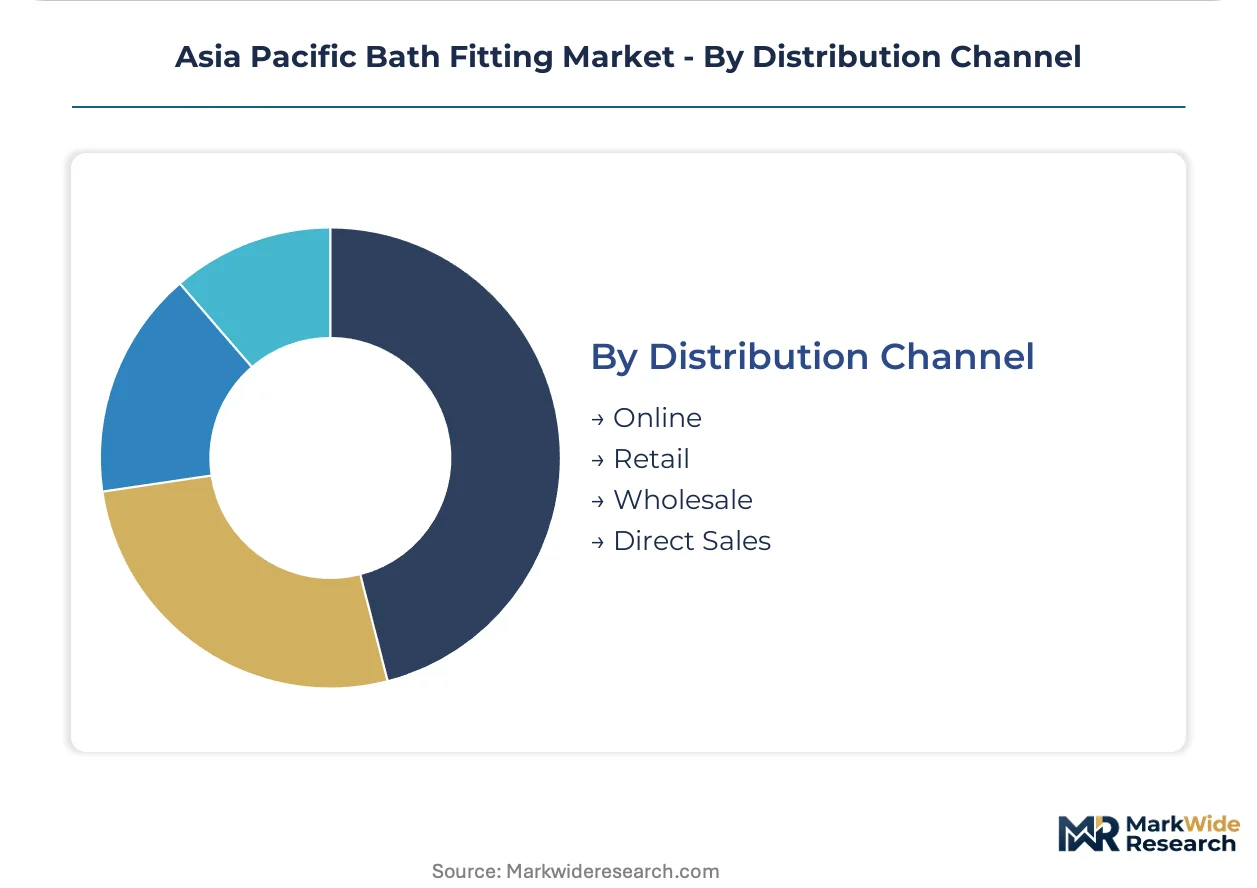
- Online:E-commerce platforms penetrate India's organized retail channel where branded bath fitting penetration remains below Chinese levels, creating whitespace for certified alloy suppliers in metro and tier-two city home improvement stores.
- Retail:Specialty bathroom fixture stores and home improvement centers serve renovation contractors and end consumers with specification consultation and immediate fulfillment.
- Wholesale:Traditional channels in Thailand and Malaysia lack real-time specification tracking, creating order-fulfillment mismatches with project-driven contractor demand.
- Direct Sales:Manufacturer-direct relationships with luxury hospitality developers and large-scale residential developers compress negotiation cycles and reward integrated design consultation capabilities.
Wholesale moves the greatest unit volume; direct sales is the steepest expansion trajectory as asset managers consolidate specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese brass foundries in Guangdong and Zhejiang export thermostatic valve assemblies to Vietnamese condominium developers and Indonesian hospitality contractors, creating a southward trade corridor that channels tier-two manufacturing capacity into Southeast Asian construction booms.
China
Residential completions in Chengdu, Xi'an, and Wuhan outpace saturated tier-one markets, concentrating faucet and shower system demand among developers seeking cost-competitive specifications. SAMR coordinates annual GB standard updates on water-efficiency ratings, forcing dual-SKU production lines at export-oriented foundries. Guangdong brass foundries engineer separate configurations for domestic compliance versus BIS and JIS export markets.
India
Organized retail channel expansion in metro and tier-two city home improvement stores creates whitespace for certified alloy suppliers where branded bath fitting penetration trails Chinese levels. BIS mandates ISI certification for brass and stainless steel fittings entering government-procured institutional healthcare and sanitation projects. Maharashtra and Gujarat foundry clusters leverage PLI scheme incentives to reduce landed costs for export-oriented brass operations.
Japan
Aging-accessibility retrofit contractors specify sensor-integrated fixtures and compact thermostatic cartridges for bathroom renovation projects supporting independent living. METI enforces JIS standards on lead-free brass formulations, compelling regional suppliers to reformulate casting processes for cross-border eligibility. Kanto and Kansai metropolitan renovation channels drive precision valve component demand.
Vietnam
Condominium developers specify thermostatic mixing valves as differentiated amenities in mid-premium residential towers, accelerating technology migration from Japanese retrofit markets. The country's national construction regulator mandates water-efficiency labeling for new residential stock. Ho Chi Minh City and Hanoi construction clusters absorb imported Chinese valve assemblies for high-rise developments.
Indonesia
Luxury hospitality asset managers in Jakarta and Bali retain direct specification authority for sensor-integrated fixtures and finish-matched accessory suites. National standards bodies enforce progressive water-efficiency requirements for commercial building permits. Jababeka and MM2100 industrial zones host assembly operations serving domestic hospitality procurement.
Asia Pacific Bath Fitting Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and design consultation capabilities, creating a tiered structure where scale advantages in casting capacity meet agility in hospitality specification response. The vendor base concentrates around three strategic archetypes: integrated brass foundry-to-brand manufacturers, technology-licensed sensor specialists, and regionally focused mid-premium fabricators. Dominant competitive moves include backward integration into captive foundry operations and direct sales relationships with asset managers displacing wholesale distributor channels.
Among India-based fabricators, Cera Sanitaryware and Jaquar occupy positions within the integrated manufacturing tier, exemplifying scale-driven compliance with BIS certification requirements. TOTO anchors the technology-specialist vector, representing sensor-integrated fixture capabilities migrating from aging-accessibility applications into Southeast Asian hospitality specifications. These three companies illustrate how geographic manufacturing concentration and regulatory compliance specialization determine competitive positioning across the regional supply base.
| Leading Market Players |
|---|
| Cera Sanitaryware |
| Jaquar |
| H & R Johnson |
| Parryware |
| American Standard |
| TOTO |
| LIXIL |
| GROHE |
| Kohler |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day brass alloy inventory cycles concentrate pricing power with Guangdong and Zhejiang foundries holding long-term London Metal Exchange hedging positions, while tier-two Chinese developers and Southeast Asian hospitality contractors absorb margin compression from certification-driven specification upgrades.
Pricing Analysis
Sensor-integrated fixture pricing gaps separate legacy ceramic-cartridge assemblies from thermostatic wax-element systems and emerging touchless activation platforms. Three-tier pricing structure across premium hospitality specifications, standard residential developer bundles, and economy polymer substitutions dominates transaction structures. Price differentiation rests on BIS/JIS/GB certification grade and volume scale procurement. Pricing pressure stems from copper-zinc alloy input volatility compressing mid-tier manufacturer margins. Economy segment buyers in Indonesian and Philippine rural markets exhibit highest price sensitivity; luxury hospitality asset managers in Bangkok and Singapore demonstrate lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate brass foundry operations in China and India, while just-in-time inventory management prevails among Japanese renovation contractors sourcing precision valve components. Geographic supply concentration centers on China, India, and Vietnam for casting and assembly operations. Raw material dependencies draw from Zambian copper concentrates, Indonesian zinc smelter output, and domestic rare-earth elements for sensor components. Single-source vulnerability from London Metal Exchange pricing volatility threatens margin stability. Distribution runs through project-direct manufacturer relationships with hospitality developers, bypassing traditional wholesale channels in Thailand and Malaysia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across national certification regimes creates niche entry points for compliant specialists, as procurement authority shifts from cost-driven contractors to design-led asset managers demanding integrated specification capabilities.
For Market Incumbents: Compound certification compliance advantages by deepening backward integration into captive brass foundry operations in Maharashtra and Gujarat PLI zones, and securing direct sales relationships with luxury hospitality asset managers displacing wholesale distributor channels. Plastic polymer substitution in Indonesian and Philippine economy segments and cross-border certification fragmentation threaten margin pools. For New Entrants and Emerging Players: Differentiate on BIS-marked alloy specialization for India's government-procured institutional healthcare and sanitation projects, where organized retail channel penetration trails Chinese levels. White-space targets include tier-two Indian city home improvement stores and Vietnamese condominium thermostatic valve specifications. Go-to-market through design consultation capabilities bundled with finish-matched accessory suites. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fragmented national certification requirements favor scaled manufacturers with multi-standard compliance engineering teams and captive foundry capacity. Acquisition target archetype: mid-premium fabricators with established BIS/JIS/GB testing infrastructure and direct hospitality relationships. Signal to watch is divergence between SAMR GB standard updates and METI lead-free mandates accelerating factory relocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Operations | Maharashtra and Gujarat PLI incentives reduce landed costs for export-oriented brass casting capacity. |
| Multi-Standard Certification Engineering Investment | Simultaneous JIS lead-content, GB water-efficiency, and BIS alloy compliance compresses rival certification timelines. |
| Direct Sales Channel Development | Manufacturer-direct relationships with Bangkok and Singapore hospitality asset managers bypass wholesale inventory mismatches. |
| Thermostatic Cartridge Miniaturization R&D | Precision wax-element sensors fitting standard 35mm valve bodies unlock mid-premium Vietnamese and Indonesian residential demand. |
| Sensor-Integrated Fixture Platform Launch | Touchless activation technology from Japan's aging-accessibility retrofit market migrates into Southeast Asian hospitality specifications. |
Study Parameters
A standing panel of brass foundry operations managers, luxury hospitality procurement directors, Indian organized retail category buyers, and Japanese bathroom renovation contractors provided ongoing calibration across primary interview cycles, validated against BIS certification databases, SAMR GB standard filings, London Metal Exchange brass pricing archives, and ASEAN construction permit records. Bottom-up project pipeline enumeration and top-down regional construction spending aggregates underwent iterative reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-user application, and distribution channel structure. CAGRs derived from fitted growth curves applied to construction completion forecasts and replacement demand cycles. Industry-specific inputs encompassed thermostatic valve adoption rates in Vietnamese condominiums and sensor-fixture specification penetration in Southeast Asian hospitality.
Decision-makers should treat outputs as directional under base assumptions of sustained tier-two Chinese residential construction and stable BIS certification enforcement; material deviation would warrant model refresh. Revision becomes warranted when copper-zinc alloy price volatility or regulatory divergence between JIS, GB, and BIS regimes crosses thresholds altering manufacturer location strategy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market