
 India Bath Fittings Market | 2026-2036
India Bath Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
India Bath Fittings Market Foresight
Consolidation among premium residential developers in Mumbai, Bangalore, and Delhi-NCR is repositioning procurement leverage toward large-format project buyers who negotiate direct supply contracts. Hindware Homes Limited leverages extensive distribution across tier-2 and tier-3 cities to sustain volume leadership in mass-market faucets and showers. Jaquar anchors its position through in-house brass forging capacity that controls material cost volatility. CERA Sanitaryware Limited differentiates via ceramic specialization spanning sanitaryware and complementary bath fittings.
India bath fittings comprise plumbed fixtures and accessories—including faucets, showerheads, taps, and bathtubs—typically manufactured through gravity die-casting of brass alloys followed by chrome plating to achieve corrosion resistance and surface durability standards specified for wet environments. These products regulate water delivery, temperature mixing, and drainage in residential, commercial, and hospitality installations. Faucets and showerheads dominate current revenue flows given their universal presence across installation types, while floor-mounted and freestanding bathtub segments command premium margins concentrated in luxury hospitality and high-end residential projects. Brass material grades sustain the largest volume share due to machinability and longevity, though stainless steel gains traction in coastal markets where salinity accelerates corrosion.
BIS watermark certification and CEA plumbing codes shape mandatory product testing for flow rates and lead content, compelling domestic manufacturers to upgrade foundry and finishing processes. State-level RERA implementations across Maharashtra, Karnataka, and Tamil Nadu enforce timely project completion, stabilizing fixture procurement schedules for developers. PLI scheme incentives for specialty steel and metal components indirectly support upstream material localization for bath fitting producers. Stakeholders must monitor evolving state building codes and municipal water tariff structures that increasingly specify low-flow fixture mandates.
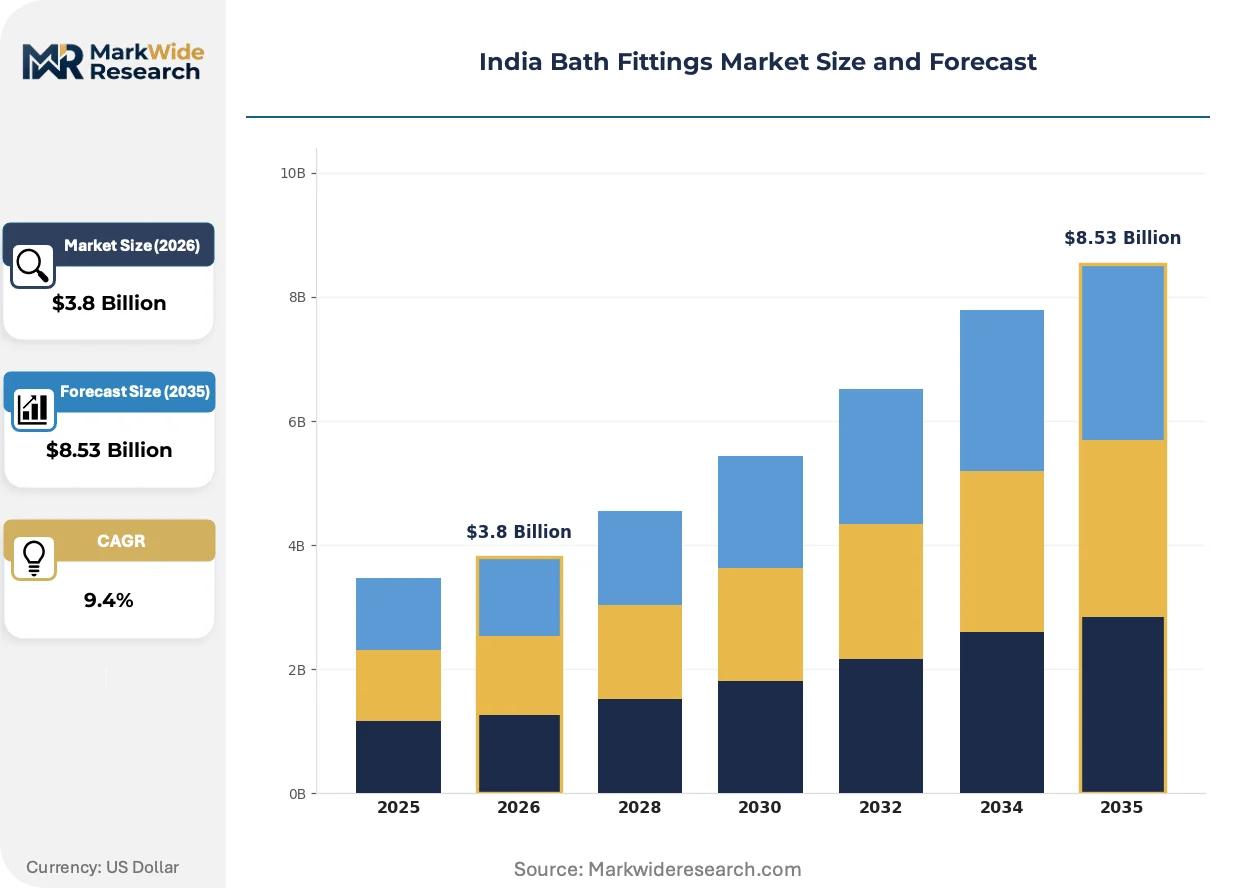
Market Dynamics
BIS watermark certification mandates and CEA plumbing codes are compressing product development timelines while forcing foundry upgrades across domestic manufacturers. Tier-1 developers in Maharashtra and Karnataka now specify sensor-enabled fixtures in master procurement contracts, reshaping supplier qualification criteria.
Growth Catalysts
- Sensor-Enabled Fixtures:Premium residential complexes in Mumbai and Bangalore are embedding touchless faucets and automated temperature controls. Hospitality chains in Goa and Kerala follow suit for hygiene differentiation.
- CEA Plumbing Codes:Central Electricity Authority mandates on flow-rate testing are standardizing product performance benchmarks. Compliance unlocks access to institutional and government housing tenders.
- Brass Forging Localization:In-house brass alloy processing capabilities at major manufacturers are insulating production from imported ingot price swings. Gujarat and Tamil Nadu foundry clusters supply downstream fitting producers.
Market Restraints
- Lead Content Compliance:BIS testing protocols for lead-free brass formulations require expensive spectrometry equipment. Small foundries in Moradabad and Jamnagar face capital barriers to certification.
- Chrome Plating Environmental Controls:State Pollution Control Board enforcement in Maharashtra and Gujarat is shuttering unregistered electroplating units. Supply of finished faucet surfaces concentrates among compliant job shops.
- Stainless Steel Substitution:Coastal markets in Kerala and Tamil Nadu are pivoting to 304-grade stainless fixtures. Brass retains interior market share but loses premium positioning in corrosive environments.
Strategic Opportunities
- Tier-3 City Penetration:Real estate pipelines in Indore, Coimbatore, and Lucknow remain underpenetrated by organized bath fitting brands. Direct distribution investments capture first-mover positioning in emerging consumption zones.
- PLI Scheme Alignment:Production-linked incentives for specialty steel and metal components subsidize upstream material localization. Bath fitting producers backward-integrate into precision casting inputs.
- Smart Home Integration:IoT-enabled water management systems are converging with bath fixtures. Developers in Hyderabad and Pune specify connected plumbing as standard in luxury inventory.
Industry Challenges
- Die-Casting Skill Scarcity:Gravity die-casting expertise for complex brass geometries is concentrated among aging technicians in Aligarh and Jamnagar. Training pipeline gaps threaten production quality consistency.
- BIS Certification Timelines:Watermark testing queues at accredited laboratories extend lead times by 8-12 weeks. Product launches miss seasonal construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bath Fittings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Showerheads, Faucets, Taps, Bathtubs Material: Ceramic, Stainless Steel, Brass, Plastic Installation Type: Wall-mounted, Floor-mounted, Freestanding, Built-in End User: Residential, Commercial, Institutional, Hospitality |
| Companies Covered | Hindware Homes Limited, H & R Johnson (India) Ltd, Jaquar, Duravit India, Ruhe, CERA Sanitaryware Limited, Parryware Limited, Somany, Kohler, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bath Fittings Market Shifts & Advancements
Digital control interfaces and material science advances are redefining fixture functionality beyond basic water delivery. Regulatory pressure on water efficiency and lead safety is accelerating product obsolescence cycles.
Thermostatic mixing valves with digital temperature displays are expanding into mid-range residential specifications. Developers in Bangalore and Chennai specify these units in 3BHK and 4BHK inventory to differentiate against standard mixer taps. The technology is expanding into price points previously dominated by manual controls, compressing margin structures for basic faucet categories.
BIS watermark certification requirements for flow-rate disclosure and lead-content limits are tightening enforcement across Maharashtra and Gujarat. Manufacturers must submit samples to accredited NABL laboratories before market release. Premium export-oriented producers in these states absorb compliance costs faster than unorganized competitors, accelerating formalization of supply concentration.
Project developers are consolidating fixture procurement under direct supply contracts with manufacturers, bypassing traditional distributor networks. Large-format residential builders in Mumbai and Delhi-NCR negotiate volume pricing and custom finishes directly. This channel compression is most visible in Maharashtra, where RERA-mandated project timelines reward procurement predictability over distributor flexibility.
India Bath Fittings Market Segmentation
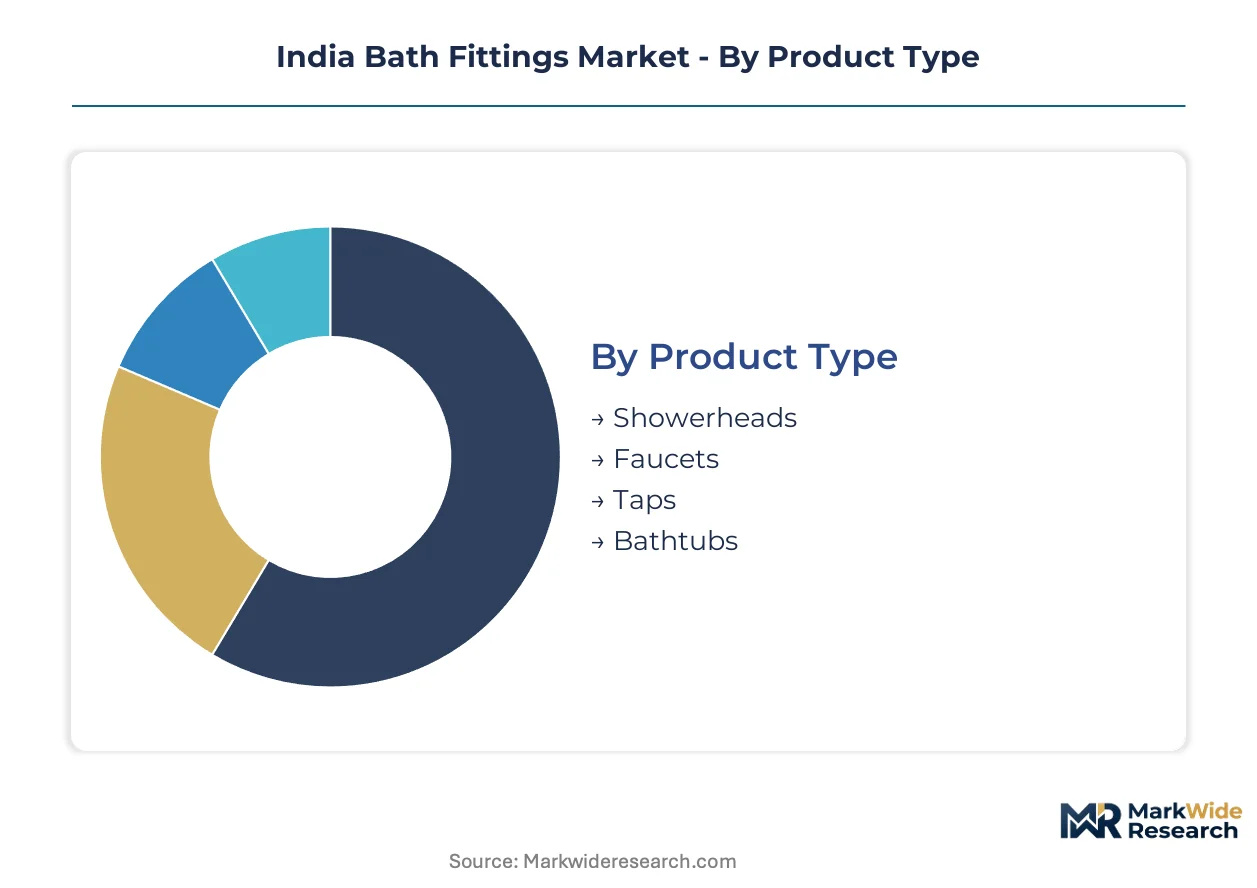
Segmentation in India's bath fittings market reveals how BIS watermark tiers and CEA flow-rate classifications split procurement budgets across installation types. Certification burdens vary sharply by material grade and end-use application, reshaping supplier qualification requirements.
Product Type:
Faucets and showerheads carry mandatory BIS testing for lead content and flow-rate disclosure, while bathtubs face lighter certification loads focused on surface durability standards.
- Faucets:Gravity die-cast brass bodies with chrome plating dominate volume. Mixer taps with ceramic disc cartridges are displacing traditional screw-down valves in Maharashtra and Gujarat residential projects due to BIS durability mandates.
- Showerheads:Multi-flow aerators and rain-style overhead fixtures require CEA flow-rate certification for institutional tenders. Sensor-enabled variants in Bangalore premium complexes command direct manufacturer contracts bypassing distributor markups.
- Taps:Bib cocks and pillar taps serve mass-market replacement cycles with lower certification thresholds. Plastic-bodied variants penetrate rural markets where BIS compliance remains uneven.
- Bathtubs:Acrylic and ceramic composite units concentrate in luxury hospitality and high-end residential. Floor-mounted and freestanding configurations bypass the universal presence requirements driving faucet and showerhead volumes.
Faucets sit at the top of the volume ranking, with sensor-enabled showerheads climbing the fastest.
Material:
Material selection maps directly to corrosion exposure and certification cost tiers, with coastal salinity and BIS lead-content rules filtering viable options.
- Brass:Zinc-copper alloys with 59-62% copper content remain the machinability standard for complex faucet geometries. In-house forging capacity at major producers insulates against imported ingot price swings from Gujarat and Tamil Nadu foundry clusters.
- Stainless Steel:304-grade fixtures displace brass in Kerala and Tamil Nadu coastal markets where salinity accelerates corrosion. BIS testing protocols for stainless focus on surface finish durability rather than lead content, lowering compliance burdens.
- Ceramic:Specialized for sanitaryware-adjacent fittings and decorative handles. CERA Sanitaryware leverages ceramic specialization across complementary bath fitting lines.
- Plastic:ABS and polypropylene variants serve economy-tier replacement markets with minimal BIS watermark requirements. Volume concentrates in tier-3 cities where price sensitivity overrides durability expectations.
Brass retains dominant volume share, though stainless steel is gaining share fastest in corrosive environments.
Installation Type:
Mounting configuration determines project-phase integration timing and developer procurement leverage, with built-in variants requiring earliest specification.
- Wall-mounted:Concealed valve bodies with exposed trim plates dominate residential and commercial specifications. RERA-mandated project timelines in Maharashtra reward predictable wall-mounted fixture procurement schedules.
- Floor-mounted:Freestanding bathtub fillers and bidet fixtures require structural floor reinforcement. Luxury hospitality projects in Goa specify floor-mounted variants for aesthetic differentiation.
- Freestanding:Pedestal sinks and independent bathtub units bypass plumbing rough-in dependencies. Premium residential developers in Delhi-NCR negotiate custom finishes directly with manufacturers for freestanding inventory.
- Built-in:Concealed cisterns and recessed shower controls demand earliest specification in construction schedules. Smart home integration in Hyderabad and Pune luxury projects favors built-in infrastructure for IoT water management.
Wall-mounted fixtures hold the volume lead, while built-in installations show the steepest expansion trajectory from smart home convergence.
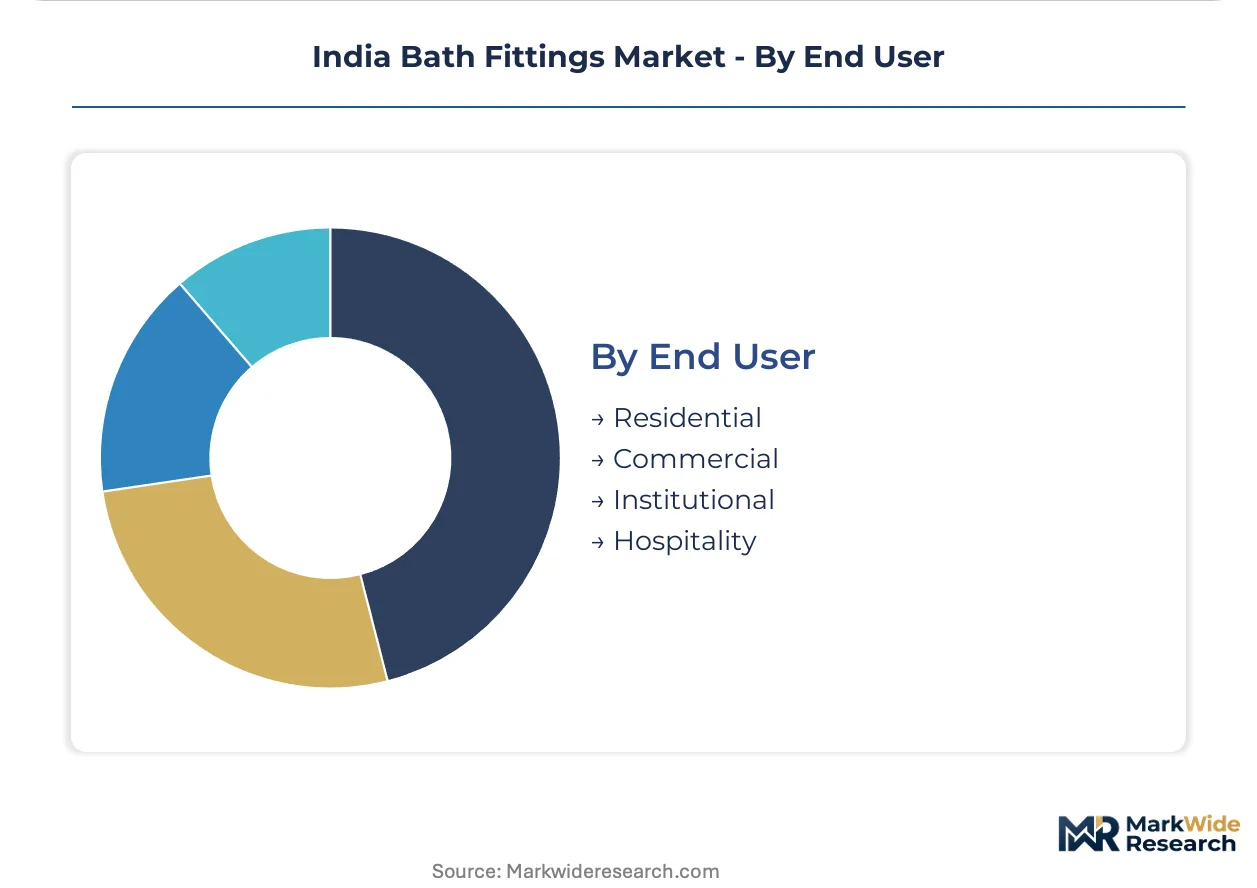
End User:
End-use segments split by certification stringency and procurement channel structure, with institutional tenders imposing the heaviest BIS and CEA compliance burdens.
- Residential:Individual homeowners and project developers drive faucet and showerhead replacement cycles. Tier-1 developers in Mumbai and Bangalore consolidate procurement under direct supply contracts bypassing traditional distribution.
- Commercial:Office complexes and retail spaces specify durable brass fixtures with extended warranty terms. CEA plumbing code compliance unlocks access to government and institutional housing tenders.
- Institutional:Schools, hospitals, and government housing impose mandatory BIS watermark and flow-rate disclosure. NABL laboratory testing queues extend lead times by 8-12 weeks for institutional-grade product launches.
- Hospitality:Hotels and resorts in Goa and Kerala prioritize sensor-enabled fixtures for hygiene differentiation. Procurement concentrates among export-oriented producers with faster compliance cost absorption than unorganized competitors.
Residential demand anchors volume, with hospitality segment expanding most quickly from hygiene-driven specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's bath fittings demand outpaces Bangladesh's nascent market by an order of magnitude, yet both face similar coastal corrosion challenges that reshape material preferences. State-level building codes and municipal water tariffs create divergent procurement incentives across sub-regions.
Maharashtra
Mumbai's premium residential towers specify sensor-enabled faucets under consolidated developer procurement contracts. BIS watermark enforcement through NABL-accredited Mumbai laboratories compresses product launch windows. Alibag and Pune manufacturing clusters supply chrome-plated brass fixtures to tier-1 developers navigating RERA-mandated completion deadlines.
Gujarat
Jamnagar's brass forging foundries feed downstream fitting producers with localized zinc-copper alloy supply. State Pollution Control Board electroplating regulations shutter unregistered job shops, concentrating finished surface supply among compliant units. Surat and Ahmedabad real estate pipelines sustain bulk fixture procurement from organized manufacturers.
Karnataka
Bangalore's luxury residential inventory embeds thermostatic mixing valves with digital displays as standard 3BHK specifications. CEA plumbing code compliance unlocks access to institutional tenders for Bengaluru-based producers. Peenya industrial estate hosts precision die-casting operations serving sensor-enabled showerhead demand from hospitality chains in Goa.
Tamil Nadu
Chennai coastal salinity accelerates 304-grade stainless steel displacement of brass fixtures in premium installations. Tiruchirappalli and Coimbatore foundry clusters supply brass inputs while local manufacturers pivot toward corrosion-resistant material grades. State building code amendments specify low-flow mandates for commercial complexes.
Delhi-NCR
Gurugram and Noida developers negotiate direct supply contracts for custom-finish freestanding bathtub inventory. Municipal water tariff structures in Delhi increasingly specify flow-rate disclosure for institutional procurement. Manesar manufacturing units serve hospitality projects in Rajasthan with export-oriented compliance capabilities.
India Bath Fittings Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale-driven volume players and premium-positioned specialists capture distinct value pools. The vendor base organizes around three strategic archetypes: mass-market distributors with tier-2/3 penetration, integrated manufacturers with captive brass forging, and ceramic-specialized diversified producers. Competitive dynamics center on backward integration into foundry operations and direct developer contract consolidation bypassing traditional distribution channels.
Among Indian market anchors, Hindware Homes Limited exemplifies the mass-market distribution archetype with extensive tier-2 and tier-3 city coverage, while Jaquar occupies a position defined by in-house brass alloy processing capabilities that buffer material cost volatility. CERA Sanitaryware Limited represents the diversified ceramic-specialist model spanning complementary sanitaryware and fitting lines. These three players illustrate how competitive positioning stratifies across supply chain control, geographic penetration, and product portfolio breadth.
| Leading Market Players |
|---|
| Hindware Homes Limited |
| H & R Johnson (India) Ltd |
| Jaquar |
| Duravit India |
| Ruhe |
| CERA Sanitaryware Limited |
| Parryware Limited |
| Somany |
| Kohler |
| Others |
Supply & Pricing Matrix
Direct developer procurement contracts in Maharashtra and Karnataka are compressing distributor margins and forcing manufacturers to absorb certification costs upfront, reshaping how supply capacity aligns with price-sensitive volume tiers. Brass ingot price volatility and chrome plating environmental compliance are feeding back into product line rationalization decisions.
Pricing Analysis
Capacity additions in Gujarat and Tamil Nadu foundry clusters are reshaping price floors for brass alloy inputs, easing material cost pressure on downstream fitting producers. Three-tier pricing structure across premium sensor-enabled, standard mixer-tap, and economy plastic-bodied levels stratifies by BIS certification grade and volume scale. Pricing pressure stems from tier-1 developer consolidation negotiating direct supply terms. Individual homeowners in tier-3 cities exhibit highest price sensitivity, while luxury hospitality projects in Goa show least.
Supply Chain Analysis
Single-source vulnerability sits with Jamnagar brass forging clusters supplying zinc-copper alloy inputs to national fitting producers. Manufacturing concentration rests on India, with secondary tooling inputs drawn from China and Germany. Raw material dependencies hinge on copper-zinc ingots, chrome plating chemicals, and ceramic disc cartridges. Tariff exposure on specialty steel alloys threatens stainless steel fixture cost structures. Distribution runs through project developer direct contracts bypassing traditional wholesale networks in tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India bath fittings market operates as a regulatory compounder where BIS watermark certification mandates and CEA plumbing code enforcement are accelerating product obsolescence and concentrating procurement among compliant manufacturers.
For Market Incumbents: Hedge against stainless steel substitution in coastal markets by diversifying material grade offerings beyond brass-dominant portfolios. Accelerate in-house forging capacity additions in Gujarat and Tamil Nadu to insulate against imported ingot price swings. Defensive consolidation through acquiring NABL-accredited testing capabilities compresses competitor launch windows. For New Entrants and Emerging Players: Direct distributor relationships in Indore, Coimbatore, and Lucknow offer lowest competitive density for organized brand establishment. Tier-3 city real estate pipelines remain underpenetrated by sensor-enabled fixture specifications. Go-to-market through regional developer consortia bypasses entrenched wholesale channel resistance. For Investors and Strategic Acquirers: Asymmetric upside sits with export-oriented manufacturers possessing faster BIS compliance cost absorption than unorganized competitors. Five-to-ten year viability favors producers backward-integrated into precision casting with captive brass alloy processing. Monitor state-level low-flow mandate adoptions as inflection indicator for thermostatic valve demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Forging | Captive alloy processing insulates Jaquar and Hindware from imported ingot price volatility. |
| Sensor-Enabled Fixture Portfolio Expansion | Premium residential developers in Mumbai specify touchless faucets as standard inventory differentiation. |
| NABL Laboratory Accreditation Investment | Accelerated BIS watermark testing unlocks seasonal construction procurement windows. |
| Tier-3 City Distribution Network Buildout | First-mover positioning in Indore and Lucknow captures emerging real estate pipeline demand. |
| Stainless Steel Product Line Diversification | 304-grade fixtures address coastal corrosion in Kerala and Tamil Nadu premium installations. |
Research Methodology
Bottom-up residential and commercial installation modeling reconciled against top-down brass alloy supply tracking forms the analytical core. Primary interviews with project procurement managers at tier-1 developers, foundry operations heads in Jamnagar and Aligarh, distributor principals in tier-2 cities, and BIS certification laboratory directors combined with secondary validation from customs trade data, RERA project registration databases, CEA plumbing code filings, and state pollution control board enforcement records. Triangulation across demand-side specification trends and supply-side capacity utilization ensures cross-verified output integrity.
Input-output matrices map product type, material grade, installation configuration, and end-use segment dimensions across the projection horizon. CAGRs derive from segment-level volume buildups tempered by regulatory compliance cost absorption rates and material substitution elasticities in coastal versus interior markets. Forecast inputs incorporate state-level RERA implementation timelines and municipal water tariff structure amendments specifying low-flow fixture mandates.
Revisions become necessary when BIS testing protocol amendments, state pollution control board electroplating enforcement escalations, or PLI scheme incentive recalibrations materialize. Forecasts reflect documented assumptions on certification timeline standardization and developer procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Global Shower Cubicles Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Artificial Stone Bathtubs Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Bathroom Pods Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market