
 Global Shower Cubicles Market | 2026-2036
Global Shower Cubicles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shower Cubicles Market Outlook
Market Context
Vietnam is reconfiguring its export-oriented ceramics and glass fabrication base to serve European and North American shower enclosure supply chains. Kohler Co. leverages integrated casting and glazing operations across multiple Asian plants to sustain cost-advantaged component flows. LIXIL Group anchors its competitive stance through captive distribution in Japan and Southeast Asia, while Masco Corporation competes via specialized retail channel control in North American home improvement.
Technical Definition and Segment Structure
A shower cubicle denotes an enclosed bathing compartment, typically fabricated from tempered safety glass ranging 6-10 mm in thickness, extruded aluminum or PVC framing, and thermoset seals, engineered to contain water spray and manage drainage within residential, commercial, or institutional wet rooms. Frameless configurations command premium positioning due to higher glass specification and precision hardware requirements, while semi-frameless variants occupy the volume-driven middle tier where cost and aesthetics balance. Alcove installations dominate residential retrofit activity, whereas walk-in formats are gaining specification in hospitality and aged-care health facilities where barrier-free access codes apply.
Regulatory Environment and Outlook
The EPA WaterSense program and EU Ecodesign requirements shape product development trajectories by mandating flow-rate thresholds and material recyclability disclosures, while OSHA and national building codes in Germany, Australia, and the United States enforce slip-resistance and tempered-glass safety standards for commercial installations. China's GB standards and India's BIS certification create parallel compliance tracks for Asian supply bases serving domestic and export markets. Stakeholders must monitor divergence between regional water-efficiency thresholds and glass safety testing protocols to avoid stranded inventory or delayed market access.
Market Dynamics
Water-efficiency mandates across Germany, the United States, and Australia are compressing product lifecycles and forcing rapid material transitions from PVC framing to recyclable aluminum and high-performance thermoset composites.
Growth Catalysts
- EPA WaterSense thresholds:Flow-rate restrictions in North America are compelling hardware upgrades and premium fixture bundling.
- Barrier-free access codes:Hospitality and aged-care facilities in Australia and Germany are specifying walk-in formats to meet accessibility mandates.
- Frameless glass specification:Precision engineering standards in Germany sustain above-average adoption of 10 mm tempered safety glass enclosures.
Market Restraints
- Aluminum price volatility:Extruded framing costs fluctuate with energy-intensive smelting economics, squeezing mid-tier margins.
- Supply concentration in Vietnam:Export-oriented ceramics and glass fabrication clusters create single-point vulnerability for European supply chains.
- GB standard divergence:China's domestic certification requirements fragment testing protocols and strand inventory for dual-market producers.
Strategic Opportunities
- India's BIS certification expansion:Unmet housing stock and urban sanitation drives create white space for standardized, cost-optimized cubicle systems.
- Digital specification platforms:Architect and contractor procurement is migrating to BIM-integrated channels that compress design-to-install timelines.
- Thermoset seal recycling mandates:EU Ecodesign recyclability disclosures will reward early movers with closed-loop material recovery systems.
Industry Challenges
- Tempered glass tempering technician shortage:Specialized heat-treatment expertise constrains capacity expansion in precision frameless manufacturing.
- Multi-jurisdiction compliance timelines:Simultaneous OSHA, REACH, and BIS certification processes delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shower Cubicles Market |
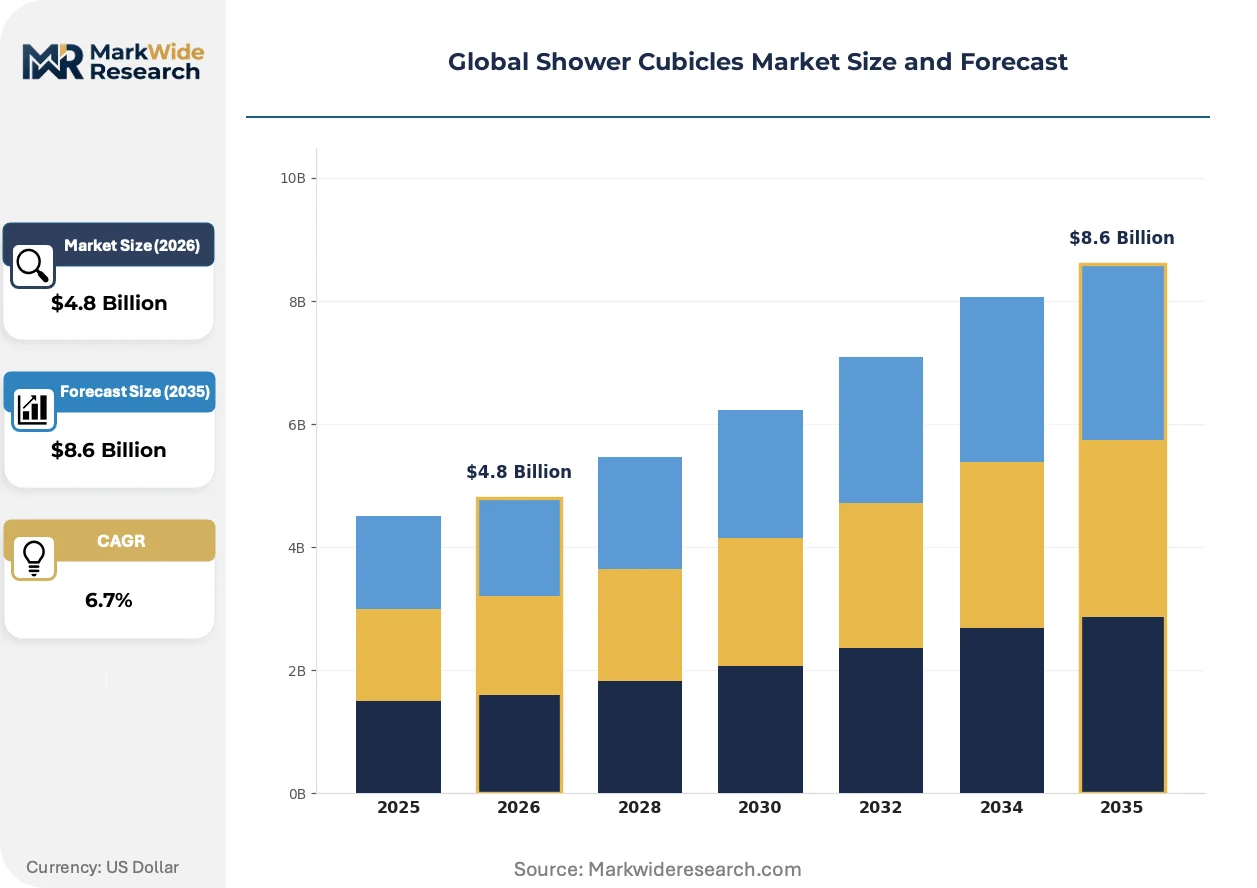
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frameless, Semi-Frameless, Framed, Bi-Fold Material: Glass, Acrylic, PVC, Composite Installation Type: Alcove, Corner, Walk-In, Curved End User: Residential, Commercial, Hospitality, Health Facilities |
| Companies Covered | Kohler Co., LIXIL Group, Masco Corporation, Jaquar Group, Huppe, Porcelanosa Group, Roca Sanitario, Villeroy & Boch, American Standard Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shower Cubicles Market Strategic Shifts
Digital fabrication and smart-material integration are compressing traditional supply chains while regulatory disclosure requirements force transparency into previously opaque specification decisions.
Ultra-clear low-iron glass with proprietary hydrophobic nano-coatings is rendering obsolete standard tempered glass maintenance cycles in premium residential and hospitality installations. High-end developers in Germany and the UAE are specifying these surfaces to reduce cleaning labor contracts. The technology is rendering obsolete the traditional service-revenue model tied to chemical treatment products.
EU Ecodesign material recyclability disclosures are forcing aluminum and thermoset suppliers to document end-of-life recovery pathways. Manufacturers serving European markets must now validate closed-loop claims through third-party auditors. Frameless enclosure producers with captive recycling partnerships are capturing specification preference from sustainability-focused hotel operators.
Builder and contractor procurement is consolidating through centralized purchasing platforms that disintermediate traditional distributor networks. Large-scale residential developers in the United States and Australia are negotiating direct factory relationships for volume-standardized alcove configurations. This channel compression is most visible in North American home improvement retail, where specialized retail control is yielding to project-direct fulfillment models.
Global Shower Cubicles Market Segmentation
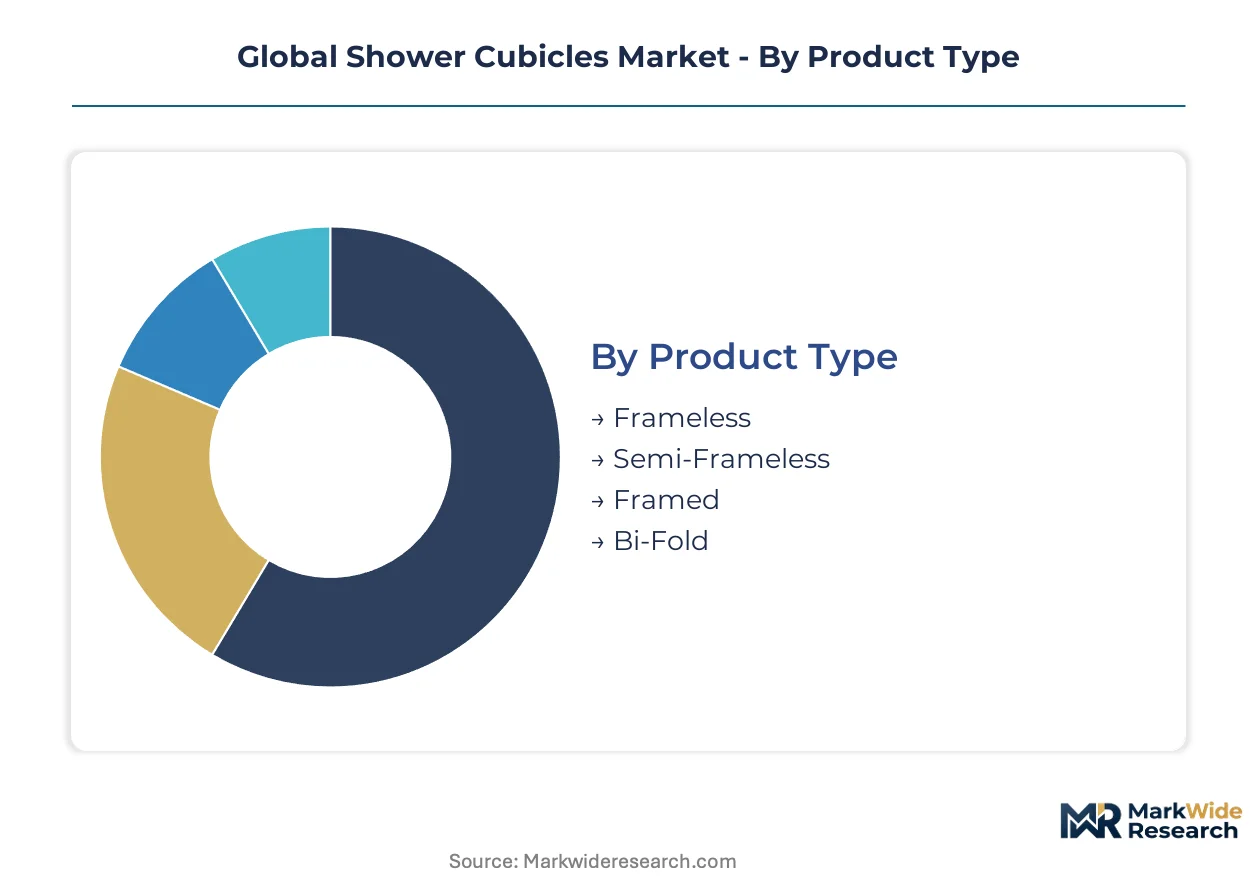
Segmentation in shower cubicles reveals divergent replacement cycles and margin structures across architectural formats. Product type and material selection directly determine specification velocity, with premium frameless systems commanding extended lead times while volume-tier alternatives turn over rapidly in renovation markets.
Product Type:
Cycle times vary dramatically across enclosure architectures, with hardware complexity and glass specification driving procurement timelines from specification to installation.
- Frameless:Heavy-gauge tempered glass panels rely on precision-machined hinges and wall brackets for structural integrity. German residential developers specify these systems for luxury housing stock, where 10 mm glass thickness and concealed hardware justify extended lead times and premium positioning.
- Semi-Frameless:Hybrid construction pairs minimal aluminum headrails with unframed glass panels to balance aesthetics and cost. Australian home improvement retailers stock these configurations most heavily, as mid-tier renovation budgets favor the compromise between frameless elegance and framed economy.
- Framed:Complete aluminum or PVC perimeter framing provides maximum water containment at lowest installed cost. Volume residential construction in India and Southeast Asia defaults to this specification.
- Bi-Fold:Hinged folding panels accommodate tight bathroom footprints where swing clearance is constrained. Compact urban apartments in Japan and South Korea drive specification for space-efficient operation.
Framed enclosures anchor the volume base while frameless systems gain share at the steepest rate.
Material:
Cost tiers separate premium glass specifications from polymer alternatives, with recyclability mandates in Europe accelerating material transitions.
- Glass:Tempered safety glass dominates premium specification, with low-iron variants reducing green tint for high-end hospitality. WaterSense-certified hardware bundling in North America pairs most naturally with glass enclosures.
- Acrylic:Thermoformed polymer panels offer impact resistance and thermal insulation at reduced weight. Mobile home and recreational vehicle manufacturers in the United States specify acrylic for transportation durability.
- PVC:Extruded polyvinyl chloride framing and paneling persists in economy-tier replacement markets. EU Ecodesign recyclability disclosures are displacing virgin PVC in favor of aluminum alternatives.
- Composite:Engineered stone-resin or fiberglass-reinforced formulations deliver stone aesthetics without weight penalties. Solid surface shower bases in Germany increasingly pair with composite wall panels for seamless wet-room construction.
Glass commands the premium tier while composite materials climb fastest in hospitality renovation specification.
Installation Type:
Application context determines format selection, with accessibility codes and spatial constraints driving specification divergence across residential and institutional environments.
- Alcove:Three-wall recessed configurations dominate residential retrofit activity, leveraging existing plumbing rough-ins. North American big-box retailers move highest unit volumes through standardized 60-inch width modules.
- Corner:Neo-angle or square footprint designs maximize floor space in compact bathrooms. Urban condominium stock in Singapore and Hong Kong sustains above-average specification rates.
- Walk-In:Barrier-free curbless entries comply with aged-care and hospitality accessibility mandates. German nursing facility construction codes require these formats for wheelchair maneuverability.
- Curved:Radius glass or acrylic construction creates visual focal points in luxury residential and boutique hotel contexts. UAE high-end residential towers specify curved enclosures for architectural distinction.
Alcove installations sustain the volume foundation while walk-in formats expand most quickly on regulatory tailwinds.
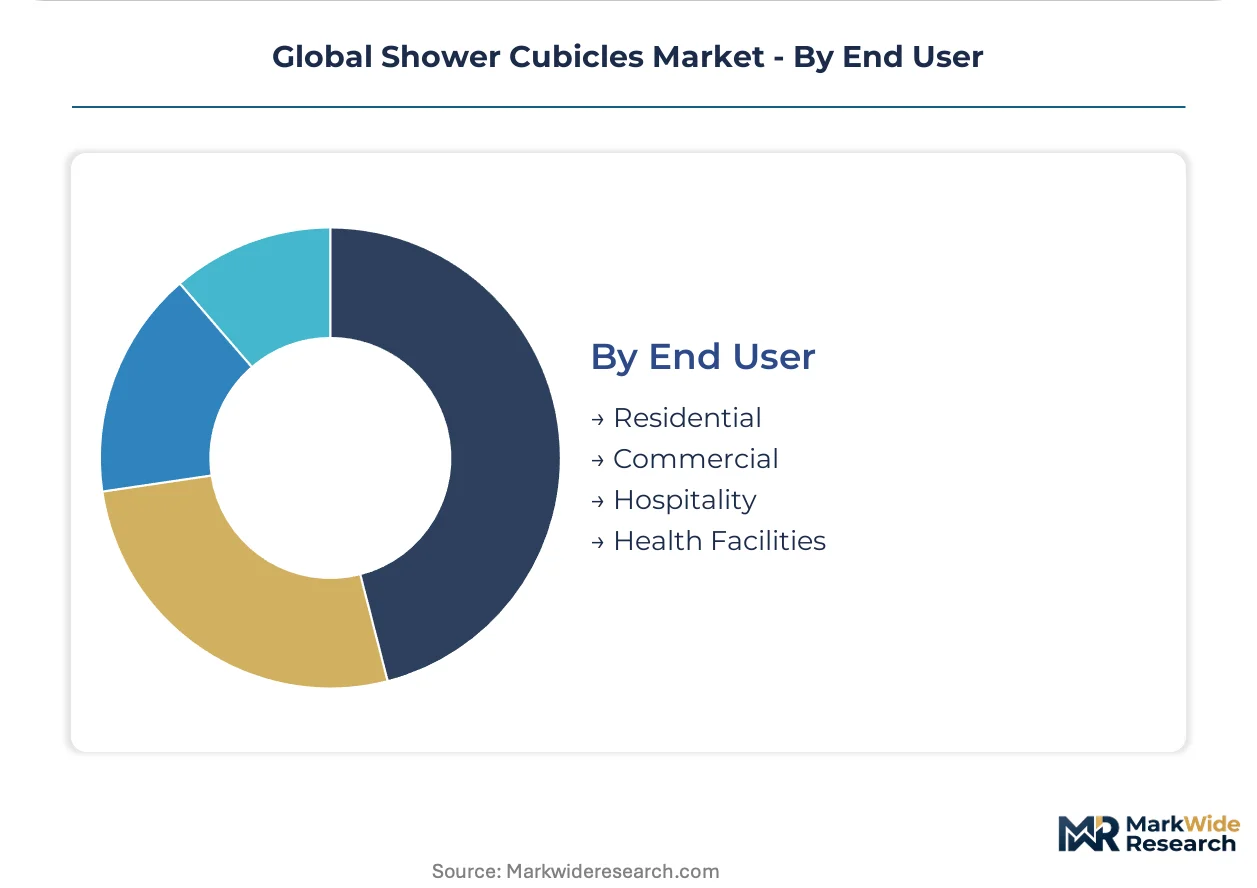
End User:
Customer type dictates durability requirements, maintenance protocols, and procurement channel preferences across divergent built environments.
- Residential:Single-family and multifamily housing drives replacement cycles tied to bathroom renovation waves. Australian owner-occupier renovation grants accelerated demand during recent program windows.
- Commercial:Office and institutional facilities prioritize vandal-resistant hardware and accelerated installation timelines. General contractor procurement platforms in the United States consolidate specification for standardized alcove units.
- Hospitality:Hotel operators balance guest experience aesthetics with housekeeping labor efficiency. Hydrophobic nano-coating adoption concentrates in UAE and German luxury hotel chains.
- Health Facilities:Hospitals and aged-care centers mandate slip-resistant flooring integration and grab-bar compatibility. Australian aged-care construction standards enforce walk-in format specification.
Residential renovation sustains the demand base while health facilities specification advances fastest on demographic and regulatory drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA WaterSense thresholds and EU Ecodesign requirements anchor demand trajectories in the two largest specification markets, while export-oriented fabrication clusters in Vietnam and precision manufacturing bases in Germany create divergent supply-side geometries.
United States
Residential bathroom renovation waves drive specification velocity, with big-box retailers moving standardized 60-inch alcove modules for retrofit activity. EPA WaterSense flow-rate restrictions compel hardware upgrades and premium fixture bundling. Southeast fabrication plants serve domestic distribution networks with cost-optimized component flows.
Germany
Precision engineering standards sustain above-average adoption of 10 mm tempered safety glass in luxury housing stock. KBA-adjacent building codes enforce slip-resistance and tempered-glass safety standards for commercial installations. Bavarian manufacturing clusters specialize in frameless enclosure hardware and concealed bracket systems for premium residential developers.
Australia
Owner-occupier renovation grants accelerated demand during recent program windows, concentrating activity in semi-frameless mid-tier configurations. Aged-care construction standards enforced by TGA-aligned state regulators mandate walk-in format specification for wheelchair maneuverability. Melbourne and Sydney distributors stock hybrid constructions most heavily for renovation channel fulfillment.
Vietnam
Export-oriented ceramics and glass fabrication bases reconfigure to serve European and North American supply chains with cost-advantaged component flows. BIS certification alignment for Indian market access creates parallel compliance tracks for dual-market producers. Ho Chi Minh City and Hanoi industrial zones concentrate tempered glass tempering capacity for frameless enclosure exports.
India
Unmet housing stock and urban sanitation drives create white space for standardized, cost-optimized cubicle systems in volume residential construction. BIS certification expansion fragments testing protocols for producers serving domestic and export markets. Gujarat and Maharashtra fabrication clusters scale aluminum framing production for economy-tier framed enclosures.
Global Shower Cubicles Market Competitive Environment
Integrated bathroom specialists and diversified building materials groups split the market between captive distribution control and project-direct fulfillment models. The vendor base concentrates around three strategic archetypes: plumbing-fixture conglomerates with casting and glazing operations, specialized enclosure fabricators with regional channel dominance, and diversified building products groups with retail network control. Competitive moves center on backward integration into glass tempering capacity and BIM-integrated specification platform development.
Within the integrated-fixture tier, Kohler Co. and LIXIL Group exemplify divergent geographic anchoring strategies. The Wisconsin-based conglomerate leverages Asian plant networks for component cost positioning. The Tokyo-anchored group controls captive distribution across Japan and Southeast Asia. Masco Corporation occupies a position between these models through specialized retail channel relationships in North American home improvement.
| Leading Market Players |
|---|
| Kohler Co. |
| LIXIL Group |
| Masco Corporation |
| Jaquar Group |
| Huppe |
| Porcelanosa Group |
| Roca Sanitario |
| Villeroy & Boch |
| American Standard Brands |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific container freight corridors connecting Ho Chi Minh City to Hamburg and Los Angeles transmit aluminum price volatility directly into landed costs for European and North American distributors, compressing mid-tier margins while enabling premium frameless producers to sustain geographic price spreads through specification lock-in with luxury developers.
Pricing Analysis
Geographic price spreads between German precision-engineered frameless systems and Vietnamese-exported framed enclosures exceed three-to-one ratios at wholesale tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by glass thickness certification and hardware origin, with 10 mm tempered specifications commanding sustained premiums. Cost compression in semi-frameless segments intensifies because aluminum smelting energy costs feed directly into extruded framing quotations. Volume residential developers in India exhibit highest price sensitivity, while German luxury housing specifiers demonstrate lowest elasticity due to engineering-mandated performance standards.
Supply Chain Analysis
Tariff exposure between Vietnam and the European Union dominates strategic planning for export-oriented fabrication clusters serving continental supply chains. Manufacturing gravity centers on Vietnam, China, and Germany, with tempered glass tempering capacity concentrating in Ho Chi Minh City industrial zones and Bavarian hardware machining clusters. Raw material flows draw from Australian alumina, Chinese float glass, and German precision steel for hinge mechanisms. Single-source vulnerability in Vietnamese ceramics and glass fabrication creates inventory strand risk during regulatory certification delays. Distribution runs through project-direct fulfillment models for large-scale developers and specialized retail channels for renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shower cubicle markets sit in early-cycle expansion as barrier-free access mandates penetrate aged-care construction codes across Germany, Australia, and North American jurisdictions, accelerating specification velocity for walk-in formats beyond traditional replacement-cycle demand.
For Market Incumbents: Entrench specification control through captive BIM platform integration that compresses architect-to-install timelines, while securing backward integration into Vietnamese tempering capacity to defend against aluminum price volatility squeezing mid-tier competitors. Frameless glass technician scarcity threatens capacity expansion timelines; prioritize apprenticeship partnerships with Bavarian technical institutes. Certification investment across EPA WaterSense, EU Ecodesign, and India's BIS creates moats against dual-market producers facing stranded inventory risks. For New Entrants and Emerging Players: Pursue India's unmet housing stock through standardized framed enclosure systems optimized for BIS certification pathways, leveraging Gujarat and Maharashtra aluminum framing clusters for cost positioning. Australia's aged-care construction pipeline offers penetrable white space for walk-in format specialists who can navigate TGA-aligned state accessibility mandates. Digital specification platform partnerships with contractor procurement networks provide fastest go-to-market velocity against entrenched distributor relationships. For Investors and Strategic Acquirers: Specialized enclosure fabricators with regional channel dominance and captive tempering partnerships represent priority acquisition archetypes for portfolio exposure to renovation-cycle resilience. Long-term viability hinges on regulatory compliance scalability across multi-jurisdiction certification tracks rather than pure manufacturing scale. Monitor EU Ecodesign recyclability disclosure enforcement as inflection indicator for thermoset seal recovery system valuations and closed-loop material recovery premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tempering Capacity | Captive heat-treatment operations insulate margin compression from aluminum price volatility and technician scarcity. |
| BIM-Integrated Specification Platform Development | Digital procurement channels disintermediate traditional distributors and compress design-to-install timelines for architects. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA WaterSense, EU Ecodesign, and BIS alignment prevents inventory stranding in dual-market production. |
| Hydrophobic Nano-Coating Technology Licensing | Proprietary surface treatments capture hospitality specification preference and obsolete traditional chemical maintenance revenue models. |
| Closed-Loop Thermoset Recovery Partnership | EU Ecodesign recyclability validation secures specification preference from sustainability-focused hotel operators. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with shower enclosure procurement managers at German luxury developers, Australian aged-care facility operators, North American big-box retail category buyers, and Vietnamese plant operations directors; alongside secondary validation through customs trade databases, EPA WaterSense certification registries, EU Ecodesign disclosure filings, and BIS product certification listings. Bottom-up unit economics triangulated against top-down construction spending forecasts across residential renovation, hospitality, and health facility verticals.
Forecast inputs incorporated product-type segmentation across frameless, semi-frameless, framed, and bi-fold architectures; material-grade stratification by glass specification, aluminum sourcing, and composite formulation; and installation-type differentiation between alcove, corner, walk-in, and curved formats. CAGRs derived from regression analysis against housing stock replacement cycles, regulatory mandate implementation timelines, and fabrication capacity expansion announcements. Industry-specific inputs included tempered glass technician pipeline data and multi-jurisdiction certification processing duration estimates.
Macroeconomic conditions sit as an overlay; deviation in residential construction lending rates, aluminum LME pricing, and trans-Pacific freight indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and certification reciprocity agreements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
North America Traditional Toilet Seat Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Europe Steam Room Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Bath Fittings and Accessories Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market