
 Shower Tray Market | 2026-2036
Shower Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Shower Tray Market Analysis
Stone resin is expanding its share in premium shower tray construction as fabricators replace heavier cast-iron and solid ceramic bases with lighter, thermally stable composites. LIXIL Corp. leverages its integrated sanitaryware distribution to push stone resin formats across Asian and European retail channels. KALDEWEI sustains its position in steel enamel through captive German manufacturing and long-durability warranties. Duravit AG anchors its competitive stance with design-forward ceramic and acrylic lines that dominate specification in commercial hospitality projects.
A shower tray is a sloped, waterproof receptor installed beneath a shower enclosure to collect and drain wastewater, typically manufactured from acrylic, stone resin, ceramic, or fiberglass with specified load-bearing capacity and anti-slip surface treatment. Its primary purpose is to protect subfloor structures from moisture intrusion while providing safe, accessible showering in residential, commercial, and institutional buildings. Stone resin and acrylic materials command the widest margin pools due to their balance of moldability, weight reduction, and premium pricing power. Walk-in and low-threshold installation types are gaining fastest as accessibility codes tighten across developed markets, while rectangular shapes still occupy the largest volume share in new construction.
EU Ecodesign requirements and CE marking obligations under the Construction Products Regulation shape minimum performance thresholds for drainage efficiency and structural integrity in European markets. REACH compliance governs chemical content in resin formulations and surface coatings, raising reformulation costs for manufacturers serving multiple jurisdictions. WaterSense certification in the United States and parallel efficiency programs in Australia and Japan add layer complexity for exporters. Stakeholders must monitor evolving accessibility mandates and material disclosure rules to anticipate which tray formats will retain specification priority.
Market Dynamics
EU Ecodesign water-efficiency mandates are compressing tray profiles and forcing material substitutions across European supply chains, while residential renovation cycles in aging Western European housing stock pull demand toward accessible, low-threshold formats.
Growth Catalysts
- REACH compliance pressure:Chemical disclosure rules under ECHA oversight are accelerating reformulation toward low-VOC resin systems in stone resin manufacturing across Germany and France.
- Aging-in-place retrofit wave:Walk-in shower tray specifications are multiplying in residential renovation contracts as accessibility codes tighten in United Kingdom and Netherlands building regulations.
- Steel enamel durability positioning:Captive German manufacturing clusters are leveraging 30-year warranty terms to defend specification share in commercial hospitality projects against lighter composite alternatives.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and fiberglass resin formulations face margin compression from propylene and styrene price swings tied to European energy markets.
- Ceramic kiln capacity concentration:High-temperature firing infrastructure for ceramic trays clusters in Italian and Spanish production zones, creating geographic supply vulnerability.
- Cast iron displacement lag:Weight and thermal mass advantages of traditional cast iron retain specification in heritage building restoration, slowing composite penetration in conservation-sensitive segments.
Strategic Opportunities
- Modular bathroom pod integration:Offsite construction contractors in United Kingdom and Scandinavia are specifying pre-fitted stone resin trays for hotel and student housing rollouts.
- WaterSense export pathway:EPA certification alignment opens specification access in United States multifamily residential developments for European manufacturers with compliant low-flow drainage designs.
- Digital templating convergence:Laser measurement and CNC fabrication workflows are collapsing lead times for custom quadrant and offset tray geometries in high-end residential markets.
Industry Challenges
- Anti-slip certification timelines:DIN 51097 and EN 16165 testing protocols extend product launch cycles by 4-6 months for new surface texture introductions.
- Installation skill fragmentation:Wet-room waterproofing competence gaps among generalist contractors create callback liability for low-threshold tray systems in renovation channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shower Tray Market |
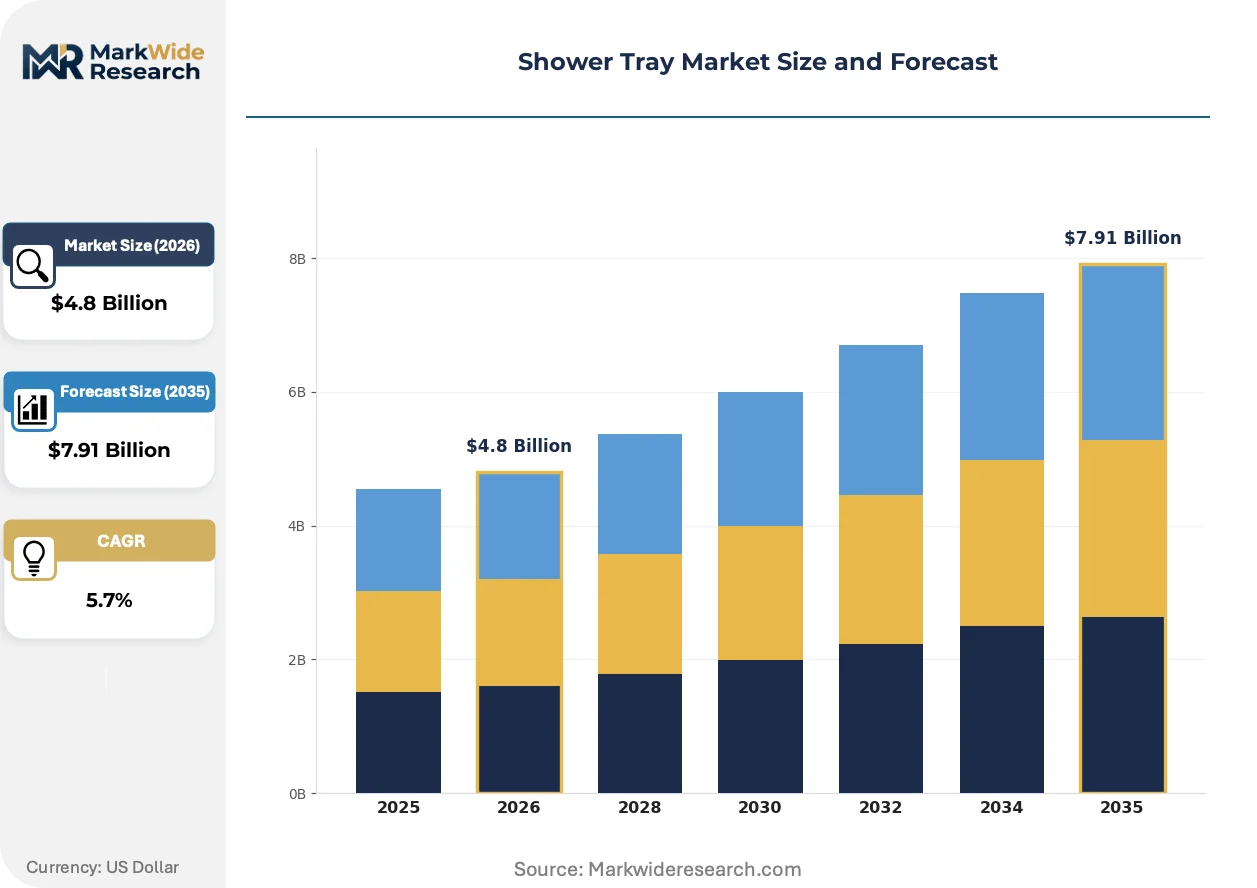
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Acrylic, Stone Resin, Ceramic, Fiberglass Shape: Rectangular, Quadrant, Square, Round Installation Type: Low Threshold, Walk-in, Surface-mounted, Recessed End User: Residential, Commercial, Hospitality, Healthcare |
| Companies Covered | LIXIL Corp., Porcelanosa Group, Duravit AG, Bette GmbH & Co. KG, KALDEWEI, Villeroy & Boch AG, Kohler Co., MX Group Ltd., Roca Sanitario SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shower Tray Market Emerging Trajectories
Material science advances and regulatory compression are converging to reshape tray construction, drainage integration, and procurement patterns across residential and commercial specification channels.
Stone resin composite formulation is modularizing tray architecture by enabling thinner wall sections without structural compromise. Hotel operators and multifamily developers in Germany and United Kingdom are specifying these profiles to reduce dead load in podium slab construction. The technology is modularizing supply chain relationships between fabricators and enclosure manufacturers, collapsing the traditional separation between tray production and shower system integration.
EU Ecodesign framework amendments are tightening minimum drainage efficiency thresholds for sanitaryware placed on the single market. Manufacturers serving France and Benelux markets are redesigning waste outlets and channel geometries to maintain flow rates under reduced water volume conditions. Low-profile tray formats with integrated linear drains are capturing specification priority in new-build residential towers where floor depth constraints intersect with efficiency mandates.
Specification authority is migrating from merchant distributors toward direct contractor relationships in renovation-heavy markets. Plumbing contractors in United Kingdom and Netherlands are bypassing traditional wholesale channels to source trays through manufacturer portals with digital templating support. This channel compression is most visible in metropolitan renovation corridors where project velocity rewards consolidated procurement and rapid lead time confirmation.
Shower Tray Market Segmentation
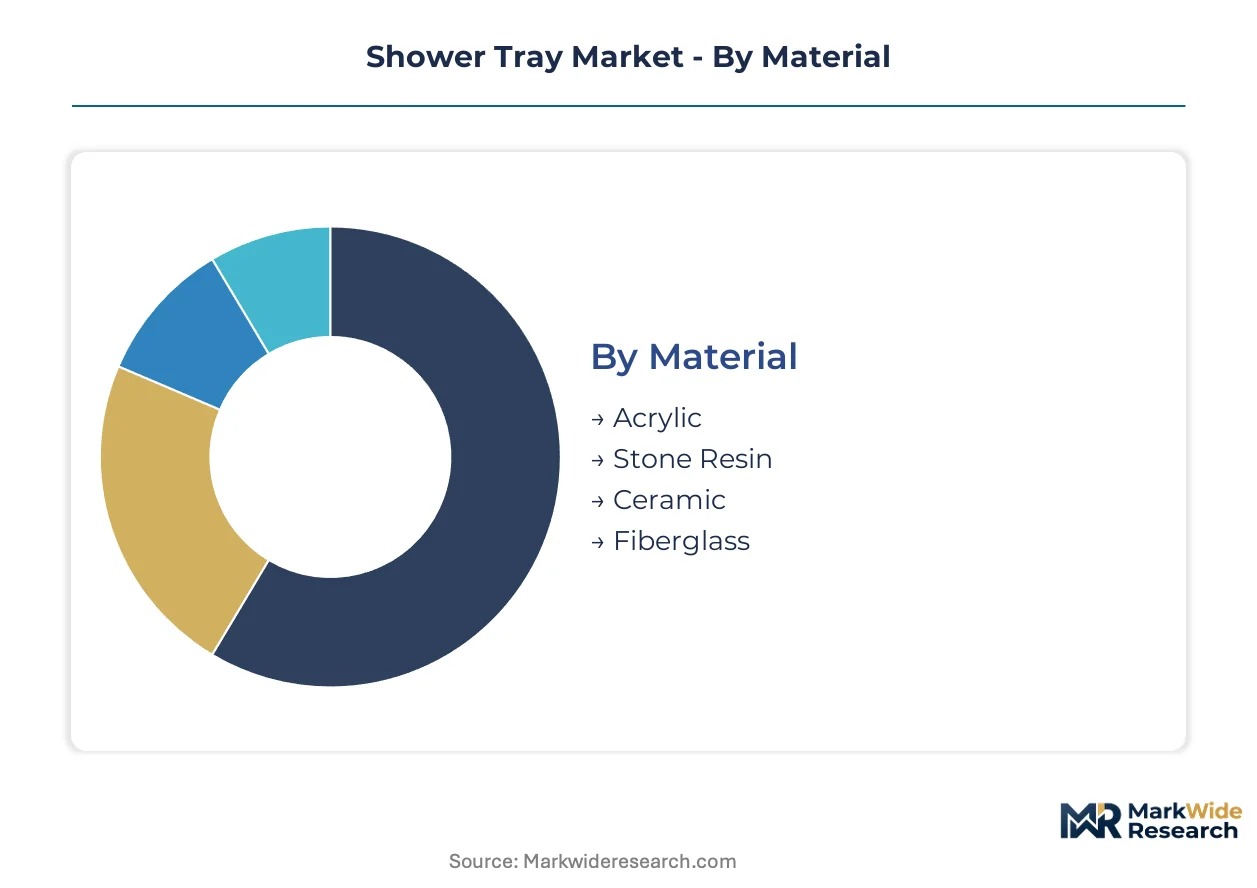
Material selection dictates load-bearing requirements and thermal performance, while installation geometry determines waterproofing complexity and accessibility compliance. Specification patterns diverge sharply between new construction, where rectangular formats dominate volume, and renovation channels, where walk-in configurations command premium positioning for aging-in-place retrofits.
Material:
Cost tier and weight-to-strength ratio drive procurement decisions across residential and commercial specification channels.
- Acrylic:Thermoformed polymer sheets reinforced with fiberglass backing deliver sub-15kg unit weights for single-installer handling. Demand concentrates in United Kingdom private rental sector retrofits where rapid turnaround favors lightweight, surface-mounted formats over structural subfloor modifications.
- Stone Resin:Mineral-filled polyester composites achieve stone-like thermal mass at 40% reduced weight versus cast ceramic. German and Dutch hotel operators specify these for podium slab construction where dead load restrictions intersect with premium finish requirements.
- Ceramic:High-temperature vitrified clay offers maximum scratch resistance and color stability for high-traffic commercial environments.
- Fiberglass:Gelcoat-surfaced reinforced plastic provides lowest unit cost for budget residential new-build specifications.
Stone resin leads on scale in commercial hospitality; acrylic leads on momentum in metropolitan renovation corridors.
Shape:
Floor plate geometry determines enclosure compatibility and waste routing efficiency in both wet-room and cubicle installations.
- Rectangular:Linear drainage channels integrate cleanly with 1200mm and 1400mm standard enclosure widths. United Kingdom volume housebuilders specify these for new-build apartments where standardized bathroom pods repeat across tower floors.
- Quadrant:Curved front edges maximize floor space in compact en-suite configurations common in London and Amsterdam micro-apartments. Digital templating services now collapse lead times for custom radius specifications in high-end residential markets.
- Square:Symmetrical waste positioning suits corner installation in conservation-area renovations where enclosure footprints face planning constraints.
- Round:Radial drainage geometry serves specialized wellness and spa applications requiring central waste aesthetics.
Rectangular formats dominate volume throughput; quadrant shapes gain share fastest in space-constrained urban retrofits.
Installation Type:
Threshold height determines accessibility compliance, waterproofing depth, and contractor skill requirements across project types.
- Low Threshold:20-35mm upstands balance water containment with step-free access for partial mobility users. Netherlands building regulations now mandate these for all publicly funded elderly housing renovations, pulling specification share from traditional raised-edge formats.
- Walk-in:Level-access designs with linear perimeter drains eliminate trip hazards entirely. United Kingdom disability facility grant programs are accelerating adoption in owner-occupied retrofit markets where occupants age in place.
- Surface-mounted:Raised profiles suit solid floor construction without wet-room tanking requirements.
- Recessed:Flush-fit formats integrate with screeded wet-room floors for seamless aesthetic continuity.
Surface-mounted trays retain largest installed base; walk-in configurations are expanding most quickly as accessibility codes tighten.
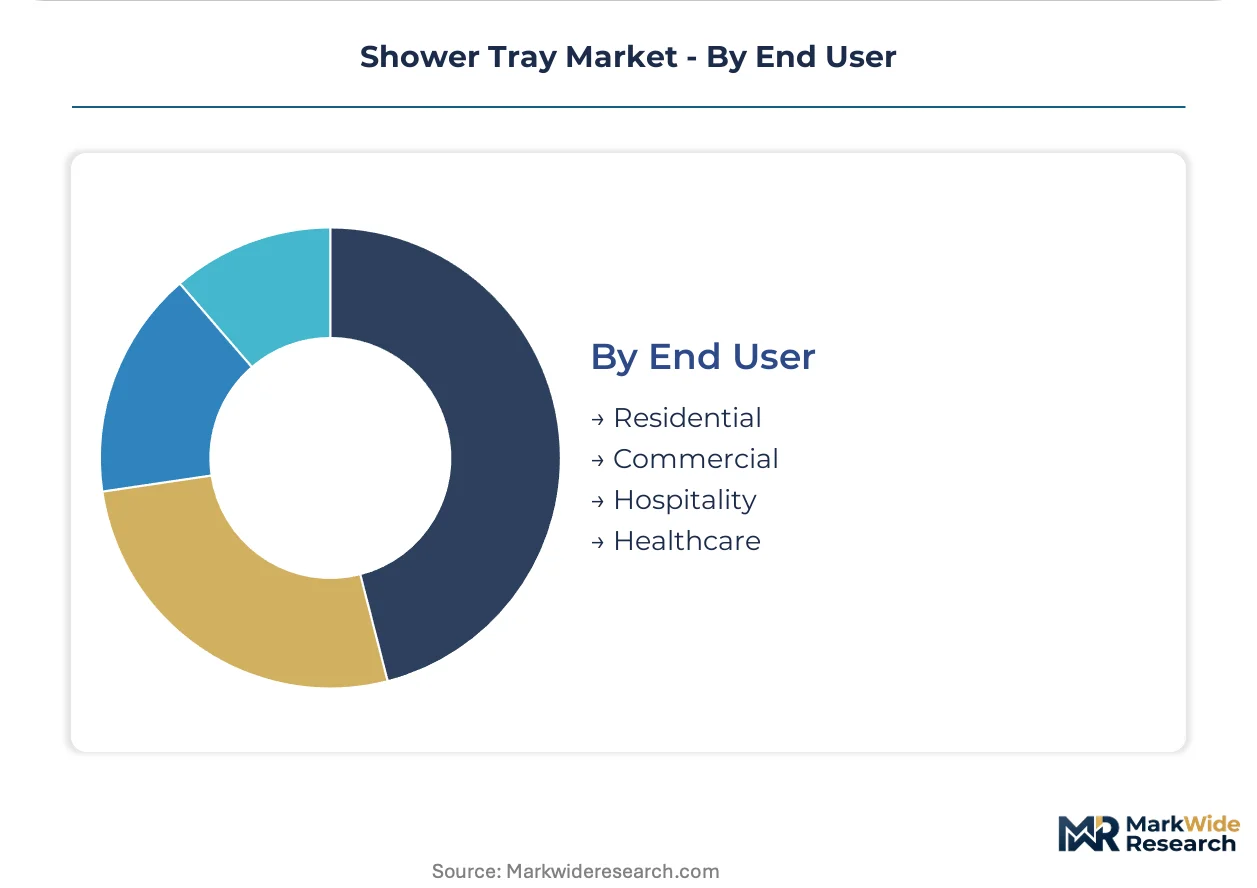
End User:
Performance durability requirements and procurement authority structures vary substantially across building use categories.
- Residential:Owner-occupier renovation decisions prioritize aesthetic customization and long-term durability warranties. German consumers demonstrate willingness to pay premium for 30-year guarantee terms on steel enamel and stone resin formats.
- Commercial:Facilities managers prioritize vandal resistance and rapid component replacement in high-traffic environments. United Kingdom student housing operators specify stone resin trays with replaceable waste gaskets to minimize maintenance downtime.
- Hospitality:Brand standards teams enforce consistent finish quality across property portfolios with accelerated refurbishment cycles.
- Healthcare:Infection control protocols specify seamless, non-porous surfaces with coved corners for clinical hygiene compliance.
Residential channels generate highest unit volume; hospitality and healthcare segments sustain steepest expansion trajectory through specification premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia's steel enamel manufacturing corridor anchors European shower tray production capacity. German fabricators supply premium formats across Western European renovation markets. Asian manufacturing clusters in Japan and China feed regional demand through distinct material specializations.
Germany
Steel enamel and stone resin production concentrates in North Rhine-Westphalia and Bavaria, serving hotel and multifamily specification channels. REACH compliance under ECHA oversight drives reformulation of resin systems toward low-VOC alternatives. KALDEWEI's captive manufacturing in Ahlen anchors steel enamel supply chains for 30-year warranty commercial projects.
United Kingdom
Metropolitan renovation corridors in London and Manchester pull demand toward walk-in and low-threshold accessible formats. Building regulations tightening accessibility mandates accelerate specification of level-access tray systems in publicly funded elderly housing. Plumbing contractors bypass traditional wholesale channels through direct manufacturer portals with digital templating support.
Netherlands
Space-constrained urban housing in Amsterdam and Rotterdam drives quadrant and compact rectangular format adoption. National building codes now mandate low-threshold installations for all publicly funded accessibility retrofits. Stone resin fabrication serves podium slab construction in high-density residential towers where dead load restrictions intersect with premium finish requirements.
Japan
Integrated bathroom pod manufacturers in the Kanto region specify lightweight acrylic and stone resin trays for prefabricated wet-room units. METI efficiency guidelines shape drainage system designs for reduced water volume operation. LIXIL Corp. leverages domestic distribution networks to supply composite formats across Asian hospitality and residential channels.
United States
Multifamily residential developers in Texas and Florida specify WaterSense-certified low-flow drainage designs for new construction volume. EPA certification alignment opens specification access for European manufacturers with compliant tray geometries. Surface-mounted formats dominate private rental sector retrofits where rapid turnaround favors minimal subfloor modification.
Shower Tray Market Vendor Landscape
Global majors compete with regional champions across material technology and distribution reach. The vendor base stratifies into three tiers: integrated sanitaryware conglomerates with captive tray production, specialized metal and composite fabricators, and regional acrylic thermoformers serving renovation contractors. Consolidation pressure concentrates in premium stone resin and steel enamel segments where warranty terms and specification relationships create defensive moats. Competitive moves center on backward integration into mineral supply chains and direct-to-contractor digital channel compression.
Within the integrated sanitaryware tier, LIXIL Corp. and Duravit AG exemplify conglomerate positioning across material categories. Among specialized German fabricators, KALDEWEI anchors steel enamel production through captive North Rhine-Westphalia manufacturing. These three occupy distinct competitive spaces: LIXIL leverages Asian and European retail channel integration, Duravit emphasizes design-forward specification in commercial hospitality, and KALDEWEI defends position through durability warranties and heritage manufacturing concentration.
| Leading Market Players |
|---|
| LIXIL Corp. |
| Porcelanosa Group |
| Duravit AG |
| Bette GmbH & Co. KG |
| KALDEWEI |
| Villeroy & Boch AG |
| Kohler Co. |
| MX Group Ltd. |
| Roca Sanitario SA |
| Others |
Supply Flow & Price Mechanics
EU Ecodesign water-efficiency mandates gate qualified supply and premium-tier pricing access by requiring reformulated resin systems and validated drainage geometries. Manufacturers achieving compliance capture specification priority in publicly funded renovation channels across Germany and the Netherlands, while non-compliant fabricators face relegation to price-sensitive private rental retrofits.
Pricing Analysis
Petrochemical feedstock volatility drives input-cost pass-through into acrylic and fiberglass tray tiers. Pricing stratifies across premium stone resin, standard ceramic, and economy fiberglass tiers based on thermal performance certification and warranty duration. Cost compression in acrylic formulations is intensifying because propylene and styrene price swings tied to European energy markets erode fabricator margins. Volume housebuilders in the United Kingdom exhibit highest price sensitivity, while German hotel operators demonstrate lowest sensitivity due to lifecycle cost accounting.
Supply Chain Analysis
Specialized mold-making and gelcoat finishing skills concentrate in North Rhine-Westphalia and Bavaria manufacturing corridors. Supply draws from mineral-filled polyester resin feedstocks sourced from German and Benelux chemical producers, reinforced glass fiber from Czech and Polish suppliers, and steel sheet from ThyssenKrupp captive mills. Single-source vulnerability exists in high-temperature ceramic kiln infrastructure clustering in Italian and Spanish production zones. Distribution runs through merchant plumbing distributors, though direct manufacturer portals are compressing channel layers in metropolitan renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shower tray market compounds steadily as aging-in-place retrofit mandates across Western European building codes sustain replacement demand regardless of new construction cyclicality.
For Market Incumbents: Deploy extended warranty terms as a defensive lever against lightweight composite substitutes. KALDEWEI's 30-year steel enamel guarantee exemplifies this approach. Incumbents should anchor specification relationships with facilities managers in hospitality portfolios while accelerating backward integration into mineral supply chains to hedge resin formulation cost volatility. For New Entrants and Emerging Players: Capture specification share in modular bathroom pod integration for United Kingdom and Scandinavian offsite construction contractors. The penetrable white space sits in digital templating services for custom quadrant geometries in high-end residential markets. A direct-to-contractor portal with laser measurement support collapses lead times and bypasses entrenched wholesale relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional stone resin fabricators because specification authority is fragmenting toward direct contractor relationships and warranty terms create defensive moats. Target mid-cap specialists with captive North Rhine-Westphalia or Bavaria manufacturing and established CE marking dossiers. Watch anti-slip certification timelines as the signal indicating which surface texture innovations will retain specification priority.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | ECHA oversight accelerates low-VOC stone resin adoption across German and French supply chains. |
| Digital Templating Service Launch | Laser measurement workflows collapse lead times for custom quadrant specifications in London and Amsterdam. |
| Direct-to-Contractor Portal Expansion | United Kingdom plumbing contractors bypass wholesale channels for consolidated procurement and rapid confirmation. |
| Modular Pod Integration Partnership | Offsite construction contractors in Scandinavia specify pre-fitted trays for hotel and student housing rollouts. |
| WaterSense Certification Alignment | EPA compliance opens specification access in Texas and Florida multifamily residential developments. |
Methodological Framework
Direct dialogue with shower tray manufacturing executives, plumbing contractor procurement leads, facilities managers in hospitality portfolios, and merchant distribution category buyers grounded this analysis. Secondary validation drew from EU Construction Products Regulation filings, ECHA REACH registration databases, United Kingdom building control approval records, and customs trade data for resin and mineral filler imports. Bottom-up volume modeling triangulated against top-down construction spend forecasts across residential renovation and new-build channels.
Top-down macroeconomic drivers and bottom-up segment-level volume builds converged across the analysis window. Segmentation dimensions modeled include material technology, installation geometry, threshold height configuration, and end-use building category. CAGRs derived from fitted growth curves applied to renovation cycle timing and regulatory mandate implementation schedules. Forecast inputs incorporated EU Ecodesign amendment timelines and accessibility code adoption patterns in Netherlands and United Kingdom jurisdictions.
Petrochemical price volatility, ceramic kiln capacity disruption, and accessibility mandate enforcement variance are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding renovation spending persistence and regulatory compliance cost pass-through. Material deviation in feedstock pricing or kiln infrastructure availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Bathroom Sink Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Bathroom Furniture Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market