
 Ceramic Wash Basin Market | 2026-2036
Ceramic Wash Basin Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Wash Basin Market Outlook
Modular vanity-basin bundling is repositioning buyer choice away from standalone fixtures toward integrated bathroom systems. LIXIL Corporation leverages its global distribution network to anchor premium bundled offerings across Asia-Pacific markets. Villeroy & Boch AG sustains its historic craftsmanship positioning while competing on design-led modular collections. Kohler Co. dominates North American specification channels through in-house production of complementary faucets, mirrors, and storage units.
A ceramic wash basin is a vitreous china fixture formed from kaolin, feldspar, and quartz, fired above 1200°C to achieve non-porous, stain-resistant surfaces designed for hand-washing, grooming, and hygiene applications in residential and commercial wet spaces. Wall-mounted basins lead in dense urban residential retrofit projects where floor space commands premium value, while vessel configurations capture margin pools in hospitality and luxury residential segments where design differentiation drives specification. Freestanding pedestal units retain steady demand in heritage property restoration and traditional design-style applications across European markets.
The EPA WaterSense program in the United States, the EU Ecodesign Directive, and India's BIS certification requirements for sanitaryware collectively enforce flow-rate limits, material safety standards, and manufacturing energy benchmarks that determine market access. Compliance with these frameworks now functions as a baseline qualifier rather than a differentiator, compressing margins for non-certified imports while rewarding domestic manufacturers with established testing relationships. Stakeholders must monitor evolving water-efficiency thresholds and carbon-border adjustment mechanisms to anticipate which production locations and product configurations retain cost-competitive access to priority markets.
Market Dynamics
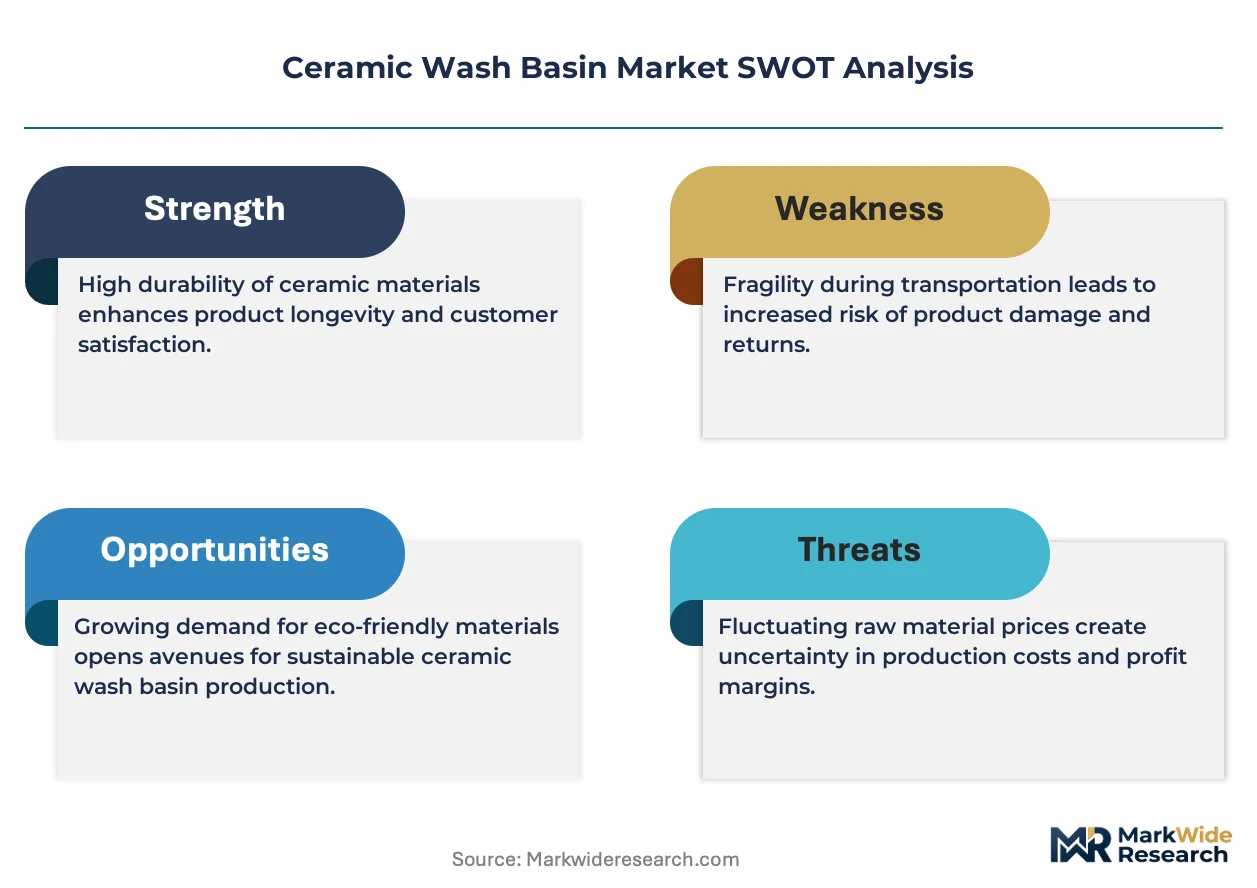
Water-efficiency mandates from the EPA, EU Ecodesign Directive, and India's BIS certification are compressing margins for non-compliant imports while rewarding domestic manufacturers with established testing relationships. These frameworks now function as baseline market access qualifiers rather than differentiators.
Growth Catalysts
- Urban housing stock expansion:India's metropolitan clusters are driving demand for wall-mounted basins in high-density residential towers where floor space commands premium value.
- WaterSense compliance:The EPA program in the United States enforces flow-rate limits that favor advanced ceramic firing technologies capable of integrating low-consumption outlet designs.
- Hospitality infrastructure investment:Southeast Asian resort and business hotel construction is pulling vessel basin specifications for design differentiation in guest bathrooms.
Market Restraints
- Kaolin supply concentration:Premium-grade ceramic clay deposits cluster in specific extraction zones, exposing manufacturers to input cost volatility and freight surcharge exposure.
- Carbon-border adjustment mechanisms:Emerging EU trade instruments threaten cost-competitive access for manufacturers in high-emission production locations without verified Scope 3 documentation.
- Engineered stone substitution:Solid surface and quartz composite materials are capturing specification share in premium residential segments where seamless integration with countertops drives buyer preference.
Strategic Opportunities
- Smart fixture convergence:Ceramic basins are integrating sensor-activated faucets and occupancy-based water management systems for commercial restroom specifications.
- Heritage restoration demand:European conservation frameworks are sustaining specification volumes for freestanding pedestal units in protected building renovations.
- Direct-to-developer channels:Large-scale residential project developers in Vietnam and Indonesia are bypassing traditional wholesale distribution for factory-direct procurement of standardized vanity-basin bundles.
Industry Challenges
- Glaze chemistry specialization:Formulating stain-resistant, non-porous vitreous surfaces requires skilled ceramic engineers, creating talent scarcity in emerging manufacturing locations.
- Multi-jurisdiction certification timelines:Simultaneous compliance with EPA WaterSense, EU CE marking, and India's BIS testing protocols extends product launch cycles and strains quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Wash Basin Market |
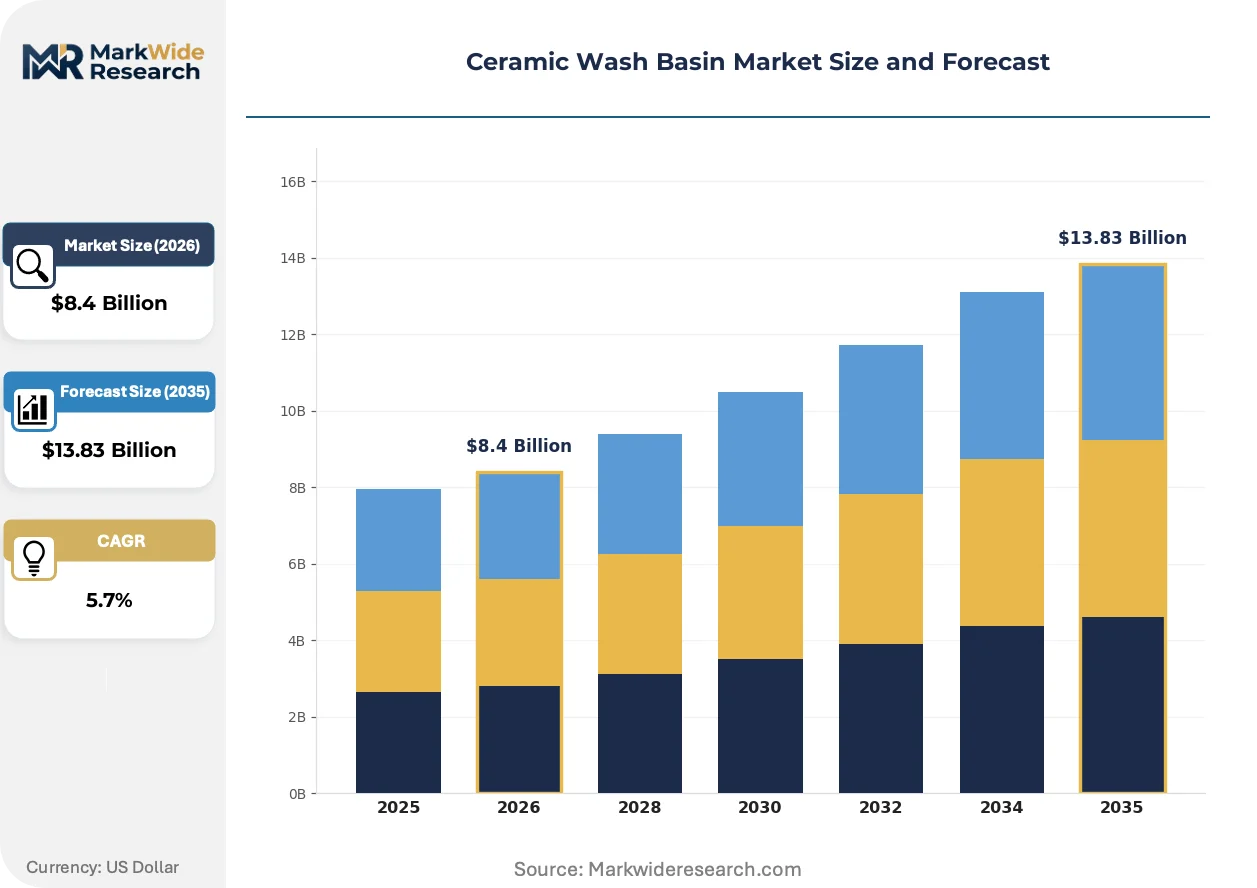
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Wall-Mounted, Vessel, Pedestal Application: Residential, Commercial, Hospitality, Healthcare Design Style: Modern, Traditional, Vintage, Minimalist Size: Small, Medium, Large, Extra Large |
| Companies Covered | LIXIL Corporation, Villeroy & Boch AG, Kohler Co., American Standard, Duravit AG, TOTO Ltd., Geberit AG, SUNREX, Roca Sanitario, S.A.U., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Wash Basin Market Strategic Shifts
Digital firing control and additive manufacturing methods are reshaping how ceramic sanitaryware achieves dimensional precision and surface consistency. These process innovations are compressing traditional craftsmanship timelines while enabling mass customization.
Nano-ceramic glaze technology is integrating antimicrobial silver-ion compounds and hydrophobic surface treatments that reduce bacterial adhesion and water spotting. Hospitality operators in Singapore and Dubai are specifying these surfaces for high-traffic restroom environments where hygiene visibility influences guest perception. The technology is integrating previously separate cleaning and maintenance cost lines into the initial fixture specification decision.
The EU Ecodesign Directive's expanding scope into sanitaryware energy and water performance is forcing retooling of traditional tunnel kiln operations. Manufacturers serving European specification channels are investing in recuperative firing systems to meet carbon intensity benchmarks. German and Italian producers with existing renewable energy procurement contracts are capturing specification share from competitors dependent on grid-mixed power.
Specifiers in luxury residential and boutique hospitality segments are demanding vessel basin configurations as standalone sculptural elements rather than integrated countertop solutions. This preference rotation is fragmenting procurement patterns between project-based bulk orders and single-unit designer channel fulfillment. The shift is most visible in Mumbai and Bangkok where interior design studios increasingly source directly from artisan ceramic ateliers for signature installations.
Ceramic Wash Basin Market Segmentation
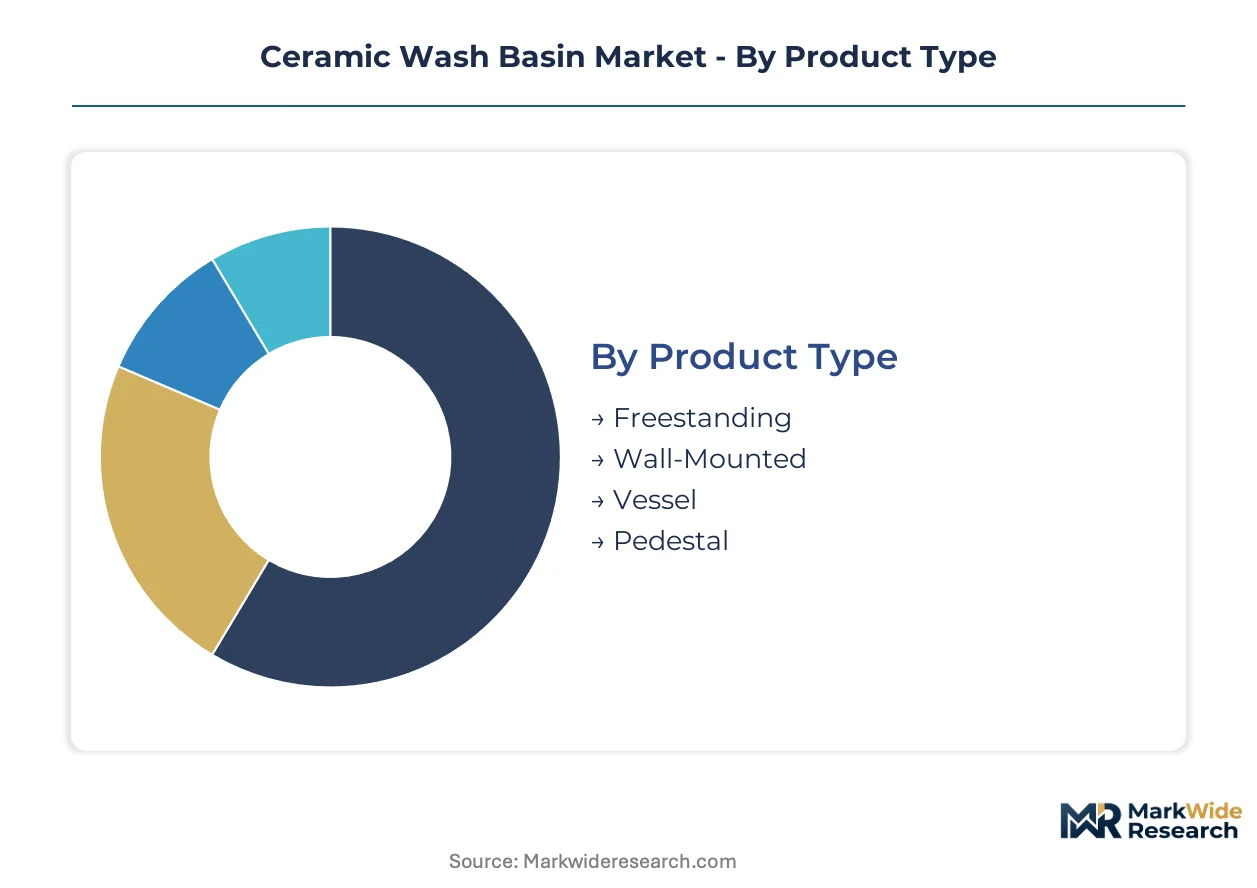
Ceramic wash basin segmentation tracks how fixture configuration, installation context, and dimensional requirements split procurement patterns across project types. Specification channels diverge sharply between bulk residential developers and boutique hospitality designers.
Product Type:
Wall-mounted and vessel configurations anchor the specification axis, with mounting geometry determining floor space economics and visual impact.
- Wall-Mounted:Ceramic basins affixed directly to vertical surfaces with concealed or exposed carriers, eliminating pedestal footprint. Demand clusters in Mumbai and Bangkok high-density residential towers where developers maximize leasable floor area per unit.
- Vessel:Above-counter bowl forms requiring countertop support, fired with thicker walls to withstand thermal shock from direct water exposure. Hospitality operators in Singapore and Dubai specify these for guest bathroom differentiation where design visibility drives booking premiums.
- Freestanding:Self-supporting monolithic forms with integrated pedestals or sculptural bases.
- Pedestal:Two-piece assemblies combining basin bowl with vertical support column, retaining specification in heritage property restorations.
Mature deployment sits with pedestal units in European conservation projects. Newer deployment is concentrated in wall-mounted configurations across Southeast Asian urban housing stock.
Application:
End-use context governs durability specifications, with traffic intensity and maintenance protocols shaping glaze chemistry and mounting hardware selection.
- Residential:Single-family and multi-unit housing installations where fixture replacement cycles align with renovation timelines. India's metropolitan clusters drive volume through standardized vanity-basin bundles in greenfield tower construction.
- Hospitality:Hotels, resorts, and serviced apartments requiring rapid-turnover durability and visual distinction. Vessel configurations dominate boutique segments where Instagram-ready bathrooms influence brand positioning.
- Commercial:Office buildings, retail spaces, and institutional restrooms with high-frequency usage patterns.
- Healthcare:Hospitals and clinics demanding antimicrobial surfaces and seamless cleaning geometries.
Volume concentration rests with residential channels. Margin expansion is climbing the fastest in hospitality specification pools.
Design Style:
Aesthetic positioning separates mass-market standardization from designer-channel premium capture, with regional taste fragmentation preventing global style dominance.
- Modern:Clean lines, thin rims, and matte or satin glaze finishes. German and Italian manufacturers anchor this segment through design-house collaborations.
- Traditional:Ornate detailing, rolled edges, and heritage color palettes. UK and French markets sustain demand through protected building renovation frameworks.
- Vintage:Reproduction forms referencing early 20th-century sanitaryware aesthetics.
- Minimalist:Extreme simplification with concealed overflow channels and integrated drain covers.
Production scale favors modern styling. Artisan capacity constraints are limiting vintage segment expansion.
Size:
Dimensional bands correlate directly with installation context and user demographics, with compact formats commanding premium pricing per square centimeter of basin area.
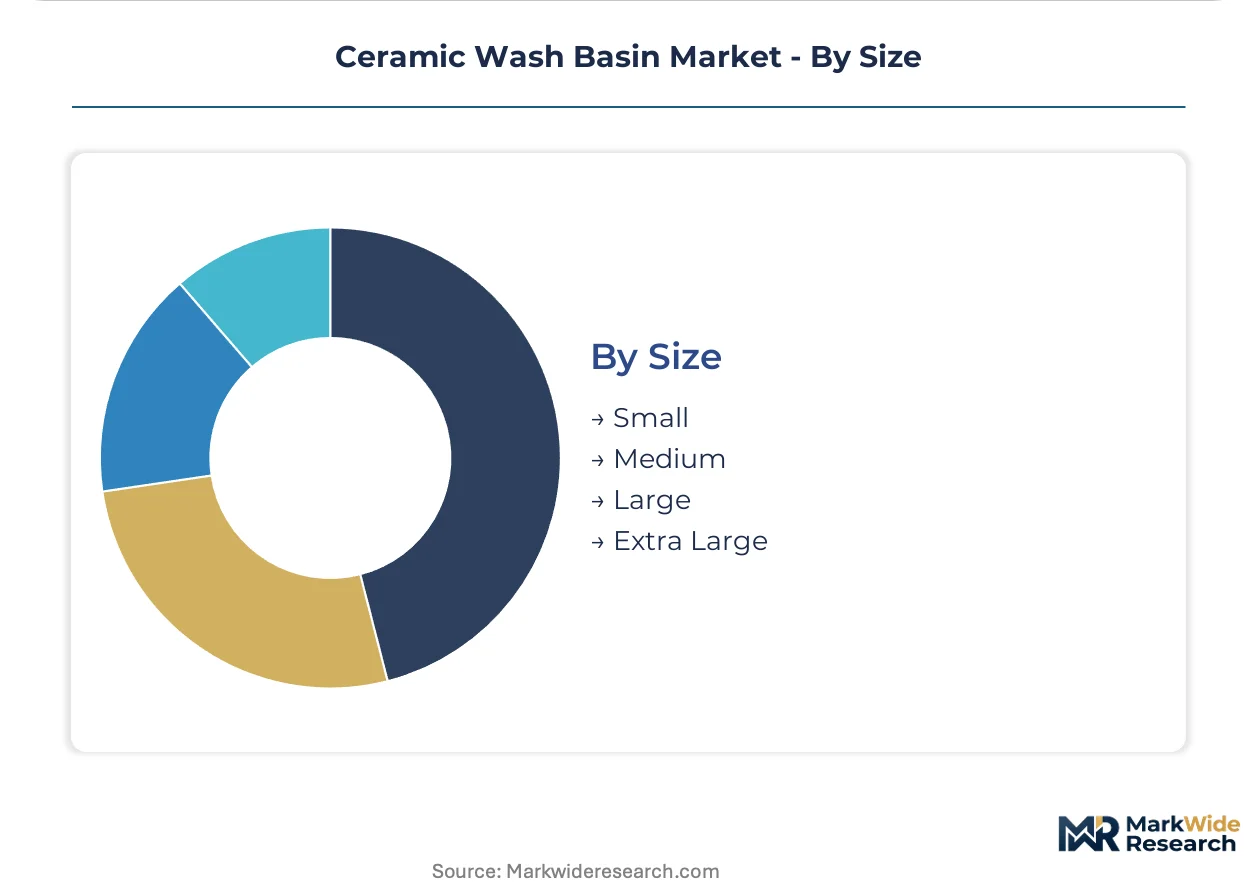
- Small:Under 450mm width, specified for powder rooms and secondary bathrooms where space constraints override functionality. Japanese compact housing and European city-center apartments drive specification.
- Medium:450-600mm width, the default specification band for standard residential bathrooms across most markets.
- Large:600-750mm width, common in master ensuite configurations and hospitality suites.
- Extra Large:Exceeding 750mm width, typically vessel or countertop-integrated forms for luxury residential and spa hospitality.
Standard procurement concentrates in medium dimensions. Specification diversity is expanding most quickly at the small and extra-large extremes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor and industrial corridor incentives are concentrating ceramic sanitaryware manufacturing in Gujarat and Rajasthan extraction zones near premium kaolin deposits.
United States
Residential retrofit demand in Sun Belt metros drives wall-mounted basin specifications for aging-in-place bathroom renovations. EPA WaterSense flow-rate mandates now disqualify non-certified imports from federal procurement channels. Dallas-Fort Worth distribution clusters service multi-family developers with standardized vanity-basin bundles.
Germany
Heritage property restoration in Berlin and Hamburg sustains pedestal basin specifications under Denkmalschutz conservation frameworks. EU Ecodesign Directive carbon intensity benchmarks favor manufacturers with renewable energy procurement contracts. North Rhine-Westphalia firing facilities are retooling tunnel kilns for recuperative heat recovery.
India
Metropolitan housing stock expansion in Mumbai and Bangalore pulls wall-mounted configurations for high-density tower construction. BIS certification requirements for sanitaryware enforce material safety and manufacturing energy benchmarks. Morbi industrial cluster in Gujarat anchors domestic production capacity with integrated glaze chemistry laboratories.
Japan
Compact housing formats in Tokyo and Osaka drive small-dimension basin specifications under 450mm width. METI energy efficiency standards for building materials shape ceramic firing technology investments. Seto ceramic production district in Aichi Prefecture maintains specialized vitreous china craftsmanship capacity.
United Arab Emirates
Hospitality infrastructure investment in Dubai and Abu Dhabi specifies vessel basin configurations for luxury guest bathroom differentiation. MOHAP building material safety regulations align with Gulf standardization protocols for imported sanitaryware. Jebel Ali free zone concentration enables re-export distribution to Saudi and Qatar project markets.
Ceramic Wash Basin Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered specification channels. The vendor base clusters around three strategic archetypes: integrated bathroom system providers, design-led premium specialists, and scale-driven standard product fabricators. Dominant competitive moves include backward integration into complementary faucet and mirror production, plus direct-to-developer channel bypass of traditional wholesale distribution.
Among Asia-Pacific integrated system providers, LIXIL Corporation and TOTO Ltd. exemplify the conglomerate archetype with captive distribution networks spanning multiple fixture categories. Villeroy & Boch AG and Duravit AG represent European design-specialist positioning within heritage craftsmanship segments. Kohler Co. anchors North American specification channels through in-house production of complementary bathroom components.
| Leading Market Players |
|---|
| LIXIL Corporation |
| Villeroy & Boch AG |
| Kohler Co. |
| American Standard |
| Duravit AG |
| TOTO Ltd. |
| Geberit AG |
| SUNREX |
| Roca Sanitario, S.A.U. |
| Others |
Value Chain & Pricing Dynamics
Large-scale residential developers in Vietnam and Indonesia anchor procurement volumes through factory-direct vanity-basin bundles, compressing wholesale margins while elevating price transparency across standardized product tiers.
Pricing Analysis
Short lead-time premiums command substantial markups in hospitality project channels where construction schedules tolerate no slip. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and glaze chemistry sophistication. Price erosion runs through economy tiers as Morbi cluster manufacturers expand firing capacity. Boutique hospitality specifiers show lowest price sensitivity, prioritizing design differentiation and antimicrobial surface integration.
Supply Chain Analysis
Regional distribution centers in Jebel Ali, Dallas-Fort Worth, and Rotterdam anchor hub-and-spoke fulfillment patterns for project-based procurement. Manufacturing concentrates in India, Germany, and Japan near premium kaolin deposits and specialized vitreous china craftsmanship zones. Raw material inputs draw from feldspar quarries in Rajasthan, quartz processors in Gujarat, and imported glaze compounds from Italian specialty chemical suppliers. Single-source vulnerability sits with premium-grade kaolin extraction zones concentrated in specific Indian districts. Distribution runs through developer-direct channels bypassing traditional wholesale tiers in Southeast Asian growth markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kaolin deposit access constraints and specialized glaze chemistry talent scarcity prop pricing power for incumbent manufacturers with captive raw material relationships.
For Market Incumbents: Deploy backward integration into complementary faucet and mirror production to defend specification channel control against modular system competitors. Invest in recuperative kiln retooling ahead of EU carbon-border adjustment enforcement. Counter engineered stone substitution threats through nano-ceramic antimicrobial surface differentiation. For New Entrants and Emerging Players: Enter via direct-to-developer channels in Indonesian and Vietnamese residential tower markets where traditional distribution relationships remain underdeveloped. Target heritage restoration segments in European conservation frameworks where artisan capacity constraints limit incumbent supply response. Pursue factory-direct vanity-basin bundling as the primary go-to-market mechanism. For Investors and Strategic Acquirers: The window for entry favors ceramic sanitaryware specialists with established BIS, EPA WaterSense, and EU CE marking certification relationships. Long-term viability hinges on securing kaolin supply agreements and glaze chemistry engineering talent pools. Monitor EU carbon-border adjustment implementation timelines as the critical inflection signal for production location competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Complementary Fixtures | Kohler and LIXIL capture specification control through captive faucet and mirror production. |
| Recuperative Kiln Technology Deployment | German and Italian manufacturers meet EU Ecodesign carbon intensity benchmarks through heat recovery systems. |
| Nano-Ceramic Antimicrobial Surface Development | Singapore and Dubai hospitality operators specify silver-ion glaze treatments for hygiene visibility. |
| Direct-to-Developer Channel Establishment | Vietnam and Indonesia project developers bypass wholesale tiers for standardized vanity-basin bundles. |
| Heritage Conservation Framework Certification | UK and French restoration projects sustain demand for freestanding pedestal units under Denkmalschutz-type protections. |
Study Parameters
Document review covered customs trade databases, sanitaryware industry association publications, and regulatory filing repositories, complemented by interviews with plant managers at Morbi cluster firing facilities, procurement leads at Southeast Asian hospitality developers, ceramic glaze chemistry specialists, and distribution channel partners across European specification markets. Secondary validation drew from BIS certification registries, EPA WaterSense product listings, EU Ecodesign implementing measure documentation, and trade flow records from Indian export promotion databases. Bottom-up volume estimates triangulated against top-down market sizing from construction activity indices and housing stock expansion projections.
Historical shipment patterns cross-referenced against expert panel input on technology adoption trajectories and regulatory enforcement timelines. Segmentation modeling tracked product configuration, installation context, application type, and regional regulatory cluster across the projection horizon. CAGRs derived from curve-fitting approaches applied to construction spending correlations and fixture replacement cycle analysis. Industry-specific forecast inputs incorporated kaolin price volatility indices and hospitality infrastructure investment pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon-border adjustment acceleration or engineered stone substitution breakthrough scenarios. Outputs reflect documented assumptions on regulatory enforcement intensity and raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Water Sink Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Malaysia Sanitaryware Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
US Smart Kitchen and Bathroom Products Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Global Shower Enclosure and Cubicles Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
United States Bath Fitting Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Asia Pacific Bath Fitting Market