
 Water Sink Market | 2026-2036
Water Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Water Sink Market Analysis
Chinese stainless steel foundries are expanding sheet-metal capacity for basin fabrication, which is broadening raw material availability for Asian manufacturers. Franke leverages captive steel processing in Switzerland to sustain margin control across European distribution. Kohler anchors North American demand through dedicated showrooms and builder-channel relationships. Blanco competes in the premium composite segment with German-engineered Silgranit formulations.
A water sink is a plumbed basin fixture, typically fabricated from stamped stainless steel, vitreous porcelain, or engineered composite resins, designed to receive water discharge for washing, food preparation, or sanitation tasks in built environments. Wall thickness, bowl depth, and drain diameter vary by application code and usage intensity. Undermount and vessel configurations now command premium positioning in residential renovations, while drop-in stainless steel dominates commercial kitchen specification for durability and replacement ease. The hospitality end-user segment favors integrated installations that streamline bathroom vanity fabrication and reduce on-site labor.
The EPA WaterSense program and California Title 20 establish maximum flow-rate thresholds that constrain faucet pairing and influence sink bowl geometry for compliance. The EU Ecodesign Directive and REACH substance restrictions govern material composition and end-of-life recyclability for European-market products. ASTM International and CSA Group maintain dimensional and performance standards that shape product testing protocols and cross-border certification costs. Stakeholders must track evolving municipal water-efficiency ordinances and material disclosure requirements to anticipate specification shifts before they harden into procurement mandates.
Market Dynamics
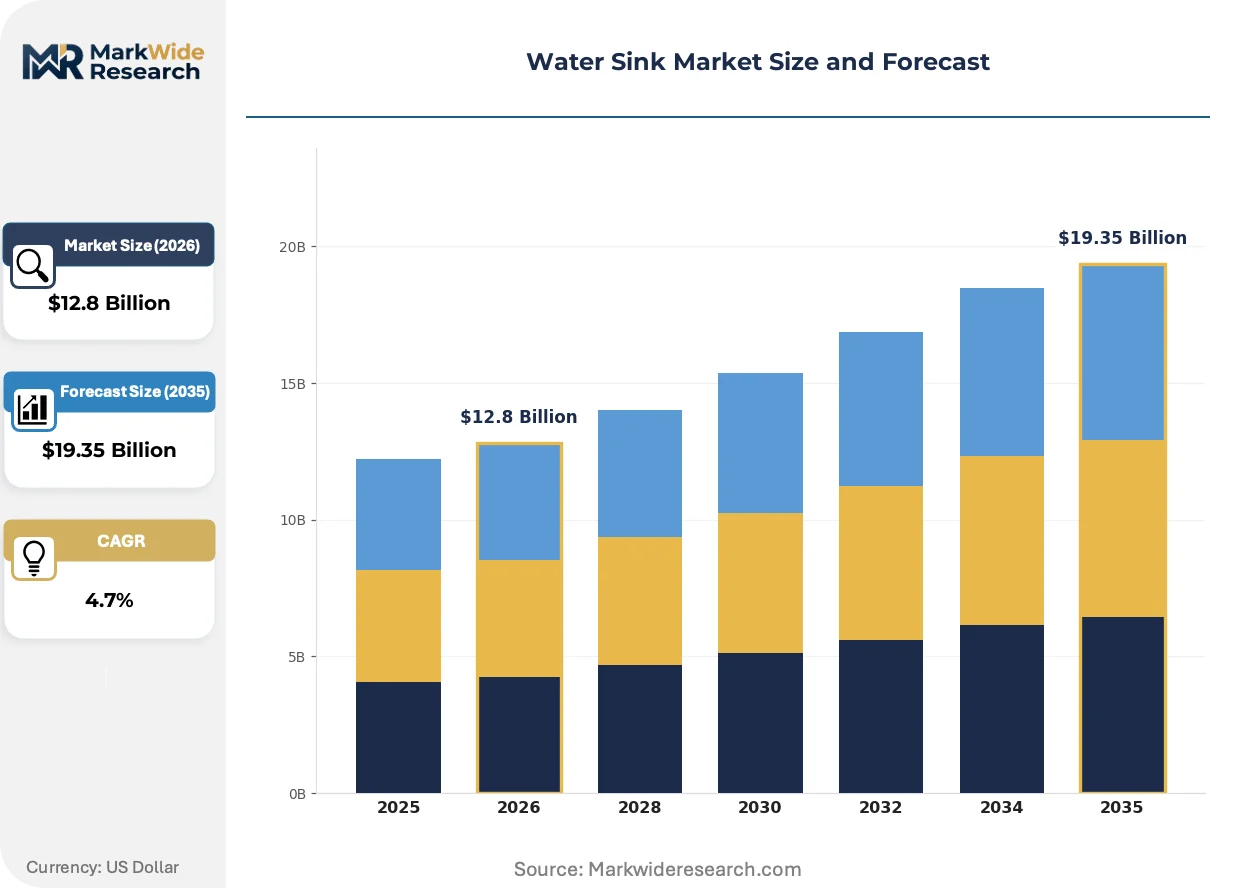
Residential kitchen renovation cycles in suburban North America are compressing replacement timelines, pulling forward demand that previously stretched across decades. This demand acceleration is colliding with tightening EPA WaterSense flow-rate mandates, forcing simultaneous bowl geometry and faucet pairing redesigns.
Growth Catalysts
- WaterSense Certification Thresholds:EPA tightening of maximum flow-rate standards is compelling fixture redesigns that favor deeper bowl geometries and integrated drain systems, stimulating replacement demand across existing housing stock.
- China Tier-One Urbanization:High-rise residential construction in Shanghai, Beijing, and Shenzhen is accelerating sink replacement cycles as developer specifications prioritize standardized, easily serviceable basin formats.
- Silgranit Composite Formulations:German-engineered resin technologies are expanding the addressable premium segment by offering scratch-resistant, color-stable alternatives to traditional stainless steel and porcelain.
Market Restraints
- Nickel Price Volatility:Stainless steel sheet production depends on nickel alloy inputs whose price swings compress fabricator margins and destabilize long-term supply contracts with residential builders.
- European REACH Compliance Costs:Substance disclosure and end-of-life recyclability documentation requirements add certification overhead that disadvantages smaller basin manufacturers without dedicated compliance staff.
- Cast Iron Substitution in Commercial Specs:Heavy-duty institutional kitchens in hospitality and healthcare are reverting to enameled cast iron for extreme durability, limiting stainless steel penetration in high-wear segments.
Strategic Opportunities
- India Urban Housing Expansion:Government affordable housing schemes in Mumbai, Delhi, and Bangalore are creating volume demand for standardized, cost-optimized drop-in configurations previously underpenetrated in South Asian markets.
- Integrated Vanity Fabrication:Hospitality end-users are specifying pre-fabricated sink-countertop assemblies that reduce on-site labor and installation variance, opening contract manufacturing relationships with bathroom furniture producers.
- California Title 20 Expansion:State-level water-efficiency ordinances are spreading to adjacent jurisdictions, creating regulatory tailwinds for low-flow-compatible basin designs that exceed federal minimums.
Industry Challenges
- Cross-Border Certification Fragmentation:ASTM dimensional standards, CSA Group performance protocols, and EU Ecodesign Directive requirements create overlapping test matrices that delay product launches and inflate third-party validation costs.
- Sheet-Metal Fabrication Skill Shortages:Precision stamping and welding expertise for thin-gauge stainless steel basin production is concentrating among aging workforces in Switzerland and Germany, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Sink Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Sinks, Circular Sinks, Vessel Sinks, Undermount Sinks Material: Stainless Steel, Porcelain, Composite, Cast Iron Installation Type: Drop-In, Wall-Mounted, Freestanding, Integrated End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Franke, Kohler, Elkay, Blanco, Roca, Moen, LIXIL, Duravit, TOTO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Sink Market Emerging Trajectories
Material science advances and regulatory pressure on water consumption are converging to reshape basin specification criteria across residential and commercial channels. Product development is pivoting toward integrated systems that simplify compliance verification.
Engineered composite resins, specifically Silgranit formulations, are decentralizing the traditional dominance of stainless steel and vitreous porcelain in premium residential renovations. Custom home builders and design-build firms are specifying these materials for scratch resistance and color consistency. This material shift is decentralizing supply relationships away from captive steel processors toward specialized polymer compounders.
REACH substance restrictions and EU Ecodesign Directive recyclability mandates are forcing reformulation of sealants, coatings, and composite binders used in basin fabrication. European manufacturers are accelerating end-of-life documentation and material passport development to maintain market access. The premium composite segment faces the steepest compliance recalibration as German-engineered formulations undergo third-party substance verification.
Builder-channel procurement is consolidating around pre-qualified vendor lists that bundle basin, faucet, and drainage components into single-source packages. National homebuilders in the United States are displacing fragmented spot-buying with multi-year master agreements that specify WaterSense-certified pairings. This bundling behavior is most pronounced in suburban North America where large-scale developers seek to standardize across subdivision portfolios.
Water Sink Market Segmentation
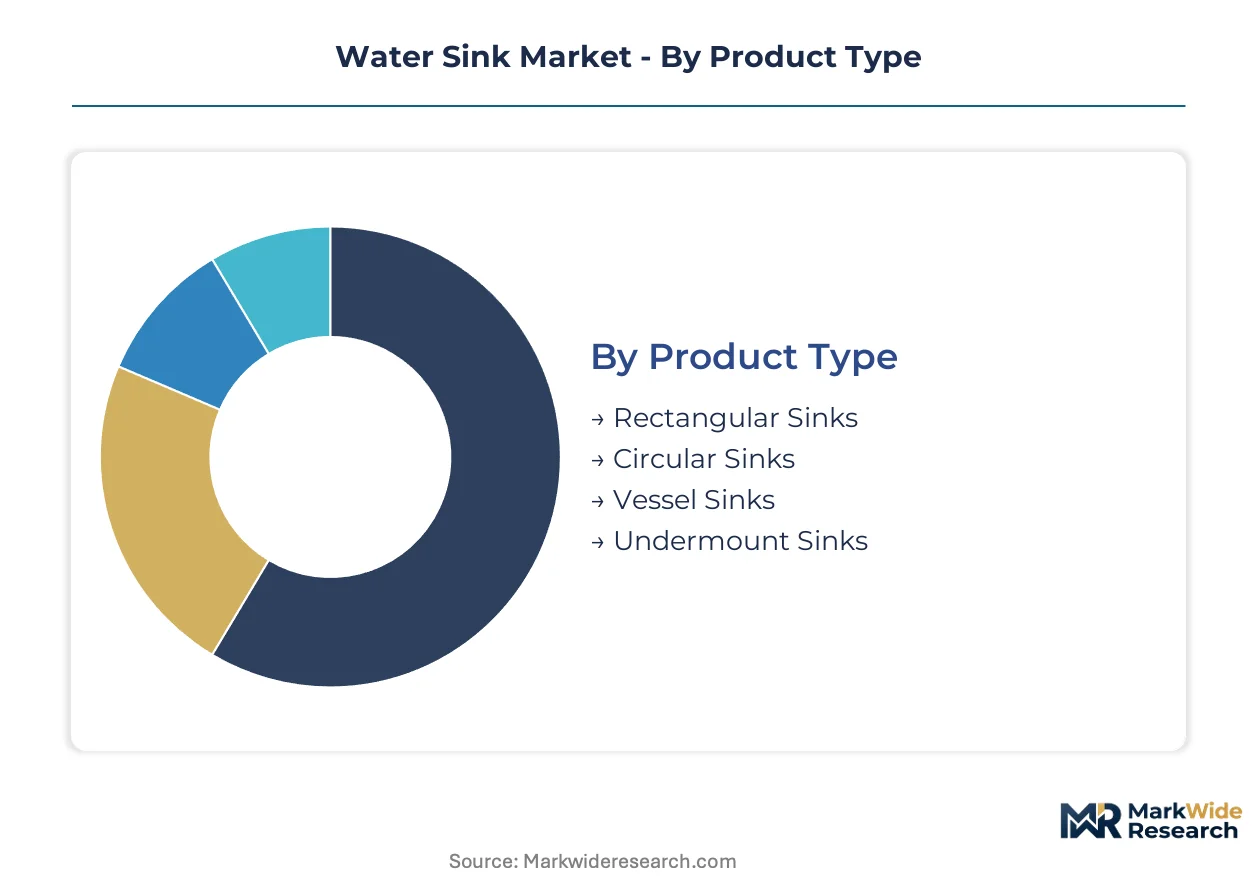
Water sink procurement decisions cascade through multiple technical dimensions that determine specification compliance, installation labor, and lifecycle durability. Builders and facility managers prioritize different attribute bundles depending on whether they optimize for first cost, renovation speed, or long-term serviceability.
Product Type:
Architects and kitchen designers select bowl geometry based on counter depth, workflow ergonomics, and the visual weight each configuration adds to built environments.
- Rectangular Sinks:These basins maximize usable surface area within standard cabinet depths, accommodating sheet pans and roasting trays in residential kitchens. Suburban North American renovation activity concentrates specification here as homeowners prioritize food-prep functionality over compact footprints.
- Vessel Sinks:Elevated bowl designs sit atop vanity surfaces rather than recessed within them, creating focal points in bathroom specifications. Hospitality end-users in China's tier-one cities specify these for guest room renovations where visual differentiation commands premium positioning.
- Circular Sinks:Compact radial geometry suits powder rooms and secondary bathrooms where space constraints dominate.
- Undermount Sinks:Sub-counter installation enables seamless countertop wiping and minimalist aesthetic alignment.
Rectangular sinks lead on scale; vessel sinks lead on momentum.
Material:
Fabrication inputs determine thermal performance, acoustic dampening, and the regulatory compliance burden each basin carries through end-of-life.
- Stainless Steel:Nickel-alloy sheet metal stamped into thin-gauge bowls dominates commercial kitchen specification for impact resistance and weld-repairability. Chinese foundry capacity expansion is broadening raw material availability for Asian manufacturers serving high-rise residential construction.
- Composite:Engineered resin formulations such as Silgranit offer color stability and scratch resistance that porcelain cannot match. German-engineered variants are gaining specification in European premium renovations where REACH substance documentation adds compliance overhead.
- Porcelain:Vitreous ceramic maintains cost positioning in volume residential replacement cycles.
- Cast Iron:Enameled heavy-gauge construction serves institutional kitchens requiring extreme durability under high-wear conditions.
Stainless steel dominates volume throughput; composite formulations are climbing the fastest.
Installation Type:
Labor economics and renovation timeline compression drive preference between retrofit-friendly and new-construction-optimized mounting systems.
- Drop-In:Self-rimming basins rest within precut countertop openings, enabling rapid replacement without substrate modification. North American suburban builders specify these for kitchen renovation projects where minimizing downtime determines contractor selection.
- Integrated:Pre-fabricated sink-countertop assemblies arrive on-site as single units, reducing installation variance and skilled labor dependency. Hospitality procurement teams favor these for bathroom vanity rollouts across multi-property portfolios.
- Wall-Mounted:Bracket-supported basins free floor space in compact commercial restrooms.
- Freestanding:Pedestal and console configurations suit heritage renovations where cabinet storage is unnecessary or architecturally inappropriate.
Drop-in configurations anchor replacement demand; integrated formats are expanding most quickly.
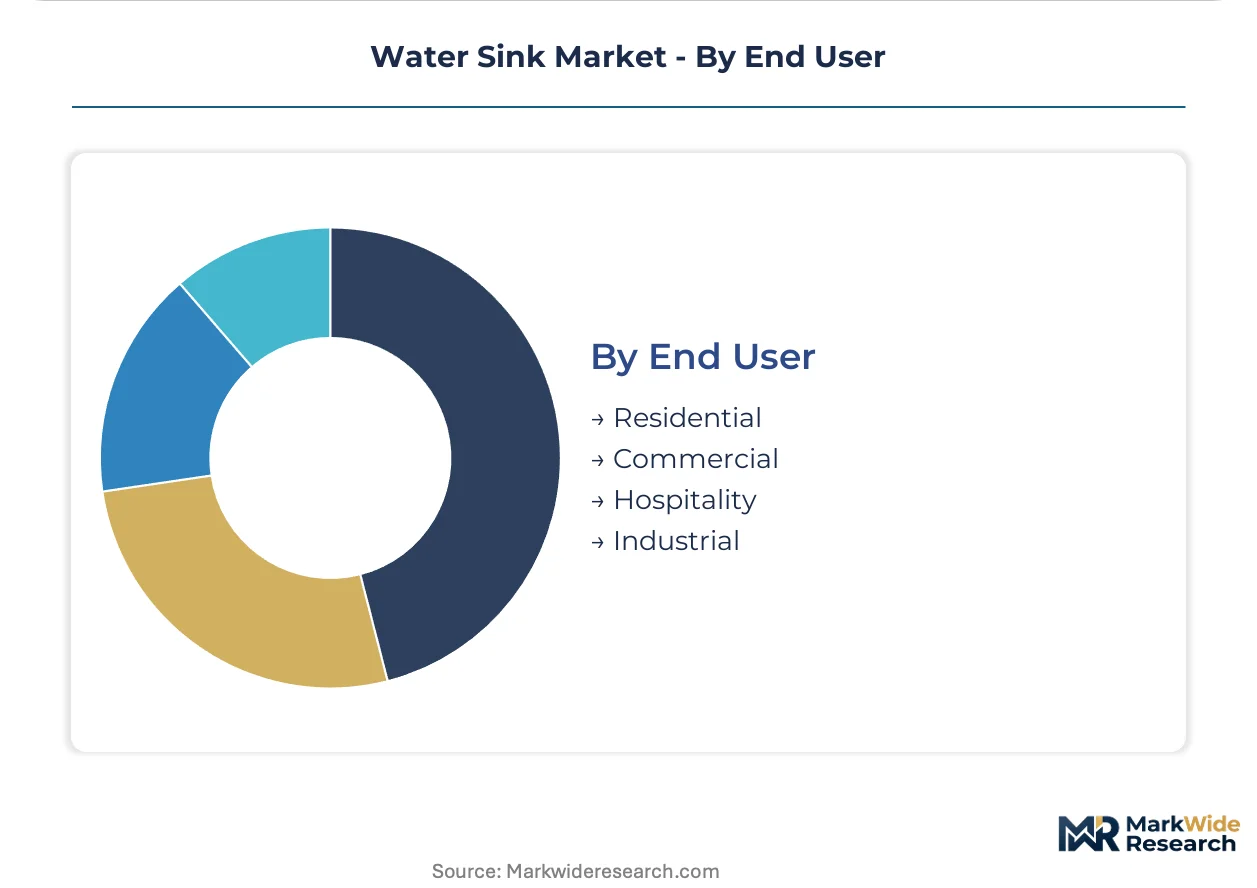
End User:
Usage intensity and regulatory exposure segment demand across warranty expectations, maintenance protocols, and specification authority concentration.
- Residential:Individual homeowners and renovation contractors drive replacement cycles influenced by kitchen redesign trends and WaterSense flow-rate compliance requirements. EPA tightening of certification thresholds is compelling simultaneous faucet and basin upgrades across existing housing stock.
- Hospitality:Hotel operators and bathroom furniture producers specify integrated vanity systems that streamline procurement and reduce on-site labor. This segment demands consistent aesthetic replication across property portfolios with accelerated replacement schedules.
- Commercial:Office and retail facility managers prioritize durability and standardized maintenance procedures.
- Industrial:Food processing and manufacturing environments specify heavy-gauge construction for chemical resistance and load-bearing capacity.
Residential channels dominate absolute volume; hospitality specification shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting fabrication investment toward markets with streamlined compliance pathways. Manufacturers are relocating stamping and finishing operations to exploit these arbitrage opportunities while maintaining specification access to premium segments.
United States
Suburban kitchen renovation contractors in Texas and Florida are compressing replacement timelines as homeowners prioritize food-prep functionality. EPA WaterSense certification thresholds are tightening flow-rate standards that constrain faucet pairing and bowl geometry. Fabricators in the Southeast are expanding capacity to serve builder-channel procurement consolidation across subdivision portfolios.
Germany
REACH substance disclosure requirements and EU Ecodesign Directive recyclability mandates are elevating compliance overhead for basin manufacturers. Premium composite formulations engineered domestically are gaining specification in bathroom renovations across Bavaria and Baden-Württemberg. Stuttgart-area fabricators are developing material passports to maintain market access under tightening substance restrictions.
China
High-rise residential construction in Shanghai, Beijing, and Shenzhen is accelerating standardized sink replacement cycles among developer specifications. GB standards and MIIT industrial policy are shaping domestic manufacturing quality benchmarks. Stainless steel foundries in the Yangtze River Delta are expanding sheet-metal capacity to supply basin fabrication for Asian manufacturers.
India
Government affordable housing schemes in Mumbai, Delhi, and Bangalore are creating volume demand for cost-optimized drop-in configurations. BIS standards and PLI scheme incentives are encouraging domestic fabrication investment. Maharashtra-based suppliers are scaling standardized basin production to serve underpenetrated South Asian replacement markets.
Switzerland
Captive steel processing operations sustain margin control for European distribution networks serving premium renovation segments. Swissmedic and federal environmental regulations govern material composition documentation for cross-border shipments. Precision stamping expertise in German-speaking cantons is concentrating among specialized workforces constraining capacity expansion.
Water Sink Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue composite material specialization and integrated vanity fabrication. The vendor base clusters around three archetypes: captive steel processors controlling upstream inputs, specialized resin compounders serving premium color-stable segments, and contract manufacturers assembling pre-fabricated sink-countertop systems. Consolidation pressure is intensifying through multi-year master agreements with national homebuilders and strategic partnerships with bathroom furniture producers.
Among European fabricators, Franke and Blanco exemplify divergent archetype positioning. Franke anchors the captive processing tier through integrated steel operations. Blanco occupies the engineered composite specialization vector with German-formulated resin technologies. Kohler represents the North American builder-channel consolidation pattern, securing specification through dedicated showroom networks and multi-year procurement agreements with suburban developers.
| Leading Market Players |
|---|
| Franke |
| Kohler |
| Elkay |
| Blanco |
| Roca |
| Moen |
| LIXIL |
| Duravit |
| TOTO |
| Others |
Supply Flow & Price Mechanics
National homebuilders in suburban North America are consolidating procurement around pre-qualified vendor lists, compressing channel margins and forcing tiered pricing stratification across premium, standard, and economy certification levels. This buyer concentration is reshaping how fabricators allocate margin between captive steel processing and outsourced composite resin sourcing.
Pricing Analysis
Builder-channel distributor markups are compressing as multi-year master agreements displace fragmented spot-buying, with pricing stratifying across WaterSense-certified premium tiers, standard compliance levels, and economy-grade non-certified alternatives. Price differentiation hinges on certification grade and volume scale, with EPA flow-rate compliance adding certification overhead that widens spreads. Cost compression in the standard tier is intensifying because Chinese stainless steel foundries are expanding sheet-metal capacity. Residential renovation contractors show the highest price sensitivity, while hospitality procurement teams prioritize installation-labor reduction over unit cost.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China operate hub-and-spoke patterns that stage finished basins near builder-channel consolidation points. Raw material sourcing draws from Yangtze River Delta stainless steel foundries, German resin compounders for Silgranit formulations, and Swiss captive steel processors. Supply chain risk centers on nickel price volatility destabilizing long-term alloy contracts. Distribution runs through dedicated showroom networks and direct builder relationships in North America, specialized bathroom furniture partnerships in Europe, and developer-channel bulk procurement in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Water Sink Market functions as a stable compounder anchored by residential kitchen renovation cycles that compress replacement timelines and sustain recurring demand across housing stock.
For Market Incumbents: Deploy captive steel processing leverage to defend margin position against nickel price volatility and Chinese foundry expansion. Franke and Kohler should deepen certification investment in WaterSense-compliant integrated drain systems to preempt regulatory displacement. Blanco must accelerate Silgranit formulation documentation for REACH substance disclosure to maintain European market access against emerging resin compounders. For New Entrants and Emerging Players: Composite material specialization offers the most penetrable wedge for challenging stainless steel dominance in premium residential renovations. Target India's affordable housing schemes in Mumbai and Bangalore with cost-optimized drop-in configurations previously underpenetrated in South Asian markets. Pursue contract manufacturing relationships with bathroom furniture producers to capture hospitality integrated vanity fabrication demand. For Investors and Strategic Acquirers: Bathroom furniture producers are the most active acquirer in this space, seeking vertical control over sink-countertop assembly to reduce installation variance across multi-property portfolios. Long-term viability rests on regulatory tailwinds from water-efficiency mandates spreading beyond California Title 20. Monitor EPA WaterSense threshold tightening as the signal indicating accelerated replacement demand pull-forward.| Strategic Initiative | Industry Significance |
|---|---|
| WaterSense Certification Investment | EPA compliance thresholds compel simultaneous faucet and basin redesigns, stimulating replacement cycles. |
| Silgranit Formulation Expansion | German-engineered resin technologies capture premium renovation specification from stainless steel and porcelain. |
| Integrated Vanity Fabrication | Pre-fabricated sink-countertop assemblies reduce hospitality on-site labor and installation variance. |
| India Capacity Localization | BIS standards and PLI scheme incentives encourage domestic fabrication for affordable housing volume demand. |
| REACH Material Passport Development | EU Ecodesign Directive recyclability mandates require end-of-life documentation for European market access. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Switzerland, with primary inputs from each region combining interviews with residential builders, hospitality procurement directors, stainless steel fabricators, and bathroom furniture producers alongside secondary validation. Trade data from customs records, EPA WaterSense certification databases, EU ECHA substance registrations, and BIS standards filings anchor quantitative inputs. Bottom-up basin shipment analysis triangulates against top-down construction spending and renovation cycle estimates.
Granularity-level modeling disaggregates volume and value across product type, material formulation, installation configuration, and end-user segment throughout the forecast period. CAGRs derive from regression analysis against housing starts, renovation expenditure indices, and regulatory compliance adoption curves. Nickel alloy price volatility indices and WaterSense certification penetration rates serve as industry-specific forecast inputs.
The model holds under stable regulatory enforcement trajectories; deviation in EPA threshold acceleration or REACH substance restriction expansion would shift replacement timing and material specification mix. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Bathroom Worktops Market
Bathroom Fixtures and Accessories
Ceramic Wash Basin Market
Bathroom Fixtures and Accessories
India Shower Cubicle Market
Bathroom Fixtures and Accessories
Bathroom Vanities Market
Bathroom Fixtures and Accessories
Sanitary Ware and Bathroom Accessories Market
Bathroom Fixtures and Accessories
Europe Bath Fitting Market
Bathroom Fixtures and Accessories
Toilet Seat Market
Bathroom Fixtures and Accessories
Plumbing Fixtures and Fittings Market
Bathroom Fixtures and Accessories
India Bath Fittings Market
Bathroom Fixtures and Accessories
Bathtub Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market