
 New RAM Market | 2026-2036
New RAM Market Size, Share, and Industry Trends Forecast 2026-2036
New RAM Market Insights
The EU F-Gas Regulation is restructuring procurement criteria for memory module suppliers across European data center builds. Samsung Electronics leverages captive EUV lithography capacity to sustain process leadership below 1α nanometer nodes. SK hynix anchors high-bandwidth memory supply for AI accelerator cards, while Micron Technology competes through domestic U.S. fabrication investments under the CHIPS Act framework.
New RAM encompasses volatile semiconductor memory cells organized in addressable arrays, fabricated through photolithographic patterning of silicon wafers with capacitor-transistor pairs storing charge states representing binary data, primarily serving as temporary high-speed workspace for processors in computing systems. DDR5 modules command premium positioning as server refresh cycles accelerate, while LPDDR4X dominates mobile device integration where power budgets constrain thermal design. Data center application demand outpaces consumer electronics as cloud operators expand AI inference infrastructure.
The U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment to China reshape fab equipment availability and node migration timelines for memory producers. South Korea's Ministry of Trade, Industry and Energy coordinates domestic supply chain resilience programs supporting local chemical and substrate vendors. Japan's METI subsidizes memory-relevant material purification facilities to reduce import dependence. Stakeholders must monitor equipment licensing rulings and regional subsidy program revisions to calibrate capacity expansion schedules against geopolitical access constraints.
Market Dynamics
Data center operators are expanding memory deployments as AI training workloads intensify, while the EU's F-Gas Regulation restricts fluorinated gas use in semiconductor etching processes, forcing fab retooling.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates fluorinated gas phase-down in etching processes, accelerating capital redeployment toward alternative chemistries and cleaner fabrication lines.
- AI accelerator integration:High-bandwidth memory modules are penetrating inference infrastructure as cloud operators scale GPU clusters for generative workloads.
- South Korean supply concentration:Advanced DRAM fabrication anchors in South Korea, with captive EUV lithography capacity sustaining node leadership below 1α nanometers.
Market Restraints
- Equipment licensing friction:U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment to China reshape fab equipment availability and node migration timelines.
- Process gas supply volatility:Fluorinated gas substitution timelines create input cost uncertainty for etching-dependent fabrication steps.
- Geographic supply concentration:Advanced DRAM production concentrates in South Korea, exposing procurement channels to single-region disruption risk.
Strategic Opportunities
- U.S. domestic fabrication:CHIPS Act subsidies enable captive memory production investments, reducing import dependence for critical data center infrastructure.
- Japan material purification:METI subsidizes memory-relevant material purification facilities, creating localized substrate and chemical supply alternatives.
- LPDDR5X mobile penetration:Next-generation mobile DRAM variants are displacing LPDDR4X in flagship smartphone thermal envelopes, opening premium module demand.
Industry Challenges
- EUV lithography talent scarcity:Specialized photomask engineering and scanner maintenance skill gaps constrain fab expansion velocity.
- Multi-node qualification timelines:DDR5 server module certification cycles extend procurement lead times for hyperscale data center refresh programs.
- Legacy DDR4 inventory absorption:Consumer electronics demand compression slows DDR4 channel clearing, complicating working capital management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New RAM Market |
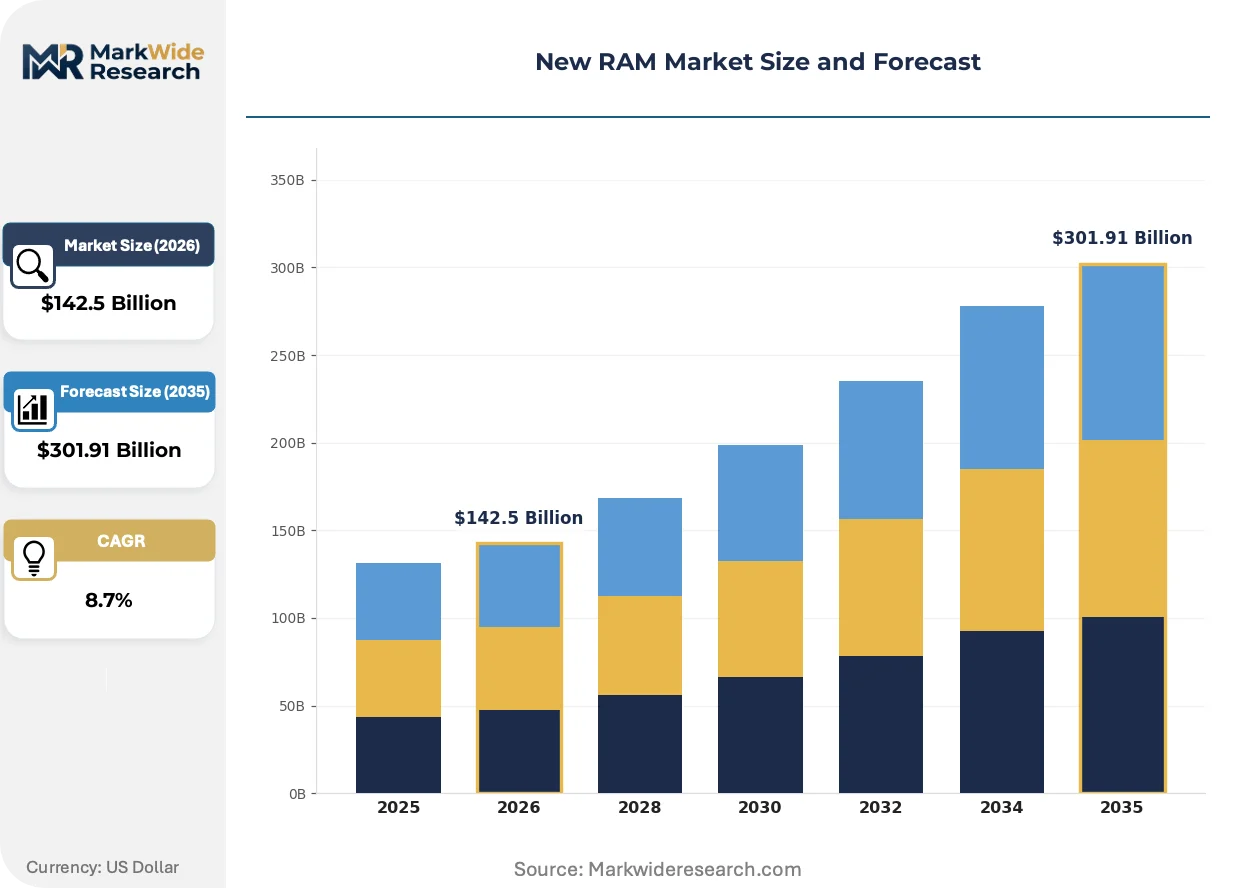
| Market Size in 2026 | $142.5 Billion |
| Market Size in 2035 | $301.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, LPDDR4X Application: Gaming, Data Center, Consumer Electronics, Mobile Devices Technology: SDRAM, Synchronous DRAM, DRAM, SRAM End User: OEMs, Retailers, System Integrators, Enterprises |
| Companies Covered | Samsung Electronics, SK hynix, Micron Technology, Nanya Technology, Winbond Electronics, Powerchip Technology, GigaDevice Semiconductor, ChangXin Memory Technologies, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New RAM Market Trends and Innovations
Process automation and regulatory chemistry shifts are compressing fabrication timelines while procurement patterns concentrate around sovereign supply chain mandates.
High-bandwidth memory stacking is automating die interconnect density in AI accelerator cards. Hyperscale cloud operators are adopting HBM3E modules at accelerated procurement cadences. This technology is automating memory bandwidth scaling without proportional PCB footprint expansion, enabling denser server blade configurations.
The EU F-Gas Regulation mandates fluorinated gas phase-down in plasma etching processes by 2030. Memory foundries are retooling toward alternative chemistries and closed-loop abatement systems. European data center builds face constrained module availability as domestic fab output adjusts to compliant process transitions.
Hyperscale procurement is consolidating around sovereign supply chain certification requirements. Tier-one cloud operators are mandating country-of-origin documentation and CHIPS Act compliance for server memory allocations. This concentration is most visible in U.S. federal cloud contracts and defense-adjacent infrastructure deployments.
New RAM Market Segmentation
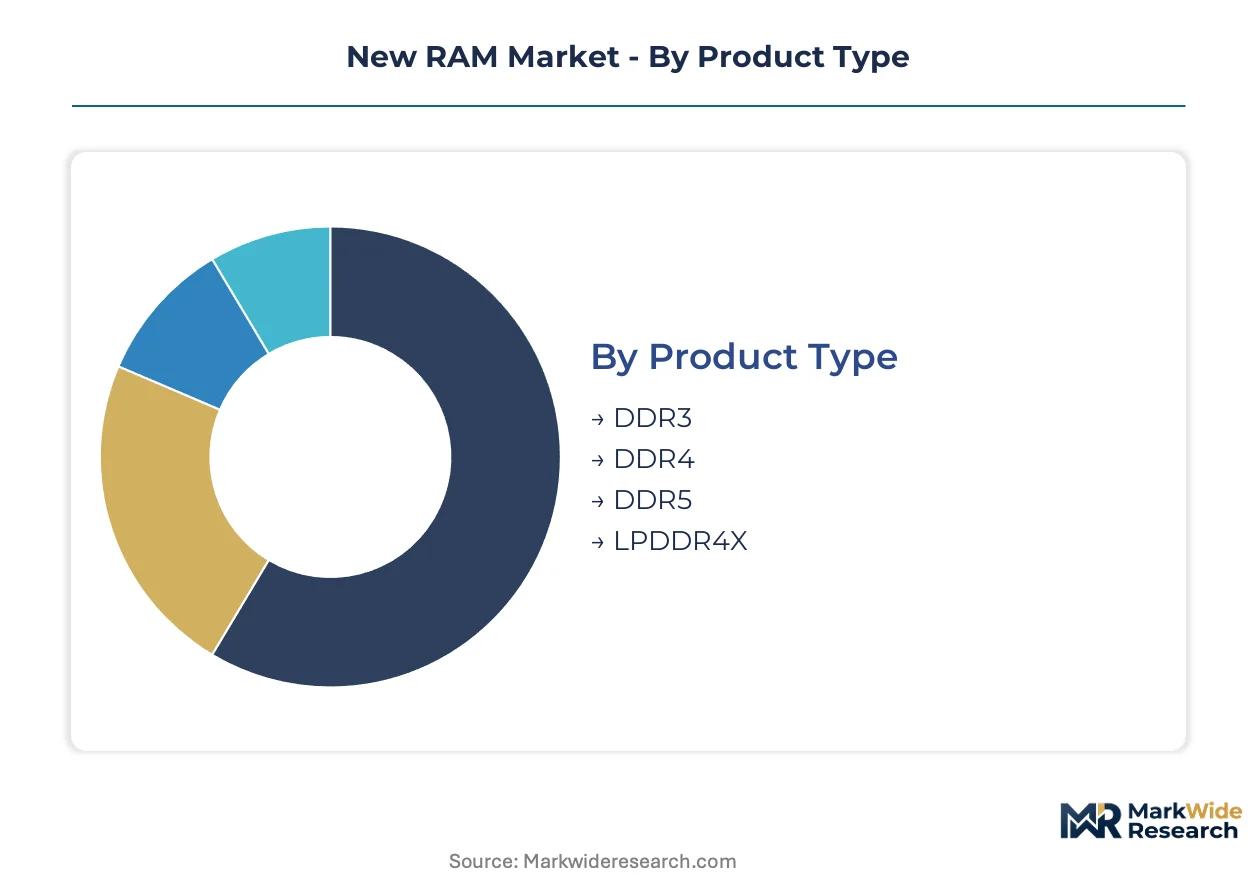
Memory module specifications diverge sharply across thermal envelopes, bandwidth requirements, and power budgets. Understanding these technical fault lines clarifies why data center procurement teams source DDR5 modules while mobile OEMs prioritize LPDDR4X stacks.
Product Type:
Process node advancement and voltage scaling differentiate module generations, with each tier targeting distinct thermal and performance envelopes.
- DDR5:Operating at 1.1V with on-die error correction, DDR5 modules double burst length to 16 and introduce independent 32-bit subchannels. Hyperscale data center operators in Virginia and Frankfurt are standardizing DDR5-4800 for AI training clusters as server refresh cycles compress.
- LPDDR4X:Ultra-low voltage operation at 0.6V enables stacked package-on-package configurations. Flagship smartphone thermal designs in South Korea and Taiwan absorb the majority of LPDDR4X die output as camera pipelines and 5G modems intensify memory bandwidth demand.
- DDR4:Legacy 1.2V modules persist in enterprise workstation refresh cycles and cost-optimized cloud edge nodes.
- DDR3:Obsolete for new designs, residual demand concentrates in industrial control systems and legacy telecommunications infrastructure requiring long-term supply continuity.
Mature deployment sits with DDR4. Newer deployment is concentrated in DDR5.
Application:
Workload characteristics dictate memory architecture selection, with bandwidth-hungry parallel processing driving divergence from consumer browsing and media consumption patterns.
- Data Center:GPU-accelerated training infrastructure demands high-capacity registered DIMMs with temperature-controlled refresh algorithms. Northern Virginia, Ashburn, and Singapore data center clusters are expanding HBM2E and DDR5 deployments for large language model inference pipelines.
- Mobile Devices:Package height constraints and aggressive standby power targets favor LPDDR4X and emerging LPDDR5X stacks. Device OEMs in Shenzhen and Bangalore specify multi-die packages under 1.0mm z-height for foldable form factors.
- Gaming:Overclocking-tolerant modules with extended heat spreaders address enthusiast desktop builds and console refresh cycles.
- Consumer Electronics:Smart television and set-top box designs utilize cost-optimized DDR4 SO-DIMMs with relaxed timing specifications.
Volume concentration weights toward mobile devices. Margin expansion is accelerating fastest in data center.
Technology:
Cell architecture and refresh mechanisms separate volatile memory categories, with capacitor-based designs dominating high-density applications and transistor-based cells serving specialized low-latency requirements.
- DRAM:One-transistor one-capacitor cells fabricated at 1α nanometer nodes enable the highest bit density per wafer. Samsung Electronics and SK hynix in South Korea anchor advanced DRAM output for server and mobile module packaging.
- SDRAM:Synchronous interface timing with burst-mode access dominates PC and server motherboard implementations. Intel and AMD platform roadmaps synchronize memory controller specifications with SDRAM JEDEC standards.
- Synchronous DRAM:Clock-aligned command and data buses eliminate asynchronous timing skew in multi-rank module configurations.
- SRAM:Six-transistor bit cells without refresh cycles provide nanosecond access latency for CPU cache hierarchies and networking lookup tables.
Mainstream volume flows through DRAM. SRAM occupies specialized latency-critical niches.
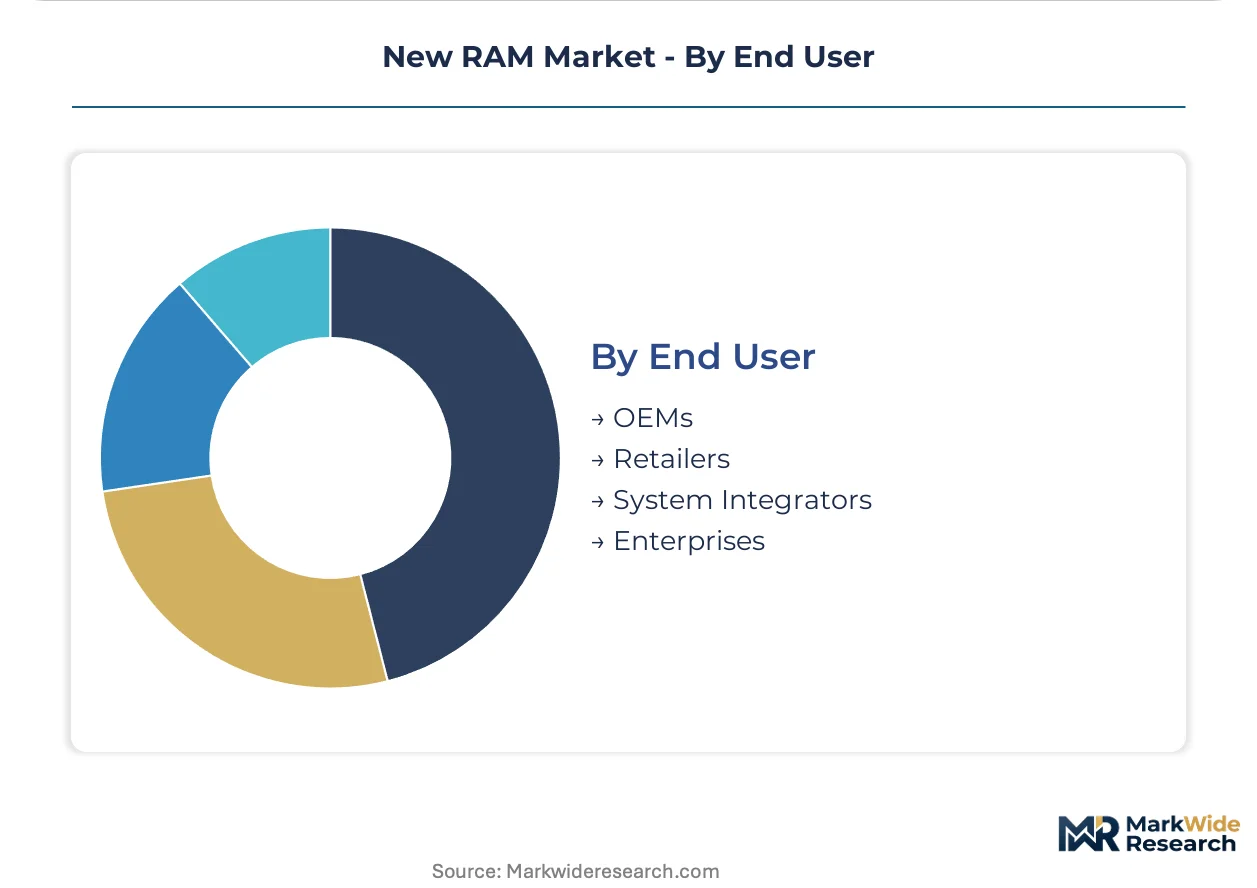
End User:
Procurement scale and technical integration depth shape vendor relationships, with direct semiconductor sourcing separating large-scale manufacturers from channel-dependent resellers.
- OEMs:Dell Technologies, Hewlett Packard Enterprise, and Lenovo negotiate annual DRAM supply agreements with foundry direct allocation. These manufacturers validate module SKUs across server platform generations with extended thermal qualification cycles.
- Enterprises:Hyperscale cloud operators including Amazon Web Services and Microsoft Azure specify custom module form factors with onboard temperature sensors and proprietary SPD programming.
- System Integrators:Regional server assemblers in Texas and Bavaria source validated DIMMs through distribution, absorbing buffer inventory for just-in-time rack integration.
- Retailers:Consumer-facing channels including Newegg and Amazon move boxed memory kits with heat spreader aesthetic differentiation and XMP profile marketing.
Direct foundry relationships concentrate with OEMs. Retail channel growth is expanding most quickly in aftermarket gaming segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the most concentrated advanced memory fabrication corridor worldwide, with Samsung Electronics and SK hynix operating captive EUV lithography clusters in the capital region. Memory module procurement patterns diverge sharply across regulatory jurisdictions as sovereign supply chain mandates reshape vendor qualification criteria.
United States
Hyperscale data center operators in Northern Virginia and Phoenix are expanding DDR5 and HBM3E deployments for AI training infrastructure. The CHIPS Act subsidizes domestic fabrication investments by Micron Technology in New York and Idaho. Boise and Manassas anchor the primary U.S.-based DRAM module assembly and testing corridors.
South Korea
AI accelerator card demand is concentrating high-bandwidth memory procurement through foundry-direct channels in Seoul and Yongin. The Ministry of Trade, Industry and Energy coordinates domestic chemical and substrate vendor resilience programs. Pyeongtaek and Icheon host the densest EUV lithography clusters for sub-1α nanometer DRAM production.
China
Domestic module integrators in Shenzhen and Shanghai are absorbing legacy DDR4 die output for consumer electronics and industrial control systems. U.S. Department of Commerce export controls on advanced semiconductor manufacturing equipment constrain node migration timelines for memory producers. Wuxi and Dalian concentrate packaging and testing capacity for regional supply chains.
Japan
Material purification facilities in Yokkaichi and Kita-Kyushu are expanding output for substrate and chemical supply to memory foundries. METI subsidizes memory-relevant material purification to reduce import dependence from South Korean and Taiwanese sources. The Kansai corridor anchors photoresist and high-purity gas production for etching process chemistry.
Germany
European data center builds in Frankfurt and Berlin face constrained module availability as domestic fab output adjusts to EU F-Gas Regulation compliance. The regulation mandates fluorinated gas phase-down in plasma etching processes by 2030. Dresden hosts the primary European DRAM fabrication and advanced packaging research cluster.
New RAM Market Competitive Landscape
Premium-margin players sit above commodity-margin players across process node leadership and EUV lithography access. The vendor base concentrates around three advanced DRAM fabricators controlling sub-1α nanometer capacity, while second-tier specialists occupy legacy node segments and niche mobile applications. Strategic archetypes separate EUV-enabled node leaders, mobile-optimized low-power specialists, and regional cost-optimized assemblers. Dominant competitive moves include sovereign subsidy capture for domestic fabrication and backward integration into captive chemical and substrate supply.
Among South Korea-based fabricators, Samsung Electronics and SK hynix exemplify the EUV-enabled node leadership archetype, occupying positions that anchor global high-bandwidth memory supply for AI accelerator cards. Micron Technology represents the geographically diversified premium-tier competitor, with its corporate structure organized under U.S. incorporation and manufacturing presence across multiple jurisdictions. These three entities collectively illustrate how advanced lithography access and sovereign subsidy alignment determine competitive positioning in the current procurement environment.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK hynix |
| Micron Technology |
| Nanya Technology |
| Winbond Electronics |
| Powerchip Technology |
| GigaDevice Semiconductor |
| ChangXin Memory Technologies |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
EUV lithography engineer scarcity in South Korea and Taiwan widens labor-cost differentials between premium and standard memory tiers, compressing margins at legacy nodes while node-leader pricing holds firm.
Pricing Analysis
Throughput-based pricing anchors server memory contracts, with hyperscale buyers negotiating per-terabyte-month rates tied to uptime guarantees rather than unit procurement. Three-tier pricing structure across premium, standard, and economy levels separates HBM3E stacks from DDR5 registered DIMMs and legacy DDR4 modules. Cost compression in DDR4 channels intensifies as consumer electronics demand absorption lags, while data center buyers show lowest price sensitivity for AI-training-optimized configurations. Certification grade and volume scale differentiate contract terms, with CHIPS Act compliance premiums visible in federal cloud procurement.
Supply Chain Analysis
Photomask engineering talent shortages in Pyeongtaek and Icheon constrain fab expansion velocity across South Korea's EUV clusters. Advanced DRAM output concentrates in South Korea, Taiwan, and the United States, drawing from high-purity silicon wafers, fluorinated etching gases, and EUV photoresists. Single-source vulnerability sits with Japanese photoresist and high-purity gas suppliers subject to METI export coordination. Distribution runs through foundry-direct allocation for hyperscale OEMs and specialized distributors for regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing captive chemical and substrate supply to secure node migration timelines against regulatory chemistry shifts.
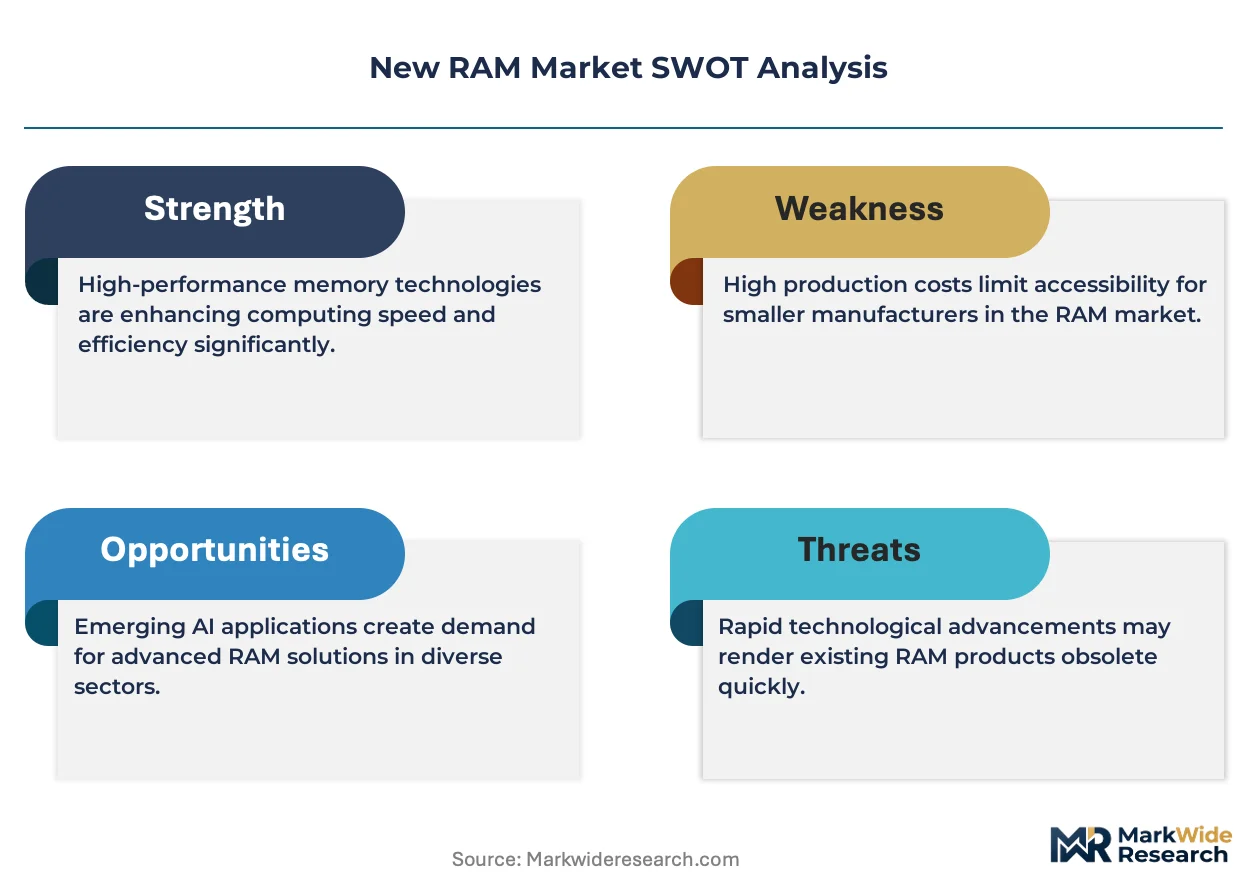
For Market Incumbents: Deepen backward integration into high-purity gas purification and photoresist formulation to offset EU F-Gas Regulation compliance costs. Lock in multi-year EUV equipment service contracts to counter scanner maintenance talent scarcity. Prioritize DDR5 server module qualification acceleration ahead of hyperscale refresh cycles. For New Entrants and Emerging Players: Specialty HBM stacking for inference-optimized AI accelerators offers the most penetrable wedge, targeting mid-tier cloud operators excluded from Samsung and SK hynix direct allocation. Focus on LPDDR5X mobile modules for foldable device OEMs in Shenzhen seeking second-source supply security. Pursue foundry partnership models rather than greenfield fab investment. For Investors and Strategic Acquirers: Re-rating potential sits with material purification specialists given METI subsidy expansion and import substitution mandates across memory-relevant chemicals. Long-term viability hinges on EUV lithography access and sovereign subsidy alignment. Watch U.S. Department of Commerce equipment licensing rulings as the inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Supply | Captive fluorinated gas and photoresist production reduces EU F-Gas Regulation exposure for European data center builds. |
| EUV Lithography Capacity Expansion | Sub-1α nanometer node leadership secures premium positioning in AI accelerator HBM procurement. |
| CHIPS Act Compliance Certification | Domestic U.S. fabrication qualification opens federal cloud and defense-adjacent memory allocations. |
| Alternative Etching Chemistry Development | Closed-loop abatement systems and fluorinated gas substitutes align with 2030 EU regulatory phase-down mandates. |
| HBM3E Module Qualification Acceleration | Early hyperscale adoption for large language model inference pipelines captures premium-margin procurement windows. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, foundry utilization rates, and memory module spot pricing anchored the trend analysis, supplemented by interviews with DRAM procurement directors at cloud operators, EUV scanner maintenance engineers, semiconductor chemical supply managers, and data center infrastructure planners. Secondary validation drew from SEC 10-K filings, equipment import licensing records, METI subsidy program documentation, and EU regulatory filings. Bottom-up module demand modeling triangulated against top-down wafer capacity forecasts.
Segment-weighting across product type, application, technology, and end-user dimensions structured the analytical framework over the projection horizon. CAGRs derived from node migration timelines, server refresh cycle compression, and AI workload intensity curves. Forecast inputs incorporated EU F-Gas Regulation compliance cost trajectories and CHIPS Act subsidy disbursement schedules.
Several conditions sit outside the modeled scope, including unannounced export control expansions, abrupt foundry equipment failures, and geopolitical disruptions to Japanese material supply. Forecasts reflect assumptions about regulatory stability and lithography technology roadmaps. Material deviation in equipment licensing rulings or sovereign subsidy revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Smartphone RAM Market
Memory Chips
Americas Dynamic Random Access Memory (DRAM) Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Japan DRAM Market
Memory Chips
GDDR6 Market
Memory Chips
Memory Module Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
MRAM Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Nano RAM Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Static Random-Access Memory (SRAM) Market