
 GDDR6 Market | 2026-2036
GDDR6 Market Size, Share, and Industry Trends Forecast 2026-2036
GDDR6 Market Foresight
The 16 Gbps speed grade is collapsing into commodity positioning as 18 Gbps and 20 Gbps variants capture premium socket allocations in data-center GPUs. Samsung Electronics leverages its captive DRAM fabrication to sustain cost advantages on high-volume gaming SKUs. SK hynix anchors supply for AI accelerator cards with thermally optimized packages. Micron Technology differentiates through EUV-based node transitions that tighten timing margins for next-generation controllers.
GDDR6 is a high-speed synchronous graphics DRAM standard operating at per-pin data rates from 14 Gbps to 22 Gbps over a 32-bit interface with 16n prefetch architecture, designed to feed massive parallel compute engines in GPUs and AI accelerators with sustained bandwidth exceeding 1 TB/s per device. High Bandwidth GDDR6 commands the steepest price premiums as AI training clusters prioritize throughput density over unit cost. Gaming GDDR6 remains the highest-volume category but faces margin compression from console cycle maturity and PC GPU inventory normalization. The 20 Gbps technology node is capturing design wins in inference accelerators where power-per-bit transferred determines total cost of ownership.
FCC equipment authorization rules shape GPU module compliance for US-bound gaming and workstation products, while EU RoHS and REACH restrictions constrain substrate materials and flame-retardant chemistries in European-bound shipments. JEDEC standardization bodies govern electrical interoperability, and their evolving pinout definitions determine backward compatibility windows for controller IP. Stakeholders must monitor whether 22 Gbps qualification timelines compress ahead of GDDR7 commercialization, as this overlap window dictates inventory risk for memory vendors and procurement flexibility for GPU designers.
Market Dynamics
The transition from 16 Gbps to 20 Gbps speed grades is compressing product lifecycles and redistributing margin pools across the memory supply chain. JEDEC's tightening signal integrity specifications are forcing controller IP redesigns while AI training clusters absorb premium bandwidth at unprecedented scale.
Growth Catalysts
- AI Training Cluster Expansion:Hyperscale datacenters in Taiwan and South Korea are commissioning GPU pods that specify 20 Gbps GDDR6 for inference acceleration, pulling wafer starts toward high-margin AI SKUs.
- REACH Substrate Compliance:EU RoHS and REACH amendments restricting halogenated flame retardants are accelerating qualification of green substrate materials that incidentally improve thermal conductivity for high-speed signaling.
- Advanced Packaging Convergence:TSMC's CoWoS and Samsung's I-Cube integration with GDDR6 PHYs is enabling 4-Hi and 8-Hi memory stacks that double bandwidth density per accelerator card.
Market Restraints
- DRAM Wafer Supply Concentration:Three Korean and Taiwanese foundries control over 90% of advanced DRAM bit supply, creating single-source vulnerability for 18 Gbps and faster speed bins.
- Signal Integrity Physics:PCB trace losses and via stubs at 20 Gbps exceed channel budgets without expensive Megtron-6 laminates or retimer chips that add latency and power.
- GDDR7 Substitution Timeline:JEDEC's next-generation standard with PAM-4 signaling threatens to truncate the 22 Gbps GDDR6 window before volume production economics mature.
Strategic Opportunities
- India Datacenter Buildout:The country's PLI scheme for electronics manufacturing is attracting GPU assembly investments that will localize memory module testing and burn-in capacity.
- Automotive Inference Edge:ADAS domain controllers in Germany and Japan are specifying automotive-grade GDDR6 for real-time sensor fusion, opening a qualification-driven premium tier.
- Japan METI Green Semiconductor Initiative:Subsidies for low-power memory technologies are incentivizing GDDR6 vendors to develop sub-1.1V operating modes for inference accelerators.
Industry Challenges
- Signal Integrity Engineering Talent Scarcity:The pool of engineers capable of optimizing 20 Gbps+ channel equalization and crosstalk cancellation is concentrated among a handful of GPU and memory controller designers.
- JEDEC Qualification Cycle Compression:Interoperability testing windows are shortening as controller IP vendors push faster product ramps, risking corner-case timing failures in production silicon.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GDDR6 Market |
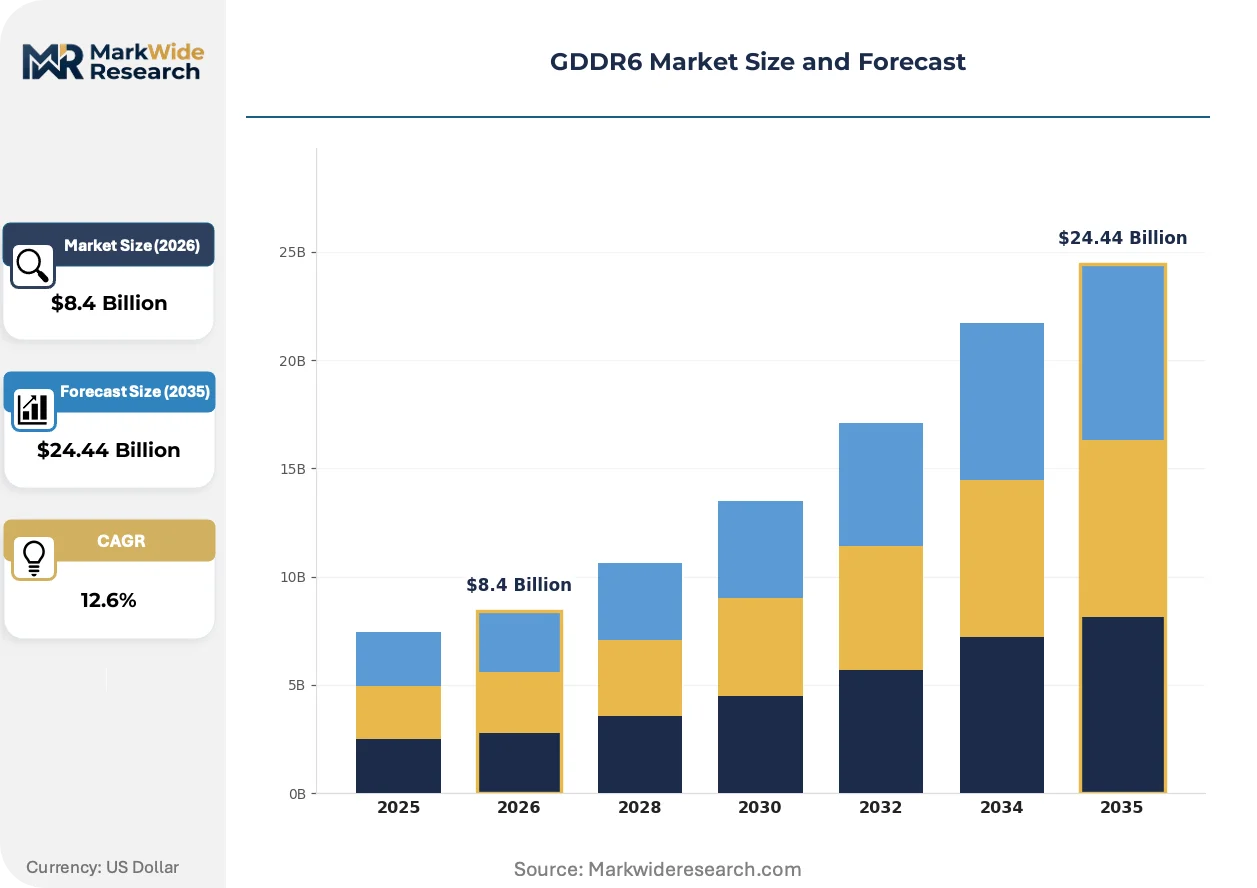
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $24.44 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard GDDR6, Low Power GDDR6, High Bandwidth GDDR6, Mobile GDDR6, Gaming GDDR6 Application: Graphics Cards, High-Performance Computing, Artificial Intelligence, Video Processing, Virtual Reality End User Industry: Consumer Electronics, Data Centers, Telecommunications, Aerospace, Semiconductor Manufacturers Technology: Data Rate 14 Gbps, Data Rate 16 Gbps, Data Rate 18 Gbps, Data Rate 20 Gbps, Data Rate 22 Gbps |
| Companies Covered | AMD, Qualcomm, Samsung Electronics, NVIDIA, Tenstorrent, SK hynix, Intel, TSMC, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GDDR6 Market Shifts & Advancements
Speed-grade stratification is fragmenting procurement patterns as buyers bifurcate between commodity gaming silicon and AI-optimized premium tiers. Three distinct vectors are reshaping competitive positioning.
High-Bandwidth GDDR6 is decomposing the traditional gaming-centric market structure. This 20 Gbps variant with thermally enhanced packages feeds NVIDIA H100 and AMD MI300 series accelerators that prioritize throughput density over unit economics. Datacenter procurement teams now negotiate directly with Samsung and SK hynix for allocation priority, bypassing traditional distribution channels that served PC OEMs.
EU F-Gas Regulation amendments targeting fluorinated greenhouse gases in semiconductor manufacturing are pressuring memory fabs to transition etching chemistries. Samsung's Pyeongtaek and SK hynix's Icheon complexes must qualify alternative plasma processes without compromising dielectric integrity. European-bound GPU modules face additional documentation burdens that extend customs clearance timelines by two to four weeks.
Buyer concentration among hyperscale cloud operators is compressing contract structures from annual frameworks to quarterly allocation agreements. Amazon Web Services, Microsoft Azure, and Google Cloud Platform now specify speed-bin guarantees and thermal throttling curves in procurement terms that were previously reserved for CPU supply. Taiwan's ODMs are responding by pre-qualifying multiple memory vendor sources for each GPU platform.
GDDR6 Market Segmentation
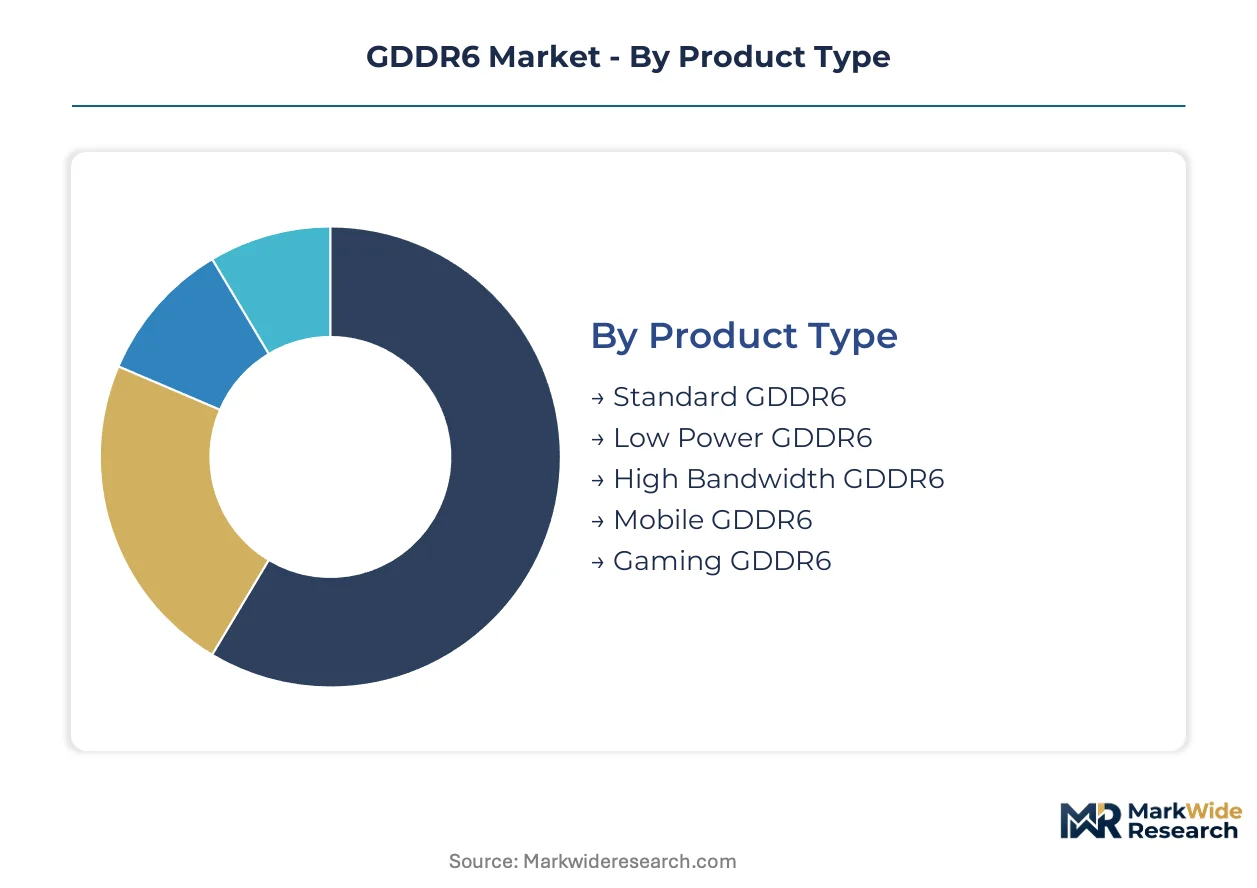
GDDR6 segmentation reveals how memory vendors allocate fabrication capacity across diverging margin pools. Speed-grade stratification and application-specific thermal requirements create distinct procurement channels that resist simple commodity classification.
Product Type:
Substitution pressure from GDDR7 PAM-4 signaling threatens premium tiers most acutely, while legacy gaming variants face longer replacement windows.
- Standard GDDR6:Baseline 16 Gbps devices with JEDEC-compliant pinouts serve mainstream graphics cards and entry-level AI inference. Taiwan ODMs consume the majority of volume for NVIDIA GeForce and AMD Radeon board production.
- Low Power GDDR6:Sub-1.2V operating modes with aggressive clock gating target battery-constrained edge devices. Japan METI green semiconductor subsidies are accelerating qualification of these devices for automotive inference controllers in Toyota and Honda supply chains.
- High Bandwidth GDDR6:20 Gbps speed bins with thermally enhanced BGA packages feed NVIDIA H100 and AMD MI300 datacenter accelerators. Hyperscale procurement teams in Taiwan and South Korea negotiate direct allocation agreements, bypassing traditional distribution.
- Mobile GDDR6:Die-stacked configurations with reduced z-height accommodate thermal constraints in gaming laptops and portable workstations. Samsung's captive smartphone display business internalizes significant volume.
- Gaming GDDR6:Cost-optimized 16-18 Gbps SKUs with standard thermal solutions face margin compression from console cycle maturity. Inventory normalization in US and European PC GPU channels is extending procurement lead times.
Gaming GDDR6 anchors the volume base while High Bandwidth GDDR6 gains share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive datacenter deployments from consumer discretionary purchases with diverging sensitivity to unit economics.
- Graphics Cards:Discrete GPU modules for gaming and professional visualization. Taiwan ODMs integrate 16-20 Gbps devices from Samsung and SK hynix into boards for US and European distribution.
- High-Performance Computing:Scientific simulation clusters at Oak Ridge National Laboratory and similar facilities specify 20 Gbps GDDR6 for memory-bandwidth-bound workloads. US Department of Energy procurement frameworks prioritize domestic supply chain resilience.
- Artificial Intelligence:Training and inference accelerators command premium speed bins with guaranteed thermal throttling curves. Amazon Web Services, Microsoft Azure, and Google Cloud Platform specify 20 Gbps allocation priority in quarterly contracts.
- Video Processing:Broadcast encoding and streaming infrastructure utilizes mid-tier 18 Gbps devices. South Korean content platforms drive regional demand concentration.
- Virtual Reality:Head-mounted displays with strict latency budgets require low-latency 18 Gbps configurations. Meta Platforms and Sony Interactive Entertainment anchor volume commitments.
Graphics Cards absorbs the largest fabrication allocation while Artificial Intelligence commands the steepest expansion trajectory.
End User Industry:
Customer type concentration creates diverging contract structures, with hyperscale operators extracting terms previously reserved for CPU procurement.
- Consumer Electronics:Gaming consoles, laptops, and desktop GPUs with price-sensitive procurement. Sony PlayStation and Microsoft Xbox platform cycles drive cyclical demand spikes.
- Data Centers:Cloud operators and colocation facilities specifying 20 Gbps devices with direct vendor relationships. Taiwan's TSMC CoWoS packaging ecosystem concentrates supply chain leverage.
- Telecommunications:Edge computing infrastructure for 5G network functions. South Korean operators SK Telecom and KT Corporation pilot GDDR6-accelerated baseband processing.
- Aerospace:Radiation-tolerant and extended-temperature variants for satellite and avionics applications. European Space Agency qualification requirements extend development timelines.
- Semiconductor Manufacturers:Captive memory production for vertically integrated GPU designers. Samsung's internal consumption for Exynos and discrete graphics products reduces merchant market availability.
Consumer Electronics provides the demand floor while Data Centers reshapes contract economics.
Technology:
Maturity gradients separate volume-production nodes from qualification-stage speed bins with diverging yield economics.
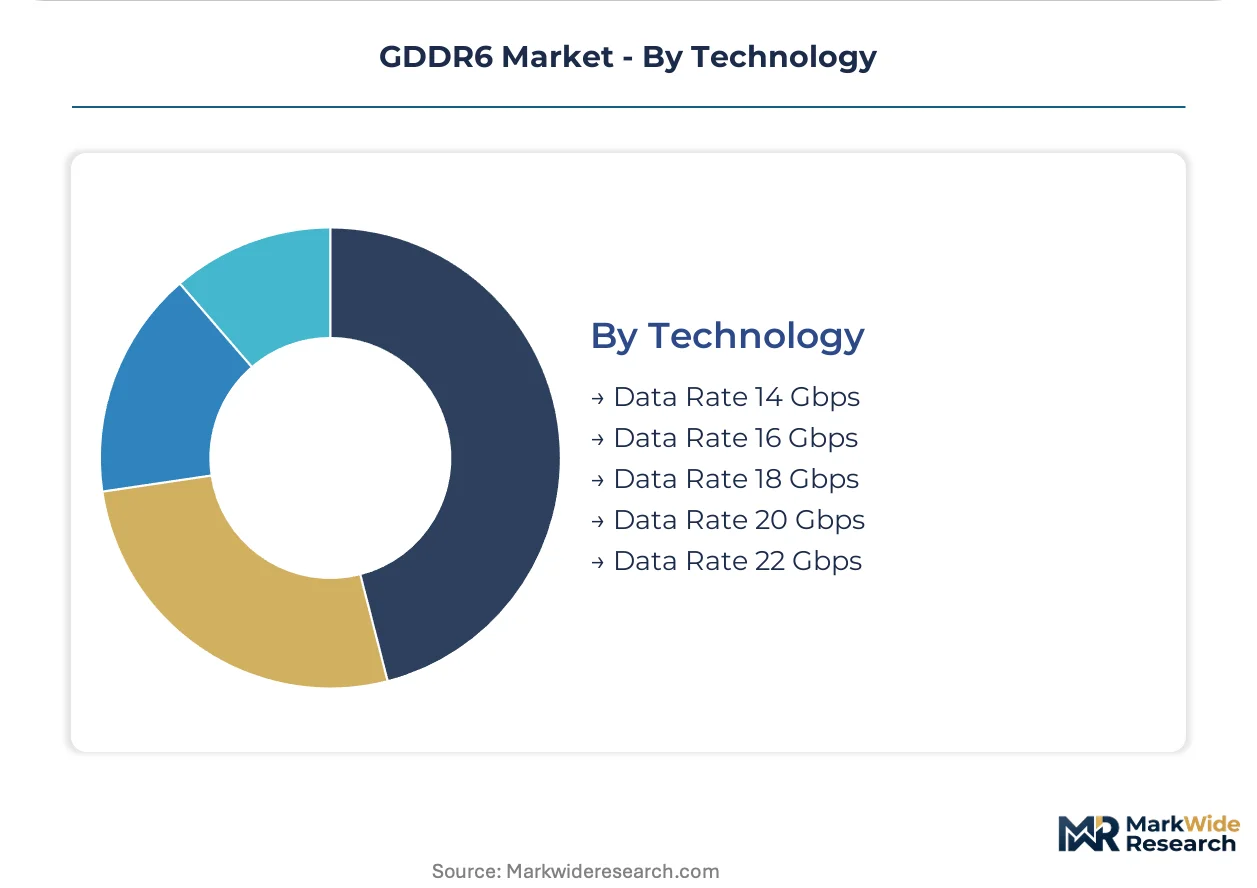
- Data Rate 14 Gbps:Legacy JEDEC baseline with full ecosystem compatibility. Automotive and industrial applications in Germany and Japan specify this grade for supply chain stability.
- Data Rate 16 Gbps:Commoditized mainstream tier with compressed margins. Gaming GPU inventory normalization in US channels is extending procurement cycles.
- Data Rate 18 Gbps:Mid-premium positioning for high-end gaming and entry-level AI inference. SK hynix has secured design wins in AMD RDNA3 architecture deployments.
- Data Rate 20 Gbps:Leading-edge production with thermally optimized packages. NVIDIA H100 accelerators specify this grade with guaranteed allocation priority from Samsung and SK hynix.
- Data Rate 22 Gbps:Pre-qualification stage facing truncation risk from GDDR7 commercialization. JEDEC interoperability testing windows are compressing as controller IP vendors accelerate product ramps.
Data Rate 16 Gbps maintains the largest shipment volume while Data Rate 20 Gbps climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced DRAM fabrication clusters in South Korea and Taiwan supply over ninety percent of high-speed GDDR6 bit output. Memory packaging and GPU assembly capacity concentrates in these jurisdictions alongside emerging testing infrastructure in India.
South Korea
SK hynix and Samsung Electronics commission GPU pods for hyperscale AI training clusters that specify 20 Gbps speed bins. The Ministry of Trade, Industry and Energy (METI) green semiconductor subsidies incentivize sub-1.1V operating mode development. The Icheon and Pyeongtaek complexes anchor wafer start allocation toward AI-optimized premium tiers.
Taiwan
TSMC's CoWoS advanced packaging ecosystem integrates GDDR6 PHYs into 4-Hi and 8-Hi memory stacks for NVIDIA and AMD accelerators. National Development Council funding supports expansion of burn-in and testing capacity for AI-bound memory modules. The Hsinchu Science Park concentrates controller IP design and signal integrity engineering talent.
United States
Department of Energy procurement frameworks at Oak Ridge National Laboratory prioritize domestic supply chain resilience for HPC memory bandwidth. FCC equipment authorization rules govern GPU module compliance for gaming and workstation products. California-based hyperscale operators negotiate quarterly allocation agreements directly with Korean memory vendors.
Japan
Toyota and Honda supply chains specify automotive-grade GDDR6 for ADAS domain controllers requiring real-time sensor fusion. METI green semiconductor initiatives accelerate qualification of low-power variants for edge inference. The Kyushu region hosts specialized testing facilities for extended-temperature automotive memory.
India
Production-linked incentive schemes attract GPU assembly investments that localize memory module testing and burn-in capacity. Central Electricity Authority regulations shape datacenter power infrastructure standards for AI cluster deployments. Karnataka and Telangana states host emerging electronics manufacturing clusters targeting memory subsystem integration.
GDDR6 Market Competitive Landscape
Concentration sits with captive DRAM fabricators and GPU designers that internalize memory controller IP. The vendor base separates into three strategic tiers: Korean memory houses with captive fabrication, fabless GPU architects specifying speed-bin requirements, and Taiwan-based packaging integrators enabling high-density stacks. Competitive moves center on backward integration into advanced node DRAM production and strategic partnerships for allocation priority in supply-constrained 20 Gbps speed grades.
Among Korean memory fabricators, Samsung Electronics and SK hynix occupy positions as the dominant merchant suppliers, with Samsung leveraging captive DRAM production for internal GPU consumption. Taiwan-based TSMC represents the packaging integration archetype through its CoWoS ecosystem. California-based NVIDIA and AMD exemplify the GPU architecture tier that dictates JEDEC specification evolution through volume procurement leverage.
| Leading Market Players |
|---|
| AMD |
| Qualcomm |
| Samsung Electronics |
| NVIDIA |
| Tenstorrent |
| SK hynix |
| Intel |
| TSMC |
| Micron Technology |
| Others |
Supply & Pricing Matrix
TSMC's CoWoS packaging scale economies concentrate margin capture among vertically integrated memory-to-GPU pipelines, compressing price floors for merchant DRAM vendors while hyperscale buyers extract allocation priority through direct contracting. Korean foundry utilization rates above ninety percent sustain premium tier pricing power even as 16 Gbps gaming variants commoditize.
Pricing Analysis
JEDEC signal integrity specifications dictate the pricing tier structure across speed-grade stratification, separating premium 20 Gbps AI-optimized devices from standard 16 Gbps gaming silicon. Three-tier pricing structure across premium, standard, and economy levels reflects thermal package differentiation and guaranteed allocation contracts versus spot-market procurement. Cost compression in the 16 Gbps tier intensifies because console cycle maturity extends inventory normalization timelines. Gaming OEMs exhibit highest price sensitivity while hyperscale datacenter operators prioritize throughput density over unit economics.
Supply Chain Analysis
Korea Strait maritime transit underwrites raw wafer and specialty chemical flows to TSMC's CoWoS packaging complexes in Hsinchu. Advanced DRAM bit supply concentrates in South Korea, Taiwan, and Japan, drawing from EUV photoresist, fluorinated etching gases, and Megtron-6 laminate substrates. Single-source vulnerability pervades 20 Gbps speed bin production where three foundries control merchant availability. Distribution runs through Taiwan ODMs for gaming GPU assembly and direct vendor relationships for hyperscale AI cluster procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speed-grade fragmentation creates white-space niches as AI inference demand bifurcates procurement between premium thermally-enhanced tiers and cost-optimized legacy gaming silicon.
For Market Incumbents: Consolidate backward integration into advanced node DRAM production to defend margin pools against GDDR7 substitution timelines. SK hynix and Samsung Electronics should expand captive EUV lithography capacity at Pyeongtaek and Icheon to secure 20 Gbps yield economics. Locking quarterly allocation agreements with NVIDIA and AMD controller IP roadmaps preserves socket priority against emerging memory vendors. For New Entrants and Emerging Players: Automotive-grade AEC-Q100 certification fast-tracks entry into ADAS domain controller supply chains at Toyota and Honda where real-time sensor fusion specifications outstrip incumbent gaming-focused portfolios. Target India's PLI-subsidized GPU assembly clusters in Karnataka and Telangana for localized memory module testing partnerships. Lead with sub-1.1V low-power variants under Japan METI green semiconductor subsidies to differentiate from Korean incumbents' datacenter-centric positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive-qualified memory vendors with multi-year platform commitments from German and Japanese OEMs. Long-term viability across the analysis window favors suppliers with JEDEC standard-setting influence and TSMC CoWoS packaging integration depth. Monitor GDDR7 PAM-4 interoperability testing timelines as the inflection signal for 22 Gbps GDDR6 inventory risk realization.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Integration | TSMC CoWoS enables 4-Hi and 8-Hi memory stacks that double bandwidth density per accelerator card. |
| Automotive Certification Pathway | AEC-Q100 qualification opens ADAS domain controller sockets at Toyota and Honda requiring extended temperature operation. |
| Low-Power Mode Development | Sub-1.1V operating modes align with Japan METI green semiconductor subsidies for edge inference deployment. |
| Direct Hyperscale Contracting | Quarterly allocation agreements with AWS, Azure, and GCP bypass distribution margin extraction. |
| EUV Node Transition | Micron's EUV-based DRAM production tightens timing margins for next-generation controller IP compatibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with GPU platform architects, memory controller IP designers, Taiwan ODM procurement leads, and hyperscale datacenter infrastructure planners; and secondary validation against JEDEC standardization documents, SEC semiconductor capex disclosures, and Korea Customs Service trade statistics. Bottom-up wafer start modeling triangulated against top-down GPU shipment forecasts from NVIDIA and AMD supply chain disclosures.
Across the projection horizon, the analytical framework modeled speed-grade segmentation, thermal package tiering, application-specific procurement channels, and regional regulatory cluster effects. CAGRs derived from bit-demand elasticity against AI training cluster deployment curves and gaming GPU inventory normalization patterns. Forecast inputs incorporated TSMC CoWoS capacity expansion timelines and EU F-Gas Regulation chemistry transition constraints.
Decision-makers should treat outputs as directional under assumptions of JEDEC interoperability timeline stability and Korean-Taiwanese fabrication concentration persistence; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as GDDR7 commercialization schedules and India PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
NAND-Based Multi-Chip Packages Market
Memory Chips
DDR RAM Market
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
DRAM Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
Memristor Market
Memory Chips
Mobile DRAM Market
Memory Chips
Japan DRAM Market
Memory Chips
New RAM Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Memory IC Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Automotive DRAM Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
Memory Market