
 MRAM Market | 2026-2036
MRAM Market Size, Share, and Industry Trends Forecast 2026-2036
MRAM Market Outlook
Magnetic tunnel junction scaling below 20nm is reconfiguring how foundries integrate non-volatile memory with logic dies. Everspin Technologies sustains technology leadership in discrete STT-MRAM devices for aerospace and industrial grade applications. Samsung Electronics leverages its captive DRAM and NAND expertise to accelerate embedded MRAM roadmaps at advanced process nodes. TSMC anchors foundry-based MRAM production, offering embedded options from 22nm down to emerging 5nm-class platforms.
MRAM (magnetoresistive random-access memory) stores data through magnetic spin orientation in ferromagnetic layers separated by thin insulating barriers, typically MgO tunnel junctions measuring 1-2nm, enabling sub-10ns write speeds with unlimited endurance and zero standby power. Embedded MRAM dominates current wafer starts as microcontroller and SoC designers replace external flash and SRAM to reduce pin count and board area. Standalone MRAM competes in niche high-reliability segments where radiation tolerance and extended temperature operation justify premium positioning over conventional NAND. Spintronic technology underpins all commercial variants, with STT-MRAM representing the dominant switching mechanism and voltage-controlled approaches emerging for lower-power operation.
FDA oversight of medical device data integrity and NHTSA functional-safety requirements for automotive electronics shape MRAM qualification protocols in the United States. The EU AI Act and MDR cybersecurity mandates are expanding non-volatile memory requirements for traceability and fail-safe logging in edge devices. Stakeholders must monitor how ISO 26262 automotive safety integrity levels and IEC 61508 industrial standards evolve to accommodate emerging MRAM failure modes distinct from floating-gate and ferroelectric alternatives.
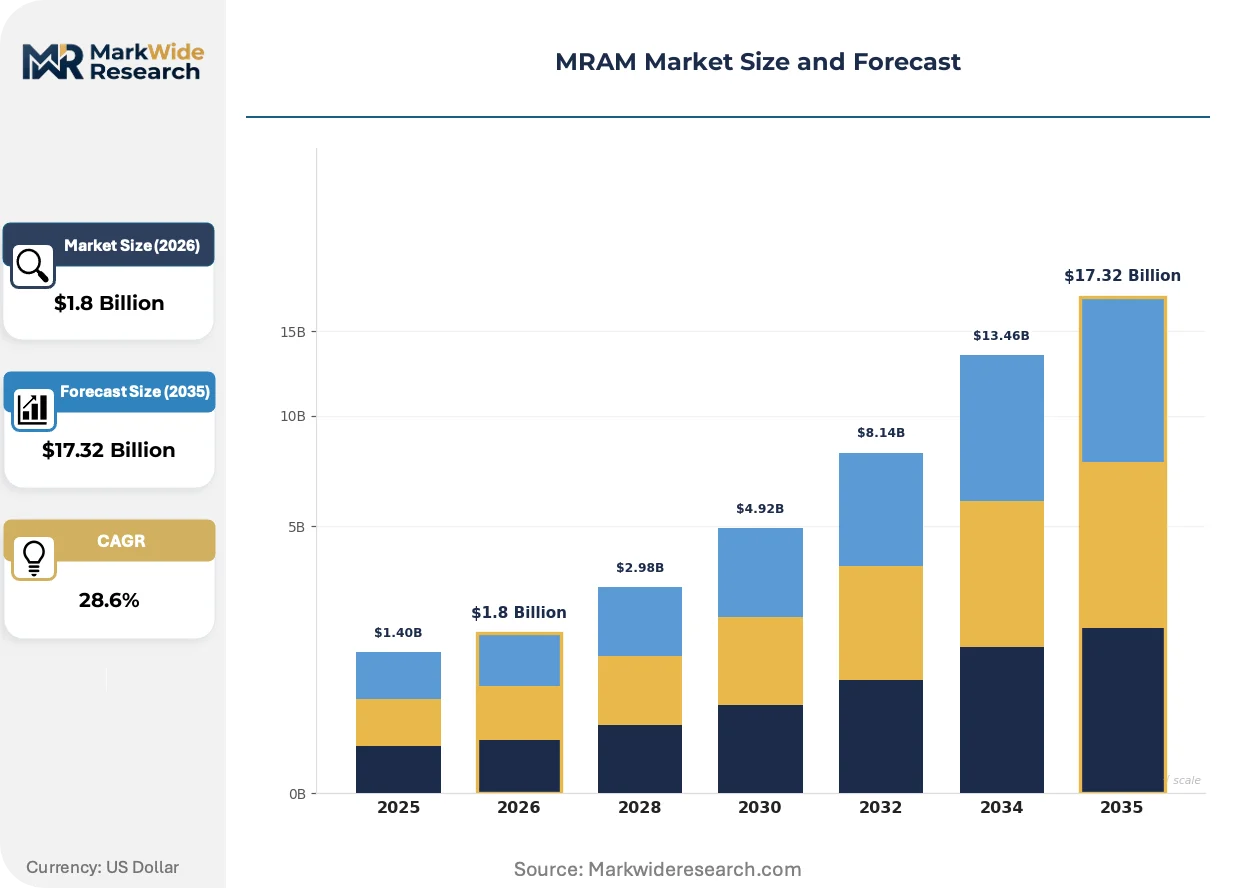
Market Dynamics
Magnetic tunnel junction scaling below 20nm is forcing foundries to reconfigure process flows as embedded MRAM displaces external flash in automotive SoCs and industrial microcontrollers. This structural shift concentrates wafer starts at advanced nodes while tightening material specifications for MgO barriers and ferromagnetic stacks.
Growth Catalysts
- Automotive functional-safety mandates:ISO 26262 ASIL-D requirements for ADAS and powertrain modules are mandating non-volatile memory with unlimited write endurance. MRAM meets these specifications where flash fails.
- Japan's semiconductor cluster policy:METI-backed subsidies for Kumamoto and Hiroshima fabs are expanding captive MRAM production capacity for domestic automotive and industrial customers.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases used in semiconductor etching processes are accelerating adoption of alternative patterning technologies compatible with MRAM magnetic stack deposition.
Market Restraints
- Equipment capex concentration:Sputtering systems for magnetic thin-film deposition require specialized vacuum chambers; supply concentrates among Japanese and German tool vendors, creating single-source vulnerability.
- Yield sensitivity to MgO uniformity:Tunnel barrier thickness variation of even 0.1nm degrades tunnel magnetoresistance ratios, constraining die-per-wafer economics at nodes below 22nm.
- Ferroelectric RAM substitution:F-RAM offers comparable endurance with lower switching voltage in low-density applications, capturing socket wins in smart meters and medical wearables.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor assembly and testing are attracting MRAM packaging investments to serve domestic automotive and telecom equipment markets.
- Space and radiation-hardened applications:Total ionizing dose tolerance above 1Mrad(Si) positions STT-MRAM for satellite avionics and deep-space probes where flash and SRAM fail.
- EU AI Act traceability mandates:Edge AI devices must maintain immutable audit logs; embedded MRAM provides tamper-resistant local storage for model versioning and inference records.
Industry Challenges
- Spintronic device physics expertise gap:Commercial MRAM design requires rare combinations of magnetism, quantum tunneling, and CMOS integration skills; universities produce fewer than 200 qualified graduates annually.
- ISO 26262 qualification timelines:Automotive safety integrity level certification for new memory technologies demands 18-24 months of fault-injection testing and field data accumulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRAM Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded MRAM, Standalone MRAM, Matrix MRAM, Others End User: Consumer Electronics, Automotive Suppliers, Aerospace, Industrial Automation Application: Data Storage, Cache Memory, Wearable Devices, Telecommunication Technology: Spintronic, CMOS Integration, STT-MRAM, Voltage Control |
| Companies Covered | Honeywell International, Everspin Technologies, Samsung Electronics, NVE Corporation, Avalanche Technology, TSMC, Infineon Technologies, SK Hynix, Intel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRAM Market Strategic Shifts
Voltage-controlled magnetic anisotropy switching is emerging as a lower-power alternative to spin-transfer torque, reshaping power budgets for battery-operated edge devices. These three developments are restructuring competitive positioning across the memory hierarchy.
STT-MRAM is digitizing storage-class memory hierarchies by embedding non-volatile buffers directly on processor dies. Hyperscale data center operators are piloting 1Gb discrete devices for persistent memory pools in AI training accelerators. This integration is digitizing board-level architecture by eliminating DIMM slots and reducing memory-access latency to sub-50ns.
REACH restrictions on cobalt and nickel compounds are forcing magnetic stack redesigns toward cobalt-iron-boron alloys with reduced heavy metal content. The EU's chemicals regulator is tightening substance authorization timelines for semiconductor precursors. European foundries are accelerating qualification of alternative ferromagnetic materials to maintain CE marking compliance for automotive shipments.
Certification-driven procurement is compressing vendor selection cycles as automotive Tier-1s pre-qualify MRAM suppliers against AEC-Q100 Grade 0 standards. Long-term supply agreements now bundle foundry wafer allocation with in-house test and burn-in capacity. This pattern is most visible in Germany, where KBA type-approval requirements for powertrain ECUs mandate traceable memory component sourcing.
MRAM Market Segmentation
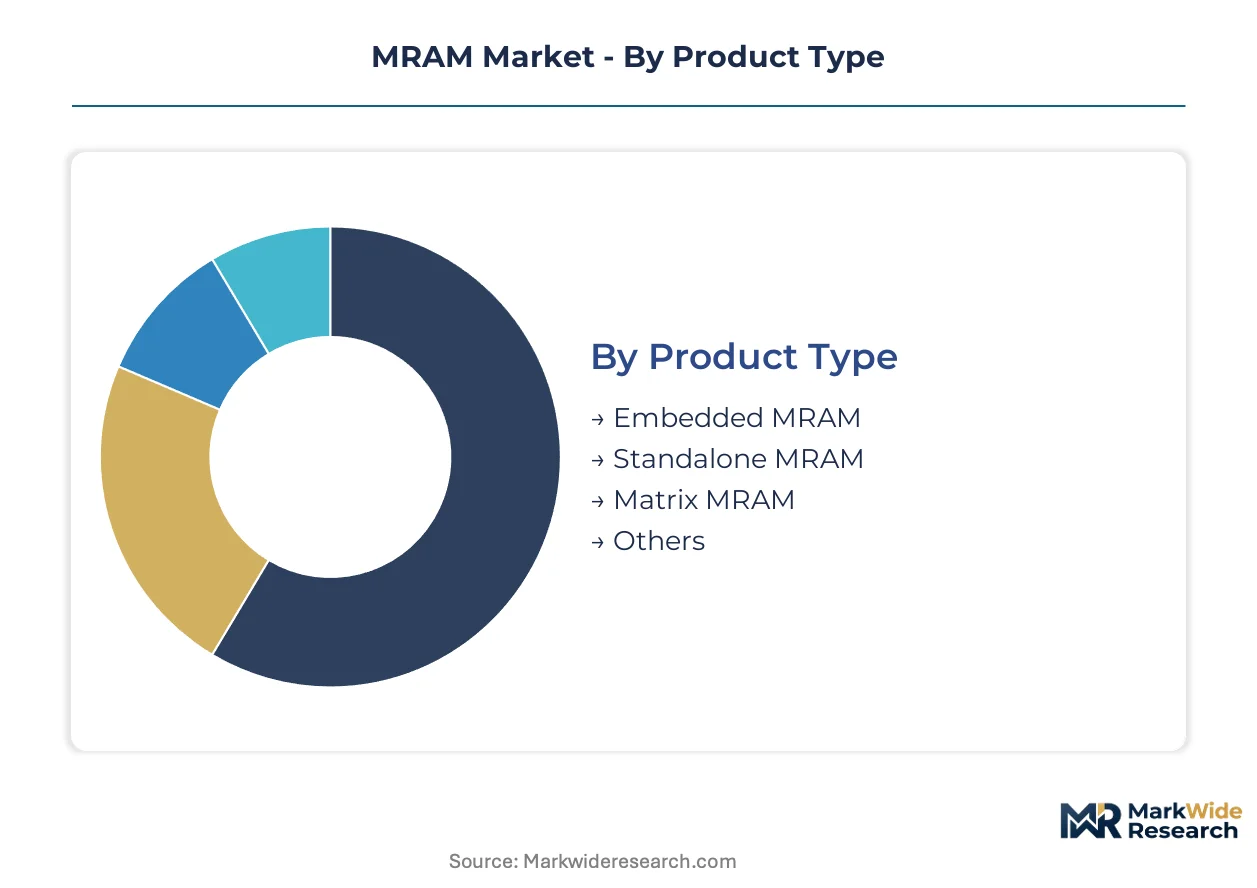
MRAM segmentation reveals how magnetic memory technology splinters across integration levels, end-use reliability requirements, and switching physics. Each dimension carries distinct qualification protocols, pricing structures, and supply chain dependencies that shape vendor strategies.
Product Type:
After-sales service intensity varies sharply across product types, with standalone devices demanding field failure analysis and embedded variants requiring foundry-level yield support.
- Embedded MRAM:Integrated directly onto SoC or microcontroller dies alongside logic transistors, eliminating external memory packages. Automotive suppliers in Germany and Japan dominate procurement as ISO 26262 ASIL-D compliance drives replacement of external flash in powertrain ECUs.
- Standalone MRAM:Packaged as discrete memory components in standard JEDEC footprints for board-level deployment. Aerospace and satellite manufacturers in the US absorb volume where radiation tolerance above 1Mrad(Si) justifies premium positioning over conventional NAND.
- Matrix MRAM:Crossbar array architectures targeting high-density storage applications with simplified lithography requirements.
- Others:Emerging variants including multi-level cell configurations and hybrid magnetic-ferroelectric devices.
By volume, Embedded MRAM leads. By growth pace, Standalone MRAM is ahead.
End User:
Cost tier stratification separates qualification-intensive automotive and aerospace buyers from price-sensitive consumer electronics procurement.
- Automotive Suppliers:Tier-1 ECU manufacturers mandate AEC-Q100 Grade 0 qualification with full traceability. KBA type-approval requirements in Germany and NHTSA functional-safety protocols in the US extend certification timelines to 18-24 months.
- Aerospace:Satellite avionics and deep-space probe programs specify total ionizing dose tolerance and extended temperature operation. NASA and ESA mission requirements drive adoption where flash endurance failure risks mission loss.
- Consumer Electronics:Smartphones and tablets prioritize bit density and unit cost over endurance specifications.
- Industrial Automation:Factory controllers and robotics systems require deterministic write latency for real-time control loops.
By revenue concentration, Automotive Suppliers lead. By expansion trajectory, Aerospace is climbing the fastest.
Application:
Volume distribution tracks the displacement of incumbent memory technologies across latency-sensitive and endurance-critical use cases.
- Cache Memory:Last-level cache replacement in AI accelerators and high-performance computing. Hyperscale operators in the US pilot 1Gb devices for persistent memory pools with sub-50ns access latency.
- Data Storage:Non-volatile buffers and logging applications requiring unlimited write cycles. EU AI Act traceability mandates for edge devices are accelerating immutable audit log implementations.
- Wearable Devices:Ultra-low-power requirements for fitness trackers and medical monitors.
- Telecommunication:Baseband processing and buffer memory in 5G infrastructure equipment.
By deployment scale, Data Storage leads. By technology pull, Cache Memory is gaining share fastest.
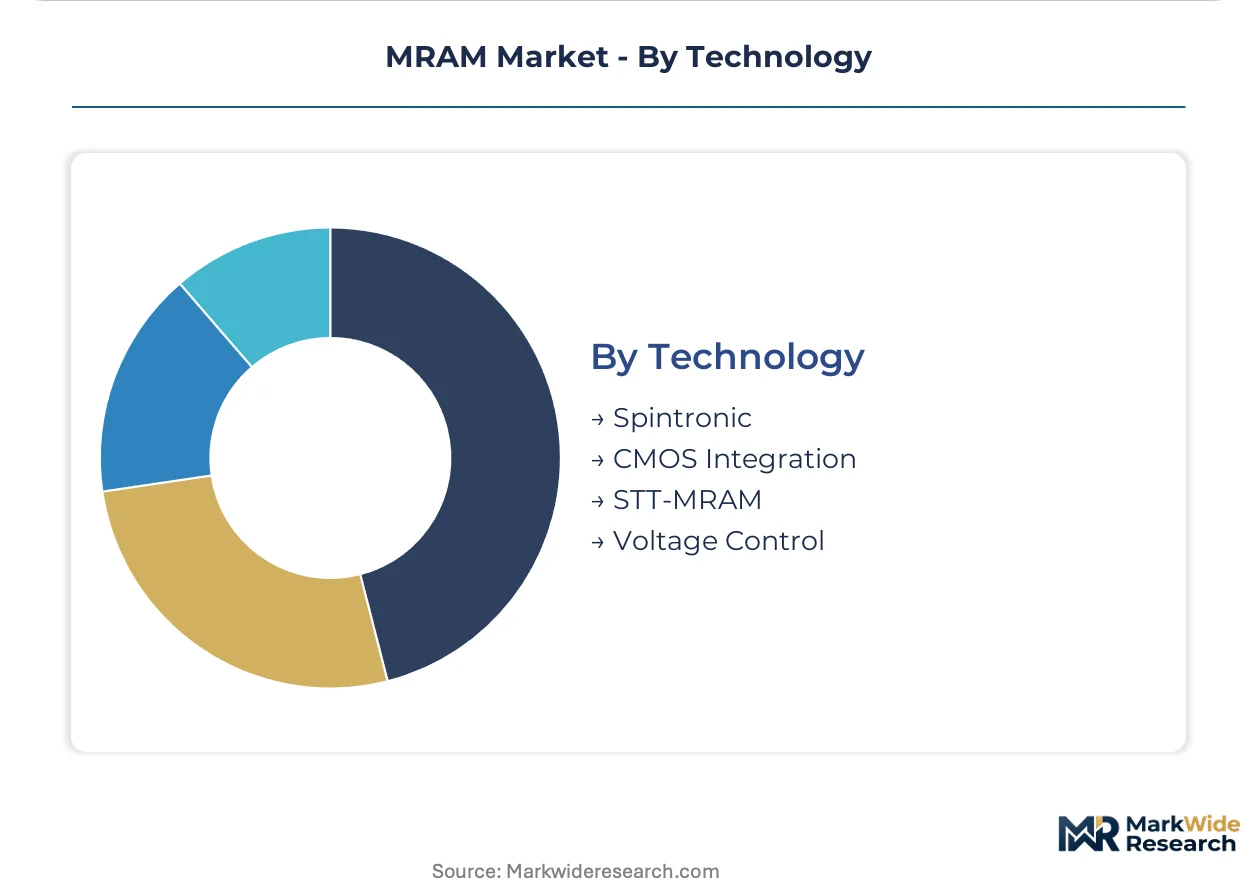
Technology:
Margin structures diverge between mature spin-transfer torque production and emerging voltage-controlled approaches requiring new equipment investment.
- STT-MRAM:Dominant commercial switching mechanism using spin-polarized current through magnetic tunnel junctions. TSMC and Samsung anchor foundry production at nodes from 22nm to emerging 5nm-class platforms.
- Voltage Control:Voltage-controlled magnetic anisotropy switching reduces write energy by eliminating spin-polarized current paths. Battery-operated edge devices in Japan and South Korea are piloting these structures for power budget extension.
- Spintronic:Foundational physics encompassing all magnetic memory variants based on electron spin manipulation.
- CMOS Integration:Process flow compatibility with standard logic fabrication enabling monolithic SoC embedding.
By manufacturing maturity, STT-MRAM leads. By development investment, Voltage Control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive Tier-1 suppliers in Germany and Japan drive qualification-intensive procurement, while aerospace buyers in the United States absorb radiation-hardened volumes. Foundry investments in Taiwan and South Korea concentrate advanced-node production capacity.
United States
NASA and defense contractors specify total ionizing dose tolerance above 1Mrad(Si) for satellite avionics. NHTSA functional-safety protocols extend automotive certification timelines to 18-24 months. Greater Boston hosts Everspin Technologies, which sustains technology leadership in discrete STT-MRAM devices for aerospace applications.
Germany
Tier-1 ECU manufacturers mandate AEC-Q100 Grade 0 qualification with full traceability for powertrain modules. KBA type-approval requirements enforce traceable memory component sourcing for automotive shipments. Bavaria anchors foundry partnerships serving domestic automotive clusters with embedded MRAM at advanced nodes.
Japan
METI-backed subsidies for Kumamoto and Hiroshima fabs expand captive MRAM production capacity. The country's semiconductor cluster policy strengthens domestic supply chains for automotive and industrial customers. Tokyo-based equipment vendors concentrate sputtering system supply for magnetic thin-film deposition.
Taiwan
TSMC anchors foundry-based MRAM production from 22nm down to emerging 5nm-class platforms. The Kumamoto fab expansion strengthens regional supply chain integration with Japanese automotive customers. Hsinchu Science Park concentrates process development expertise for magnetic tunnel junction scaling below 20nm.
South Korea
Samsung Electronics leverages captive DRAM and NAND expertise to accelerate embedded MRAM roadmaps. Battery-operated edge device manufacturers pilot voltage-controlled magnetic anisotropy structures for power budget extension. Seoul Capital Area hosts SK Hynix, which occupies a position within the memory semiconductor archetype.
MRAM Market Competitive Environment
Channel-controlling players compete with product-specialist players across qualification tiers. The market structures around three layers: captive foundry operations, discrete device specialists, and diversified memory conglomerates. Strategic archetypes include radiation-hardened niche suppliers, automotive-grade embedded memory providers, and hyperscale data center solution vendors. Dominant competitive moves center on foundry capacity allocation agreements and long-term automotive pre-qualification contracts.
Within the radiation-hardened and industrial-grade tier, Everspin Technologies and Avalanche Technology exemplify specialist positioning. Among diversified technology conglomerates, Honeywell International and Samsung Electronics occupy positions spanning aerospace, automotive, and consumer applications. Intel represents the integrated device manufacturer archetype with captive fabrication and system-level integration capabilities. TSMC anchors the pure-play foundry vector, offering embedded MRAM options across multiple customer designs without competing in end-products.
| Leading Market Players |
|---|
| Honeywell International |
| Everspin Technologies |
| Samsung Electronics |
| NVE Corporation |
| Avalanche Technology |
| TSMC |
| Infineon Technologies |
| SK Hynix |
| Intel |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese sputtering equipment for magnetic thin-film deposition determines both pricing tier spreads and supply chain shape in the MRAM market. Foundries absorb premium pricing for AEC-Q100 Grade 0 qualified wafers while automotive Tier-1s lock in multi-year offtake agreements to secure capacity.
Pricing Analysis
Cost-plus contracts with cobalt and nickel compound indexation dominate long-term automotive supply agreements. Three-tier pricing structure across radiation-hardened aerospace, automotive-grade embedded, and industrial standard tiers separates qualification-intensive buyers from cost-sensitive consumer segments. Pricing pressure stems from F-RAM substitution in low-density medical wearables and smart meters. Consumer electronics procurement teams exhibit highest price sensitivity, while satellite manufacturers accept premium positioning for total ionizing dose tolerance above 1Mrad(Si).
Supply Chain Analysis
Extended payment terms from automotive Tier-1s and supply-chain finance facilities from Japanese equipment vendors stabilize working capital across the MRAM value chain. Manufacturing concentrates in Taiwan, Japan, and South Korea where TSMC, Samsung, and METI-backed Kumamoto fabs anchor production. Raw material dependencies center on MgO tunnel barriers, cobalt-iron-boron alloys, and specialized sputtering targets. Single-source vulnerability on Japanese vacuum chamber systems creates structural risk. Distribution runs through foundry direct sales for embedded variants and specialized distributors for discrete aerospace components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
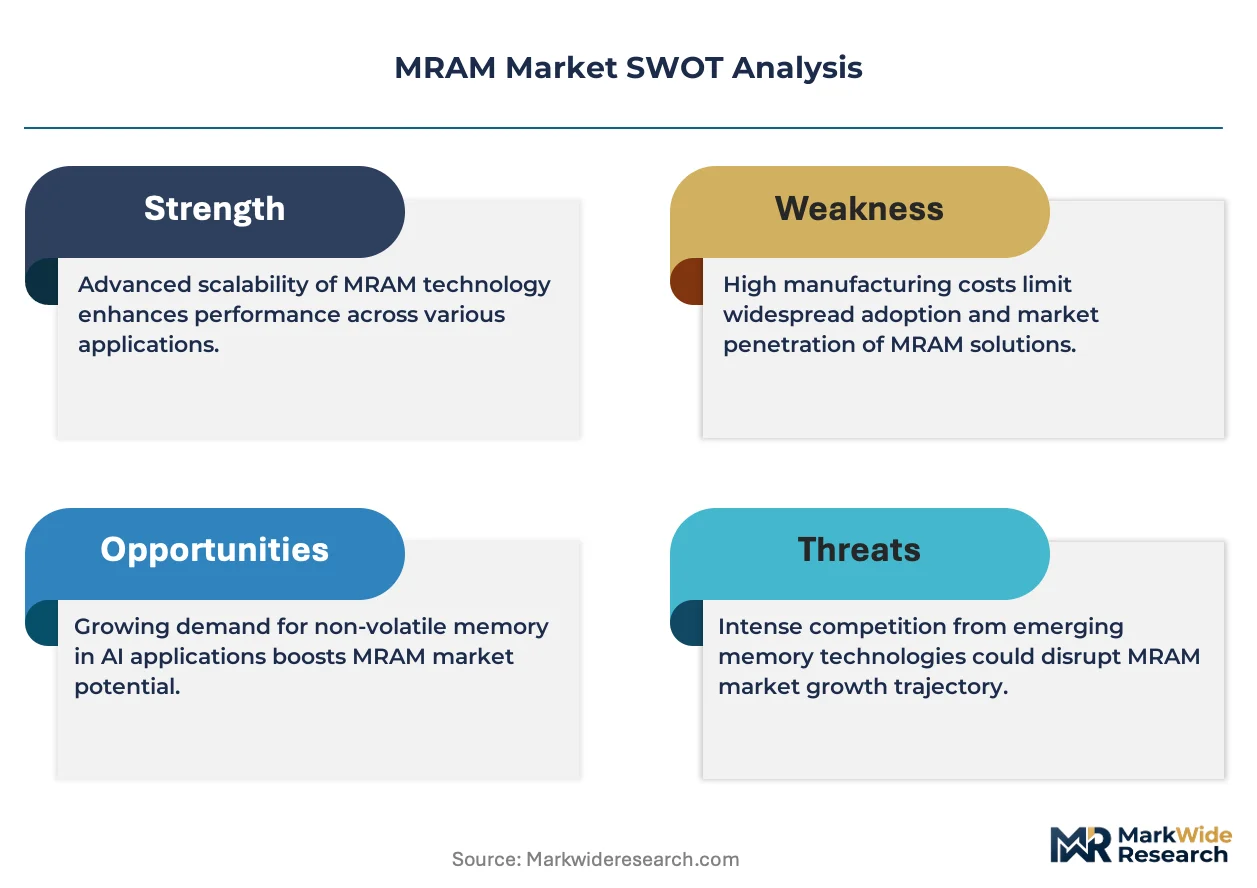
Fragmentation opportunity emerges as automotive functional-safety mandates splinter demand across ASIL-D qualified embedded suppliers, radiation-hardened discrete specialists, and voltage-controlled technology pioneers.
For Market Incumbents: Harden market position through captive sputtering equipment capacity in Japan and accelerated ISO 26262 qualification timelines. Defensive consolidation should target automotive pre-qualification contracts bundling foundry wafer allocation with in-house test and burn-in capacity. Ferroelectric RAM substitution in medical wearables represents the primary substitute threat requiring response through voltage-controlled magnetic anisotoxy development. For New Entrants and Emerging Players: India's PLI scheme for semiconductor assembly and testing represents the most penetrable entry point for MRAM packaging investments serving domestic automotive and telecom equipment markets. Voltage-controlled switching technology for battery-operated edge devices in South Korea offers second white-space opportunity. Go-to-market angle should emphasize power budget extension for AI inference at the edge. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors spintronic device physics specialists with automotive certification momentum. Long-term viability across a 5-10 year window rests on foundry capacity allocation agreements rather than discrete device manufacturing scale. Acquisition target archetype: embedded MRAM design houses with TSMC or Samsung process development relationships. Signal to watch: voltage-controlled magnetic anisotoxy pilot adoption rates in Japanese consumer electronics.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Pre-Qualification Contracting | Locks in 18-24 month ISO 26262 certification timelines with German Tier-1 ECU manufacturers. |
| Voltage-Controlled Technology Development | Reduces write energy for battery-operated edge devices competing with F-RAM in South Korea. |
| India PLI Scheme Participation | Captures packaging investments serving domestic automotive clusters under DGFT incentives. |
| Sputtering Equipment Backward Integration | Mitigates single-source risk on Japanese vacuum chamber suppliers for magnetic stack deposition. |
| Space Qualification Acceleration | Positions STT-MRAM for NASA and ESA satellite avionics where flash endurance fails. |
Study Parameters
A spread of perspectives from foundry process engineers, automotive Tier-1 procurement directors, aerospace component qualification leads, and spintronic device physicists converged on the working assumptions. Primary interviews combined with secondary validation from SEC filings, METI semiconductor cluster reports, TSMC technology disclosure documents, and ESA mission requirement specifications. Bottom-up wafer start estimates and top-down memory market sizing triangulated across the analysis window.
Demand-supply-balance framing anchored the forecast framework across product type, end user reliability tier, switching technology, and regional production cluster dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating automotive ECU content per vehicle trends, satellite launch manifests, and edge AI device shipment patterns. Voltage-controlled magnetic anisotoxy development timelines and EU F-Gas Regulation compliance costs fed industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles, automotive production volumes, or rare earth magnet pricing would shift the trajectory. Forecasts reflect documented assumptions on foundry yield ramp rates and automotive certification timeline adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Magneto Resistive RAM (MRAM) Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
Memristor Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
China Dynamic Random Access Memory (DRAM) Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
Memory Chip Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
DDR RAM Market
Memory Chips
In-Memory Computing Market