
 Global Argatroban Market | 2026-2036
Global Argatroban Market Size, Share, and Industry Trends Forecast 2026-2036
Global Argatroban Market Foresight
EU MDR is realigning the cost-of-entry calculus for anticoagulant manufacturers seeking CE-marked argatroban products. Mitsubishi Tanabe Pharma leverages its originator heritage and Japanese manufacturing base to sustain supply continuity across regulated markets. Pfizer Inc anchors its position through hospital channel control and critical-care portfolio breadth. Fresenius Kabi competes on parenteral manufacturing scale and European distribution density.
Argatroban is a synthetic direct thrombin inhibitor derived from L-arginine, administered intravenously with a half-life of approximately 39-51 minutes and hepatic metabolism that eliminates the need for dose adjustment in renal impairment. Its primary purpose is anticoagulation in patients with heparin-induced thrombocytopenia requiring rapid, reversible anticoagulation. Injection solution formulations dominate hospital procurement due to immediate usability in critical care settings, while lyophilized powder formats serve markets where cold-chain logistics remain constrained. Heparin-induced thrombocytopenia therapy areas generate the most concentrated demand, though percutaneous coronary intervention applications represent a growing procedural use case as interventional cardiology volumes expand.
FDA, EMA, and PMDA each enforce distinct pharmacovigilance and GMP standards that shape batch release timelines, labeling requirements, and post-market surveillance obligations for argatroban suppliers. The FDA's Risk Evaluation and Mitigation Strategy frameworks for anticoagulants add compliance layers that favor established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving thrombin inhibitor guidelines from cardiology societies and hematology associations that could expand or contract procedural indications.
Market Dynamics
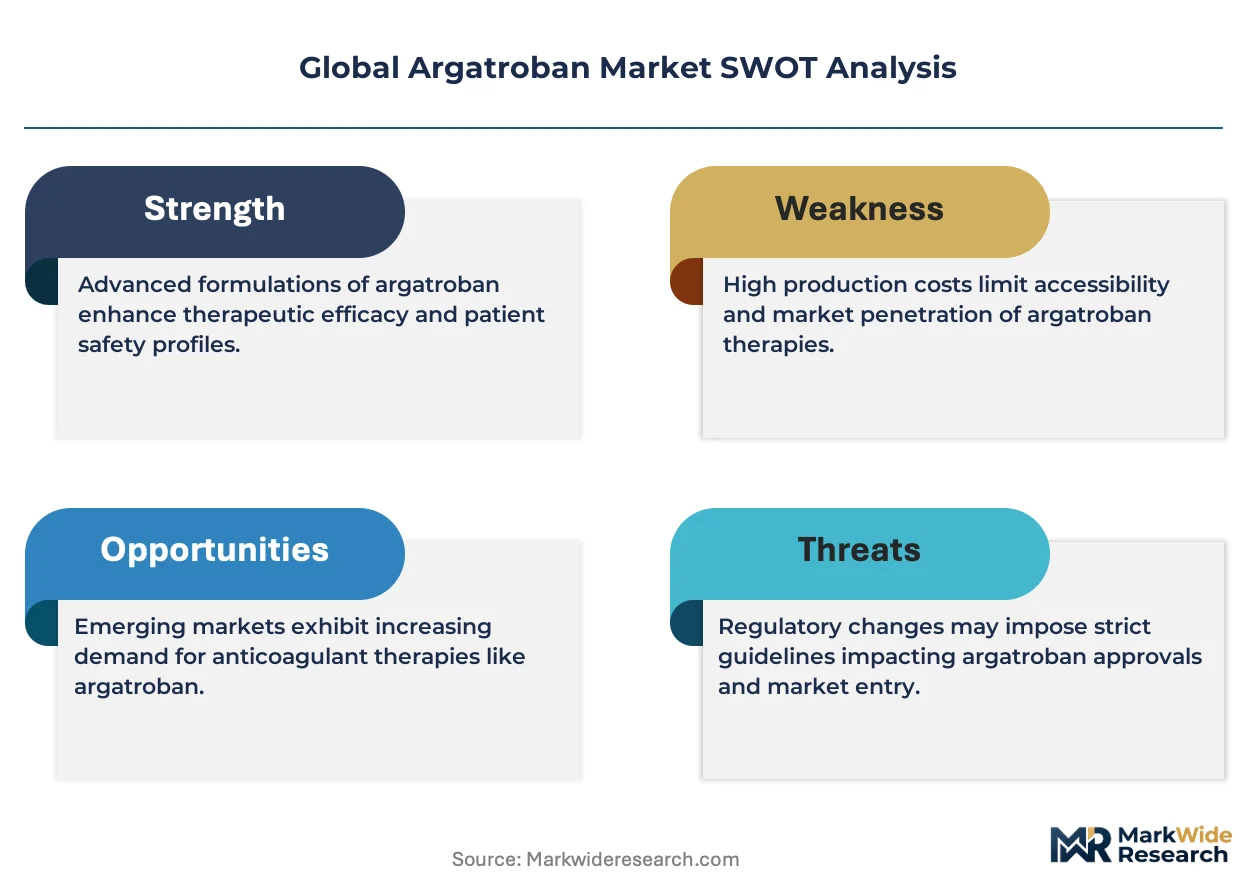
Hospital procurement consolidation is compressing argatroban supplier margins while FDA Risk Evaluation and Mitigation Strategy frameworks elevate compliance costs for new entrants. Direct thrombin inhibitor demand concentrates in tertiary cardiac centers managing heparin-induced thrombocytopenia cases.
Growth Catalysts
- PCI volume expansion:Interventional cardiology procedural growth in the United States sustains periprocedural anticoagulation demand. Academic medical centers drive concentrated purchasing power for direct thrombin inhibitors.
- EU MDR alignment:Updated medical device regulations in Europe are streamlining quality benchmarks for parenteral anticoagulant manufacturing. Established suppliers leverage CE-marking continuity to defend hospital formulary positions.
- Hepatic metabolism advantage:Argatroban's non-renal clearance pathway addresses the expanding chronic kidney disease patient population requiring anticoagulation. Nephrology-critical care cross-disciplinary protocols favor this pharmacokinetic profile.
Market Restraints
- Input cost volatility:L-arginine derivative synthesis depends on amino acid feedstock pricing subject to agricultural commodity fluctuations. Japanese and Chinese API sourcing concentrates exposure.
- Substitution threat:Bivalirudin and fondaparinux compete for PCI and HIT indications with comparable efficacy profiles. Payer formularies in Germany and France actively promote therapeutic interchange.
- Regulatory friction:FDA pharmacovigilance requirements for anticoagulants mandate extensive post-market surveillance infrastructure. Batch release timelines extend for manufacturers lacking dedicated REMS compliance teams.
Strategic Opportunities
- Brazil market entry:ANVISA regulatory pathways for essential medicines create accelerated approval tracks for established anticoagulant suppliers. Private hospital networks in São Paulo and Rio de Janeiro represent concentrated demand nodes.
- Lyophilized format expansion:Powder formulations eliminate cold-chain dependencies for rural and emerging market distribution. This technology convergence with ambient-stable packaging opens procurement channels outside tertiary hospital networks.
- Critical care protocol integration:ICU sedation-analgesia-anticoagulation bundled order sets in US academic centers create formulary stickiness. Vendor partnerships with electronic health record platforms embed product-specific dosing algorithms.
Industry Challenges
- Specialized manufacturing workforce scarcity:Parenteral GMP facility operators with sterile injectable experience command premium compensation. Training pipelines for aseptic processing technicians lag facility expansion timelines.
- Legacy system integration friction:Hospital pharmacy information systems require custom interface development for real-time inventory management of high-cost anticoagulants. Implementation timelines delay automated dispensing cabinet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Argatroban Market |
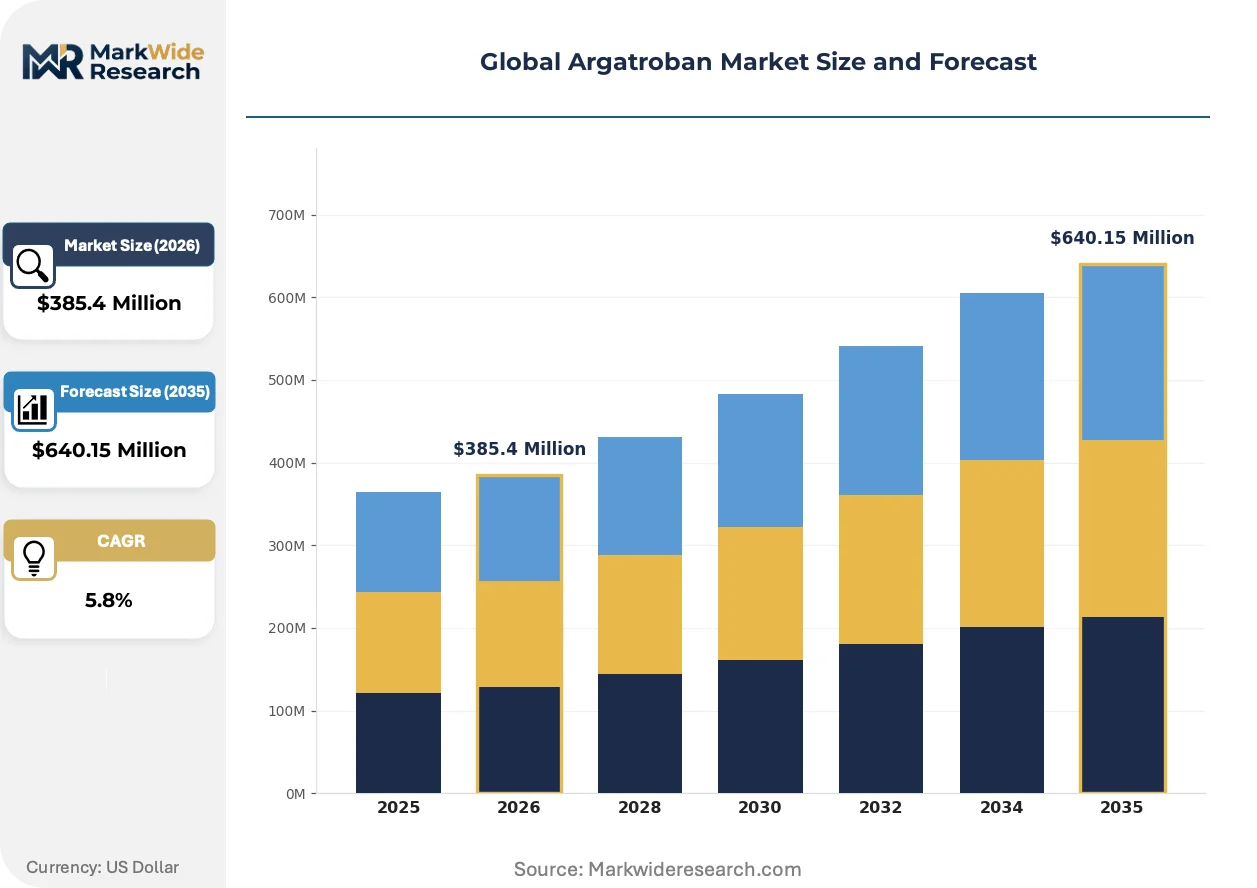
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Solution, Concentrate, Pre-mixed Bag, Lyophilized Powder Therapy Area: Heparin-Induced Thrombocytopenia, Anticoagulation in PCI, Deep Vein Thrombosis, Pulmonary Embolism, Acute Coronary Syndrome End User: Specialty Clinics, Ambulatory Surgical Centers, Blood Banks, Research Laboratories, Home Healthcare Providers Distribution Channel: Hospital Pharmacies, Wholesale Distributors, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Mitsubishi Tanabe Pharma, AuroMedics Pharma LLC, Pfizer Inc, Viatris Inc, Hikma Pharmaceuticals PLC, Fresenius Kabi, Teva Pharmaceutical Industries, Eagle Pharmaceuticals, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Argatroban Market Shifts & Advancements
Formulation stability engineering and regulatory data harmonization are reshaping how argatroban suppliers compete across divergent national approval frameworks. Manufacturing scale and pharmacovigilance infrastructure now separate viable competitors from marginal participants.
Lyophilized powder technology is absorbing cold-chain elimination requirements for emerging market distribution. Hospital systems in India and Southeast Asia are adopting ambient-stable formats to bypass refrigeration infrastructure gaps. This stability engineering is absorbing margin pressure from logistics cost inflation while expanding addressable geography beyond traditional injectable markets.
EMA's updated Good Manufacturing Practice Annex 1 for sterile medicinal products is mandating barrier isolation technology and continuous particulate monitoring. European manufacturing sites face capital reinvestment cycles to maintain batch release eligibility. Parenteral anticoagulant suppliers with legacy open-filling lines in Italy and Spain are accelerating facility modernization to avoid supply interruptions.
Hospital pharmacy procurement committees are consolidating anticoagulant purchasing through sole-source contracts tied to critical-care portfolio breadth. Group purchasing organizations in the United States are displacing individual hospital formulary autonomy with system-wide therapeutic class management. This concentration is most visible in integrated delivery networks across Texas and Florida, where standardized HIT protocols override individual physician preference.
Global Argatroban Market Segmentation
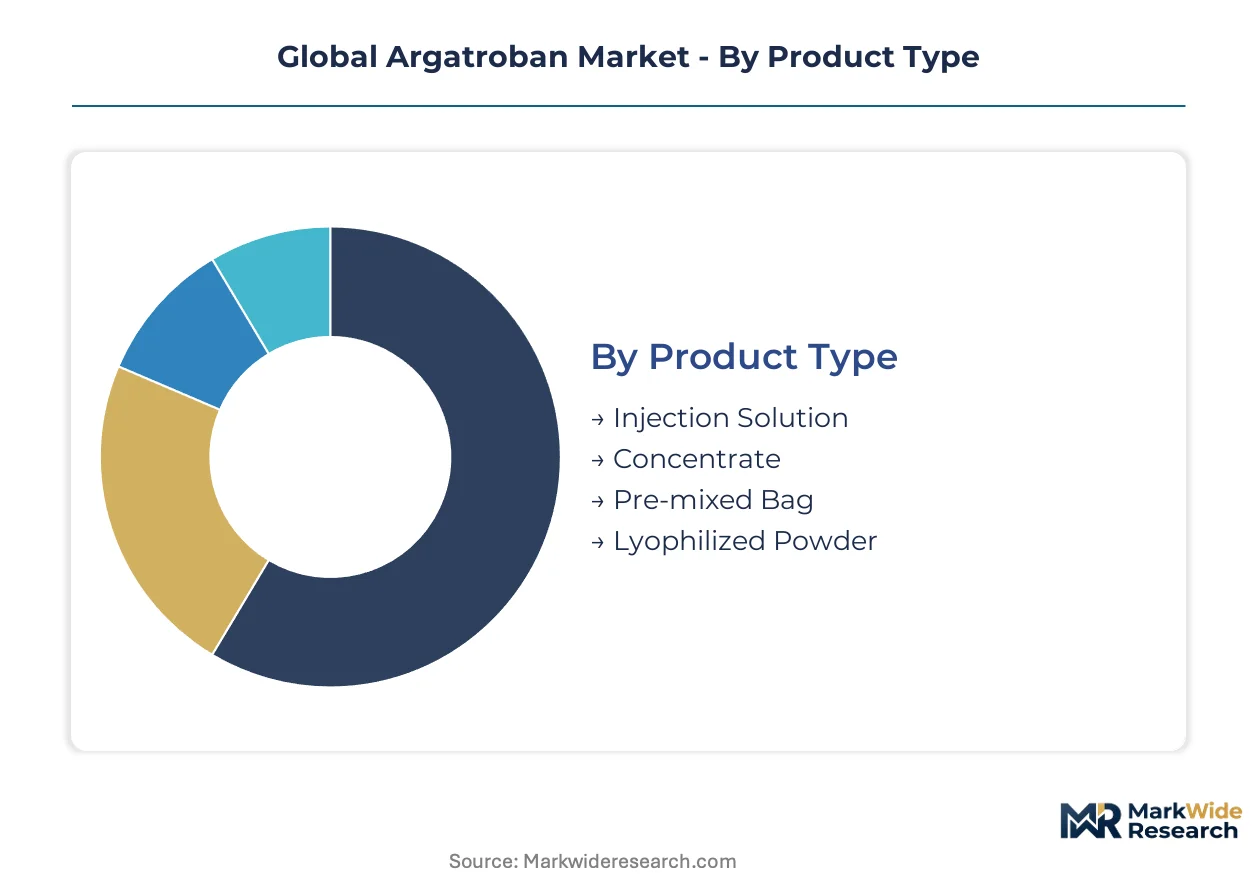
Argatroban's intravenous administration and narrow therapeutic index create distinct segmentation logic across formulation stability, clinical indication specificity, and procurement channel control. Hospital pharmacy committees prioritize immediate usability and cold-chain reliability when segmenting supplier offerings.
Product Type:
Customization intensifies from ready-to-use liquids toward powder formats requiring reconstitution, reflecting divergent infrastructure capabilities across hospital tiers and geographies.
- Injection Solution:Ready-to-use liquid formulations dominate tertiary cardiac center procurement due to elimination of compounding steps. United States academic medical centers specify this format for emergency HIT protocols where dosing speed determines clinical outcomes.
- Lyophilized Powder:Freeze-dried formulations achieve ambient stability for 24-36 months, bypassing refrigeration requirements. Indian and Southeast Asian hospital systems adopt this segment fastest where cold-chain gaps constrain injectable distribution.
- Concentrate:High-potency vials requiring dilution serve pharmacy-controlled compounding workflows in centralized hospital settings.
- Pre-mixed Bag:Manufacturer-prepared infusion bags reduce preparation errors in high-stress critical care environments.
Leading the category by volume: Injection Solution. Growing fastest: Lyophilized Powder.
Therapy Area:
Clinical application breadth spans rare immunologic emergency through routine interventional procedure, with reimbursement intensity varying sharply across indication severity.
- Heparin-Induced Thrombocytopenia:Immune-mediated platelet activation requiring immediate anticoagulant substitution generates the most concentrated demand. United States diagnosis rates and FDA REMS frameworks sustain this segment's formulary priority.
- Anticoagulation in PCI:Percutaneous coronary intervention applications expand with interventional cardiology procedural volumes. German and French payer formularies scrutinize cost-effectiveness against bivalirudin alternatives.
- Deep Vein Thrombosis:Off-label utilization in heparin-contraindicated patients supports niche demand in hematology services.
- Pulmonary Embolism:Critical care applications in massive or submassive presentations require rapid therapeutic anticoagulation.
- Acute Coronary Syndrome:Adjunctive use in unstable angina and non-ST elevation MI protocols varies by institutional guideline adoption.
HIT commands the highest unit pricing. PCI applications are expanding most quickly as procedural volumes climb.
End User:
Site-of-care distribution reflects severity stratification, with highest-acuity settings commanding premium procurement terms and formulary control.
- Specialty Clinics:Hematology and anticoagulation management centers coordinate chronic therapy transitions.
- Ambulatory Surgical Centers:Outpatient interventional facilities adopt argatroban for same-day PCI cases with HIT risk factors.
- Blood Banks:Transfusion services utilize argatroban for platelet additive solutions and apheresis anticoagulation.
- Research Laboratories:Academic medical centers source material for thrombin inhibition studies and coagulation assay development.
- Home Healthcare Providers:Infusion nursing services administer extended therapy for complex HIT cases requiring outpatient anticoagulation.
Hospital-based infusion dominates volume. Home healthcare is gaining share fastest as discharge protocols shorten inpatient stays.
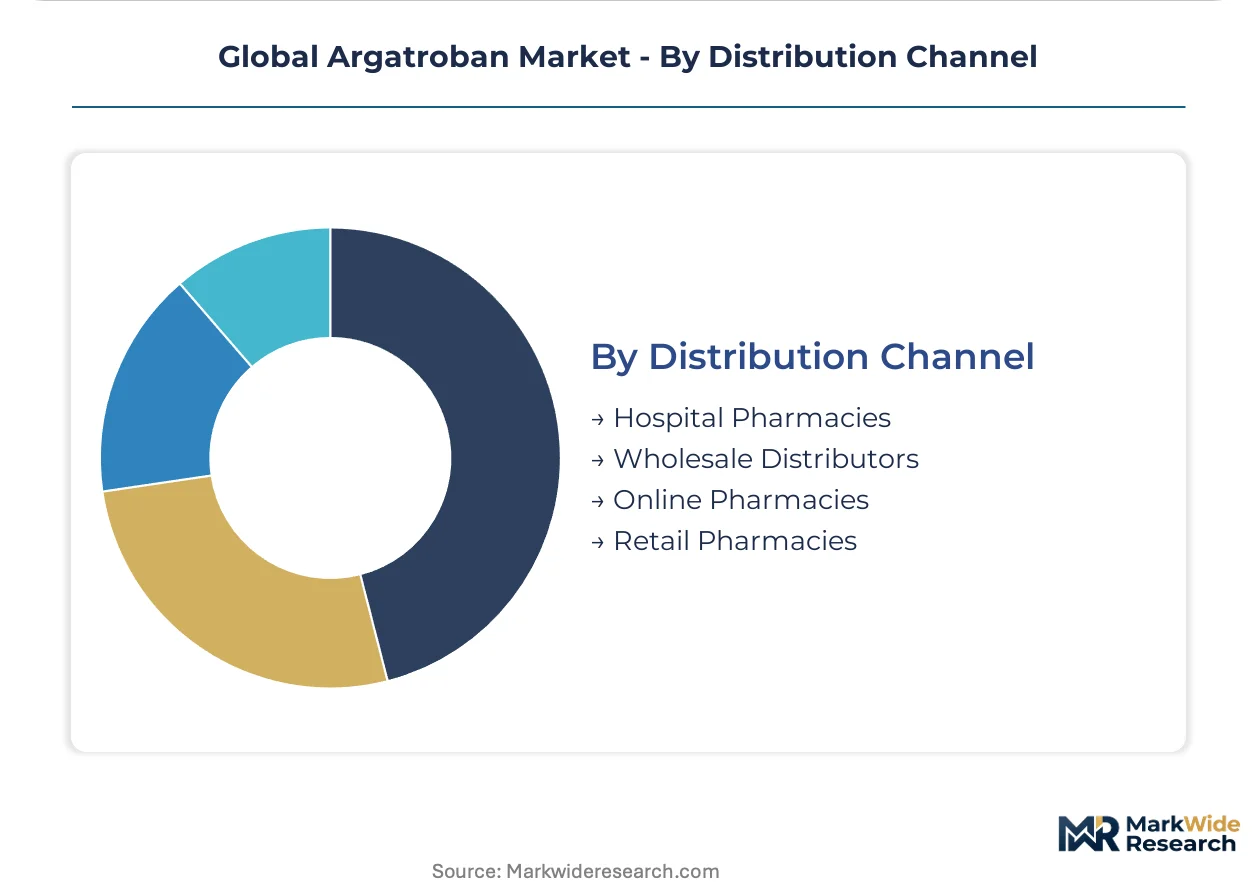
Distribution Channel:
Channel selection determines inventory visibility, with direct hospital relationships enabling real-time consumption tracking and automated replenishment.
- Hospital Pharmacies:Direct procurement through centralized pharmacy operations captures the majority of argatroban consumption. Integrated delivery networks in Texas and Florida consolidate purchasing through sole-source contracts.
- Wholesale Distributors:McKesson and Cardinal Health channel products to independent hospitals and regional systems lacking direct manufacturer relationships.
- Online Pharmacies:Digital procurement platforms serve research laboratories and specialty clinics with low-volume, high-frequency ordering patterns.
- Retail Pharmacies:Community pharmacy participation remains minimal due to parenteral administration requirements and cold-chain handling constraints.
Hospital pharmacies lead by volume. Wholesale distributors are expanding fastest as network consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement of direct thrombin inhibitors concentrates in the United States, where PCI procedural volumes and HIT diagnosis rates sustain therapeutic demand. Germany and Japan follow as secondary markets, driven by distinct regulatory frameworks and manufacturer heritage positions. Emerging adoption in India and Brazil reflects expanding critical care infrastructure and localized manufacturing incentives.
United States
Academic medical centers in Texas and Florida drive concentrated purchasing power for argatroban through integrated delivery network consolidation. FDA Risk Evaluation and Mitigation Strategy frameworks for anticoagulants elevate compliance costs that favor established suppliers with dedicated regulatory infrastructure. The Cleveland Clinic and Mayo Clinic systems anchor formulary standardization across multi-state hospital networks.
Germany
Interventional cardiology procedural growth in Bavaria and North Rhine-Westphalia sustains periprocedural anticoagulation demand. EMA pharmacovigilance requirements and updated GMP Annex 1 standards mandate barrier isolation technology investments for sterile injectable manufacturing. Berlin-based hospital pharmacy committees actively scrutinize cost-effectiveness against bivalirudin alternatives in PCI protocols.
Japan
PMDA's distinct batch release timelines and post-market surveillance obligations shape supplier selection for heparin-induced thrombocytopenia therapy. Mitsubishi Tanabe Pharma's domestic manufacturing base leverages originator heritage to sustain supply continuity across regulated Asian markets. Osaka and Tokyo metropolitan hospital networks prioritize hepatic metabolism advantages for chronic kidney disease patient populations.
India
CDSCO regulatory pathways for essential medicines create accelerated approval tracks for established anticoagulant suppliers entering private hospital networks. Lyophilized powder adoption accelerates in Maharashtra and Karnataka where cold-chain gaps constrain traditional injectable distribution. Apollo and Max Healthcare systems in Delhi-NCR and Mumbai represent concentrated demand nodes for critical care anticoagulation.
Brazil
ANVISA's streamlined approval tracks for essential medicines attract multinational suppliers to São Paulo and Rio de Janeiro private hospital markets. Ambient-stable formulation demand expands as pharmacy infrastructure outside tertiary centers lacks reliable refrigeration. Hospital Israelita Albert Einstein and Hospital Sírio-Libanês anchor procurement standardization for HIT management protocols.
Global Argatroban Market Competitive Landscape
Japanese producers anchor one tier through originator heritage and regional manufacturing continuity; European and North American specialists hold formulary positions through hospital channel control and parenteral manufacturing scale. The vendor base stratifies across three archetypes: heritage originators with API-to-finished-dose integration, generic injectable specialists with GMP sterile facility networks, and critical-care portfolio players leveraging bundled procurement contracts. Capacity expansion in lyophilized formats and strategic partnerships with electronic health record platforms constitute dominant competitive moves.
Within the heritage originator tier, Mitsubishi Tanabe Pharma exemplifies geographic anchoring through Japanese manufacturing continuity. Among North American critical-care portfolio players, Pfizer Inc occupies a position tied to hospital formulary breadth and sedation-analgesia-anticoagulation bundled order sets. Fresenius Kabi represents the European parenteral manufacturing archetype, with distribution density supporting CE-marked product defense across German and French hospital procurement committees.
| Leading Market Players |
|---|
| Mitsubishi Tanabe Pharma |
| AuroMedics Pharma LLC |
| Pfizer Inc |
| Viatris Inc |
| Hikma Pharmaceuticals PLC |
| Fresenius Kabi |
| Teva Pharmaceutical Industries |
| Eagle Pharmaceuticals |
| Sandoz |
| Others |
Supply & Pricing Matrix
Hospital formulary consolidation across integrated delivery networks in Texas and Florida forces suppliers to absorb logistics cost inflation while maintaining batch release eligibility under FDA Risk Evaluation and Mitigation Strategy frameworks. This procurement concentration shifts pricing power toward buyers with system-wide therapeutic class management authority.
Pricing Analysis
Volume concentration in injection solution formats supports margin stability at the premium tier, while lyophilized powder segments face intensifying cost compression from emerging market entrants. Pricing stratifies across originator heritage suppliers, CE-marked European specialists, and generic injectable manufacturers competing on parenteral GMP scale. Payer formularies in Germany and France actively drive therapeutic interchange toward bivalirudin alternatives, eroding argatroban pricing in PCI indications. Academic medical centers with sole-source contracts exhibit lowest price sensitivity; rural hospital systems dependent on wholesale distributors show highest.
Supply Chain Analysis
Reverse-logistics flows for expired or temperature-deviated argatroban batches remain minimal given parenteral anticoagulant destruction protocols, though lyophilized powder stability is reducing cold-chain return volumes. Active pharmaceutical ingredient synthesis concentrates in Japan and China, with L-arginine derivative feedstock sourcing exposed to agricultural commodity fluctuations. Finished dose manufacturing rests on sterile injectable capacity in Italy, Spain, and the United States under EMA and FDA GMP standards. Single-source vulnerability pervades barrier isolation technology suppliers for Annex 1 compliance. Distribution runs through hospital pharmacy direct procurement and McKesson-Cardinal wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing technician scarcity constrains sterile injectable capacity expansion, propping pricing for manufacturers with trained workforce pipelines and validated barrier isolation infrastructure.
For Market Incumbents: Anchor formulary positions through critical-care portfolio breadth and EHR-embedded dosing algorithms that create protocol stickiness. Counter bivalirudin substitution threats by emphasizing hepatic metabolism advantages in chronic kidney disease populations. Prioritize lyophilized powder capacity additions in India and Brazil to capture ambient-stable demand growth. For New Entrants and Emerging Players: Launch via private hospital network partnerships in São Paulo and Rio de Janeiro, where ANVISA accelerated approval tracks reduce regulatory barriers. Target Maharashtra and Karnataka in India with lyophilized formats bypassing cold-chain gaps. Pursue GPO contract participation in Texas and Florida integrated delivery networks as the most penetrable channel. For Investors and Strategic Acquirers: Re-rating potential sits with sterile injectable specialists possessing validated Annex 1 barrier isolation and existing argatroban API relationships, given EMA compliance timelines extending for legacy open-filling lines. Monitor FDA pharmacovigilance inspection frequency as an inflection indicator for supply discontinuation risk among marginal participants.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Powder Capacity Expansion | Ambient stability opens procurement channels in Indian and Southeast Asian hospital systems lacking refrigeration infrastructure. |
| EMA Annex 1 Compliance Investment | Barrier isolation technology validates European manufacturing sites for continued batch release eligibility under updated GMP standards. |
| EHR Platform Partnership | Embedded dosing algorithms in Epic and Cerner systems create formulary stickiness through ICU protocol integration. |
| Brazil ANVISA Registration | Accelerated approval tracks for essential medicines enable market entry into São Paulo private hospital networks. |
| Critical-Care Portfolio Bundling | Sedation-analgesia-anticoagulation order sets defend hospital formulary positions against therapeutic interchange pressures. |
Research Methodology
Independent corroboration across FDA REMS compliance documentation, EMA GMP inspection records, and hospital procurement database extracts underwrites the qualitative findings. Primary interviews with sterile injectable manufacturing executives, regulatory affairs leads, hospital pharmacy directors, and GPO contracts managers combined with secondary validation from ClinicalTrials.gov entries, formulary database snapshots, and SEC 10-K pharmaceutical segment disclosures. Bottom-up demand modeling across dosage forms and therapy areas triangulates against top-down market sizing from import-export customs records.
Comparable-period anchoring to historical PCI procedural volume trends and HIT diagnosis rate trajectories established the forecast baseline across the projection horizon. Segmentation dimensions modeled include formulation stability tier, clinical indication severity, end-user site-of-care acuity, and regional regulatory cluster complexity. CAGRs derive from logarithmic trend fitting to volume and value outputs, with explicit incorporation of EU MDR transition timelines and PMDA batch release variability as industry-specific forecast inputs.
The model assumes a particular technology adoption path for lyophilized powder stability engineering; alternative pathways for ambient-tolerant liquid formulation development would alter the outlook. Forecasts reflect assumptions regarding continued FDA REMS framework stability and EMA Annex 1 enforcement consistency. Practitioners should monitor ANVISA regulatory pathway modifications and aseptic processing technician training pipeline expansion for early signals of supply constraint easing or intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Sezary Syndrome Market