
 Europe Insulin Delivery Devices Market | 2026-2036
Europe Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Delivery Devices Market Foresight
Hospital procurement consortia across Europe is reshaping how device manufacturers reach end-users, favoring vendors with localized service networks and value-based contracting capabilities. Novo Nordisk A/S leverages its integrated diabetes care platform to sustain direct relationships with payers and clinicians. Sanofi competes through broad portfolio breadth spanning pens, pumps, and digital ecosystems. Ypsomed Holding AG anchors its position in pen needle and pump patch technologies with Swiss manufacturing precision.
Insulin delivery devices encompass mechanical and electromechanical systems engineered to administer exogenous insulin with dosing accuracy typically within ±5% variance, incorporating either prefilled cartridge mechanisms or programmable basal-bolus algorithms for glycemic management. Insulin pens occupy the largest volume share due to established reimbursement codes and patient familiarity across European markets. Smart insulin pens with Bluetooth connectivity represent the fastest-expanding delivery technology segment, as integrated dose logging and clinician data sharing reshape adherence monitoring. Continuous glucose monitoring paired pump systems command premium positioning where integrated closed-loop automation reduces hypoglycemic events.
EMA medical device oversight and the EU MDR framework enforce clinical evidence requirements and post-market surveillance that elevate barriers for new entrants while accelerating consolidation among established manufacturers. REACH compliance for device materials and the EU AI Act's emerging provisions for algorithm-driven dosing software add layered compliance obligations. Stakeholders must monitor reimbursement recalibration in France and Italy, where health technology assessment bodies weigh device cost against reduced complication expenditure.
Market Dynamics
The EU Medical Device Regulation is compressing recertification timelines and forcing manufacturers to consolidate clinical evidence portfolios ahead of May deadlines, fundamentally restructuring how device vendors allocate R&D capital across the continent.
Growth Catalysts
- Home care migration:Elderly diabetes patients in Germany, France, and Italy are transitioning from clinic-based administration to self-managed pen and pump therapy, expanding addressable device volumes.
- EMA guidance alignment:Streamlined approval pathways for combination products are reducing time-to-market for integrated glucose monitoring systems.
- Bluetooth-enabled dosing:Smart pens with dose-logging capabilities are digitizing adherence tracking and enabling remote clinician oversight.
Market Restraints
- Polymer supply concentration:Medical-grade plastics for pen housings depend on a narrow supplier base concentrated in Germany and Switzerland, exposing manufacturers to input volatility.
- MDR transition friction:The EU MDR's expanded clinical evidence requirements are extending recertification cycles and freezing portfolio decisions for mid-tier manufacturers.
- CGM substitution pressure:Continuous glucose monitoring systems paired with automated insulin delivery are displacing conventional pen-based regimens in premium reimbursement tiers.
Strategic Opportunities
- Italian regional expansion:Northern Italy's Lombardy and Veneto regions show underpenetrated pump adoption relative to diabetes prevalence, creating whitespace for localized service networks.
- EU AI Act compliance:Algorithm-driven dosing software faces emerging governance frameworks, positioning early-compliant vendors for preferred procurement status.
- Pharmacy channel digitization:Direct-to-patient platforms are bypassing traditional hospital procurement consortia and capturing recurring pen needle replenishment revenue.
Industry Challenges
- Biocompatibility certification delays:REACH-compliant material substitutions require extended cytotoxicity testing, stretching product update timelines.
- Legacy system integration:Hospital electronic health record architectures in France and Germany lack standardized APIs for smart pen data interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Delivery Devices Market |
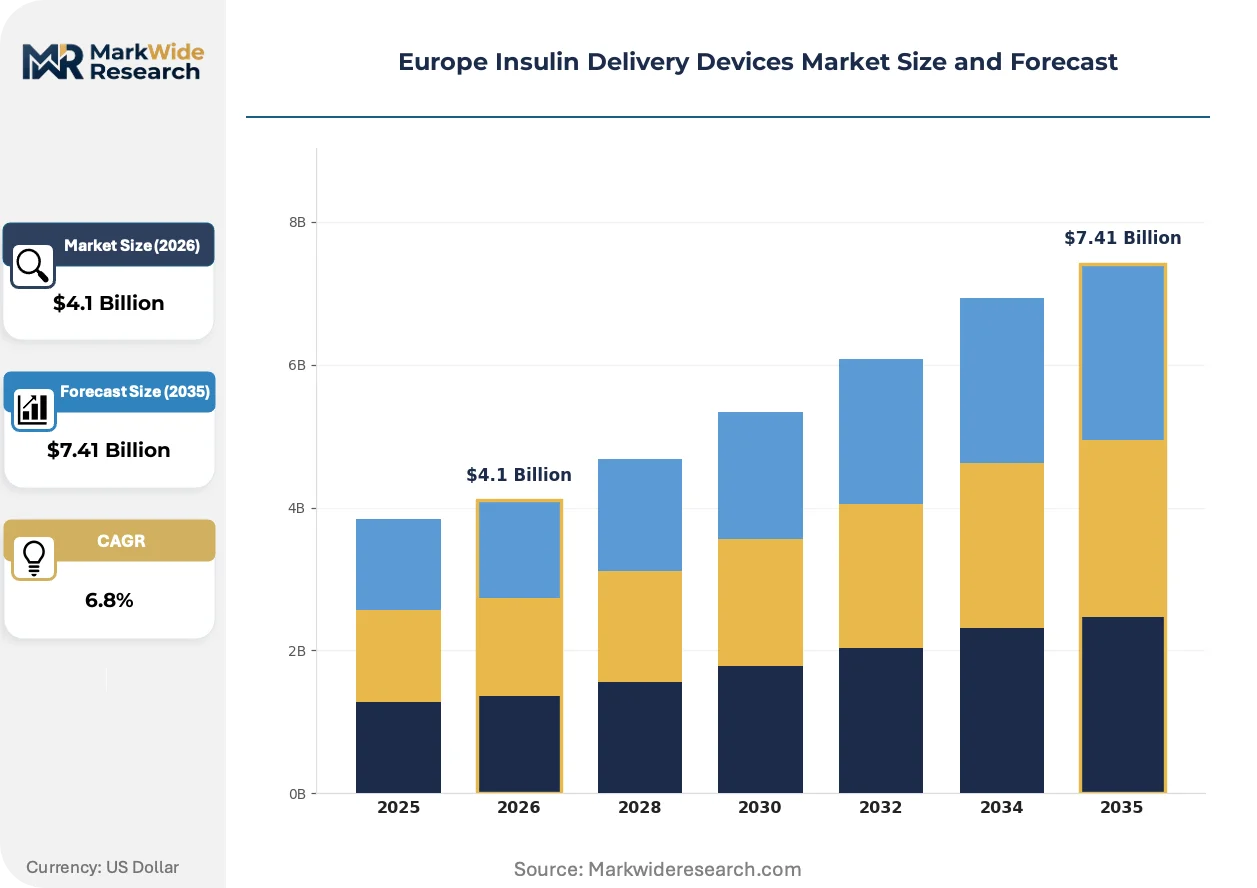
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insulin Pens, Insulin Pumps, Jet Injectors, Syringes Usage Setting: Home Care, Hospitals, Clinics, Long-Term Care Facilities Delivery Technology: Continuous Glucose Monitoring, Bluetooth Enabled, Smart Insulin Pens, Manual Patient Type: Type 1 Diabetes, Type 2 Diabetes, Pediatric Patients, Elderly Patients |
| Companies Covered | Novo Nordisk A/S, Sanofi, Medtronic, Ypsomed Holding AG, Eli Lilly and Company, Becton, Dickinson and Company, Insulet Corporation, Tandem Diabetes Care, Inc., Roche, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Delivery Devices Market Shifts & Advancements
Connectivity and automation are converging to transform insulin delivery from mechanical administration into data-integrated disease management, with regulatory frameworks racing to catch up to hardware capabilities.
Smart insulin pens equipped with Bluetooth modules and accelerometer-based dose detection are digitizing patient adherence patterns and compressing the feedback loop between dosing behavior and clinical intervention. Endocrinology practices in Germany and the Netherlands are adopting these devices at accelerating rates, particularly for Type 1 pediatric populations where parental remote monitoring reduces clinic visits. The technology is digitizing how payers assess treatment compliance, enabling outcome-based contract structures that tie reimbursement to verified dosing frequency.
The EU AI Act's risk classification framework for algorithmic medical decision support is reshaping development roadmaps for closed-loop pump systems. Manufacturers must now document training data provenance and establish human oversight protocols for automated basal rate adjustments. Integrated pump-CGM systems face the steepest compliance burden, with notified bodies in Germany and France requiring expanded clinical validation studies before CE marking.
Hospital procurement consortia in France and Italy are consolidating purchasing power and unbundling after-sales service from device acquisition contracts. Regional buying groups in Lombardy and Ile-de-France now negotiate multi-year framework agreements that separate hardware supply from training and maintenance obligations. This restructuring is most visible in pen needle and disposable pump supply categories, where standardized tender specifications favor vendors with localized logistics networks over integrated service offerings.
Europe Insulin Delivery Devices Market Segmentation
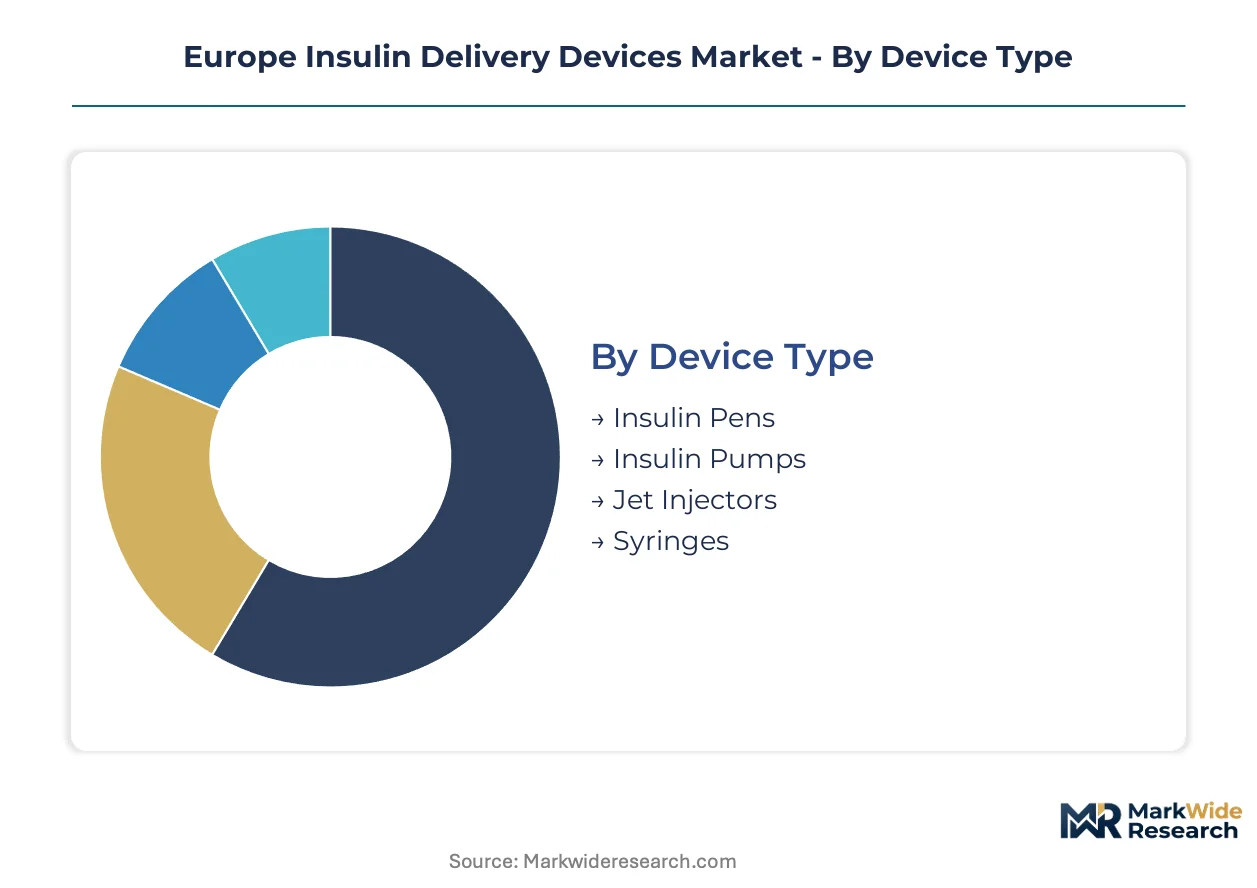
Insulin delivery device segmentation reveals how reimbursement structures, patient autonomy levels, and clinical oversight requirements fragment demand across distinct hardware categories and care settings. Understanding these divisions clarifies where manufacturers must build service infrastructure versus where transactional supply relationships suffice.
Device Type:
After-sales-service intensity varies dramatically across device categories, with electromechanical systems demanding localized technical support networks that pen-based delivery avoids entirely.
- Insulin Pens:Mechanical and prefilled cartridge systems engineered for discrete basal-bolus dosing with typical ±5% volume accuracy. Demand concentrates in Germany and France where outpatient reimbursement codes favor self-administration; patient familiarity with pen mechanics reduces training burdens for providers.
- Insulin Pumps:Programmable electromechanical devices delivering continuous subcutaneous insulin infusion with algorithmic basal rate modulation. Adoption clusters in pediatric Type 1 populations across the Netherlands and Scandinavian markets where integrated CGM pairing receives favorable health technology assessment scoring.
- Jet Injectors:Needle-free systems using high-pressure gas propulsion to breach dermal barriers. Limited penetration in Italy and Spain due to reimbursement ambiguity and higher per-dose consumable costs.
- Syringes:Conventional vial-and-syringe administration requiring manual dose drawing. Residual demand in Eastern European markets where pen device reimbursement remains restricted.
Insulin pens hold the largest share; momentum sits with insulin pumps.
Usage Setting:
Cost tier stratification separates acute-care procurement with bundled service contracts from retail pharmacy channels where price transparency dominates.
- Home Care:Self-administered therapy environments including patient residences and assisted living facilities. Elderly diabetes populations in Germany, France, and Italy are migrating to home-based pen and pump therapy, expanding addressable device volumes outside institutional procurement.
- Hospitals:Acute-care institutions with centralized pharmacy operations and electronic health record integration requirements. Procurement consortia in Ile-de-France and Lombardy are unbundling device supply from training obligations, reshaping vendor selection criteria.
- Clinics:Outpatient endocrinology practices and diabetes centers providing supervised initiation therapy. German diabetes centers (Diabetologische Schwerpunktpraxen) serve as pump initiation gatekeepers with formalized training certification requirements.
- Long-Term Care Facilities:Nursing homes and skilled nursing environments managing polypharmacy elderly populations. Staff turnover and dosing error liability create demand for simplified pen devices with dose confirmation features.
Home care captures the steepest expansion trajectory; hospitals retain the highest per-unit value concentration.
Delivery Technology:
Technology maturity curves separate established mechanical delivery from emerging connectivity platforms facing evolving EU AI Act governance.
- Continuous Glucose Monitoring:Interstitial fluid glucose sensors paired with automated insulin delivery algorithms. Integrated pump-CGM systems command premium positioning in Germany and the Netherlands where closed-loop automation reduces hypoglycemic event rates.
- Bluetooth Enabled:Wireless data transmission modules embedded in pen housings or pump controllers. Pediatric Type 1 populations in Germany and the Netherlands are adopting these devices for parental remote monitoring and reduced clinic visit frequency.
- Smart Insulin Pens:Dose-logging devices with accelerometer-based injection detection and clinician data sharing. Digitizing adherence tracking enables outcome-based contract structures that tie reimbursement to verified dosing frequency.
- Manual:Non-connected mechanical delivery without data capture capabilities. Residual category in price-sensitive segments and markets with delayed digital infrastructure deployment.
Manual delivery retains volume dominance; Bluetooth-enabled systems are gaining share fastest.
Patient Type:
Application-specific requirements differentiate pediatric populations needing parental oversight interfaces from elderly cohorts prioritizing simplicity and error prevention.
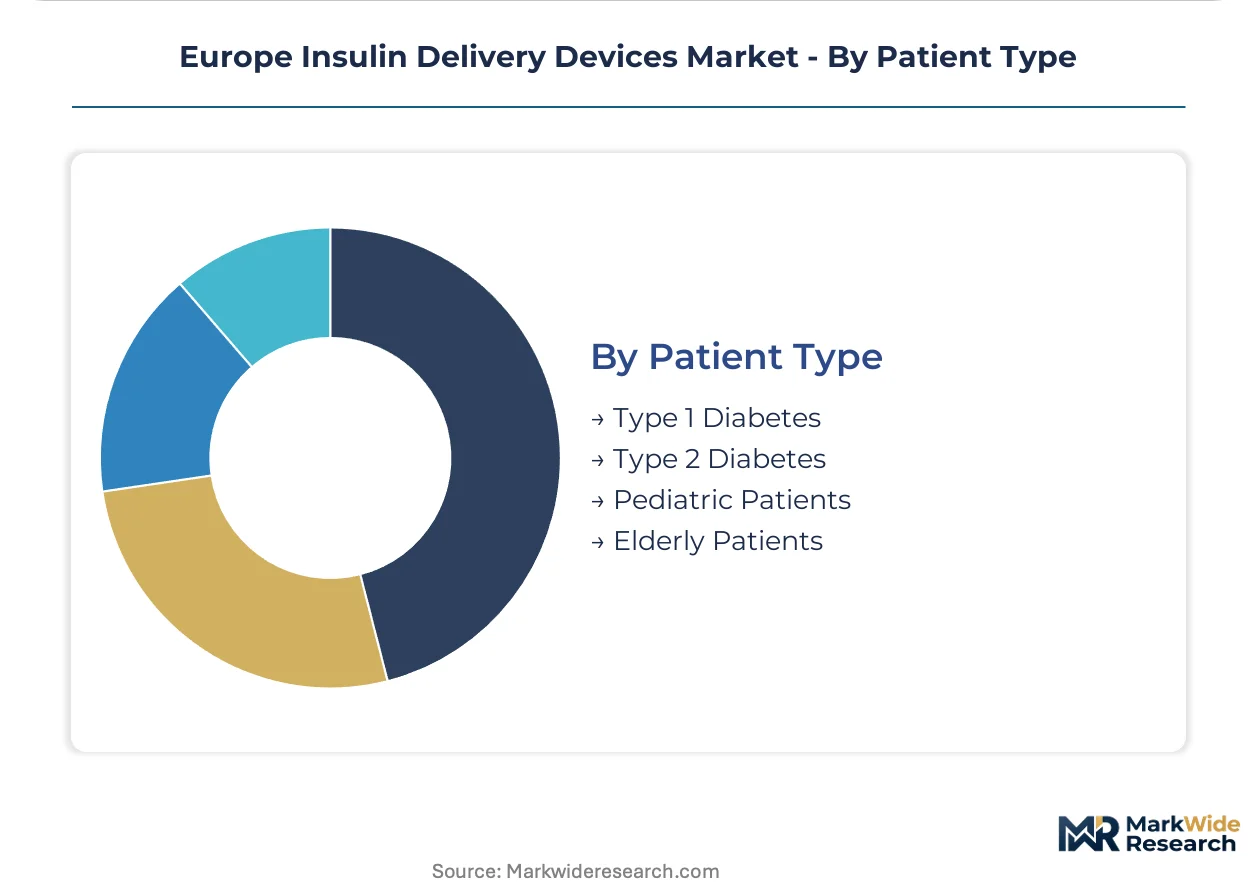
- Type 1 Diabetes:Autoimmune insulin-dependent populations requiring intensive basal-bolus regimens or pump therapy. Pediatric Type 1 patients in Germany and the Netherlands drive adoption of connected devices with remote monitoring capabilities.
- Type 2 Diabetes:Progressive insulin-requiring populations with varying degrees of β-cell preservation. Elderly Type 2 patients across Italy and France are transitioning from clinic-based administration to self-managed pen therapy.
- Pediatric Patients:Children and adolescents under 18 with distinct glycemic targets and caregiver involvement requirements. Parental remote monitoring features influence device selection in German and Dutch markets.
- Elderly Patients:Patients over 65 with comorbidity burdens and dexterity limitations. Dose confirmation and large-display interfaces dominate device preferences in French and Italian long-term care settings.
Type 2 diabetes holds the largest patient base; Type 1 diabetes shows the highest device intensity per capita.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underpins distribution efficiency across the continent's northern diabetes care corridor, connecting manufacturing clusters in Switzerland and Germany to clinical centers in the Netherlands and France.
Germany
Diabetes prevalence among elderly populations and comprehensive reimbursement codes for self-administered pen therapy anchor device demand. The EU MDR recertification deadlines are compressing product update cycles for manufacturers serving German diabetes centers. Bavaria's medical technology cluster around Munich hosts pump initiation training facilities that gatekeeper pediatric Type 1 adoption.
France
Health technology assessment bodies in Paris weigh device expenditure against reduced hospitalization costs, reshaping procurement criteria for integrated pump-CGM systems. ANSM oversight of combination products adds layered approval requirements for algorithm-driven dosing platforms. The Île-de-France hospital procurement consortium unbundles device supply from training contracts, favoring vendors with localized service networks.
Italy
Northern regions exhibit underpenetrated pump adoption relative to diabetes prevalence, creating whitespace for service infrastructure investment. Regional health authorities in Lombardy and Veneto negotiate multi-year framework agreements that separate hardware acquisition from maintenance obligations. Milan's medical device logistics hub supports pen needle replenishment through pharmacy channel digitization.
Netherlands
Pediatric Type 1 populations drive adoption of Bluetooth-enabled devices with parental remote monitoring capabilities. Favorable health technology assessment scoring for closed-loop automation reduces hypoglycemic event rates in Amsterdam and Rotterdam clinical networks. The country's electronic health record standardization supports smart pen data interoperability better than neighboring markets.
Switzerland
Swissmedic oversight maintains stringent clinical evidence requirements that elevate barriers for new pump entrants. Ypsomed's domestic manufacturing precision anchors pen needle and pump patch supply chains serving adjacent EU markets. Basel's pharmaceutical corridor integrates device development with insulin formulation research.
Europe Insulin Delivery Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated diabetes care platforms that combine device hardware with digital adherence monitoring and direct payer relationships. Established pharmaceutical-device hybrids leverage reimbursement breadth and clinical evidence portfolios to defend positions, while specialized pump manufacturers compete on algorithm sophistication and closed-loop automation. Three archetypes dominate: vertically integrated diabetes care platforms, electromechanical pump specialists, and precision pen needle fabricators. Competitive moves center on M&A to acquire connectivity capabilities and geographic expansion of localized service networks to satisfy unbundled procurement contracts.
Among Nordic-anchored integrated platforms, Novo Nordisk A/S and insulin-focused pharmaceutical incumbents exemplify the diabetes care archetype that binds device supply to formulation portfolios. Swiss precision manufacturers including Ypsomed Holding AG occupy positions in pen needle and pump patch technologies where manufacturing quality anchors supply relationships. These company groupings represent how geographic origin and corporate structure shape competitive positioning without requiring speculative claims about specific strategic initiatives or financial performance.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Medtronic |
| Ypsomed Holding AG |
| Eli Lilly and Company |
| Becton, Dickinson and Company |
| Insulet Corporation |
| Tandem Diabetes Care, Inc. |
| Roche |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Swiss medical-grade polymer suppliers determines both tiered pricing spreads and supply chain configuration across European insulin delivery device markets. REACH compliance costs and MDR recertification timelines compress margin structures while forcing manufacturers toward consolidated procurement relationships.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement consortia contracts, with three-tier pricing separating closed-loop pump-CGM systems from standard insulin pumps and mechanical pen devices. Price differentiation hinges on algorithmic sophistication and after-sales service bundling, with Bluetooth-enabled pens commanding mid-tier positioning. Pricing pressure stems from unbundled tender specifications in Lombardy and Ile-de-France that separate hardware from maintenance obligations. Pharmacy channel buyers exhibit highest price sensitivity, while pediatric diabetes centers prioritize remote monitoring capabilities over per-unit cost.
Supply Chain Analysis
Tariff exposure between Switzerland and adjacent EU markets dominates supply chain risk calculus for pen needle and pump patch manufacturers. Component sourcing draws from Germany, Switzerland, and the Netherlands for precision-machined housings, medical-grade polycarbonates, and sensor substrates. Single-source vulnerability concentrates in Swiss polymer compounding facilities serving Ypsomed's domestic production base. Distribution runs through Rhine-Alpine freight corridors connecting Basel manufacturing clusters to German diabetes centers and Dutch pediatric networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as integrated glucose monitoring and automated dosing algorithms reshape device value from hardware delivery toward data-integrated disease management ecosystems.
For Market Incumbents: Build algorithmic moats through closed-loop automation capabilities that lock in pediatric Type 1 populations and payer preference. Deepen backward integration into sensor substrate manufacturing to reduce Swiss polymer supply exposure. Secure MDR recertification ahead of notified body bottlenecks to freeze out mid-tier competitors lacking clinical evidence portfolios. For New Entrants and Emerging Players: Pursue pharmacy channel digitization in Northern Italy's underpenetrated pump markets, where regional health authority framework agreements favor localized logistics over integrated platforms. Target elderly Type 2 populations in French long-term care facilities with simplified pen devices featuring dose confirmation interfaces. Anchor go-to-market strategy through direct-to-patient replenishment platforms bypassing hospital procurement consortia. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electromechanical pump specialists with algorithmic differentiation over commodity pen manufacturers. Long-term viability rests on EU AI Act compliance positioning for automated dosing software. Watch for inflection signals in French health technology assessment scoring shifts that elevate closed-loop automation reimbursement tiers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR recertification ahead of May deadlines secures notified body bandwidth against competitor portfolio freezes. |
| Hospital System Partnership | Unbundled service contracts in Lombardy and Ile-de-France favor vendors with localized technical training networks. |
| Software Companion Development | Bluetooth-enabled dose logging enables outcome-based payer contracts tying reimbursement to verified adherence. |
| Backward Integration into Sensor Substrates | Captive supply of CGM components reduces German polymer supplier concentration risk. |
| Reimbursement Strategy Investment | French ANSM combination product alignment positions algorithm-driven pumps for premium HTA scoring. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA device filings, EU MDR notified body databases, and hospital procurement consortium tender documents across Germany, France, Italy, and the Netherlands. Primary interviews engaged biomedical engineers at diabetes centers, GPO contracts managers in Ile-de-France, regulatory affairs leads at notified bodies, and pharmacy channel operators in Lombardy. Bottom-up device shipment estimates triangulated against top-down diabetes prevalence and reimbursement code analysis.
Forecast inputs span device type segmentation by delivery technology, usage setting stratification across home care and institutional channels, patient type differentiation between Type 1 and Type 2 populations, and regional regulatory cluster variations in MDR implementation timing. CAGRs derive from installed base evolution modeling and replacement cycle dynamics across pen, pump, and closed-loop system categories. Algorithmic dosing software regulatory risk weights and REACH material substitution timelines inform scenario boundaries.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CGM-native entrants or AI-first dosing software developers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
NF-KB Inhibitors Market