
 Network Documentation Software Market | 2026-2036
Network Documentation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Network Documentation Software Market Intelligence
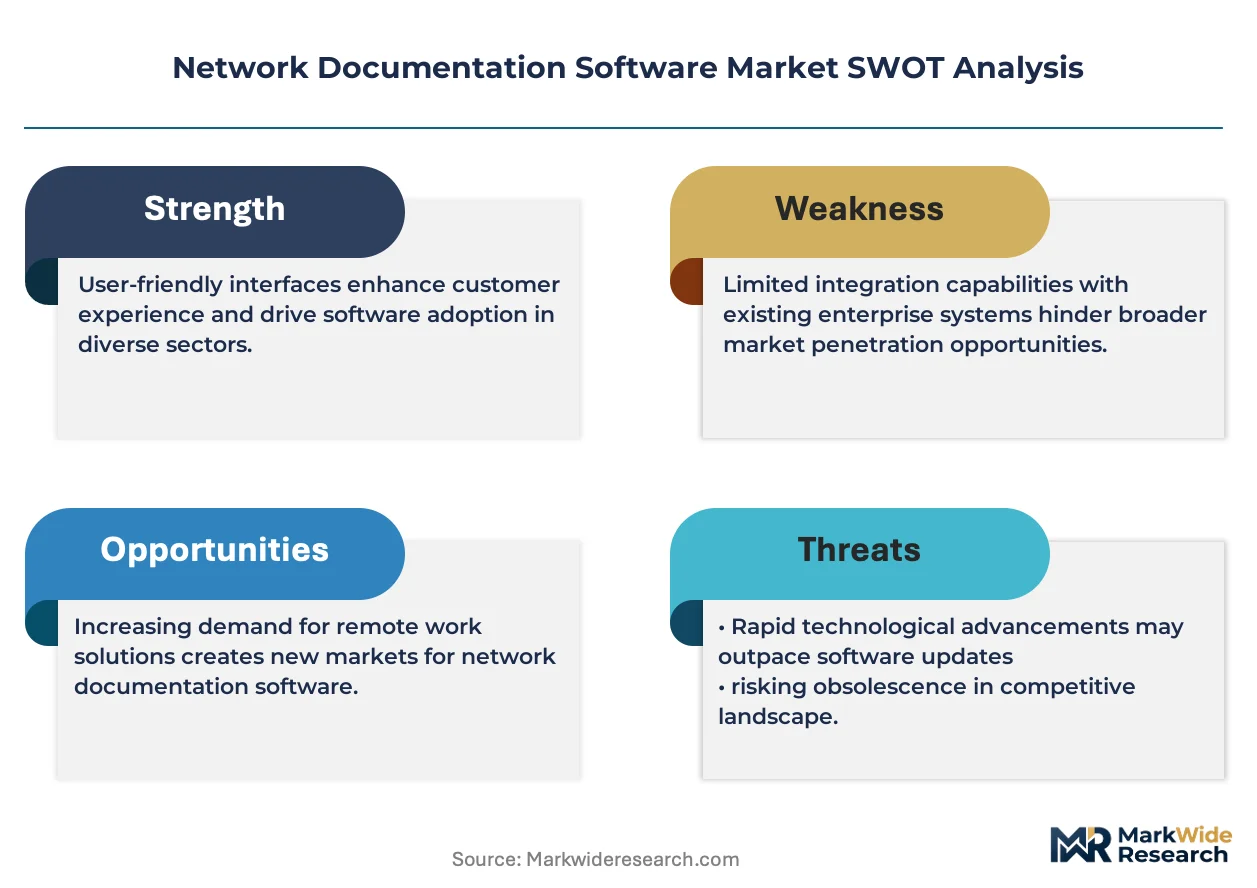
The reliance on siloed, manually-updated spreadsheets and diagrams for network administration is collapsing under the weight of modern network complexity. IT Glue specializes in documentation platforms tailored for Managed Service Providers, a key growth segment. Atlassian's Confluence leverages its broad collaboration ecosystem to serve enterprise IT departments with integrated knowledge bases. Auvik differentiates with its real-time network mapping and inventory automation features for distributed environments.
Network documentation software provides a centralized repository for recording a network's physical and logical topology, including device configurations and interconnections. These platforms use protocols like SNMP for automated asset discovery, ensuring the documentation remains current against constant network changes. Cloud-based SaaS solutions represent the fastest-growing deployment model, displacing traditional on-premises installations. While large enterprises remain a significant end-user base, Managed Service Providers are driving new license adoption due to their need for efficient multi-tenant capabilities.
Compliance with data protection regulations such as Europe's GDPR and the US HIPAA drives adoption, as auditable network records are essential evidence for security posture. These frameworks mandate that organizations can demonstrate strict control over data pathways and asset configurations. The critical decision for buyers now centers on selecting platforms with the most robust automation and third-party API integration capabilities, rather than building less-scalable in-house tools.
Market Dynamics
The convergence of escalating network complexity and stringent data governance mandates is the central force shaping the market. As enterprises adopt hybrid and multi-cloud architectures, the inadequacy of manual documentation methods becomes a critical operational risk, compelling investment in automated platforms.
Growth Catalysts
- Regulatory Compliance Mandates:Frameworks like Europe's GDPR require organizations to maintain detailed, auditable records of their network infrastructure to prove control over personal data pathways, directly stimulating demand for compliant documentation tools in sectors like finance and healthcare.
- Hybrid Cloud Adoption:The architectural shift toward hybrid environments that blend on-premises data centers with public cloud services from providers like AWS and Google Cloud necessitates sophisticated tools to map and manage assets across disparate locations.
- Managed Service Provider Expansion:The growth of the MSP segment, which serves multiple clients, creates strong demand for multi-tenant documentation platforms that enable efficient, scalable management of diverse and complex customer networks from a single pane of glass.
Market Restraints
- High Subscription Costs:The total cost of ownership for enterprise-grade SaaS documentation platforms, including licensing and integration fees, remains a significant barrier for small and medium-sized businesses with constrained IT budgets, limiting market penetration.
- Persistence of In-House Tools:A considerable portion of the market continues to rely on legacy, manually updated tools like spreadsheets and Visio diagrams, representing a powerful substitution threat that slows the adoption of commercial software, particularly in less-regulated industries.
- Legacy System Incompatibility:Many established enterprises operate older networking hardware that lacks modern API or SNMP support, which severely limits the effectiveness of automated discovery and mapping features, diminishing the value proposition of advanced documentation platforms.
Strategic Opportunities
- Emerging Market Penetration:Rapidly digitizing economies in countries such as India and Brazil present significant greenfield opportunities for vendors as new businesses build out their network infrastructure and require documentation tools from the outset.
- OT and IoT Network Documentation:Extending documentation capabilities beyond traditional IT to include Operational Technology and Internet of Things networks in industrial sectors like manufacturing and energy provides a major avenue for market expansion.
- AIOps Integration:The convergence of documentation platforms with AI for IT Operations (AIOps) creates an opportunity to offer predictive analytics, identifying potential network issues and automating remediation based on real-time and historical configuration data.
Industry Challenges
- Automation Skills Gap:A persistent shortage of network engineers proficient in modern automation protocols and declarative configuration languages hinders the effective implementation and ongoing management of sophisticated documentation platforms within enterprise IT teams.
- Third-Party Tool Integration:Achieving and maintaining seamless API-level integration with a highly fragmented ecosystem of third-party IT service management (ITSM), security information and event management (SIEM), and network monitoring tools is a constant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Network Documentation Software Market |
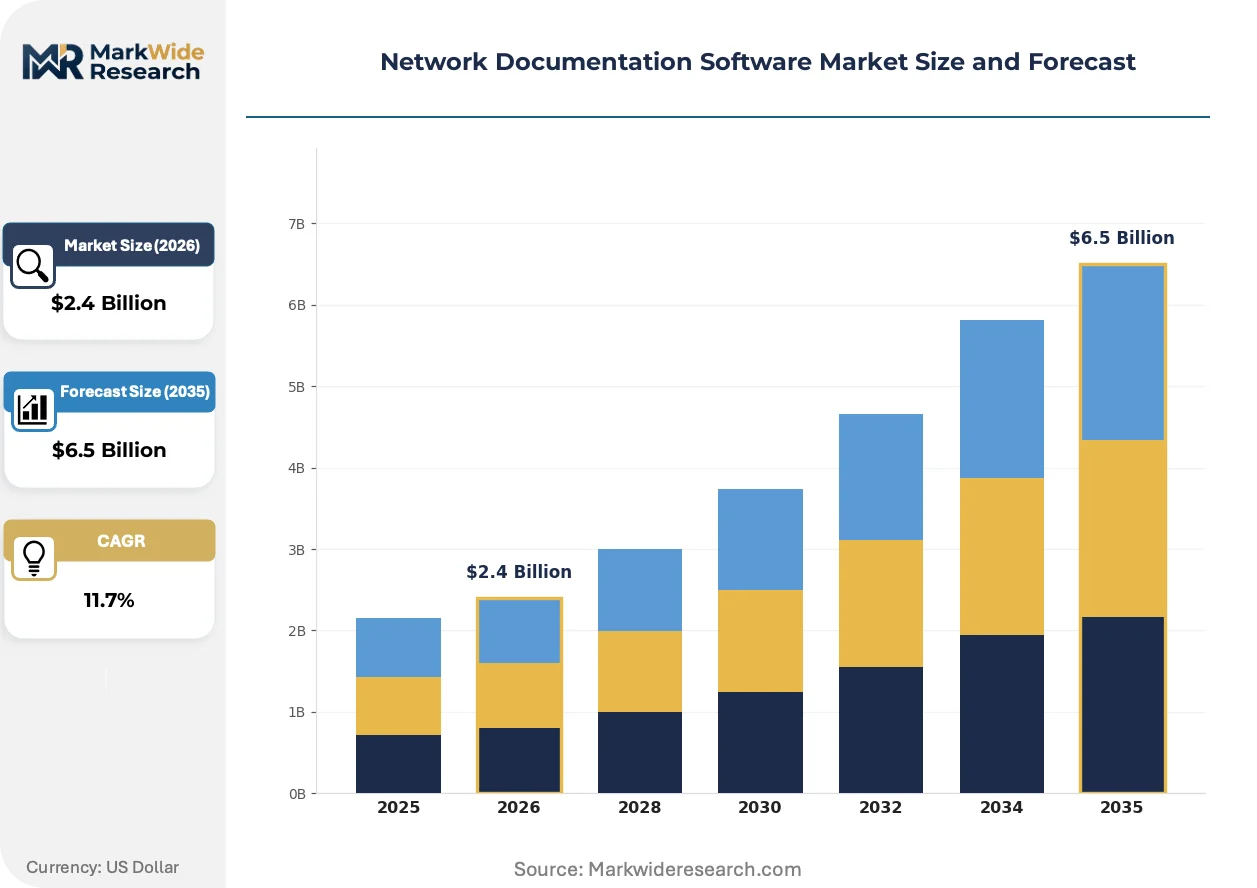
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, SaaS End User: IT Departments, Network Administrators, Managed Service Providers, Enterprises Feature: Network Mapping, Compliance Management, Workflow Automation, Reporting Solution: Diagramming Tools, Inventory Management, Configuration Management, Documentation |
| Companies Covered | Auvik, BookStack, Ferndesk, Nuclino, Notion, IT Glue, Confluence, Document360, Hudu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Network Documentation Software Market Strategic Shifts & Innovations
The market is defined by a decisive shift from static documentation to dynamic, automated network intelligence. This evolution is driven by the need for real-time visibility and control to manage distributed infrastructure and ensure compliance in an environment of constant change.
SaaS-based platforms featuring automated discovery via protocols like SNMP and direct API integrations are becoming the industry standard. Managed Service Providers and enterprises with geographically dispersed teams are the primary adopters of these cloud-native solutions. This subscription-based SaaS model is displacing traditional on-premises software, which demanded significant upfront capital investment and relied on periodic manual updates.
Data governance frameworks, including Europe’s GDPR and the US HIPAA, are powerful adoption drivers. These regulations compel organizations to produce verifiable evidence of their network topology, asset configurations, and data pathways to demonstrate security posture during audits. Consequently, sectors such as healthcare and financial services are prioritizing investment in platforms that offer immutable change logs and granular access controls.
Enterprise IT teams are moving away from developing and maintaining homegrown documentation systems based on internal wikis or shared diagrams. This behavioral shift stems from the high opportunity cost and inability of in-house tools to match the automation, integration, and scalability of commercial platforms. The trend is most pronounced within technology-focused business clusters in the United States and Germany, where engineering resources are guarded for core product development.
Network Documentation Software Market Segmentation
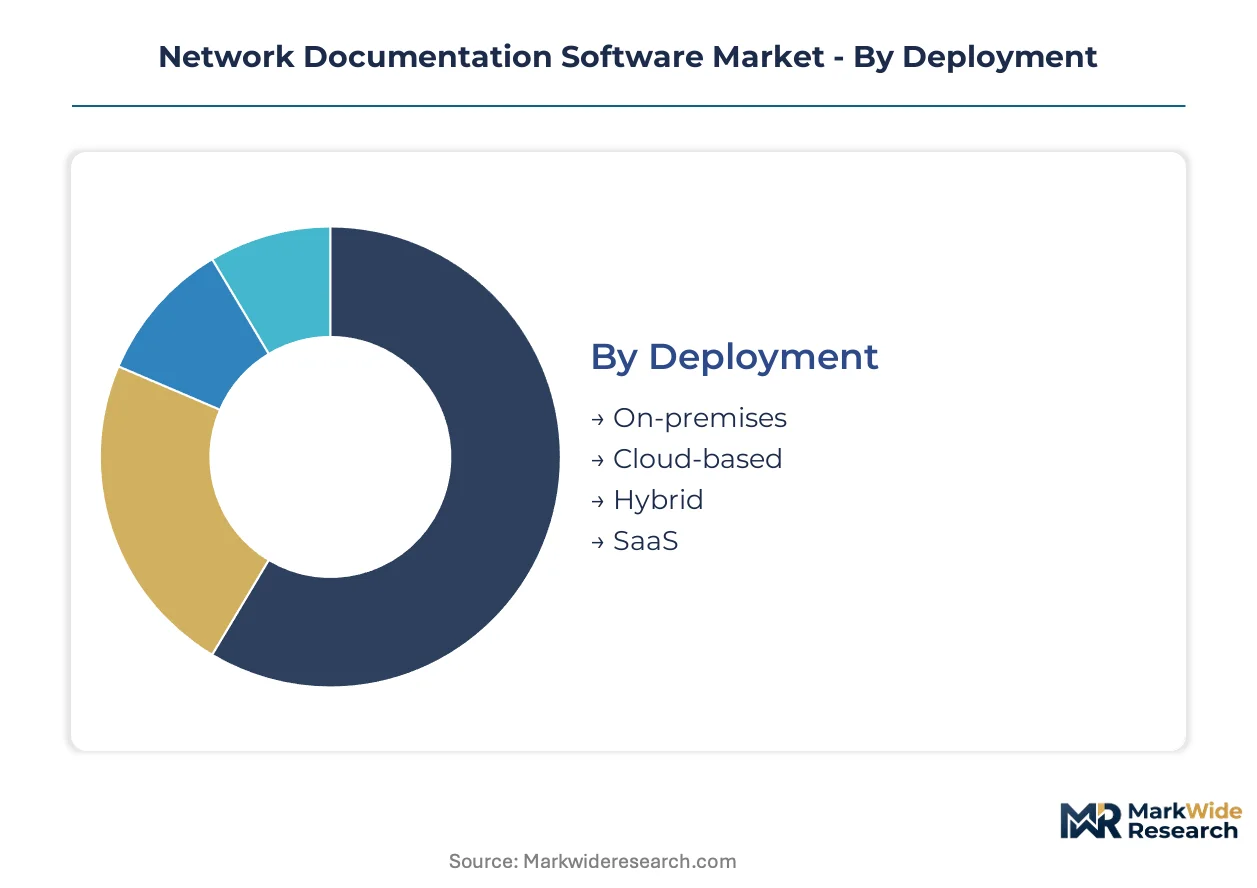
The network documentation software market segments across various dimensions, reflecting the diverse needs of organizations striving for enhanced network visibility and operational efficiency. Understanding these segments is crucial for vendors to tailor solutions and for buyers to identify platforms best suited to their specific infrastructure challenges.
Deployment:
Deployment models for network documentation software reflect varying infrastructure maturity levels across different global regions.
- On-premises:These solutions are installed and run on an organization's internal servers, offering complete control over data and infrastructure.
- Cloud-based:These solutions are hosted by a third-party vendor and accessed over the internet, eliminating on-site infrastructure management. Demand is strong in technology-centric business clusters within the United States, driven by the need for scalable and accessible documentation across distributed teams.
- Hybrid:This model combines elements of both on-premises and cloud deployments, allowing organizations to store sensitive data locally while leveraging cloud flexibility.
- SaaS:A specific sub-type of cloud-based deployment, SaaS offers subscription-based access to fully managed software, reducing upfront capital expenditure. This model represents the fastest-growing trajectory, gaining traction among Managed Service Providers in Germany seeking efficient multi-tenant capabilities for client network management.
Cloud-based deployment currently holds the largest share; momentum sits with SaaS solutions.
End User:
End-user categories for network documentation software delineate distinct operational requirements and purchasing behaviors.
- IT Departments:These internal teams within organizations use the software to maintain accurate records of their network assets and configurations.
- Network Administrators:Individual professionals responsible for network operation and maintenance rely on these tools for daily management and troubleshooting.
- Managed Service Providers:These organizations manage IT services for other businesses, requiring multi-tenant platforms for efficient oversight of diverse client networks. Their expansion drives new license adoption, particularly in markets like the United States and Europe.
- Enterprises:Large organizations with complex, distributed IT infrastructures utilize these tools for comprehensive network visibility and compliance across numerous departments. Stringent data governance mandates under GDPR and HIPAA compel their investment in robust documentation.
Managed Service Providers are expanding most quickly, while large Enterprises represent a substantial established end-user base.
Feature:
Key features within network documentation software address critical functional needs for network management and operational efficiency.
- Network Mapping:This feature automatically discovers and visualizes network topology, displaying devices, connections, and their interdependencies in real-time. It is essential for managing hybrid cloud architectures and distributed environments within enterprises.
- Compliance Management:This functionality provides auditable records of network configurations and changes, crucial for meeting regulatory requirements like GDPR and HIPAA. Financial services and healthcare sectors prioritize this for demonstrating security posture.
- Workflow Automation:This feature streamlines routine network documentation tasks, such as updating asset records or generating configuration backups, reducing manual effort.
- Reporting:Tools for generating customizable reports on network inventory, configuration changes, and compliance status support operational oversight and auditing requirements.
Network Mapping remains a foundational feature, with Compliance Management capabilities gaining significant traction due to regulatory pressures.
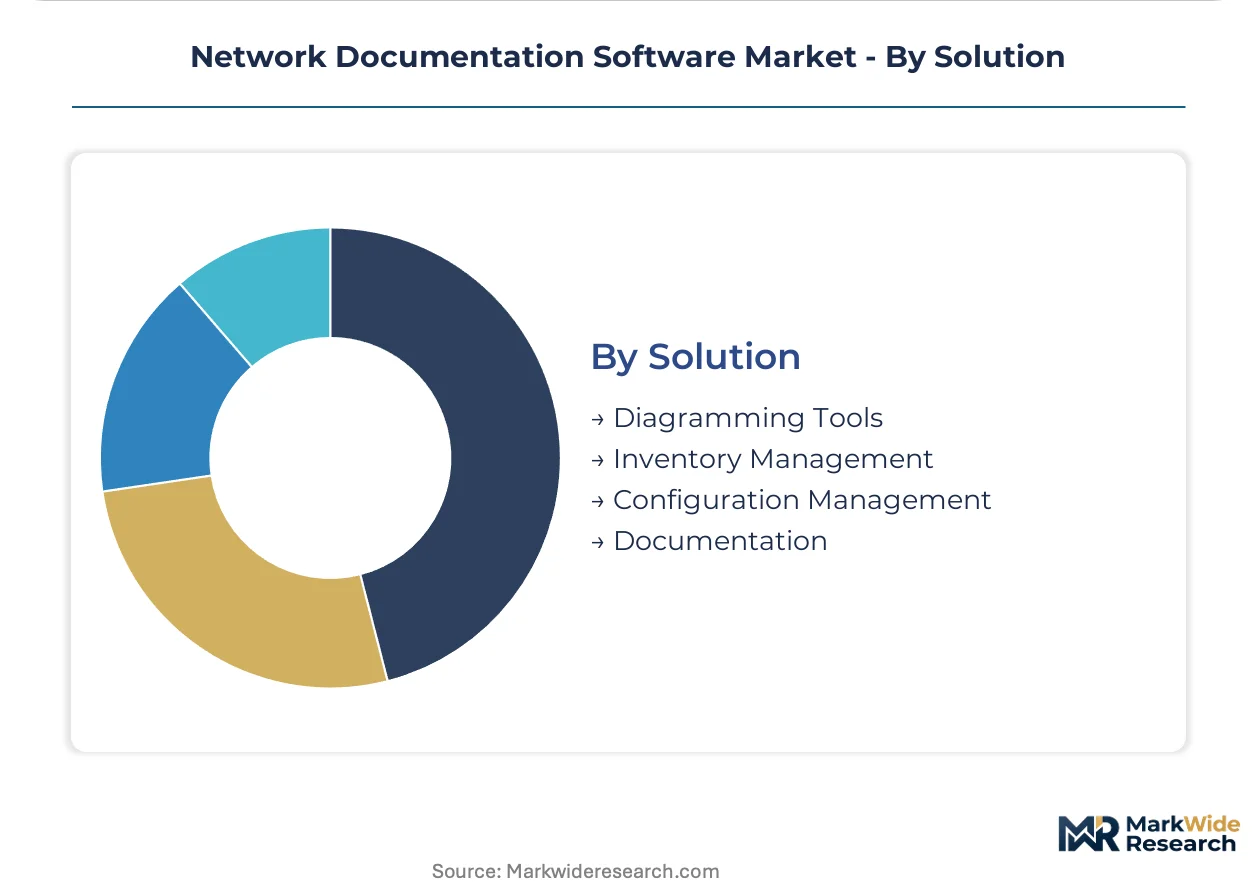
Solution:
Solution types reflect the evolution of network documentation, from basic visual aids to sophisticated automated systems.
- Diagramming Tools:These provide visual representations of network layouts, often relying on manual input for updates and accuracy.
- Inventory Management:This solution automatically discovers and maintains a comprehensive database of all network assets, including hardware, software, and their attributes. It provides real-time visibility into distributed environments, particularly for Managed Service Providers.
- Configuration Management:These solutions track and manage all changes to network device configurations, maintaining a historical record and enabling automated rollback. This is vital for maintaining network stability and security across complex enterprise infrastructures.
- Documentation:This encompasses the broader capability of centralizing network information, including policies, procedures, and contact details, beyond just technical specifics.
Configuration Management and Inventory Management are seeing increased investment as organizations move away from traditional Diagramming Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US HIPAA regulation significantly influences network documentation software adoption, particularly in sectors managing sensitive data. This demand extends to other developed economies where data governance mandates drive investment in auditable network records. Key markets are demonstrating distinct patterns of adoption and regulatory influence.
United States
Hybrid cloud adoption and stringent data governance drive demand for sophisticated documentation. HIPAA compliance requires auditable records of network configurations for healthcare providers. Technology clusters in Silicon Valley and Boston are rapidly deploying cloud-based SaaS solutions for distributed teams.
Germany
Managed Service Providers are expanding their use of multi-tenant documentation platforms for client networks. Europe's GDPR mandates detailed infrastructure records to prove control over personal data. Financial services and automotive sectors in Frankfurt and Munich prioritize platforms with robust compliance management features.
India
Rapid digitization across various industries creates greenfield opportunities for documentation software vendors. India's evolving data protection framework will increasingly compel organizations to maintain auditable network records. Technology hubs in Bengaluru and Hyderabad are building out infrastructure with documentation tools from the outset.
Japan
Complex enterprise IT environments and a focus on operational efficiency drive demand for automated network mapping tools. Japan's APPI necessitates careful management of data pathways and asset configurations. Manufacturing and electronics companies in Tokyo and Osaka invest in solutions for comprehensive network visibility.
United Kingdom
The shift towards hybrid cloud architectures compels enterprises to invest in tools for managing assets across disparate locations. The UK GDPR requires organizations to demonstrate strict control over data processing and network infrastructure. London's financial technology sector strongly adopts platforms offering immutable change logs and granular access controls.
Network Documentation Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the network documentation software market structure. The market exhibits a tiered competitive landscape, with established players alongside niche innovators. Two strategic archetypes dominate: comprehensive platform providers and specialized automation tools. Dominant competitive moves include strategic partnerships to expand integration capabilities and portfolio diversification to address new end-user segments.
Within the specialized documentation platform archetype, Auvik exemplifies real-time network mapping and inventory automation, a critical capability for managing complex distributed environments. IT Glue occupies a position as a key provider of tailored documentation platforms, specifically serving the Managed Service Provider segment with efficient multi-tenant capabilities. Confluence, from Atlassian, anchors the enterprise IT department segment, leveraging its broad collaboration ecosystem to offer integrated knowledge bases and extensive project documentation across large organizations.
| Leading Market Players |
|---|
| Auvik |
| BookStack |
| Ferndesk |
| Nuclino |
| Notion |
| IT Glue |
| Confluence |
| Document360 |
| Hudu |
| Others |
Cost & Logistics Intelligence
Manual documentation methods, largely in-house, are being displaced by commercial network documentation software. This substitution reshapes vendor supply strategies and pricing models, favoring cloud-based solutions.
Pricing Analysis
Geographic price spreads for network documentation software reflect varying regulatory compliance burdens and end-user purchasing power. SaaS-based subscription models dominate, with pricing differentiated by automation depth, API integration breadth, and multi-tenant capabilities. High subscription costs create pricing pressure for small and medium-sized businesses. Large enterprises and Managed Service Providers exhibit lower price sensitivity, prioritizing robust features for compliance and efficiency.
Supply Chain Analysis
Reliance on hyperscaler cloud infrastructure represents a key chokepoint for SaaS network documentation providers. Supply concentration for advanced software development exists in technology clusters within the United States and Germany. Core dependencies include robust API frameworks and SNMP protocol support for automated discovery. Vendor lock-in with specific cloud providers presents a structural risk. Distribution runs through direct sales and Managed Service Provider partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The network documentation software market stands at a platform-economics inflection, driven by the imperative for seamless interoperability across the broader IT ecosystem. Integration with ITSM and SIEM tools defines essential value for end-users.
For Market Incumbents:Compound existing platform advantages by accelerating investment in AIOps integration and predictive analytics capabilities. This defends against emerging AIOps platforms that threaten to displace standalone documentation. Focus on acquiring specialized automation tools to overcome the automation skills gap within client IT teams. Strengthen channel control through strategic partnerships with Managed Service Providers.
For New Entrants and Emerging Players:Anchor in underserved segments by offering specialized solutions for Operational Technology and Internet of Things networks. Target rapidly digitizing economies in India and Brazil, providing greenfield opportunities. Focus on transparent, value-based pricing for small and medium-sized businesses to overcome high subscription cost barriers. Emphasize ease of deployment and pre-built compliance templates for specific industrial regulations.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors specialized SaaS providers with robust automation and integration capabilities. Long-term viability remains strong as regulatory mandates and network complexity intensify. Acquisition targets include niche players with advanced real-time mapping or AIOps integration. Watch for increased M&A activity among larger platforms seeking to consolidate automation features.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen API Integrations | Enhances interoperability with existing ITSM and SIEM tools for enterprise clients. |
| Target Emerging Markets | Captures greenfield demand in rapidly digitizing economies like India and Brazil. |
| Extend to OT/IoT Networks | Unlocks new revenue streams by addressing industrial control system documentation needs. |
| Acquire AI/Automation Specialists | Integrates advanced predictive analytics and real-time discovery capabilities into core offerings. |
| Strengthen MSP Channel Partnerships | Expands market reach and accelerates license adoption through multi-tenant deployments. |
Research Approach
A spread of perspectives from CTOs, IT procurement officers, network administrators, and Managed Service Provider executives converged on the working assumptions. This approach combined primary interviews with validation from secondary sources including company filings, technology journals, and regulatory body publications. Bottom-up data gathering was triangulated against top-down market sizing.
Deployment model, end-user type, feature set, solution category, and regional adoption patterns defined the segmentation dimensions modeled. Compound Annual Growth Rates were derived from historical data and projected adoption curves across the analysis window. Hybrid cloud adoption rates and regulatory compliance spending served as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued regulatory enforcement and stable cloud infrastructure costs; material deviation would warrant model refresh. Economic downturns impacting IT budgets or rapid shifts in data governance frameworks present specific risk factors. Practitioners should keep alternative scenarios live as technology adoption and regulatory landscapes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Recovery Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Global PPC Software Market
Software & Services
Business Rules Management System Market
Software & Services
Global HMI Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Global Nosql Software Market
Software & Services
Simulation Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Game Development Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Sports League Management Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Asia-Pacific ERP Software Market