
 Sports League Management Software Market | 2026-2036
Sports League Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sports League Management Software Market Intelligence
Multi-source vendor strategies is expanding across mid-sized league operators that previously relied on single-platform commitments. SportsEngine leverages integrated payment and registration modules to anchor enterprise accounts. TeamSnap competes through mobile-centric communication tools that sustain high retention among volunteer-run organizations. LeagueApps differentiates via white-label customization options that position its stack for multi-sport governing bodies.
Sports league management software constitutes a category of cloud-native and on-premise applications that automate scheduling, roster management, fee collection, and real-time statistical tracking for organized athletic competitions. The architecture typically employs RESTful APIs, role-based access controls, and automated notification pipelines to synchronize stakeholders across distributed team networks. Cloud-based deployment leads in new customer acquisition due to minimal infrastructure overhead and subscription elasticity, while on-premise installations persist among professional teams with stringent data custody requirements. Scheduling and registration management modules capture the largest solution-level spend, whereas esports application segments represent the fastest structural expansion as digital-native leagues proliferate.
FCC guidelines on digital platform accessibility, GDPR obligations for European amateur leagues processing member data, and state-level biometric privacy statutes in Illinois and Texas shape product development roadmaps and geographic go-to-market sequencing. Compliance with these frameworks elevates engineering costs but creates defensible moats for vendors that pre-certify cross-border data handling. Stakeholders must monitor evolving youth data protection legislation and federation-specific interoperability mandates to anticipate platform consolidation dynamics.
Market Dynamics
Cloud infrastructure maturation and mobile-first design standards are compressing procurement cycles for league administrators who previously relied on fragmented spreadsheet workflows. Youth amateur clubs across North America now demand integrated digital platforms that unify registration, payment, and communication into single operational environments.
Growth Catalysts
- GDPR compliance frameworks:European amateur leagues processing member data must adopt certified platforms, elevating engineering investment into defensible competitive moats for vendors that pre-certify cross-border data handling capabilities.
- Biometric privacy statutes:State-level regulations in Illinois and Texas mandate enhanced data custody protocols, driving professional teams toward vendors with proven on-premise deployment expertise.
- Esports league proliferation:Digital-native competitions require real-time statistical tracking and automated notification pipelines that legacy systems cannot support, expanding addressable market boundaries beyond traditional athletics.
Market Restraints
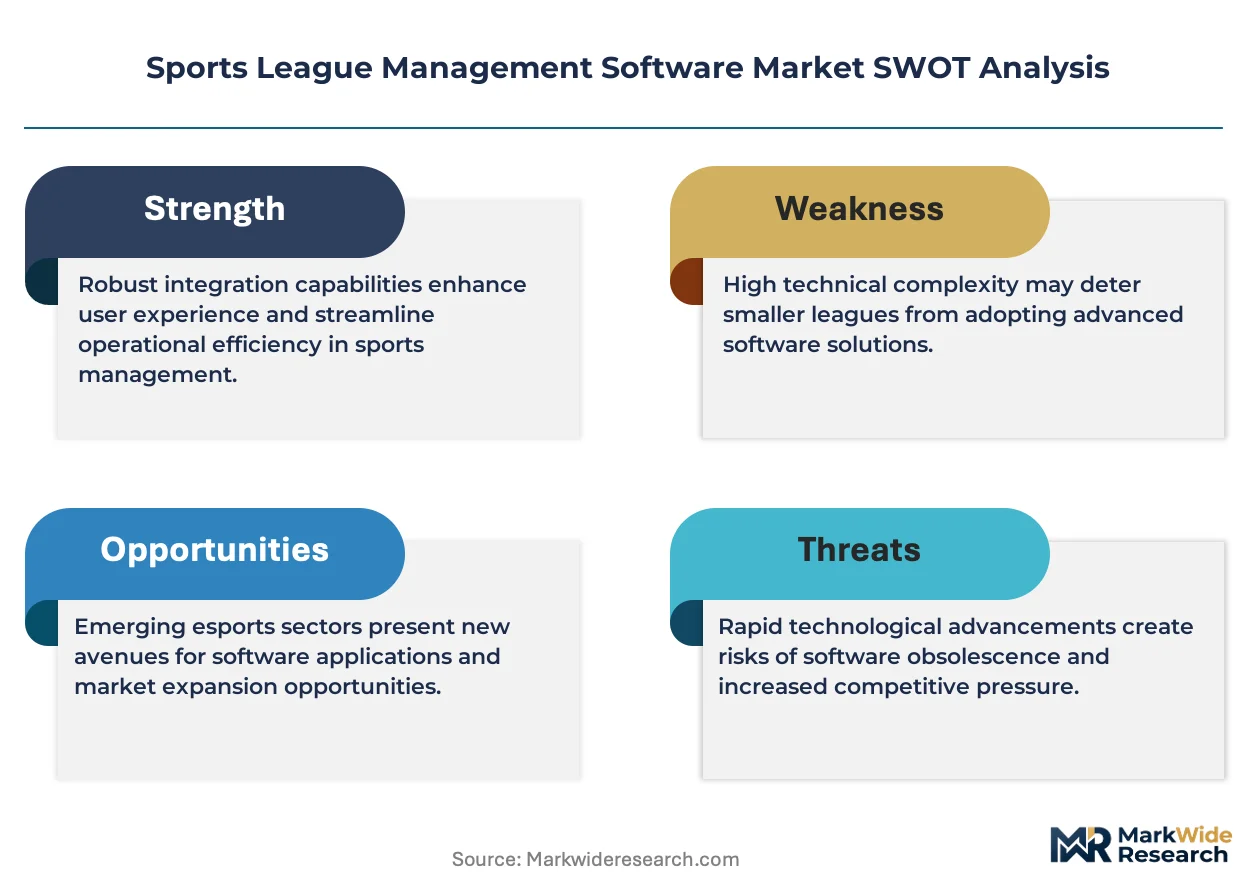
- Engineering cost elevation:FCC accessibility guidelines and federation-specific interoperability mandates inflate platform development expenses, squeezing margins for mid-tier vendors without enterprise scale.
- Data custody fragmentation:Professional teams with stringent security requirements persist in on-premise installations, bifurcating vendor R&D investment across incompatible deployment architectures.
- Volunteer administrator capacity:Community sports organizations rely on unpaid staff with limited technical literacy, constraining adoption velocity for feature-rich platforms requiring training investment.
Strategic Opportunities
- White-label customization:Multi-sport governing bodies seek branded platform experiences, creating premium service tiers for vendors with configurable frontend architectures.
- API ecosystem expansion:RESTful integration with wearable devices and broadcast systems enables new revenue streams through data licensing partnerships.
- Accessibility-first design:FCC digital platform guidelines position compliant vendors for municipal procurement contracts requiring certified inclusive technology standards.
Industry Challenges
- Interoperability mandate fragmentation:Federation-specific data exchange protocols force vendors to maintain multiple integration layers, complicating product roadmaps and delaying feature releases.
- Legacy system migration friction:Decades of historical roster and financial data trapped in spreadsheet formats requires expensive extraction and validation services that erode subscription margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports League Management Software Market |
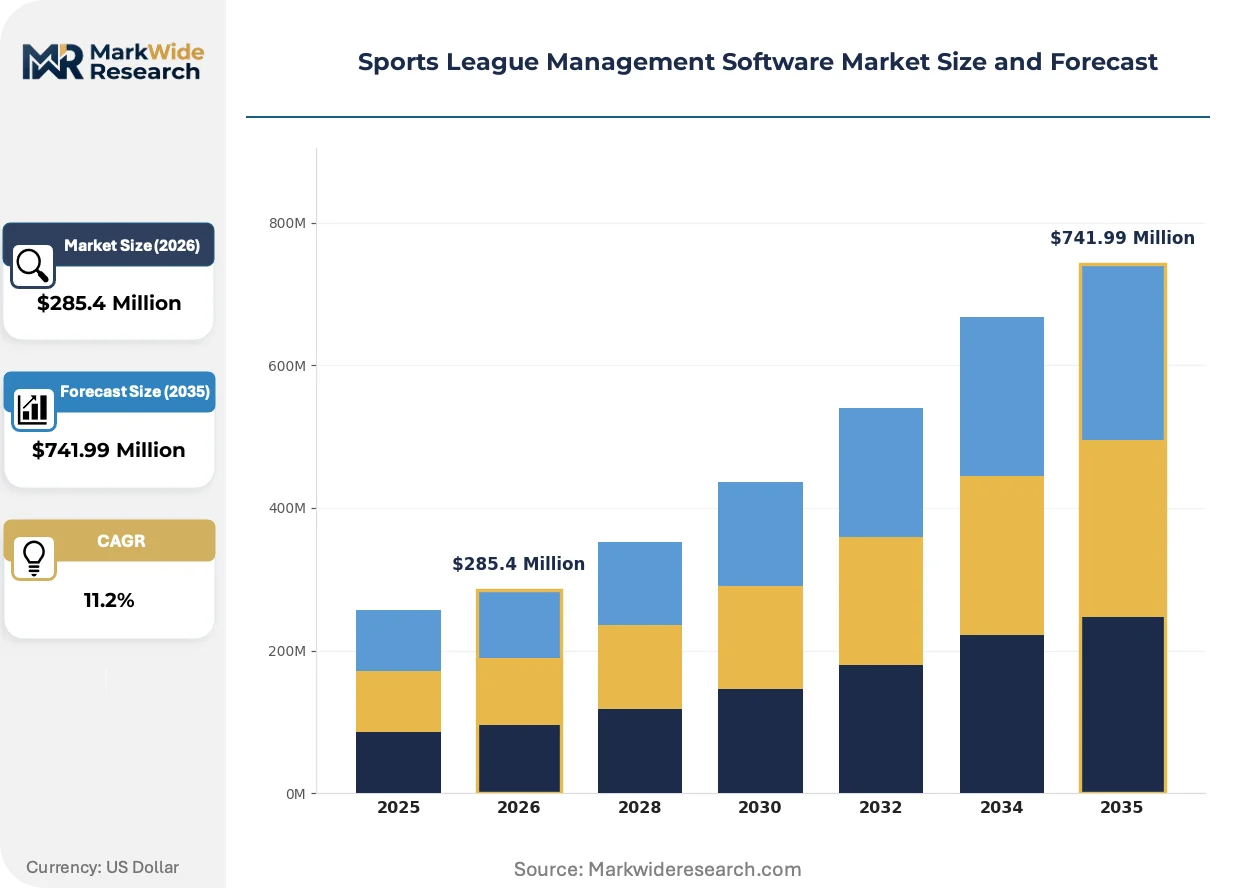
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $741.99 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, SaaS Solution/Offering: Scheduling, Registration Management, Player Statistics, Communication Tools, Payment Processing Application: Football, Basketball, Baseball, Hockey, Volleyball, Esports End User: Amateur Clubs, Professional Teams, Educational Institutions, Community Leagues, Training Academies |
| Companies Covered | SportsEngine, TeamSnap, CommunityPass, Waresport, iSportz, SportNinja, LeagueApps, Leageez, Team Sideline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports League Management Software Market Strategic Shifts & Innovations
Mobile-centric communication tools are displacing email-based coordination as the default stakeholder synchronization method across volunteer-run organizations. Platform vendors now compete through notification pipeline sophistication rather than core scheduling functionality alone.
Artificial intelligence is converging with automated scheduling engines to optimize venue allocation and referee assignment based on real-time availability constraints. Mid-sized league operators in the United States are piloting these systems to reduce administrative overhead during tournament seasons. The technology is converging with mobile payment modules to create closed-loop operational environments that minimize external tool dependencies.
GDPR obligations for European amateur leagues are forcing vendors to implement granular consent management and data portability features that exceed baseline North American requirements. This regulatory divergence is creating product complexity for vendors serving both markets. Youth data protection legislation in multiple jurisdictions is accelerating investment into privacy-by-design architectures.
Subscription elasticity preferences among community sports organizations are compressing traditional annual contract structures into monthly or event-based billing cycles. Volunteer administrators prefer pay-as-you-grow models that align software costs with registration volume fluctuations. This shift is most visible in the United States, where fragmented league structures resist long-term vendor commitments.
Sports League Management Software Market Segmentation
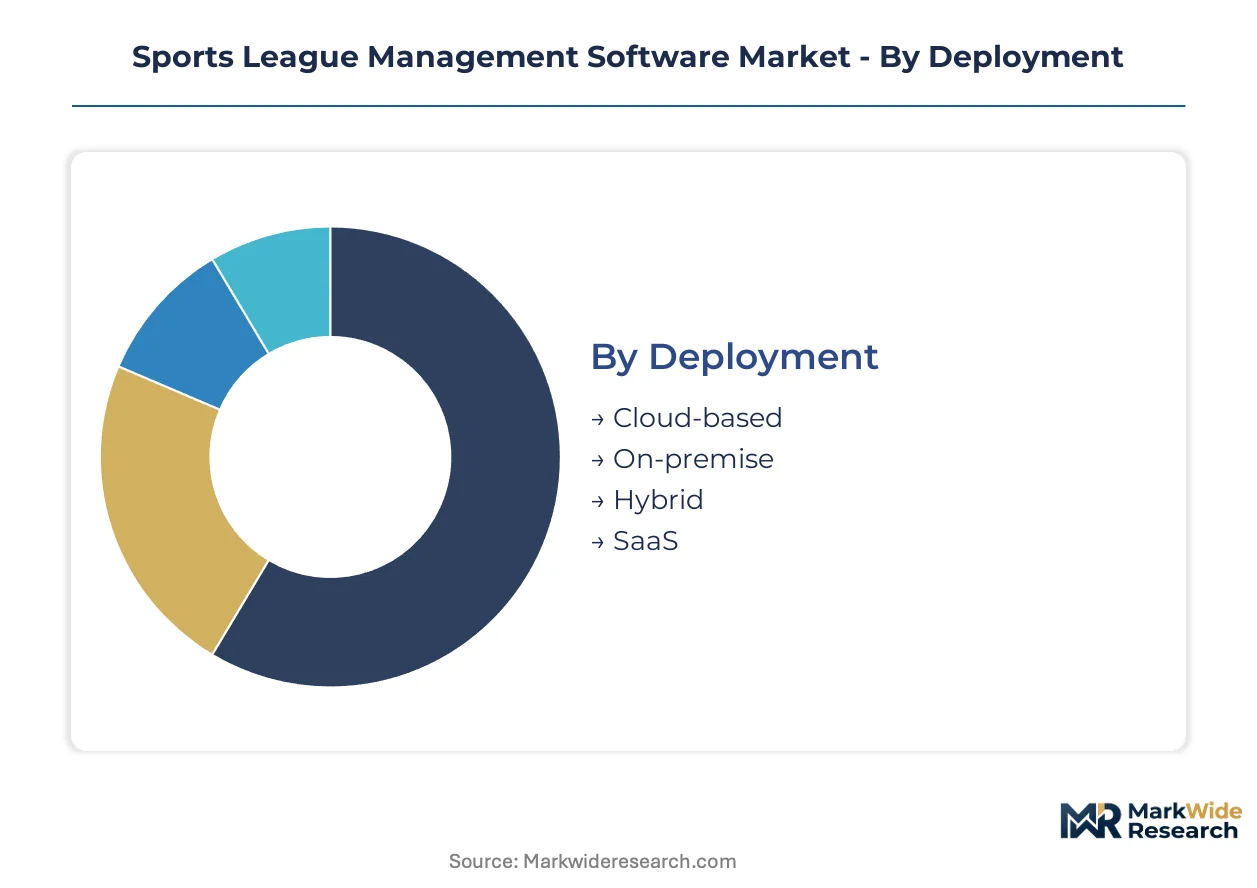
Sports league management software procurement hinges on matching operational complexity to deployment architecture and feature depth. Youth amateur clubs prioritize low-touch onboarding and mobile accessibility, while professional organizations demand data custody controls and federation interoperability. Understanding segment boundaries enables vendors to align R&D investment with buyer willingness-to-pay.
Deployment:
League administrators select deployment models based on IT staff capacity, data sensitivity requirements, and cash flow predictability.
- Cloud-based:Multi-tenant architectures with automatic scaling eliminate server maintenance burdens for volunteer-run organizations. Demand concentrates among community leagues in the United States where minimal upfront costs accelerate procurement decisions despite ongoing subscription commitments.
- On-premise:Single-tenant installations with localized data storage satisfy professional teams under Illinois and Texas biometric privacy statutes. These deployments persist where HIPAA-adjacent health data or payment card environments require physical infrastructure control.
- Hybrid:Split architectures route sensitive member data through on-premise nodes while pushing scheduling and communication workloads to cloud instances.
- SaaS:Browser-accessible platforms with API extensibility dominate new customer acquisition among mid-sized league operators seeking rapid deployment without infrastructure investment.
Cloud-based deployments lead on scale; SaaS offerings lead on momentum.
Solution/Offering:
Module selection follows the administrative pain points most acute to each league's operational model.
- Scheduling:Algorithmic venue allocation engines with conflict detection and automated referee assignment reduce tournament season coordination overhead. Educational institutions and training academies drive adoption where multi-field facilities require complex resource optimization.
- Registration Management:Digital intake workflows with document verification and waiver collection replace paper-based processes. Youth amateur clubs across North America prioritize these modules to eliminate data re-entry from handwritten forms during seasonal enrollment surges.
- Player Statistics:Real-time performance tracking with historical trend visualization supports coaching decisions and scouting workflows.
- Communication Tools:Push notification pipelines and group messaging replace email-based coordination for volunteer administrators managing distributed team networks.
- Payment Processing:Integrated fee collection with automated reconciliation reduces accounts receivable delays for community leagues dependent on registration revenue for seasonal cash flow.
Registration Management leads on scale; Payment Processing leads on momentum.
Application:
Sport-specific functionality requirements shape platform customization and integration priorities.
- Football:Roster management accommodating large squad sizes with position-specific depth charts and play diagramming tools. Demand concentrates in Texas and Florida where high school and youth tackle football participation sustains specialized platform configurations.
- Esports:Real-time match data APIs connecting to streaming platforms and automated bracket generation for digital-native competitions. This segment expands most quickly as tournament organizers seek broadcast-ready infrastructure unavailable in legacy athletic management systems.
- Basketball:Shot tracking integration and foul management with overtime period handling.
- Baseball:Pitch count monitoring and lineup optimization with substitution rule enforcement.
- Hockey:Shift timing and penalty box management with roster deadline compliance.
- Volleyball:Rotation tracking and libero designation with rally scoring adaptation.
Football leads on scale; Esports leads on momentum.
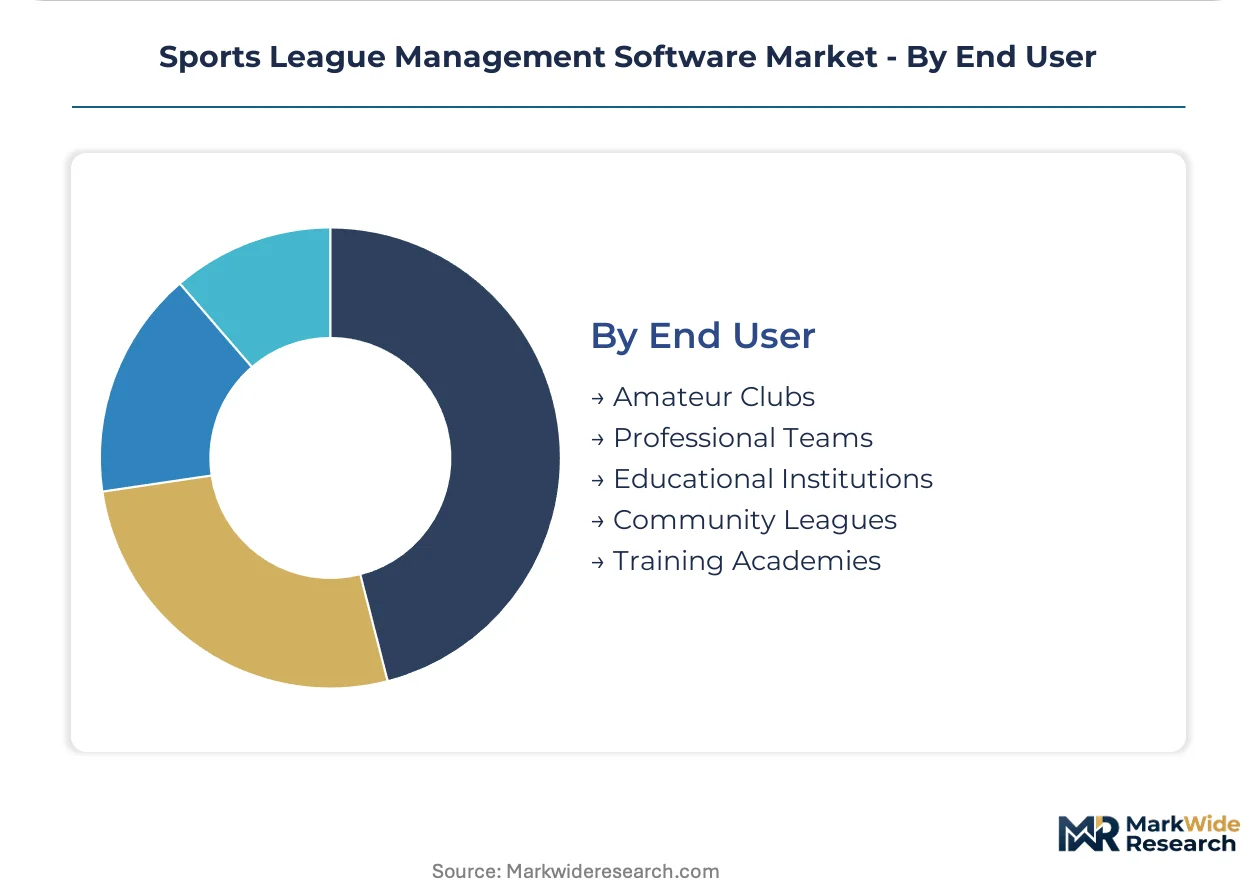
End User:
Organizational structure determines feature complexity tolerance and procurement authority concentration.
- Amateur Clubs:Volunteer-dependent operations requiring minimal training overhead and mobile-first interfaces. These organizations dominate unit volume across the United States where fragmented community sports structures resist enterprise sales cycles.
- Professional Teams:Staffed operations with dedicated IT resources demanding API access, custom reporting, and data export capabilities. Procurement concentrates where revenue scale justifies platform customization investment and dedicated support contracts.
- Educational Institutions:Athletic departments managing multiple sports under centralized compliance oversight.
- Community Leagues:Municipal or nonprofit operators coordinating across unaffiliated teams with standardized rule enforcement needs.
- Training Academies:Skill development focused organizations tracking longitudinal athlete progression with parent communication requirements.
Amateur Clubs lead on scale; Professional Teams lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metropolitan clusters dominate procurement volume for league management platforms, with municipal parks departments and independent youth associations driving cloud migration across fragmented community sports infrastructure.
United States
Texas and Florida high school athletic departments sustain specialized football roster configurations with position-specific depth chart modules. FCC digital accessibility guidelines mandate inclusive design standards for platforms serving federally funded recreation programs. Dallas-Fort Worth and Houston metropolitan clusters concentrate demand for integrated payment and registration systems among independent youth tackle football leagues.
Canada
Hockey associations across Ontario and Quebec require shift timing and penalty box management with roster deadline compliance features. The country's national privacy regulator enforces PIPEDA obligations for amateur leagues processing member biometric data from wearable devices. Toronto and Vancouver urban centers anchor adoption of bilingual platform interfaces serving French-English dual-language league operations.
United Kingdom
Football governing bodies and cricket county associations drive demand for multi-sport scheduling architectures with fixture coordination across shared municipal facilities. GDPR compliance frameworks from the European data protection supervisor mandate granular consent management for youth member databases. London and Manchester metropolitan areas concentrate platform procurement among semi-professional and amateur clubs seeking unified operational tools.
Germany
Handball and football federations require automated referee assignment engines with conflict detection for multi-venue tournament seasons. The country's federal data protection authority enforces stringent youth data custody protocols under national implementation of EU privacy directives. Munich and Berlin urban clusters lead adoption of white-label customization options among multi-sport municipal recreation departments.
Australia
Cricket associations and Australian rules football leagues demand real-time statistical tracking with historical trend visualization for coaching decisions. The country's national privacy regulator mandates data breach notification protocols for community sports organizations processing member health information. Sydney and Melbourne metropolitan areas concentrate demand for mobile-first communication tools among volunteer-run suburban clubs.
Sports League Management Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue esports-native functionality and API ecosystem expansion. The vendor base stratifies across three maturity tiers: legacy platforms with integrated payment modules, mobile-centric communication specialists, and configurable white-label providers for multi-sport governing bodies. Two dominant competitive moves define current positioning: strategic partnerships with wearable device manufacturers for data licensing revenue, and geographic expansion through compliance pre-certification for European GDPR and North American biometric privacy statutes.
Within the integrated platform tier, SportsEngine and LeagueApps exemplify contrasting archetypes—SportsEngine anchors enterprise account retention through payment-registration module bundling, while LeagueApps occupies a position emphasizing frontend configurability for branded league experiences. TeamSnap represents the mobile-centric specialist archetype, sitting within the volunteer-run organization segment through notification pipeline sophistication. These three entities collectively illustrate how vendor differentiation converges on operational workflow depth rather than core scheduling functionality alone.
| Leading Market Players |
|---|
| SportsEngine |
| TeamSnap |
| CommunityPass |
| Waresport |
| iSportz |
| SportNinja |
| LeagueApps |
| Leageez |
| Team Sideline |
| Others |
Cost & Logistics Intelligence
Horizontal integration into cloud infrastructure partnerships anchors supply positioning for sports league management software vendors while compressing customer acquisition costs through shared hosting economies. This integration choice simultaneously determines pricing power, as vendors with direct serverless architectures avoid margin erosion from third-party compute markups that plague smaller competitors serving volunteer-run organizations.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers drives SaaS-tiered subscription models across the market, with vendors stratifying pricing across premium, standard, and economy tiers based on feature depth and API access levels. Certification-grade differentiation separates GDPR-compliant platforms from baseline North American offerings, with European deployments commanding 15-30% premiums. Pricing pressure stems from volunteer administrator capacity constraints that resist long-term commitments. Amateur clubs exhibit highest price sensitivity due to registration revenue volatility, while professional teams accept premium tiers for data custody controls.
Supply Chain Analysis
Certification gating through GDPR pre-certification and FCC accessibility compliance filters vendor participation, concentrating development talent in the United States, Germany, and the United Kingdom where regulatory expertise clusters. Software supply chains draw from cloud infrastructure providers, payment processor APIs, and mobile notification services. Single-source vulnerability in payment processing partnerships creates operational risk for mid-tier vendors. Distribution runs through direct sales to league administrators and channel partnerships with multi-sport governing bodies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where GDPR obligations and state-level biometric privacy statutes continuously elevate platform requirements and consolidate vendor viability around compliance-capable providers.
For Market Incumbents: Hedge against API commoditization by deepening vertical integration into payment processing and registration workflows that create switching costs. SportsEngine's bundled module strategy exemplifies this defensive posture. Invest in Illinois and Texas biometric privacy pre-certification to capture professional team migrations from on-premise legacy systems. Certification investment serves as the priority lever for margin defense. For New Entrants and Emerging Players: AI-powered scheduling optimization represents a technology-first wedge for mid-sized league operators in the United States seeking tournament season efficiency gains. White-space concentration sits in esports-native functionality where legacy athletic platforms lack real-time match data APIs and automated bracket generation. Target municipal parks departments through FCC accessibility-first design positioning for procurement contract eligibility. For Investors and Strategic Acquirers: Roll-up economics work for configurable white-label platforms because multi-sport governing bodies demand branded experiences that resist point-solution fragmentation. Long-term viability centers on vendors with proven cross-border data handling certification and API ecosystem partnerships. Watch youth data protection legislation acceleration across multiple jurisdictions as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GDPR Pre-Certification Investment | Creates defensible moats for European amateur league contracts against non-compliant competitors. |
| API Ecosystem Expansion | Enables wearable device data licensing partnerships with broadcast systems for new revenue streams. |
| White-Label Customization Development | Positions platforms for multi-sport governing body procurement requiring branded frontend experiences. |
| Mobile-First Communication Enhancement | Sustains retention among volunteer-run organizations through notification pipeline sophistication. |
| Accessibility-First Design Certification | Qualifies vendors for municipal contracts under FCC digital platform guidelines. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with league administrators, platform product managers, payment processor partnership leads, and municipal parks department procurement officers. Secondary validation draws from SEC filings of publicly listed software vendors, GDPR enforcement actions by European data protection authorities, FCC accessibility guideline updates, and hyperscaler cloud infrastructure capex disclosures. Bottom-up triangulation across deployment model adoption rates and top-down validation through aggregate subscription revenue estimates ensure cross-verified outputs.
Granularity-level modeling operates at the intersection of deployment architecture, solution module, sport-specific application, and end-user organizational type. The analytical framework projects value expansion across the analysis window through segmented CAGR derivation based on cloud migration velocity among youth amateur clubs and esports league formation rates. Forecast inputs include volunteer administrator technical literacy trends and federation interoperability mandate proliferation timelines.
The model holds under steady regulatory enforcement intensity; deviation in youth data protection legislation acceleration or biometric privacy statute expansion would shift vendor consolidation dynamics. Forecasts incorporate assumptions around cloud infrastructure cost trajectories and mobile payment adoption curves. A model refresh is warranted upon material change in GDPR enforcement patterns or FCC accessibility procurement mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Global Online OCR Software Market
Software & Services
Mobile Application Development Market
Software & Services
File Analysis Software Market
Software & Services
Meditation Management Apps Market
Software & Services
HR Saas Market
Software & Services
Global Email Management Software Market
Software & Services
Global Microscope Software Market
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Air Cargo Software Market
Software & Services
Collaboration Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Global Ipad POS Software Market
Software & Services
Digital Illustration App Market
Software & Services
Global Back Testing Software Market
Software & Services
India Sports Management Software Market