
 North America Restaurant Management Software Market | 2026-2036
North America Restaurant Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
North America Restaurant Management Software Market Insights
Cloud infrastructure capacity across the United States and Canada is expanding to meet restaurant operator demand for real-time data synchronization. Oracle Corporation leverages its enterprise database heritage to anchor large franchise deployments. Toast, Inc. competes through vertically integrated hardware-software bundles designed for mid-market chains. NCR Corporation dominates legacy on-premises transitions with hybrid migration tools.
Restaurant management software encompasses point of sale, inventory management, staff scheduling, and reservation management platforms that synchronize front-of-house and back-of-house operations through centralized data architectures. These systems typically integrate payment processing, kitchen display systems, and third-party delivery APIs to reduce order latency and labor allocation errors. Point of sale deployments generate the deepest margin pools due to payment processing attach rates, while cloud-based delivery leads expansion as operators abandon server-room maintenance. Full-service restaurants represent the most mature end-user category with complex table-management requirements, whereas food trucks drive fastest adoption through mobile-first configurations.
FCC guidelines govern wireless payment terminal certifications, while PCI DSS standards mandate encryption protocols for cardholder data across all North American jurisdictions. State-level biometric privacy laws in Illinois and Texas increasingly shape facial-recognition payment authentication roadmaps. Stakeholders must monitor evolving state data-breach notification timelines alongside emerging FDA Food Code digitization requirements that could mandate digital temperature logging integration.
Market Dynamics
PCI DSS compliance deadlines and state-level biometric privacy mandates are forcing restaurant operators to replace legacy payment terminals before end-of-life, compressing procurement cycles and consolidating vendor selection around certified cloud-native platforms.
Growth Catalysts
- California Consumer Privacy Act (CCPA) expansions:Multi-location operators in California and Texas metro corridors accelerate unified system deployments to streamline data governance across state lines.
- Third-party delivery API integration:Full-service restaurants demand synchronized kitchen display systems to reduce order latency from DoorDash, Uber Eats, and Grubhub channels.
- Food trucks and mobile-first configurations:Cellular-enabled POS terminals with offline transaction caching penetrate this fastest-growing operator category.
Market Restraints
- Payment processor concentration:Three dominant processors control interchange fee structures, limiting margin capture for software vendors.
- Legacy on-premises technical debt:Decades-old SQL Server and AS/400 installations resist cloud migration without expensive middleware layers.
- Illinois Biometric Information Privacy Act (BIPA):Facial-recognition payment authentication roadmaps face litigation exposure and compliance delays.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia multi-unit operators show underpenetrated demand for unified labor-scheduling and inventory modules.
- FDA Food Code digitization:Proposed digital temperature logging mandates create attach-rate opportunities for IoT sensor integrations.
- Voice-ordering and AI-driven upselling convergence:Drive-thru chains pilot natural-language processing for order accuracy and check-size optimization.
Industry Challenges
- Certification timeline compression:FCC wireless terminal certifications and PCI DSS validation cycles now overlap, stretching engineering resources.
- Integration complexity with fragmented legacy POS:Proprietary protocols from 1990s-era systems require expensive custom API development.
- Cybersecurity talent scarcity:Qualified penetration testers and encryption specialists command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Restaurant Management Software Market |
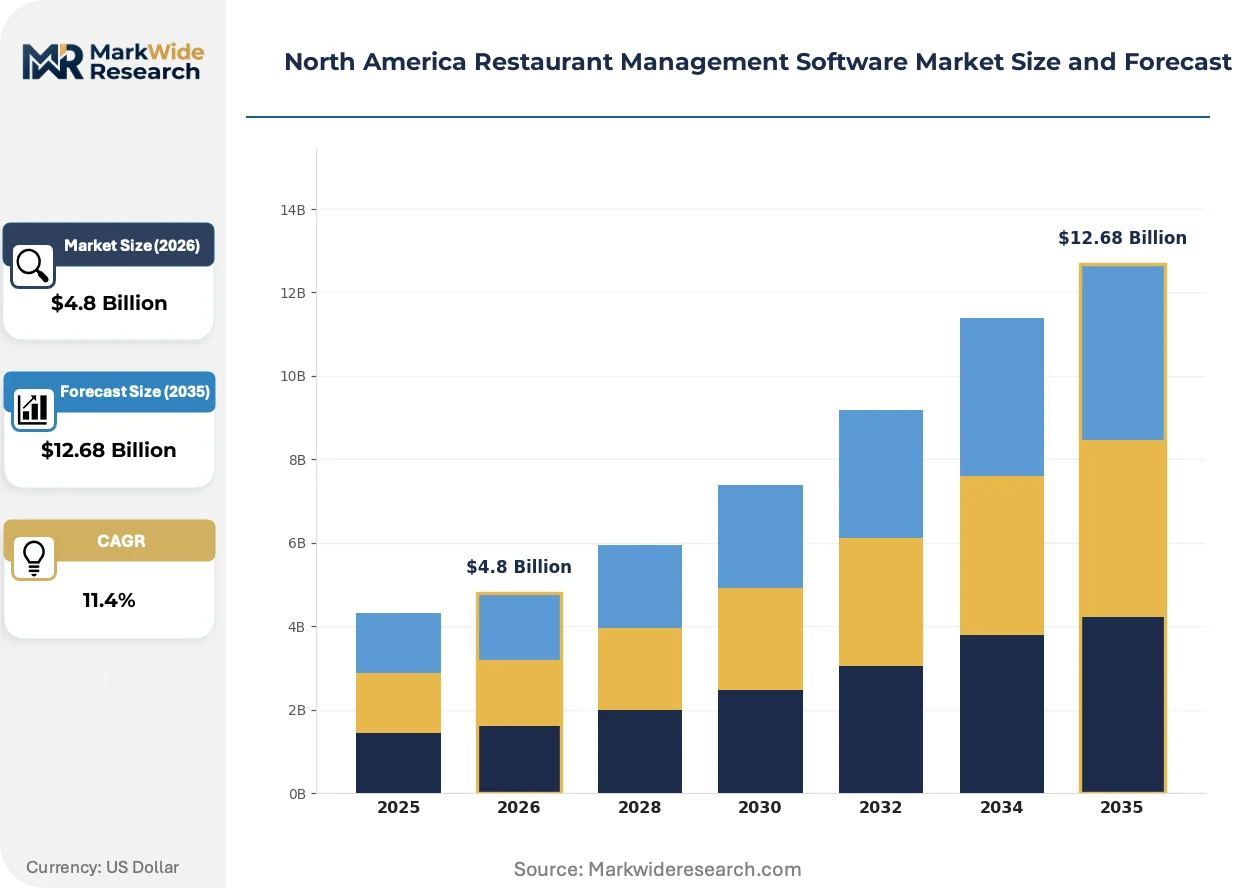
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point of Sale, Inventory Management, Staff Scheduling, Reservation Management End User: Full-Service Restaurants, Quick Service Restaurants, Cafés, Food Trucks Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | Oracle Corporation, Revel Systems, TouchBistro, Fourth, Fiserv, NCR Corporation, Lightspeed Commerce, Jolt, Toast, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Restaurant Management Software Market Trends and Innovations
Real-time data synchronization requirements are reshaping how restaurant operators evaluate vendor architectures, with latency tolerance thresholds tightening across all deployment scales.
Edge computing nodes deployed inside restaurant locations are absorbing transaction processing loads previously routed to centralized cloud data centers. Quick-service chains with 500-plus locations adopt these micro-datacenter configurations to maintain POS uptime during internet outages. This distributed architecture is absorbing reliability risk from last-mile connectivity failures while adding hardware complexity to vendor support models.
The Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act impose consent and retention rules on facial-recognition payment systems. Vendors must now maintain separate authentication roadmaps for states with biometric statutes versus those without. Full-service restaurants in Chicago and Dallas-Fort Worth delay facial-pay rollouts pending legal clarity, while operators in jurisdictions without such laws accelerate trials.
Subscription-based pricing models displace perpetual-license structures across mid-market chain procurement. Chief financial officers prefer operational expenditure treatment for software costs amid interest rate volatility. This preference shift concentrates in California and Texas metro corridors where private-equity-backed restaurant groups dominate ownership structures and optimize balance-sheet metrics.
North America Restaurant Management Software Market Segmentation
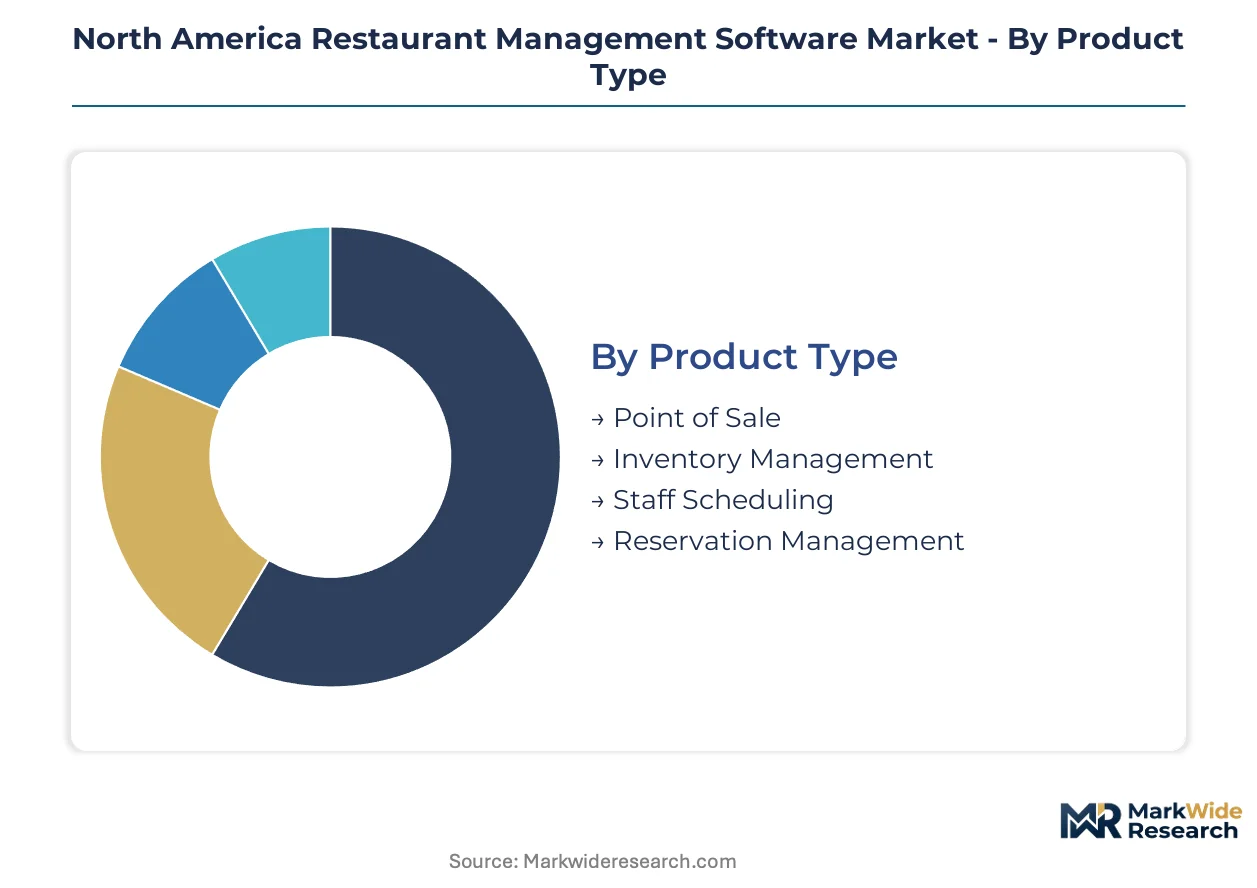
Restaurant operators across North America select management software modules based on operational complexity and compliance burden. Segmentation reveals where procurement budgets concentrate and which deployment architectures are displacing legacy infrastructure.
Product Type:
Replacement cycles accelerate as PCI DSS deadlines force terminal upgrades and cloud-native architectures displace server-room installations.
- Point of Sale:Hardware-software bundles process card-present transactions through encrypted payment terminals with integrated kitchen display routing. Full-service restaurants in California and Texas metro corridors prioritize these deployments to unify multi-location reconciliation and reduce interchange leakage.
- Inventory Management:Real-time ingredient tracking modules synchronize with supplier APIs and recipe-costing databases to automate par-level alerts. Quick-service chains with 500-plus locations deploy these systems most aggressively to compress food-cost variance across distributed kitchens.
- Staff Scheduling:Labor-optimization platforms integrate POS transaction data with predictive demand algorithms to automate shift allocation.
- Reservation Management:Table-inventory systems synchronize online booking channels with floor-plan optimization to reduce turn-time gaps.
Volume placements concentrate in Point of Sale; the faster expansion belongs to Inventory Management.
End User:
Operator scale and real-estate footprint determine deployment complexity and integration requirements across customer categories.
- Full-Service Restaurants:Complex table-management requirements drive demand for reservation-POS-kitchen display integration with split-check functionality and coursing controls. PCI DSS compliance mandates and CCPA data governance obligations compress procurement timelines for multi-location operators in California and Texas.
- Quick Service Restaurants:High-throughput configurations prioritize drive-thru optimization, kitchen display synchronization, and loyalty program integration at the POS. Chains with 500-plus locations dominate this segment's technology budgets as they pilot voice-ordering AI and edge-computing nodes for uptime resilience.
- Cafés:Counter-service models favor tablet-based POS with mobile payment acceptance and simplified inventory modules for ingredient batches.
- Food Trucks:Cellular-enabled terminals with offline transaction caching penetrate this category fastest as mobile-first configurations bypass fixed infrastructure entirely.
Technology spending concentrates in Full-Service Restaurants; Food Trucks are climbing the fastest as cellular-first architectures eliminate capital barriers.
Deployment:
Cost tier differentiation separates enterprise-grade reliability investments from mid-market operational expenditure preferences.
- Cloud-Based:Subscription-priced SaaS architectures eliminate server-room maintenance and enable real-time data synchronization across distributed locations. Private-equity-backed restaurant groups in California and Texas metro corridors favor this model to optimize balance-sheet metrics amid interest rate volatility.
- On-Premises:Legacy SQL Server and AS/400 installations persist where technical debt and proprietary protocol dependencies resist migration without expensive middleware layers.
- Hybrid:Mixed architectures preserve sensitive payment data on local nodes while routing analytics to cloud dashboards for multi-location visibility.
- Mobile:Cellular-first deployments with offline caching serve food trucks and pop-up operations where fixed connectivity is unavailable.
Contract values concentrate in Cloud-Based deployments; Mobile configurations are gaining share fastest among emerging operator categories.
Service Type:
Margin capture varies sharply between one-time implementation revenue and recurring support streams.
- Consulting:Workflow redesign and compliance-readiness assessments guide operators through PCI DSS certification and state-level biometric privacy alignment.
- Implementation:System integration, data migration, and staff training services generate project-based revenue concentrated in full-service restaurant deployments.
- Support:24/7 technical assistance and escalation management command premium pricing from quick-service chains where POS downtime halts revenue.
- Maintenance:Patch management, security updates, and hardware replacement programs produce the most predictable recurring revenue streams.
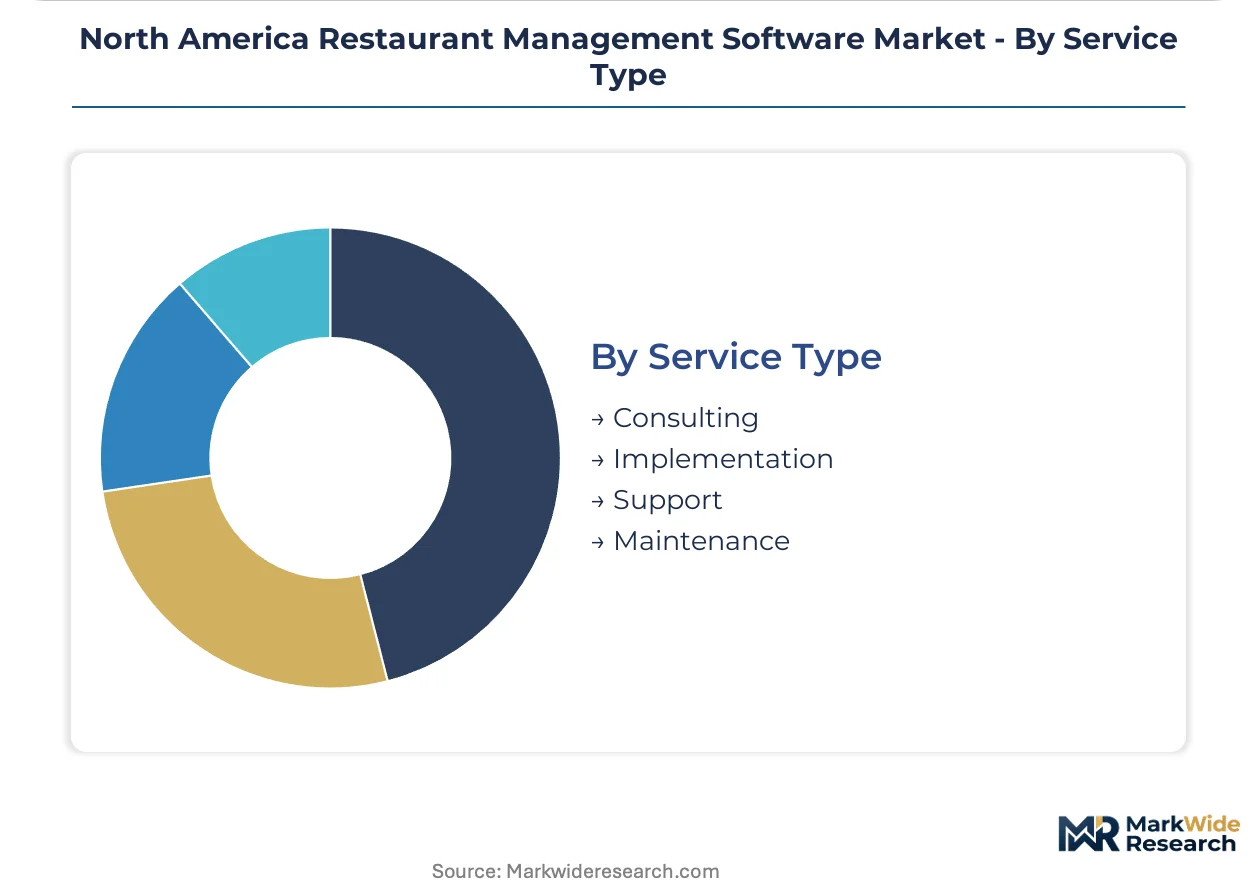
Revenue concentration sits with Maintenance contracts; Consulting services show the steepest expansion trajectory as compliance complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscale data centers anchor cloud infrastructure capacity for restaurant software deployments across the continent.
United States
California and Texas metro corridors concentrate multi-location operator demand for unified cloud-based systems. The FCC governs wireless payment terminal certifications while PCI DSS compliance deadlines compress procurement cycles for legacy terminal replacements. Chicago and Dallas-Fort Worth operators delay facial-recognition payment rollouts pending clarity on Illinois BIPA and Texas biometric statutes.
Canada
Ontario and British Columbia multi-unit operators show underpenetrated demand for unified labor-scheduling and inventory modules. Health Canada coordinates with provincial regulators on payment processing standards while the Office of the Privacy Commissioner monitors biometric data collection practices. Toronto and Vancouver technology clusters host emerging SaaS vendors targeting cross-border franchise deployments.
Mexico
Mexico City Metro and Nuevo León restaurant groups accelerate POS modernization amid informal-to-formal sector transitions. The central bank (Banco de México) supervises payment system stability while PROFECO enforces consumer protection standards for digital transactions. Guadalajara's emerging technology corridor attracts regional software development centers serving Spanish-language operator segments.
North America Restaurant Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue mobile-first configurations and voice-ordering AI convergence. The vendor base stratifies across enterprise database heritage, vertically integrated hardware-software bundles, and legacy on-premises migration specialists. Three archetypes dominate: cloud-native platform builders, hybrid architecture transition enablers, and cellular-enabled mobile deployment innovators. Consolidation pressure intensifies through strategic partnerships and vertical integration moves.
Within the enterprise heritage tier, Oracle Corporation and NCR Corporation anchor large franchise and legacy transition deployments respectively. Toast, Inc. exemplifies the vertically integrated bundle approach targeting mid-market chains with hardware-software convergence. These three occupy positions spanning the deployment complexity spectrum from hyperscale cloud to edge-computing node configurations.
| Leading Market Players |
|---|
| Oracle Corporation |
| Revel Systems |
| TouchBistro |
| Fourth |
| Fiserv |
| NCR Corporation |
| Lightspeed Commerce |
| Jolt |
| Toast, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native SaaS architectures are displacing perpetual-license deployments across California and Texas metro corridors, compressing vendor cost structures while concentrating procurement power among private-equity-backed restaurant groups that negotiate enterprise-tier subscriptions across multi-location footprints. This technology transition simultaneously reduces hardware maintenance burdens for operators and shifts margin capture toward recurring support streams for vendors.
Pricing Analysis
Warranty and service bundling separates premium-tier contracts from standard SaaS offerings, with PCI DSS compliance validation and 24/7 uptime guarantees commanding attach-rate premiums. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, integration depth, and support responsiveness. Cost compression in the standard tier is intensifying because payment processor concentration limits software vendor margin capture. Quick-service chains with 500-plus locations show least price sensitivity due to downtime cost exposure, while independent food trucks prioritize economy cellular-first configurations.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for encrypted payment terminal chipsets, where semiconductor fabrication concentrates. Hardware-software bundles draw from Chinese component assembly for POS terminals, Mexican manufacturing for edge-computing node enclosures, and domestic U.S. final integration. Tariff exposure runs through cross-border component flows for payment hardware. Distribution runs through direct vendor sales teams for enterprise deployments and value-added resellers for mid-market chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where payment processing attach rates and hardware-software convergence determine competitive durability. Incumbents and entrants alike pursue downstream control over transaction economics to defend margin pools.
For Market Incumbents: Anchor cloud infrastructure investments in Silicon Valley and Toronto data center clusters to maintain latency advantages for real-time kitchen display synchronization. Consolidate around PCI DSS certification pre-validation to compress procurement cycles threatened by Toast's vertically integrated bundles. Prioritize backward integration into payment processing to reduce interchange leakage and capture deeper margin pools from transaction volume. For New Entrants and Emerging Players: Capture underpenetrated demand among Ontario and British Columbia multi-unit operators seeking unified labor-scheduling and inventory modules absent dominant incumbent presence. Food trucks and mobile-first configurations offer fastest penetration velocity given minimal legacy technical debt and cellular-enabled deployment simplicity. Lead with offline transaction caching and API-native architecture as differentiated go-to-market positioning against server-room-dependent competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by payment processors seeking software-layer integration or hyperscale cloud providers expanding vertical SaaS portfolios. Long-term viability hinges on recurring revenue concentration exceeding eighty percent and net revenue retention above benchmark thresholds for restaurant technology. Monitor FDA Food Code digitization rulemaking as inflection signal for IoT sensor integration attach-rate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies POS, kitchen display, and third-party delivery APIs to reduce order latency for DoorDash and Uber Eats channels. |
| Geographic Expansion | Targets Ontario and British Columbia multi-unit operators with localized compliance for Canadian provincial labor regulations. |
| Strategic Partnership | Aligns with edge-computing hardware vendors to maintain POS uptime resilience during internet outages for 500-plus location chains. |
| Product Launch | Introduces voice-ordering AI modules for drive-thru accuracy and check-size optimization in quick-service deployments. |
| Acquisition of Specialist Firm | Absorbs IoT sensor developers to capture FDA Food Code digitization mandates for digital temperature logging integration. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and PCI DSS certification databases formed the secondary backbone, supplemented by customs records for payment hardware import flows. Primary interviews with restaurant technology executives, multi-location operator IT directors, and POS integration specialists validated deployment trend assumptions. Bottom-up location-count modeling across California and Texas metro corridors combined with top-down vendor revenue triangulation across the analysis window.
Historical trendline analysis examined subscription pricing migration patterns and cloud-deployment velocity across full-service and quick-service operator categories. The analytical framework modeled deployment model, organization size, vertical segment, and integration complexity dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory blending rather than single-source extrapolation. Forecast inputs incorporated PCI DSS compliance deadline impacts and state-level biometric privacy law adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to payment processor consolidation, FCC wireless certification timeline shifts, and Illinois BIPA litigation exposure. Forecasts reflect documented assumptions regarding cloud infrastructure capacity expansion and restaurant operator capital expenditure preferences. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Air Cargo Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global Website Builder Software Market
Software & Services
CGI Software Market
Software & Services
Middleware Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Data Discovery Software Market
Software & Services
Background Removal Software Market
Software & Services
Global Document Management Software Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Clustering Software Market
Software & Services
Illustration Software Market
Software & Services
France HR Payroll Software Market
Software & Services
Online Lottery Software Market
Software & Services
Push Notifications Software Market