
 Hydraulic Modeling Software Market | 2026-2036
Hydraulic Modeling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Modeling Software Market Analysis
Project finance for municipal water infrastructure is reconfiguring competitive dynamics in hydraulic modeling software, as asset-light SaaS subscriptions replace perpetual licensing for budget-constrained public buyers. Bentley Systems leverages its integrated engineering software ecosystem to anchor municipal accounts across North America and Europe. Innovyze specializes in water distribution network analytics, while DNV competes through maritime and offshore fluid dynamics expertise that extends into coastal flood applications.
Hydraulic modeling software encompasses computational tools that simulate fluid behavior in pipe networks, open channels, and surface water systems using numerical methods such as finite difference and finite volume algorithms. These platforms integrate topographic data, rainfall records, and infrastructure schematics to predict flow rates, pressure distributions, and flood inundation extents for design and operational decisions. Real-time modeling segments are gaining structural prominence as utilities deploy sensor-integrated digital twins for operational control, while 2D modeling maintains maturity in standard stormwater compliance workflows. Cloud-based deployment is capturing the fastest expansion as engineering firms and environmental consultants seek collaborative platforms that reduce on-premise IT overhead.
EPA stormwater regulations and the EU Floods Directive shape product requirements by mandating predictive analytics for combined sewer overflow mitigation and flood hazard mapping. ISO standards for hydraulic structure design influence software validation protocols that vendors must satisfy for engineering firm procurement. Stakeholders should monitor evolving interoperability mandates between modeling platforms and utility SCADA systems, as regulatory pressure for real-time infrastructure resilience intensifies without uniform data standards across jurisdictions.
Market Dynamics
Cloud-native architectures are compressing deployment cycles for hydraulic modeling platforms, forcing incumbent vendors to reengineer legacy codebases while municipal buyers abandon perpetual licenses for operational expenditure models.
Growth Catalysts
- EPA stormwater mandates:Combined sewer overflow regulations in the United States require predictive analytics for infrastructure upgrades, pulling engineering firms toward simulation platforms with real-time sensor integration.
- Digital twin convergence:Utilities are deploying sensor-integrated hydraulic replicas for operational control, creating demand for platforms that synchronize SCADA data with simulation engines.
- Netherlands dike safety protocols:National water boards mandate real-time flood simulation capabilities, concentrating procurement among specialized engineering consultancies serving Rhine-Meuse-Scheldt delta systems.
Market Restraints
- Legacy data silos:Municipal utilities operate decades-old asset databases in incompatible formats, creating friction for cloud migration and inflating implementation timelines.
- Specialized talent scarcity:Computational fluid dynamics expertise concentrates within academic institutions and national research laboratories, constraining vendor scaling.
- High-performance computing costs:Two-dimensional flood simulations demand GPU clusters that strain public sector IT budgets, particularly in smaller municipalities.
Strategic Opportunities
- EU Floods Directive implementation gaps:Member states with delayed transposition schedules present first-mover advantages for vendors offering compliant hazard mapping workflows.
- AI-accelerated mesh generation:Machine learning algorithms trained on topographic datasets are reducing preprocessing time for complex terrain models, opening new service lines.
- Subscription pricing penetration:Asset-light SaaS models are unlocking procurement pathways for budget-constrained environmental consultancies previously excluded from enterprise licensing tiers.
Industry Challenges
- Interoperability standard gaps:Absence of unified data exchange protocols between modeling platforms and utility SCADA systems forces costly custom integration projects.
- Validation protocol divergence:ISO hydraulic structure standards vary by national adoption, complicating software certification for engineering firms operating across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Modeling Software Market |
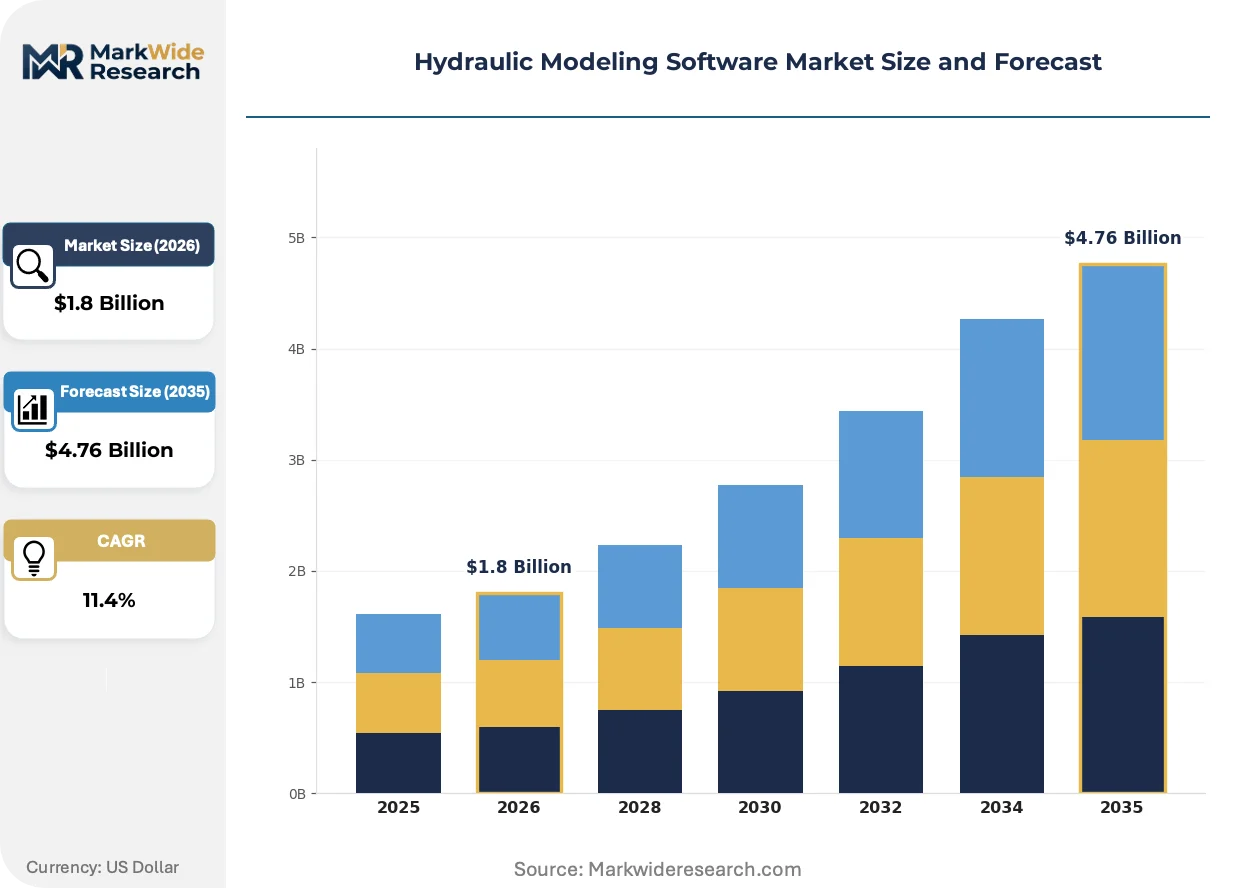
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Modeling, 3D Modeling, Computational Fluid Dynamics, Real-Time Modeling Application: Urban Planning, Water Resource Management, Stormwater Analysis, Flood Risk Assessment Deployment: On-Premise, Cloud-Based, Hybrid, Software as a Service End User: Municipalities, Environmental Consultants, Engineering Firms, Research Institutions |
| Companies Covered | KYPipe LLC, DNV, Bentley Systems, Haestad Methods, Innovyze, Autodesk, Carlson Software, XP Solutions, CivilGEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Modeling Software Market Emerging Trajectories
Computational methods are pivoting from batch-processed design simulations toward continuous operational intelligence, embedding hydraulic models directly into infrastructure control loops.
GPU-accelerated finite volume solvers are rendering obsolete CPU-dependent computation for two-dimensional flood inundation mapping. German environmental agencies are deploying these architectures for Rhine basin real-time forecasting, compressing simulation runtimes from hours to minutes. This performance leap is collapsing the distinction between design-phase and operational-phase software categories.
The EU Floods Directive's 2026 reporting deadlines are forcing member states to standardize hazard mapping methodologies. Engineering consultancies in the Netherlands and Belgium are consolidating procurement around platforms with pre-validated compliance modules. Vendors are responding by embedding national hydraulic structure databases directly into subscription tiers.
Municipal engineering departments are unbundling software procurement from implementation services, creating direct vendor relationships that bypass traditional systems integrators. This pattern concentrates in North American cities with mature IT procurement offices. Environmental consultancies are pivoting toward specialized modeling expertise rather than platform resale margins.
Hydraulic Modeling Software Market Segmentation
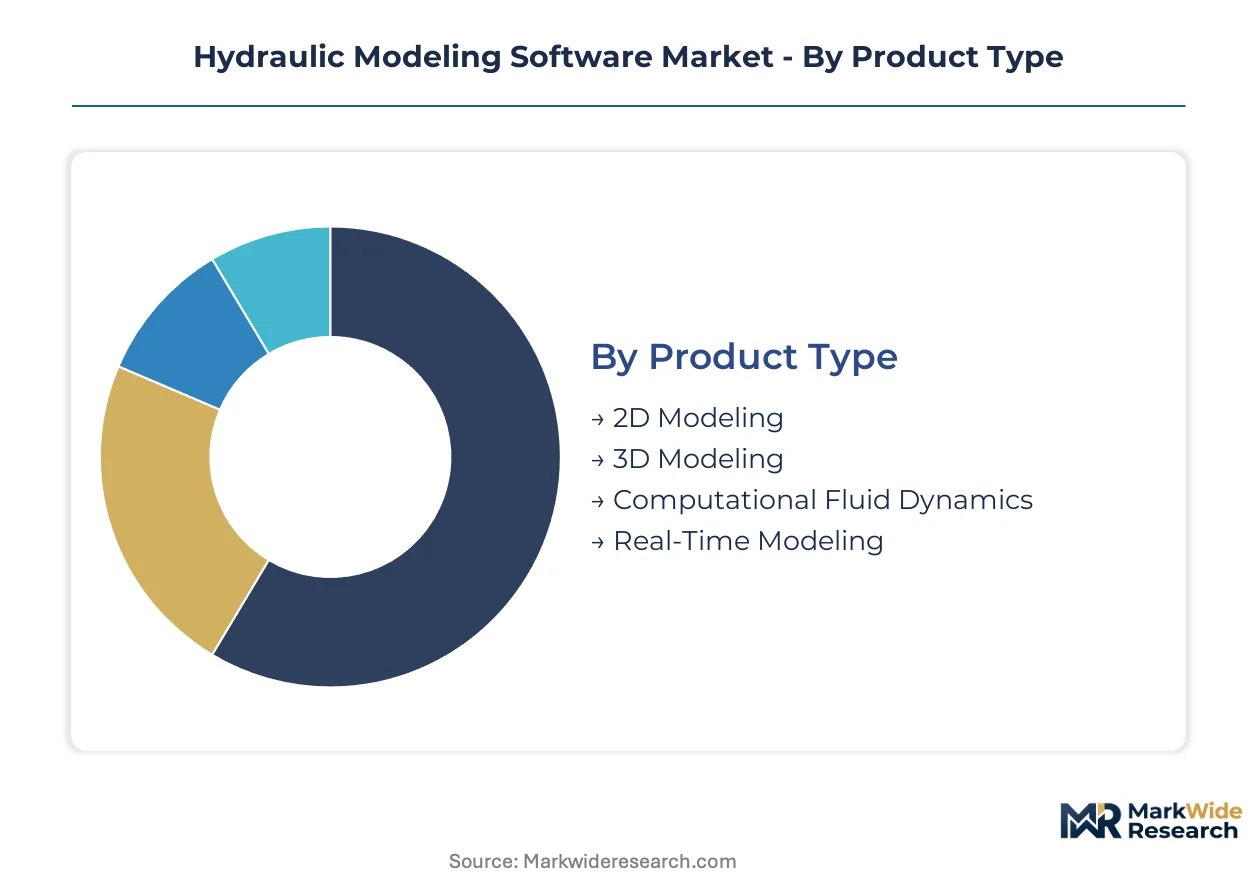
Segmentation in hydraulic modeling software reveals how computational methods, deployment architectures, and buyer types allocate investment across design-phase and operational-phase use cases. Distinct technical requirements separate municipal procurement from engineering consultancy adoption.
Product Type:
Maturity spans from established 2D platforms to emerging real-time architectures that embed simulation engines directly into infrastructure control systems.
- 2D Modeling:Finite difference and finite volume algorithms simulate surface water flow across topographic grids for floodplain mapping and stormwater compliance. German environmental agencies deploy these platforms for Rhine basin forecasting, where runtime compression from hours to minutes is reshaping operational workflows.
- Real-Time Modeling:Sensor-integrated digital twins synchronize SCADA data with hydraulic engines for continuous infrastructure control. Dutch water boards mandate these capabilities for dike safety assessments in the Rhine-Meuse-Scheldt delta, concentrating procurement among specialized engineering consultancies.
- 3D Modeling:Navier-Stokes solvers resolve complex flow structures around hydraulic structures and urban drainage junctions.
- Computational Fluid Dynamics:High-fidelity turbulence modeling serves offshore maritime applications and detailed structure design validation.
2D Modeling handles the majority of throughput; Real-Time Modeling is gaining share fastest as utilities deploy sensor-integrated infrastructure control.
Application:
Cost tier separation distinguishes capital-intensive flood risk platforms from operational expenditure models in urban planning and stormwater compliance.
- Flood Risk Assessment:Probabilistic flood mapping integrates hydrologic models with climate projections for insurance pricing and land-use regulation. Netherlands and Belgium engineering consultancies are consolidating procurement around platforms with pre-validated EU Floods Directive compliance modules.
- Stormwater Analysis:Combined sewer overflow simulation supports EPA-mandated infrastructure upgrades in United States municipalities. Cloud-based platforms with real-time sensor integration are pulling engineering firms toward subscription pricing models.
- Urban Planning:Zoning and development review tools simulate drainage impacts for building permit evaluation.
- Water Resource Management:Allocation optimization models balance agricultural, industrial, and municipal demands across river basin systems.
Flood Risk Assessment commands premium pricing tiers; Stormwater Analysis is expanding most quickly under regulatory compliance deadlines.
Deployment:
Volume concentration is shifting from perpetual licenses toward recurring revenue architectures that reduce municipal IT overhead.
- Cloud-Based:Browser-accessible platforms enable collaborative model development across distributed engineering teams. United States municipalities are expanding procurement to comply with EPA stormwater regulations while avoiding on-premise server maintenance.
- Software as a Service:Subscription tiers embed national hydraulic structure databases and compliance validation workflows. Environmental consultancies previously excluded from enterprise licensing are unlocking procurement pathways through asset-light pricing.
- On-Premise:Installed software persists in high-security environments and legacy IT infrastructures with restricted external connectivity.
- Hybrid:Mixed architectures keep sensitive asset data local while leveraging cloud compute for simulation processing.
Cloud-Based deployment captures the steepest expansion trajectory; Software as a Service is penetrating the mid-market fastest.
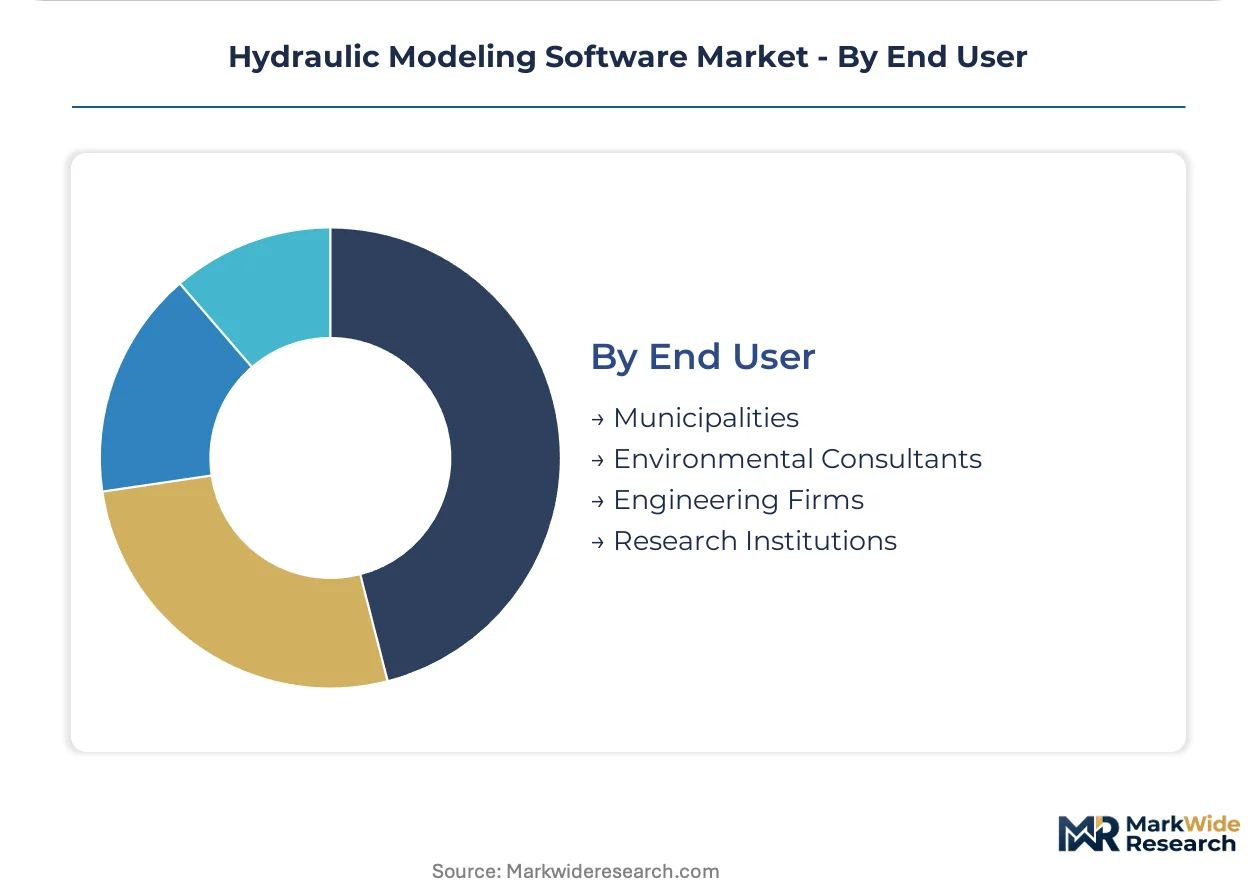
End User:
Customer type determines procurement authority and implementation complexity, from centralized municipal IT departments to decentralized research laboratories.
- Engineering Firms:Multi-project licensing supports consultancy workflows across flood-prone river basins in Germany and the Netherlands. National water board mandates for real-time simulation capabilities are concentrating demand among specialized providers.
- Municipalities:Budget-constrained public buyers are abandoning perpetual licenses for operational expenditure models. Cloud-native platforms compress deployment cycles while reducing upfront capital requirements.
- Environmental Consultants:Specialized modeling expertise is replacing platform resale margins as municipal departments unbundle software from implementation services.
- Research Institutions:Academic licenses support method development and validation studies for next-generation solver algorithms.
Engineering Firms represent the largest revenue pool; Municipalities are converting fastest to subscription architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal engineering departments and water utilities concentrate procurement across five national markets where regulatory mandates and infrastructure investment cycles align. Each geography exhibits distinct buyer archetypes shaped by compliance deadlines and procurement sophistication.
United States
EPA stormwater regulations drive municipal procurement of cloud-based platforms with real-time sensor integration. Engineering firms serving combined sewer overflow mitigation projects pull demand toward subscription pricing models. Chicago and Philadelphia anchor implementation activity where legacy infrastructure upgrades dominate capital planning.
Germany
Rhine basin flood forecasting requirements concentrate demand among specialized environmental consultancies. State environmental agencies deploy GPU-accelerated platforms for real-time inundation mapping. The Cologne-Düsseldorf corridor hosts engineering clusters where national water board mandates reshape vendor selection criteria.
Netherlands
Dike safety protocols in the Rhine-Meuse-Scheldt delta mandate continuous simulation capabilities for water board procurement. Rotterdam and Amsterdam municipal utilities pioneer digital twin deployments for operational flood control. National hydraulic structure databases embed directly into compliant software tiers.
United Kingdom
Environment Agency flood risk mapping programs sustain consultancy demand for 2D modeling platforms. Thames Estuary infrastructure resilience projects accelerate cloud migration among London borough engineering departments. Scottish Water's digital transformation creates secondary demand for sensor-integrated systems.
Belgium
EU Floods Directive transposition deadlines compress procurement timelines for Flemish and Walloon water authorities. Engineering consultancies in Brussels and Antwerp consolidate around pre-validated compliance modules. Scheldt basin coordination requirements favor platforms with cross-border data interoperability.
Hydraulic Modeling Software Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure where integrated engineering software ecosystems anchor municipal accounts while vertical specialists capture consultancy workflows. The vendor base organizes around three archetypes: platform conglomerates with cross-disciplinary integration, water-domain specialists with network analytics depth, and maritime-fluid dynamics hybrids extending into coastal applications. Dominant competitive moves include cloud-native reengineering of legacy codebases and unbundling of implementation services from software licensing.
Within the integrated-platform tier, Bentley Systems occupies a position exemplifying ecosystem-based municipal anchoring across North American and European accounts. Innovyze represents the water-specialist archetype with concentrated expertise in distribution network analytics. DNV sits within the maritime-extension category, translating offshore fluid dynamics capabilities into coastal flood applications. These three anchors illustrate how vendor origin shapes competitive positioning without determining market outcomes.
| Leading Market Players |
|---|
| KYPipe LLC |
| DNV |
| Bentley Systems |
| Haestad Methods |
| Innovyze |
| Autodesk |
| Carlson Software |
| XP Solutions |
| CivilGEO |
| Others |
Supply Flow & Price Mechanics
Cologne-Düsseldorf engineering clusters anchor European hydraulic modeling capacity, with GPU-accelerated solver development concentrated among German environmental consultancies serving Rhine basin forecasting contracts. This geographic concentration grants incumbent vendors pricing power over municipal buyers facing EPA stormwater compliance deadlines.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO-validated hydraulic structure modules commanding subscription premiums from engineering firms operating across multiple jurisdictions. Three-tier pricing structure across premium, standard, and economy levels segments by real-time sensor integration depth and compliance database coverage. Cost compression in mid-market SaaS tiers intensifies because cloud-native entrants are undercutting legacy perpetual-license conversions. Municipalities exhibit highest price sensitivity, while Dutch water boards mandated by dike safety protocols show lowest elasticity.
Supply Chain Analysis
Export-control restrictions on GPU-accelerated computing hardware limit flows to Chinese infrastructure software vendors, constraining solver development capacity outside approved jurisdictions. Supply concentrates in Germany, the Netherlands, and the United States for core algorithm development, with cloud compute infrastructure drawing from hyperscaler networks in Ireland and Virginia. Raw material dependencies include proprietary mesh-generation libraries, topographic LiDAR datasets, and SCADA integration middleware. Single-source vulnerability runs through NVIDIA GPU allocation queues for high-performance flood simulation clusters. Distribution runs through direct vendor relationships that municipal IT departments are consolidating, bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in hydraulic modeling software reflects accelerating digital twin deployment among utilities seeking operational-phase revenue streams beyond design-tool licensing.
For Market Incumbents: Harden cloud-native architecture investments against emerging vertical specialists threatening municipal account erosion. Prioritize backward integration into sensor hardware partnerships to lock SCADA data flows. Defensive patent filings around AI-accelerated mesh generation algorithms will constrain entrant solver development timelines. For New Entrants and Emerging Players: Establish a beachhead in Belgian and Polish engineering consultancies facing EU Floods Directive compliance gaps with limited incumbent penetration. Target mid-tier environmental consultancies previously excluded from enterprise licensing through asset-light SaaS tiers. Go-to-market leverage rests on pre-validated national hydraulic structure databases that compress implementation timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors water-domain specialists with network analytics depth over integrated platform conglomerates facing cloud-reengineering costs. Five-to-ten-year viability hinges on real-time modeling segment capture as utilities operationalize digital twins. Acquisition targets should exhibit proven SCADA integration capabilities and compliance module pre-certification. Monitor EPA enforcement intensity on combined sewer overflow regulations as inflection signal for municipal procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses deployment cycles for municipal buyers abandoning perpetual licenses under EPA stormwater mandates. |
| SCADA Integration Partnership | Locks operational data flows for digital twin deployments mandated by Netherlands dike safety protocols. |
| AI-Accelerated Mesh Generation | Reduces preprocessing time for German environmental agencies deploying Rhine basin real-time forecasting. |
| Compliance Module Pre-Certification | Accelerates procurement timelines for Belgian consultancies facing EU Floods Directive reporting deadlines. |
| Sensor Hardware Backward Integration | Captures telemetry revenue streams from utilities deploying continuous infrastructure control systems. |
Methodological Framework
Desk research of EPA enforcement records, EU Floods Directive transposition schedules, and municipal procurement databases preceded structured interviews with water utility CTOs, engineering firm project directors, environmental consultancy principals, and national water board procurement officers. Secondary validation drew from SEC filings of publicly traded infrastructure software vendors, hyperscaler cloud revenue disclosures, and ISO hydraulic structure standard revision drafts. Bottom-up triangulation across vendor-reported subscription metrics and top-down validation against municipal IT budget allocations anchored volume estimates.
Assumptions held fixed include regulatory enforcement intensity on stormwater compliance and cloud migration rates among budget-constrained public buyers, while GPU cost curves and SCADA interoperability standard adoption were varied across sensitivity scenarios. Segmentation dimensions modeled encompass deployment architecture, end-user type, application use case, and real-time versus design-phase functionality. CAGRs were derived from logistic adoption curves fitted to historical SaaS transition patterns in adjacent infrastructure software categories. Industry-specific inputs included Rhine basin flood frequency datasets and EPA consent decree timelines for combined sewer overflow mitigation.
Sensitivities concentrate around EPA enforcement acceleration, EU member state transposition delays, and hyperscaler GPU allocation policy shifts. Forecasts reflect these documented assumptions and scenario weights. Material shifts in regulatory penalty structures or export-control restrictions on simulation hardware would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Global User Interface Service Market
Software & Services
Saas Based HRM Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Content Creation Software Market
Software & Services
Global Award Management Software Market
Software & Services
Europe Yacht Management Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global Automotive Software Market
Software & Services
Global Application Management Services Market
Software & Services
Global Embedded Database Management Systems Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market
Software & Services
Global Decision Support Software Market
Software & Services
Server Software Market
Software & Services
Software Containers Market