
 Game Development Software Market | 2026-2036
Game Development Software Market Size, Share, and Industry Trends Forecast 2026-2036
Game Development Software Market Analysis
Multi-source engine licensing is shifting as studios balance proprietary customization against subscription economics. Unity Technologies leverages its asset marketplace to sustain developer retention across mobile and indie segments. Epic Games anchors high-fidelity production through Unreal Engine's royalty model and twin motion integration. NVIDIA Corporation dominates real-time ray tracing hardware-software coupling, extending its CUDA ecosystem into game rendering pipelines.
Game development software comprises integrated toolchains for asset creation, physics simulation, scripting environments, and build deployment, typically requiring GPU acceleration and multi-threaded CPU architectures to achieve 60-120 frames per second rendering targets. Game engines command the largest installed base while cloud-based deployment models capture the fastest expansion as studios abandon on-premises server farms for elastic compute. Testing frameworks represent a concentrated margin pool where automated quality assurance reduces manual regression cycles for large studios shipping across console, PC, and mobile simultaneously.
China's SAMR enforces GB software standards and content classification protocols that shape engine localization requirements and distribution platform access. The EU AI Act and GDPR impose algorithmic transparency and data minimization obligations on analytics-integrated development suites deployed to European users. Stakeholders must monitor regulatory divergence between Washington's export control frameworks for GPU technology and Brussels' emerging digital product safety mandates.
Market Dynamics
Cloud-based engine deployment is compressing capital requirements for indie studios while tightening vendor lock-in dynamics across the production toolchain. Elastic compute access is rewriting studio formation economics and geographic distribution of development capacity.
Growth Catalysts
- Indie Studio Formation:Reduced server infrastructure costs through AWS and Azure GPU instances enable solo developers to prototype high-fidelity projects without on-premises hardware.
- China's GB Standards:Mandatory software compliance and content classification protocols force engine localization investments that deepen platform integration.
- Ray Tracing Hardware:NVIDIA's CUDA ecosystem penetration into consumer GPUs creates baseline capability expectations across mid-tier development.
Market Restraints
- GPU Export Controls:Washington's Commerce Department restrictions on advanced semiconductor shipments to China fragment hardware-software coupling strategies.
- Subscription Cost Accumulation:Per-seat licensing for engines, asset stores, and cloud build pipelines compound operational expenditure burdens for mid-size studios.
- Rendering Pipeline Complexity:Real-time ray tracing integration demands specialized shader programming expertise that concentrates talent at established firms.
Strategic Opportunities
- India's Developer Pool:Bangalore and Hyderabad technical institutes produce animation and scripting specialists available below US wage rates.
- EU AI Act Compliance Tools:Algorithmic transparency mandates for procedural content generation create demand for audit-integrated development suites.
- WebAssembly Distribution:Browser-based game deployment bypasses platform store fees and reduces build fragmentation across mobile and desktop.
Industry Challenges
- Technical Artist Scarcity:The intersection of shader programming and visual design skills remains underdeveloped in standard computer science curricula.
- Cross-Platform Certification:Console manufacturer compliance testing for PlayStation and Xbox certification adds 4-8 week ship delays.
- Asset Pipeline Integration:Legacy Maya and 3ds Max workflows resist seamless import into real-time engines without manual retopology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Game Development Software Market |
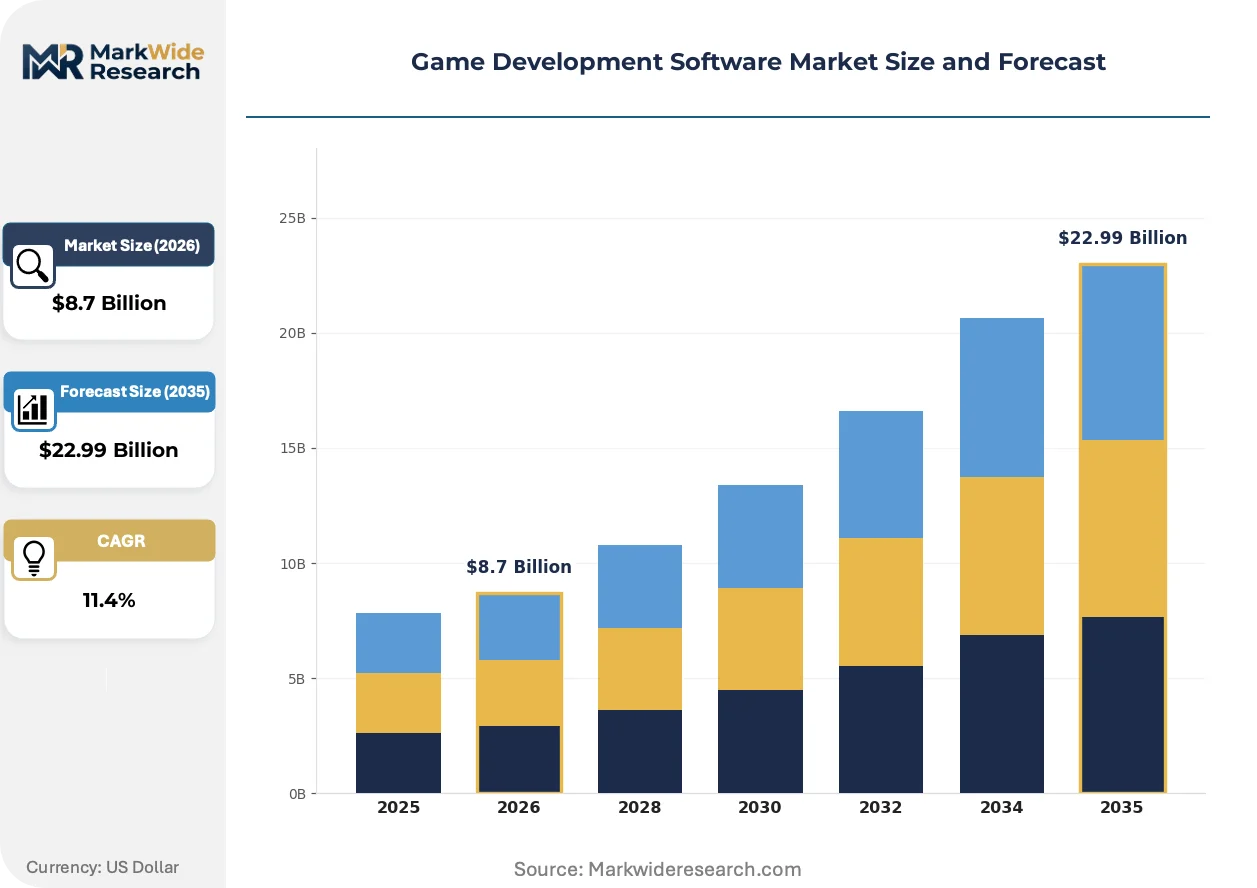
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Game Engines, Asset Management Tools, Collaboration Software, Testing Frameworks Deployment Model: On-Premises, Cloud-Based, Hybrid, Software as a Service End User: Indie Developers, Large Studios, Educational Institutions, Freelancers Feature: Cross-Platform Support, Real-Time Editing, Integrated Analytics, VR Support |
| Companies Covered | Unity Technologies, Epic Games, Autodesk, Adobe, Microsoft Corporation, Amazon, Crytek, NVIDIA Corporation, Cocos Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Game Development Software Market Emerging Trajectories
Neural network inference at the edge is compressing content production timelines while regulatory fragmentation around algorithmic systems forces architectural adaptation. These pressures are simultaneously accelerating automation and complicating deployment geography.
Generative adversarial networks trained on proprietary asset libraries are rewriting texture and environment generation workflows. Mid-tier studios in Poland and Brazil adopt these tools to compensate for smaller art departments. The technology is rewriting the labor composition of production teams, shifting headcount toward prompt engineering and away from manual modeling.
The EU AI Act's risk classification system for procedural content generation imposes documentation and human oversight mandates on European-deployed titles. Engine vendors must embed audit trails for algorithmic outputs. Studios targeting German and French distribution channels are restructuring their content pipelines to segregate EU-bound builds from other regions.
Revenue share negotiations between developers and platform holders are intensifying as Epic Games Store and Steam compete on commission rates. Mobile-first studios in Southeast Asia are diversifying toward PC distribution to escape app store fee structures. South Korean publishers lead this migration, establishing direct download infrastructure to capture margin from their established intellectual property.
Game Development Software Market Segmentation
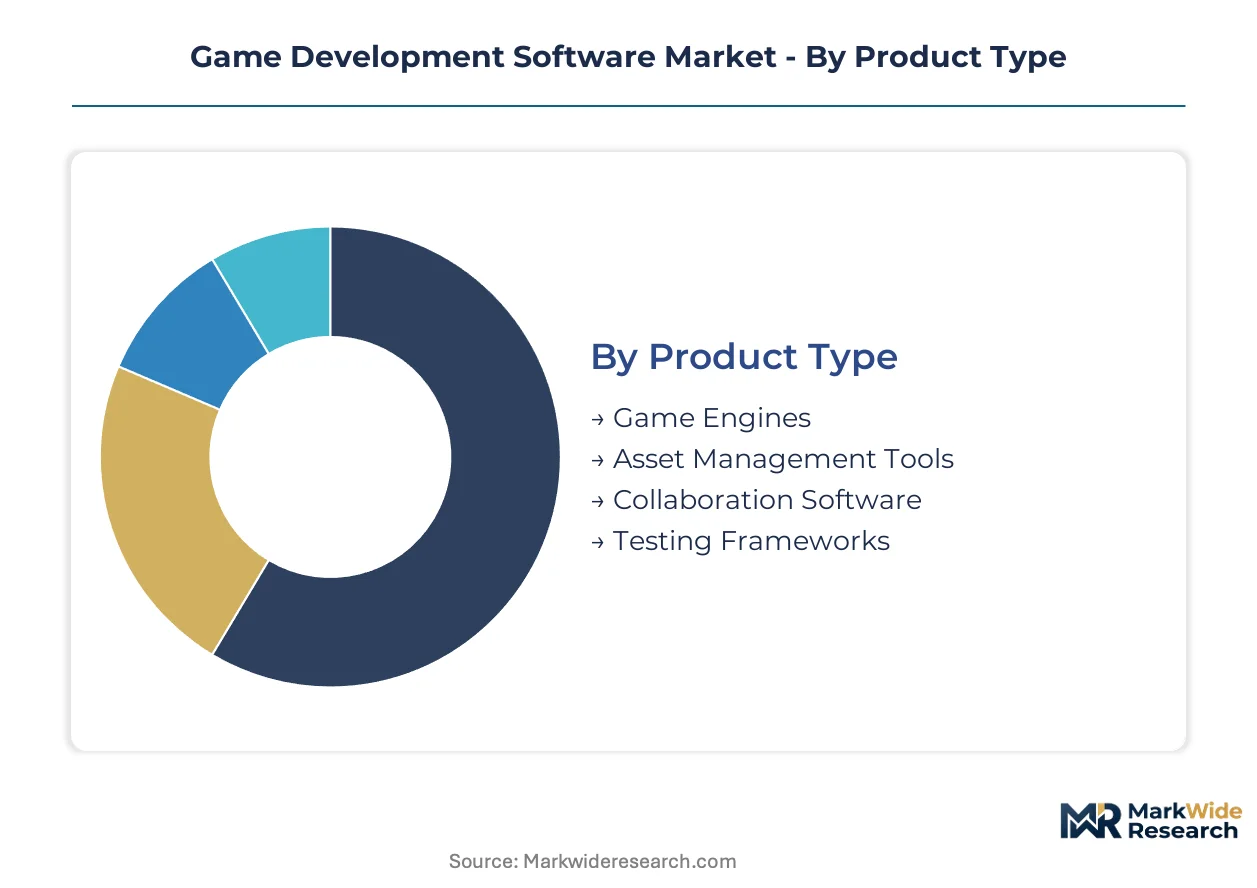
Game development software segmentation reveals how tooling requirements fragment across studio scale, technical ambition, and infrastructure constraints. Engine licensing models and deployment economics create distinct purchasing patterns that reshape vendor go-to-market strategies.
Product Type:
Standalone engines operate as discrete platforms requiring separate pipeline integration, while embedded toolchains merge into broader creative suites with unified asset flows.
- Game Engines:Core runtime environments providing physics, rendering, and scripting foundations. California and Washington state clusters anchor demand as AAA studios prioritize real-time ray tracing capabilities and source code access for proprietary modification.
- Asset Management Tools:Version control and metadata systems tracking 3D models, textures, and audio across distributed teams. Large studios shipping simultaneous console-PC-mobile builds concentrate procurement here to compress iteration cycles.
- Collaboration Software:Real-time co-editing and review platforms for remote production workflows.
- Testing Frameworks:Automated quality assurance suites reducing manual regression overhead.
Volume placements concentrate in Game Engines; the faster expansion belongs to Testing Frameworks.
Deployment Model:
Cost tier segmentation separates capital-intensive ownership from operational expenditure models, with hybrid architectures capturing studios transitioning legacy infrastructure.
- Cloud-Based:Elastic GPU compute accessed via subscription eliminating server farm capital expenditure. Indie studios in Poland and Brazil adopt these to prototype high-fidelity projects without hardware investment, though egress fees and vendor lock-in accumulate operational burdens.
- Software as a Service:Fully managed environments with automatic updates and shared infrastructure. Mid-tier studios in Southeast Asia favor this for predictable per-seat budgeting across fluctuating project pipelines.
- On-Premises:Self-hosted installations retaining full data sovereignty and customization control.
- Hybrid:Split architectures keeping sensitive assets local while leveraging cloud build farms.
Customer migrations favor Cloud-Based configurations; Hybrid deployments are climbing the fastest as security-conscious studios seek intermediate positions.
End User:
Application-based segmentation distinguishes commercial production from educational and individual use cases with diverging feature requirements and price sensitivity.
- Indie Developers:Solo creators and micro-studios prioritizing low-friction onboarding and asset marketplace ecosystems. China's tightening GB content standards and SAMR compliance obligations are forcing these users toward localized engine versions with built-in review pipelines.
- Large Studios:Multi-hundred-person operations requiring source code licensing and dedicated support tiers. These buyers anchor revenue concentration through enterprise agreements spanning multiple product categories.
- Educational Institutions:Universities and technical institutes training pipeline-ready talent.
- Freelancers:Contract specialists purchasing month-to-month access for project-specific engagements.
Revenue concentration sits with Large Studios; Indie Developers represent the steepest expansion trajectory as formation economics compress globally.
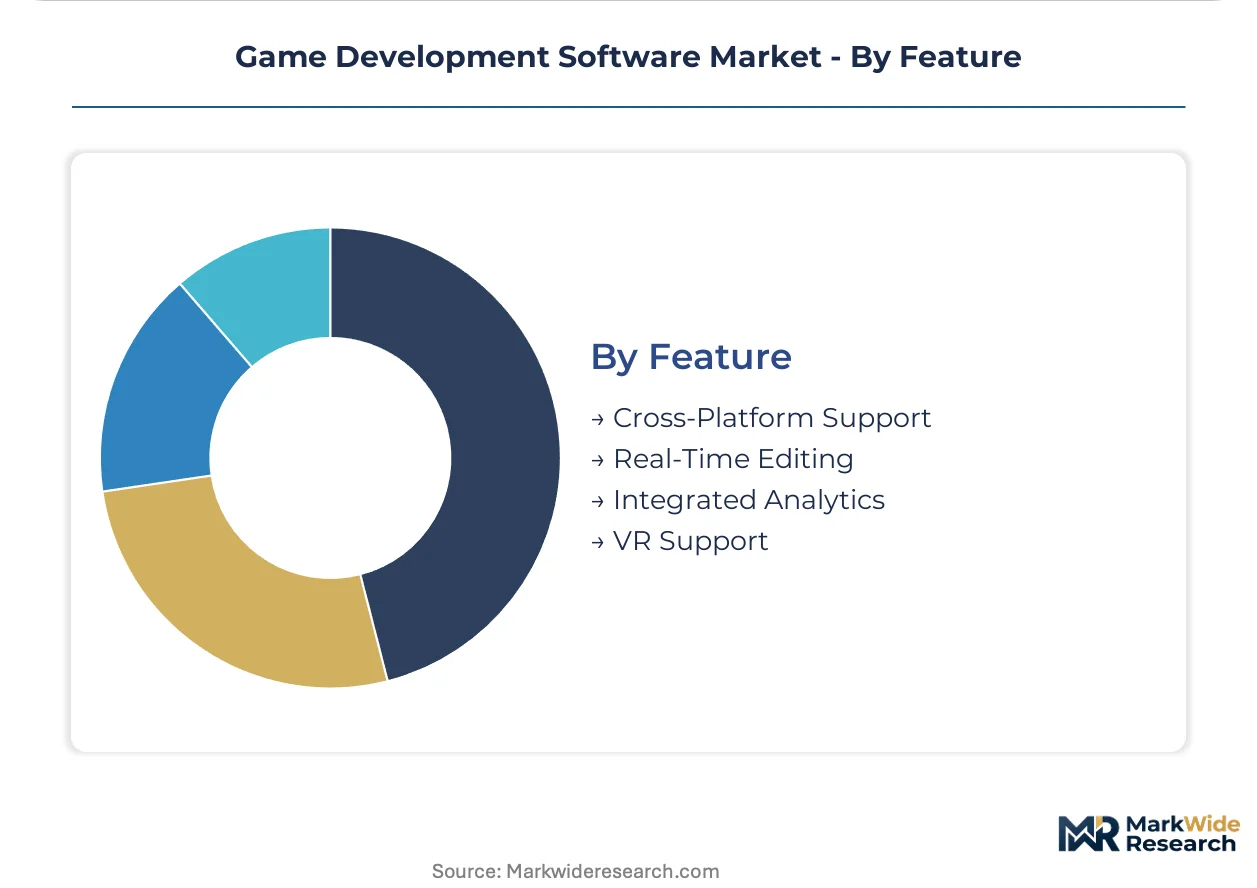
Feature:
Maturity-based segmentation separates baseline functionality from emerging capabilities reshaping competitive positioning and upgrade cycles.
- Cross-Platform Support:Unified build pipelines targeting console, PC, mobile, and web from single codebases. South Korean publishers migrating toward PC distribution prioritize this to escape mobile app store fee structures while maintaining existing intellectual property.
- Real-Time Editing:Instant preview environments eliminating compile-wait cycles. Technical artist scarcity in standard computer science curricula makes this capability essential for studios competing for shader programming talent.
- Integrated Analytics:Player behavior telemetry embedded during development for live service planning.
- VR Support:Stereoscopic rendering and motion controller integration for immersive hardware targets.
Procurement prioritizes Cross-Platform Support; VR Support is gaining share fastest as hardware install bases mature beyond early adopter phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU fabrication clusters in Taiwan and South Korea anchor hardware-software coupling for real-time rendering pipelines. These semiconductor localities determine baseline capability expectations across development studios worldwide.
United States
California and Washington state clusters dominate AAA production pipelines with concentration around San Francisco Bay Area and Seattle metro. Washington's Commerce Department export controls on advanced semiconductors reshape hardware-software strategies for China-facing operations. Austin and Los Angeles studios anchor mid-tier indie formation through accelerator networks.
China
SAMR enforcement of GB software standards and content classification protocols deepens engine localization investments. Beijing and Shanghai development hubs face tightening compliance obligations for distribution platform access. Shenzhen hardware integration specialists couple consumer GPU supply with middleware adaptation.
Germany
Cologne and Berlin clusters concentrate technical artist talent for shader programming specialization. The EU AI Act imposes algorithmic transparency mandates on procedural content generation deployed to German users. Hamburg publishers restructure pipelines to segregate EU-bound builds with embedded audit trails.
South Korea
Seoul Capital Area publishers lead migration from mobile toward PC distribution to escape app store fee structures. Busan-Ulsan technical institutes supply animation specialists below US wage rates. Daegu-Gyeongbuk studios establish direct download infrastructure for intellectual property margin capture.
Poland
Warsaw and Krakow mid-tier studios adopt generative adversarial networks to compensate for smaller art departments. EU AI Act compliance requirements force architectural adaptation for algorithmic content pipelines. Wrocław technical universities expand prompt engineering curricula to meet shifting labor composition demands.
Game Development Software Market Vendor Landscape
Technology licensing dominates the current landscape as engine vendors compete through royalty models and source code access tiers. The vendor base concentrates around three strategic archetypes: integrated platform operators with asset marketplace ecosystems, hardware-coupled specialists leveraging GPU architecture control, and open-source challengers disrupting subscription economics. M&A activity targets middleware specialists for pipeline integration, while geographic expansion captures emerging developer pools in Eastern Europe and Southeast Asia.
Among North American platform operators, Unity Technologies and Epic Games exemplify divergent monetization archetypes—subscription-marketplace hybrid against royalty-based high-fidelity production. Autodesk occupies a position within creative suite incumbents resisting seamless real-time engine integration. NVIDIA Corporation anchors hardware-software coupling through CUDA ecosystem penetration into consumer rendering pipelines. These three represent the dominant competitive vectors shaping procurement patterns across studio scale segments.
| Leading Market Players |
|---|
| Unity Technologies |
| Epic Games |
| Autodesk |
| Adobe |
| Microsoft Corporation |
| Amazon |
| Crytek |
| NVIDIA Corporation |
| Cocos Technology |
| Others |
Supply Flow & Price Mechanics
Technical artist scarcity in Poland and Brazil compresses labor-cost differentials into pricing-tier spreads across engine licensing models, with studios in lower-wage markets accessing cloud-based tiers while California clusters absorb premium source-code licensing premiums.
Pricing Analysis
Service-bundling separates dedicated support tiers from self-service subscriptions, with enterprise agreements wrapping source-code access and compliance consulting into annual contracts. Pricing stratifies across premium, standard, and economy tiers based on rendering pipeline complexity and GB standards certification requirements. Cost compression in indie-facing SaaS tiers intensifies as AWS and Azure GPU instances commoditize elastic compute access. Large studios with multi-project pipelines exhibit lowest price sensitivity; solo developers and educational institutions drive volume at entry price points.
Supply Chain Analysis
Shader programming specialists concentrate in Cologne, Bangalore, and Seoul, constraining talent availability for real-time engine customization and ray-tracing pipeline development. GPU hardware fabrication anchors in Taiwan and South Korea, with CUDA ecosystem dependencies tethering software optimization to NVIDIA's consumer card release cycles. Single-source vulnerability runs through TSMC's advanced node capacity for AI-accelerated content generation chips. Distribution runs through direct engine vendor portals and hyperscaler marketplaces, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around engine vendors controlling asset marketplace ecosystems, with subscription cost accumulation and GPU export control fragmentation forcing weaker middleware specialists toward acquisition or exit.
For Market Incumbents: Deploy source-code access tiers as retention levers against open-source challengers. Acquire automated testing framework specialists to compress certification timelines for PlayStation and Xbox compliance. Deepen integration with NVIDIA's CUDA roadmap to lock in ray-tracing performance advantages as hardware-software coupling tightens.
For New Entrants and Emerging Players: Enter via WebAssembly distribution channels bypassing platform store fee structures. Target India's Bangalore and Hyderabad technical institutes for animation and scripting outsourcing partnerships. Build go-to-market around EU AI Act compliance tooling for procedural content audit trails.
For Investors and Strategic Acquirers: Re-rating potential sits with middleware specialists owning cross-platform build pipeline IP given South Korean publisher migration toward PC distribution. Long-term viability favors firms with captive GPU optimization expertise or regulatory compliance automation. Watch NVIDIA's consumer GPU release cadence as inflection indicator for real-time rendering capability baselines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies asset flows between Maya workflows and real-time engines, reducing manual retopology overhead for large studios. |
| Acquisition of Specialist Firm | Captures automated testing frameworks that compress PlayStation and Xbox certification timelines by 4-8 weeks. |
| Geographic Expansion | Establishes presence in Poland and Brazil to access generative adversarial network adoption among mid-tier studios. |
| Strategic Partnership | Couples engine licensing with AWS and Azure GPU instances to capture indie studio formation economics. |
| Product Launch | Introduces EU AI Act-compliant audit trails for procedural content generation targeting German and French distribution. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and engine vendor partnership announcements formed the secondary backbone, cross-referenced against primary interviews with game engine CTOs, technical art directors, platform certification leads, and indie studio founders. Bottom-up project pipeline tracking across California, Washington state, and South Korea clusters combined with top-down vendor revenue segmentation to establish baseline market sizing.
Historical trendline analysis across engine licensing transitions—from perpetual to subscription to royalty models—informed projection frameworks over the analysis window. Segmentation dimensions modeled include deployment model elasticity, studio scale tier, rendering pipeline complexity, and regional regulatory cluster density. CAGRs derived from elasticity-adjusted adoption curves incorporating GPU hardware refresh cycles and SAMR compliance obligation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Washington Commerce Department GPU export control expansion or EU AI Act enforcement escalation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Social Collaboration Software Market
Software & Services
Construction Enterprise Resource Planning (ERP) Software Market
Software & Services
Yacht Management Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Global Auction Software Market
Software & Services
Europe Printing Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Binary Drivers Market
Software & Services
Parametric Design Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Metal Fabrication Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Global Screen Mirroring Apps Market