
 Global Telco Data Monetization Market | 2026-2036
Global Telco Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telco Data Monetization Market Foresight
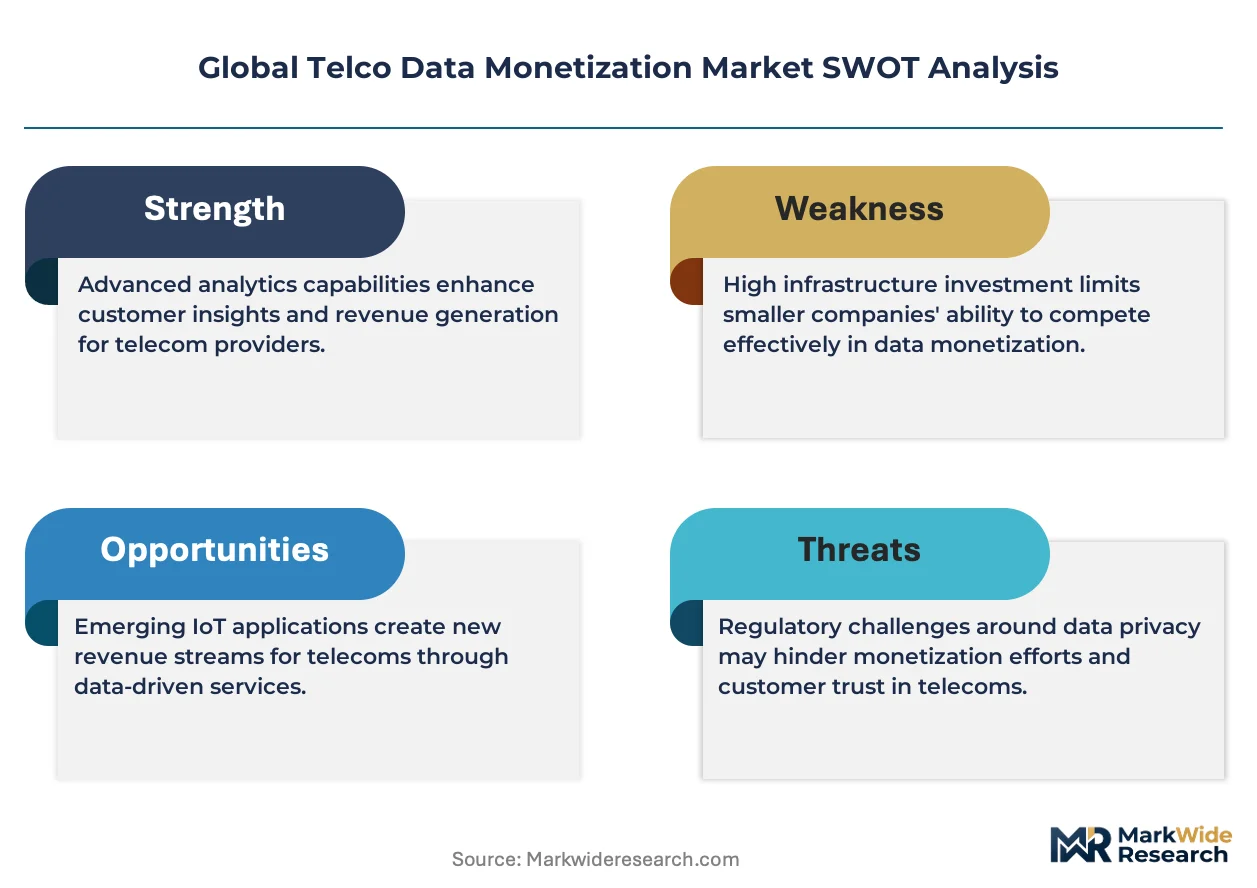
Platform licensing revenue from network analytics APIs is reconfiguring margin pools away from traditional connectivity tariffs. Nokia Corporation leverages its deep telecom infrastructure footprint to anchor data monetization toolkits inside carrier core networks. Oracle Corporation competes through cloud-native analytics architectures that extend telco data pipelines into enterprise data warehouses. Huawei Technologies dominates in emerging markets where its end-to-end equipment stack controls both data generation and monetization layers.
Telco data monetization encompasses the systematic extraction, aggregation, and commercialization of subscriber behavioral, location, and network performance data through software platforms and API services, typically processed via real-time stream analytics with sub-second latency requirements for use cases like geofenced advertising and dynamic network slicing. Its primary commercial purpose is converting passive network operations into recurring software revenue streams for communication service providers. Analytics platforms and data-as-a-service offerings lead current revenue composition, while edge computing deployments represent the fastest-growing structural segment as carriers push inference closer to radio access networks to reduce backhaul costs and meet latency-sensitive enterprise SLAs. Customer insights solutions occupy the deepest margin pools where telcos combine first-party data with external datasets for financial services and digital advertisers.
The Federal Communications Commission in the United States and the European Union's GDPR framework collectively shape market access by mandating granular subscriber consent and data minimization protocols before any commercial data transfer. China's Ministry of Industry and Information Technology enforces domestic data localization requirements that restrict cross-border telco data flows and privilege national platform vendors. Stakeholders must monitor evolving national AI regulations that will determine whether telco datasets qualify as critical infrastructure inputs subject to enhanced scrutiny.
Market Dynamics
API-first data marketplaces are compressing time-to-revenue for carriers while fragmenting buyer relationships away from long-term enterprise contracts toward pay-per-query consumption models.
Growth Catalysts
- GDPR-compliant consent management platforms:European carriers deploy granular opt-in frameworks that unlock subscriber behavioral datasets for financial services credit scoring without regulatory penalty.
- Edge computing infrastructure:Radio access network deployments enable sub-50 millisecond inference for geofenced retail advertising, attracting enterprise buyers from brick-and-mortar chains.
- India:TRAI's data governance guidelines create standardized frameworks for telco-analytics commercialization, accelerating bank partnerships for rural credit assessment.
Market Restraints
- Cross-border data localization mandates:China's MIIT restricts subscriber data flows outside domestic cloud infrastructure, fragmenting platform architectures for multinational carriers.
- Subscriber churn volatility:Prepaid-dominant emerging markets degrade dataset continuity, undermining longitudinal behavioral models for insurance underwriting.
- API commoditization:Standardized network analytics interfaces erode pricing power as hyperscale cloud providers bundle telco data pipes into broader enterprise data lake offerings.
Strategic Opportunities
- Brazil:ANVISA's health data interoperability mandates create openings for telco mobility patterns to augment pharmaceutical supply chain optimization.
- 5G network slicing plus AI inference:Converged architectures enable real-time quality-of-service guarantees for autonomous vehicle fleet operators seeking guaranteed latency tiers.
- Embedded finance distribution:Mobile wallet integrations transform carrier apps into primary channels for micro-lending origination, bypassing traditional bank branch networks.
Industry Challenges
- Real-time stream processing talent scarcity:Carriers compete with fintechs for Apache Kafka and Flink engineers capable of sub-second pipeline engineering.
- Legacy billing system integration:Decades-old BSS/OSS stacks require expensive middleware layers to expose usage events as monetizable data products.
- Cross-jurisdictional consent reconciliation:Multi-national carriers face conflicting opt-in requirements between GDPR's explicit consent and sectoral frameworks in Gulf Cooperation Council markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telco Data Monetization Market |
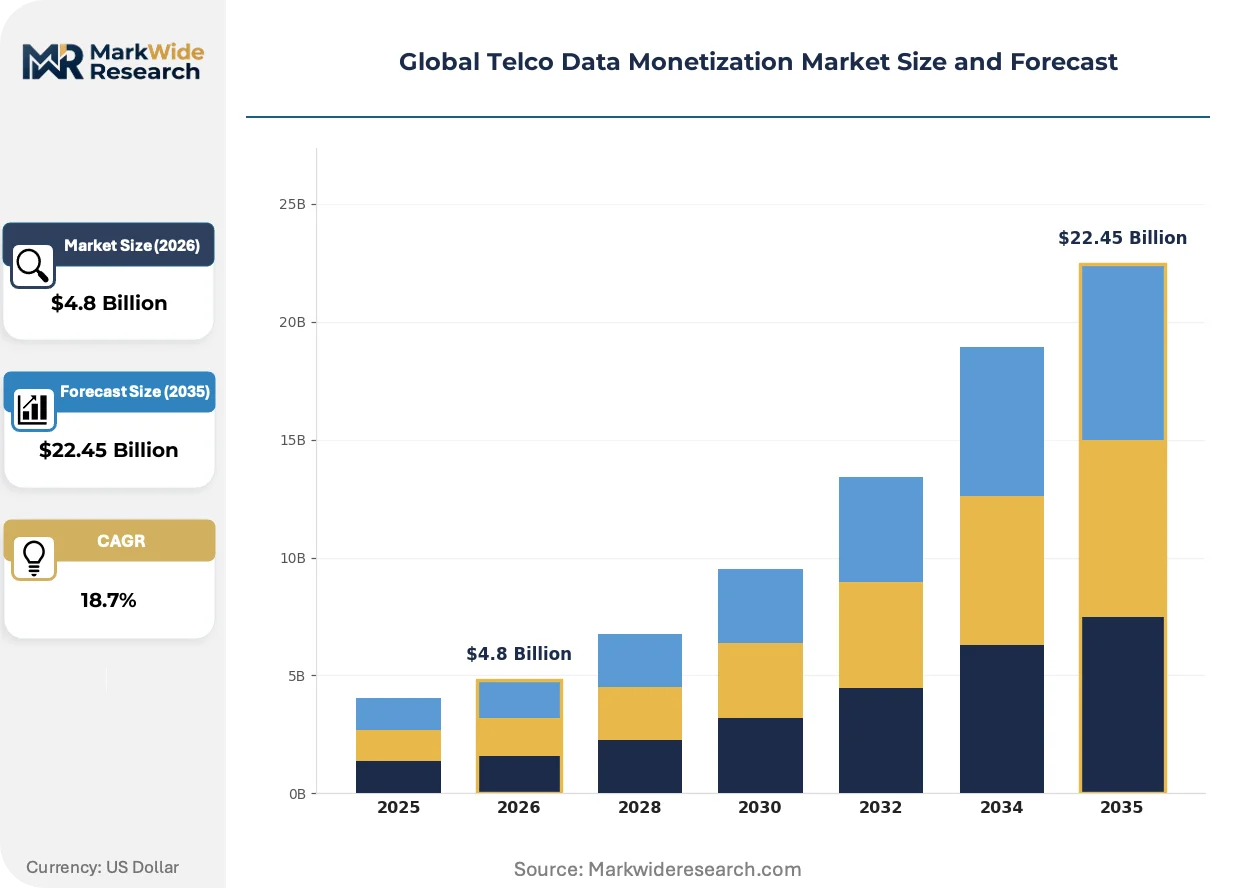
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Analytics Platforms, Data-as-a-Service, Revenue Assurance, Fraud Management, Customer Insights Use Case: Churn Prediction, Network Optimization, Targeted Advertising, Subscription Management, Risk Assessment Deployment Model: Cloud-based, On-Premises, Hybrid, Edge Computing End User Segment: Mobile Network Operators, Internet Service Providers, Content Providers, Digital Advertisers, Financial Institutions |
| Companies Covered | Nokia Corporation, SAS Institute, AT&T, Amdocs Limited, Huawei Technologies, Verizon Communications, Telefonaktiebolaget LM Ericsson, Oracle Corporation, Vodafone Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telco Data Monetization Market Shifts & Advancements
Federated learning architectures are redrawing competitive boundaries by enabling model training across carrier silos without raw data centralization, fundamentally altering who captures value in the analytics stack.
Edge-native stream processing is collapsing the latency gap between radio access network data generation and actionable enterprise intelligence. Automotive fleet managers in Germany now ingest anonymized mobility patterns directly from roadside multi-access edge computing nodes, eliminating round-trip delays to centralized cloud regions. This compression is forcing traditional data warehouse vendors to reposition around hybrid architectures that federate inference rather than aggregate storage.
The EU AI Act's risk-tiered compliance framework is restructuring how carriers classify and price subscriber-derived inference outputs. High-risk applications including credit scoring and biometric identification now require documented algorithmic impact assessments before commercial deployment, extending sales cycles but creating compliance-service revenue streams for specialized consultancies. French and German carriers have established dedicated algorithmic accountability offices to pre-certify data products for financial services buyers.
Enterprise procurement of telco-derived intelligence is fragmenting from annual platform licenses toward consumption-based API metering with granular event-level billing. Retail chains in the United States now optimize campaign spend against foot-traffic correlation scores purchased per thousand queries rather than subscribing to bundled analytics suites. This unbundling is compressing contract values for carriers while expanding addressable buyer pools to mid-market advertisers previously priced out of enterprise data contracts.
Global Telco Data Monetization Market Segmentation
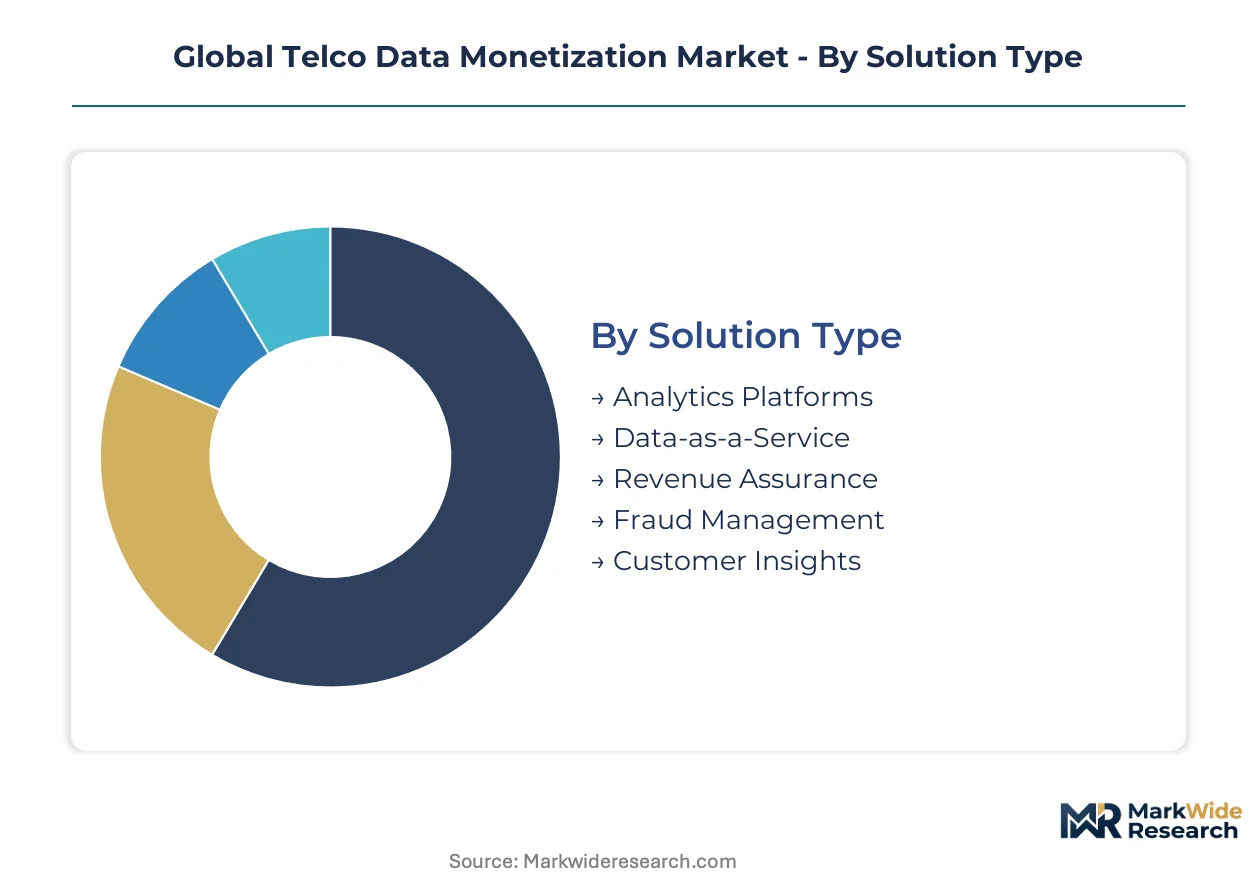
Segmentation in telco data monetization reveals how carriers package network intelligence into commercially distinct offerings. Each dimension—solution architecture, application purpose, infrastructure placement, and buyer category—carries divergent margin profiles and technical requirements that reshape competitive positioning across the value chain.
Solution Type:
Cost tier stratification separates packaged software platforms from raw data feeds and specialized assurance tools, with premium pricing attaching to integrated analytics suites.
- Analytics Platforms:Unified software stacks ingest subscriber behavioral streams, network performance metrics, and location signals through pre-built visualization layers. Financial institutions in the United States concentrate procurement here for credit scoring models built on granular mobility patterns. GDPR-mandated consent management modules now embed directly into platform architectures.
- Data-as-a-Service:API-delivered raw or lightly processed datasets expose anonymized subscriber segments, foot-traffic indices, and network quality benchmarks without long-term platform commitments. Digital advertisers in Germany access these feeds through per-query metering to fuel geofenced campaign optimization.
- Revenue Assurance:Systems audit usage records against billing events to capture leakage from prepaid voucher fraud or interconnect settlement errors.
- Fraud Management:Real-time scoring engines flag SIM cloning, international revenue share fraud, and synthetic identity patterns.
- Customer Insights:Carriers combine first-party data with external psychographic datasets to build propensity models for cross-sell targeting.
Analytics Platforms command the established base. The steepest expansion runs through Data-as-a-Service.
Use Case:
Application maturity varies sharply across operational efficiency, revenue protection, and external monetization objectives.
- Churn Prediction:Machine learning models score subscriber defection probability from usage pattern decay, customer service interaction sentiment, and competitive network roaming events. Mobile network operators in India deploy these systems to protect prepaid ARPU in hypercompetitive circles.
- Targeted Advertising:Audience segments built from app usage fingerprints, location dwell times, and content consumption preferences feed demand-side platforms. Brick-and-mortar retail chains in Brazil purchase mobility correlation scores to optimize store placement and promotional timing.
- Network Optimization:Predictive models anticipate congestion events and guide dynamic spectrum allocation.
- Subscription Management:Usage-based pricing engines flex data allowances against real-time consumption patterns.
- Risk Assessment:Alternative credit scoring models infer repayment capacity from airtime purchase regularity and social network connectivity density.
Churn Prediction retains the deepest carrier investment. Targeted Advertising climbs the fastest as privacy-compliant identity graphs mature.
Deployment Model:
Infrastructure placement decisions trade latency sensitivity against capital intensity and data sovereignty constraints.
- Edge Computing:Stream processing nodes collocated with radio access networks enable sub-50 millisecond inference for autonomous vehicle fleet operators and augmented reality retail applications. Germany's roadside multi-access edge deployments now host anonymized mobility analytics without cloud round-trips.
- Cloud-based:Hyperscale elastic capacity supports batch model training and non-latency-sensitive business intelligence workloads. Content providers in the United States prefer this model for subscriber engagement analytics with variable query volumes.
- On-Premises:Carrier-owned data centers retain sensitive subscriber records under direct physical control.
- Hybrid:Tiered architectures keep PII in private infrastructure while pushing anonymized aggregates to public cloud for cost efficiency.
Cloud-based deployments hold the current volume base. Edge Computing captures the steepest trajectory as 5G standalone cores proliferate.
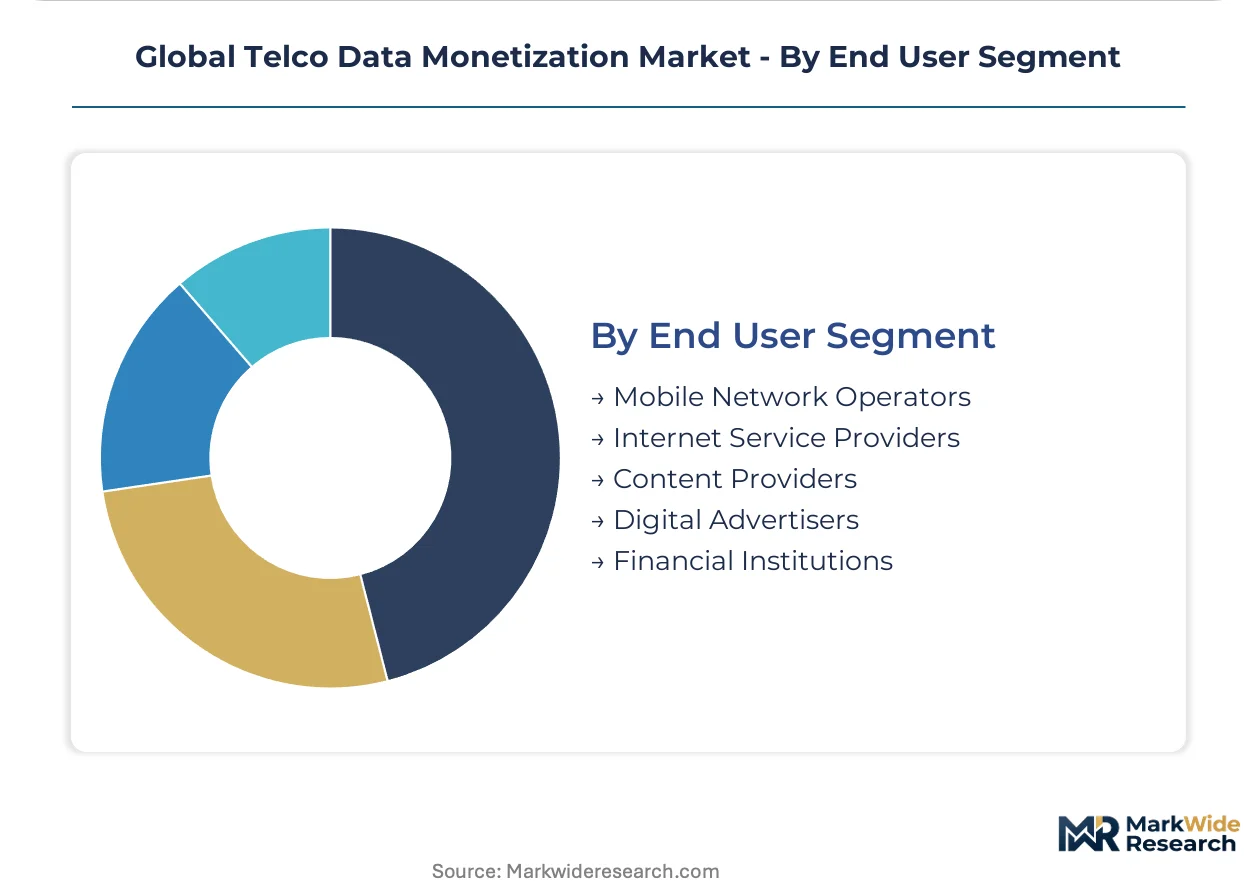
End User Segment:
Customer type determines pricing power, with financial services buyers commanding premium data quality tiers and stringent compliance documentation.
- Financial Institutions:Banks, insurers, and fintechs purchase credit scoring signals, fraud detection features, and identity verification attributes derived from subscriber payment behavior and device authentication patterns. India's rural lending partnerships with carriers exemplify this segment's expansion.
- Digital Advertisers:Agencies and demand-side platforms acquire audience segments, foot-traffic attribution, and campaign effectiveness measurement. United States retail chains now optimize media spend against telco-derived store visit correlation scores.
- Mobile Network Operators:Peer carriers exchange roaming analytics and network quality benchmarks.
- Internet Service Providers:Fixed-line operators purchase mobile mobility patterns to inform fiber buildout prioritization.
- Content Providers:Streaming services and gaming platforms buy quality-of-experience data to optimize CDN placement.
Mobile Network Operators anchor the incumbent revenue pool. Financial Institutions drive the sharpest growth as alternative credit data gains regulatory acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carrier infrastructure investments cluster in markets with dense 5G deployments and permissive data governance frameworks. The United States and China dominate platform revenue through divergent regulatory models. European carriers navigate stricter consent requirements while building cross-border data exchanges.
United States
Verizon and AT&T monetize granular location streams for retail foot-traffic analytics and financial fraud detection. The FCC mandates opt-in consent for subscriber data commercialization under evolving privacy enforcement. Dallas and Seattle host the densest concentrations of carrier data science operations, with AWS and Azure co-location driving edge inference deployments for real-time advertising use cases.
Germany
Deutsche Telekom federates subscriber behavioral models across EU carriers without raw data centralization under GDPR constraints. The EU AI Act imposes algorithmic impact assessments for credit-scoring applications, extending carrier sales cycles. Munich and Berlin anchor automotive-telco partnerships where roadside multi-access edge nodes deliver sub-50 millisecond mobility analytics to vehicle fleet operators.
China
MIIT's data localization mandates restrict cross-border flows while privileging domestic equipment vendors across network and analytics layers. The MIIT enforces subscriber data residency requirements that fragment multinational carrier architectures. Shenzhen and Beijing concentrate Huawei's end-to-stack deployments where equipment control extends through data generation to monetization platforms.
India
Reliance Jio and Bharti Airtel partner with rural banks for alternative credit scoring based on airtime purchase regularity and device authentication patterns. TRAI's data governance guidelines standardize telco-analytics commercialization frameworks. Mumbai and Bangalore cluster fintech-engineering talent where carriers compete with payment platforms for Apache Kafka pipeline specialists.
Brazil
Vivo and Claro leverage mobility patterns for pharmaceutical supply chain optimization under ANVISA health data interoperability mandates. ANVISA's sector-specific frameworks create openings for telco-derived intelligence in logistics planning. São Paulo anchors Latin America's deepest carrier data science hiring pools, with Portuguese-speaking engineers commanding premium compensation for real-time stream processing roles.
Global Telco Data Monetization Market Competitive Landscape
Infrastructure vendors and cloud-native analytics providers split the market between embedded network intelligence and enterprise data warehouse extension. The vendor base concentrates around three strategic archetypes: equipment manufacturers with core network anchoring positions, hyperscale cloud platforms with elastic compute capacity, and carrier-owned captive analytics units. Dominant competitive moves include API-first marketplace launches that compress time-to-revenue and federated learning alliances that enable cross-carrier model training without data centralization.
Among equipment-anchored vendors, Nokia Corporation and Huawei Technologies exemplify divergent geographic positioning strategies. Nokia leverages its European infrastructure footprint to embed monetization toolkits inside carrier core networks. Huawei dominates emerging markets where end-to-end equipment control spans data generation through commercialization layers. Oracle Corporation occupies the cloud-native tier, extending telco data pipelines into enterprise data warehouses through subscription analytics architectures. These three anchors illustrate how competitive positioning fragments across regulatory boundaries and infrastructure ownership models.
| Leading Market Players |
|---|
| Nokia Corporation |
| SAS Institute |
| AT&T |
| Amdocs Limited |
| Huawei Technologies |
| Verizon Communications |
| Telefonaktiebolaget LM Ericsson |
| Oracle Corporation |
| Vodafone Group |
| Others |
Supply & Pricing Matrix
Undercapacity in edge computing infrastructure across Germany and India is forcing carriers to prioritize capital deployment toward radio access network collocations, compressing near-term pricing flexibility for latency-sensitive API tiers while elevating premiums for guaranteed sub-50 millisecond service levels.
Pricing Analysis
GDPR dictates the pricing tier structure across European carrier data products, with explicit consent requirements separating premium audited datasets from standard anonymized feeds. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: financial institutions purchase premium tiers with algorithmic impact documentation, while mid-market advertisers access standard API metering. Cost compression in economy tiers is intensifying because hyperscale cloud providers bundle telco data pipes into broader enterprise lake offerings. Digital advertisers in Brazil exhibit highest price sensitivity; financial institutions in the United States demonstrate lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for telco data monetization hardware, with MIIT localization mandates fragmenting multinational carrier architectures. Equipment concentration centers on Finland, Sweden, and China for core network analytics infrastructure. Raw material dependencies span semiconductor foundry capacity, specialized optical components, and edge server chassis. Distribution runs through carrier-direct licensing with hyperscale cloud marketplace intermediation expanding for mid-market API access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telco data monetization is crossing a platform-economics inflection where API-first marketplaces and federated learning alliances are redefining value capture, with interoperability between carrier silos becoming the decisive competitive moat.
For Market Incumbents: Pre-empt API commoditization by embedding consent management modules directly into platform architectures before GDPR-equivalent frameworks proliferate in Gulf Cooperation Council markets. Anchor edge computing deployments in automotive corridor partnerships to secure sub-50 millisecond latency tiers that hyperscale clouds cannot replicate. Prioritize algorithmic accountability office investments to pre-certify credit scoring products for financial services buyers. For New Entrants and Emerging Players: Rural India presents the most penetrable geography for alternative credit scoring partnerships with carriers underserved by incumbent analytics vendors. Target embedded finance distribution through mobile wallet integrations that bypass traditional bank branch networks. Lead with Apache Kafka pipeline engineering capabilities to differentiate against legacy BSS/OSS integration bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among carriers with captive edge infrastructure and direct enterprise API relationships rather than platform-licensing intermediaries. Long-term viability favors vendors controlling both data generation and monetization layers in markets with data localization mandates. Monitor TRAI-style governance guideline adoptions as the signal for regulatory framework maturation that accelerates bank-carrier partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Alliance Formation | Enables cross-carrier model training without raw data centralization under GDPR constraints. |
| Edge Computing Infrastructure Deployment | Collocates inference nodes with radio access networks to meet autonomous vehicle fleet SLAs. |
| API-First Marketplace Launch | Compresses time-to-revenue while fragmenting buyer relationships toward pay-per-query models. |
| GDPR-Compliant Consent Platform Integration | Embeds granular opt-in frameworks that unlock subscriber datasets for financial services. |
| Algorithmic Accountability Office Establishment | Pre-certifies data products for EU AI Act high-risk application requirements. |
Research Methodology
Desk research of carrier financial disclosures, regulatory filings with the FCC and MIIT, and API marketplace documentation preceded structured interviews with carrier data science executives, fintech partnership leads, and enterprise procurement officers at financial institutions. Primary fieldwork combined with secondary validation against TRAI guideline releases and EU AI Act implementation timelines. Bottom-up carrier revenue segmentation triangulated against top-down platform vendor licensing disclosures.
Forecasts held fixed the prevailing regulatory consent frameworks and 5G standalone core deployment trajectories while varying edge computing penetration rates and federated learning adoption curves across the projection horizon. Segmentation dimensions modeled include solution architecture, deployment model, use case maturity, and buyer industry vertical. CAGRs derived from carrier-reported data services revenue growth and platform vendor booking trends, with cross-referencing to hyperscale cloud telco partnership announcements.
Practitioners should monitor GDPR-equivalent framework adoptions in Asia-Pacific markets and MIIT enforcement intensity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Social Intelligence Market
Analytics
Condition Monitoring Service Market
Analytics
HR Analytics Market
Analytics
Online Analytical Processing Market
Analytics
Europe Operational Intelligence Market
Analytics
UAE Geospatial Analytics Market
Analytics
APAC Retail Analytics Market
Analytics
Italy ICT Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Dark Analytics Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
App Analytics Tools Market
Analytics
Marketing Analytics Software Market
Analytics
Manufacturing Predictive Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Global Network Analytics Market