
 Social Business Intelligence Market | 2026-2036
Social Business Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Social Business Intelligence Market Outlook
GDPR enforcement is expanding the cost-of-entry calculus for vendors processing European social data. Microsoft Corporation leverages its Azure cloud infrastructure to sustain compliance-ready deployments across multiple jurisdictions. Oracle Corporation anchors its competitive position through deep integration with enterprise data warehouses. Salesforce, Inc. differentiates via native connectivity to its CRM ecosystem, reducing implementation friction for marketing agencies.
Social Business Intelligence denotes the practice of aggregating, processing, and analyzing unstructured social media data to generate actionable business insights, typically employing natural language processing engines capable of parsing multilingual sentiment at scale. Its primary commercial purpose centers on enabling real-time competitive monitoring and customer behavior prediction for revenue protection. Cloud-based deployment models dominate current adoption due to elastic compute requirements during viral event spikes, while on-premises installations retain footholds among banking and defense sectors with strict data sovereignty mandates. Customer Insights solutions command premium pricing relative to basic social listening tools, as they tie sentiment signals directly to lifetime value calculations and churn risk scoring.
The EU AI Act, GDPR, and ISO 27001 collectively shape product architecture decisions, with the EU AI Act imposing risk-classification requirements on automated sentiment systems that influence credit or employment outcomes. FDA oversight applies where social BI tools process patient-reported outcomes for pharmaceutical marketing, creating dual-track compliance for healthcare-focused vendors. Stakeholders must weigh the trade-off between cloud scalability and jurisdictional data residency as regulatory fragmentation deepens across the United States, European Union, and China.
Market Dynamics
Regulatory fragmentation across the United States, European Union, and China is forcing vendors to architect multi-jurisdictional compliance layers into core product stacks, elevating engineering costs while compressing time-to-market for new sentiment analysis features.
Growth Catalysts
- EU AI Act risk classification:Mandatory algorithmic impact assessments for high-risk sentiment systems create recurring revenue streams for compliance audit modules.
- Real-time brand monitoring:Financial services institutions deploy social BI for instantaneous reputation threat detection during viral crisis events.
- Elastic cloud infrastructure:Viral event spikes drive compute demand that only hyperscale architectures can satisfy profitably.
Market Restraints
- GDPR data residency costs:European processing mandates require redundant infrastructure investments that inflate vendor operating expenses.
- Multilingual NLP complexity:Low-resource language sentiment parsing demands specialized training data that remains scarce.
- API rate limiting:Platform providers impose throttling that constrains real-time data ingestion velocity for enterprise clients.
Strategic Opportunities
- Patient-reported outcomes:FDA-regulated pharmaceutical marketing creates dual-track compliance products with premium pricing power.
- ISO 27001 certification:Security-conscious banking procurement mandates open doors for audited on-premises deployments.
- Edge computing convergence:On-device sentiment processing reduces latency for defense sector classified environments.
Industry Challenges
- Computational linguist scarcity:Specialized talent for low-resource language model development commands compensation premiums that compress margins.
- Legacy CRM integration:Custom middleware requirements for enterprise data warehouse connectivity extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Business Intelligence Market |
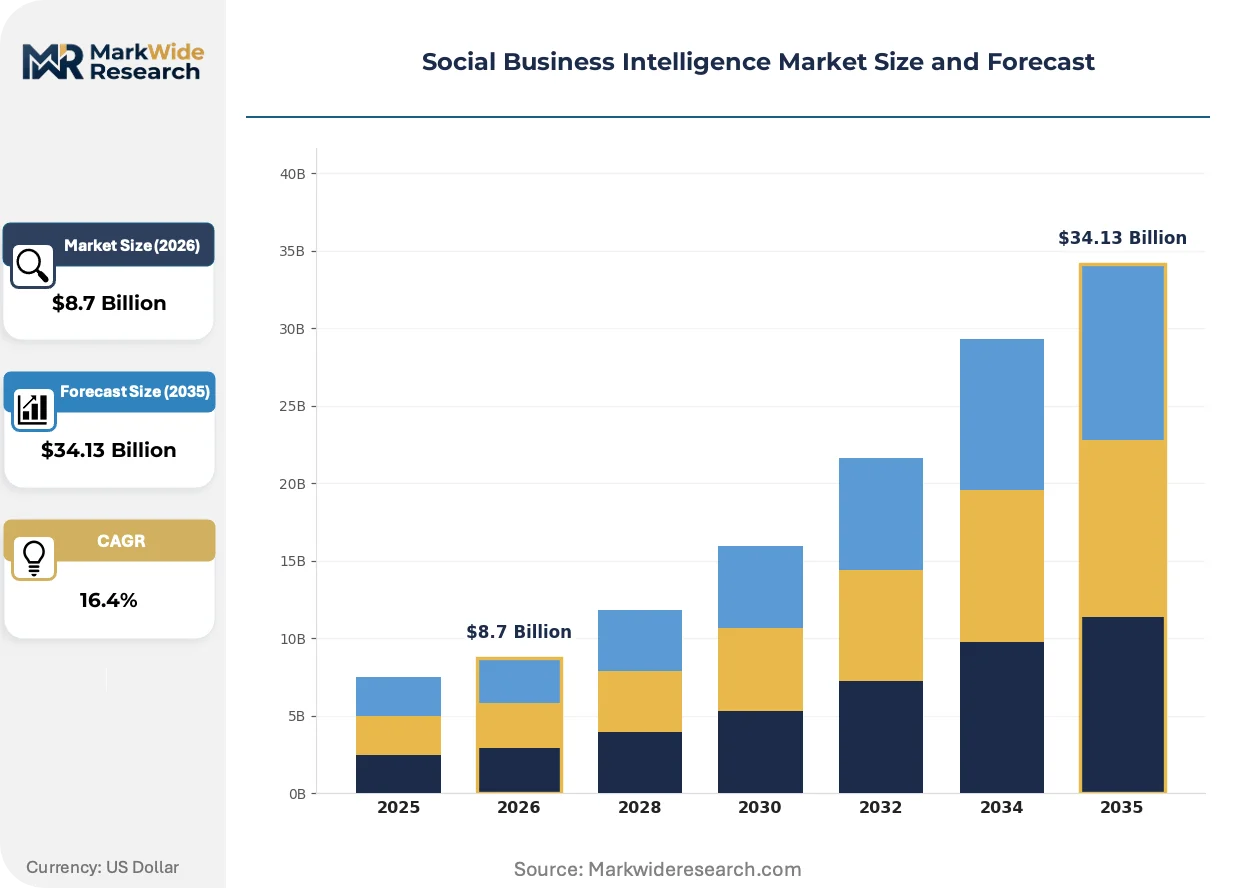
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Data Analytics, Customer Insights, Competitive Intelligence, Social Listening Deployment Model: Cloud-based, On-premises, Hybrid, SaaS End User: Enterprises, Startups, Marketing Agencies, Non-profits Feature Set: Sentiment Analysis, Trend Detection, Engagement Metrics, Reporting Tools |
| Companies Covered | IBM Corporation, SAP SE, Microsoft Corporation, Oracle Corporation, Salesforce, Inc., SAS Institute Inc., Sprinklr, Inc., Adobe, Inc., Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Business Intelligence Market Strategic Shifts
Natural language processing architectures are fragmenting into composable microservices that permit rapid reconfiguration for jurisdiction-specific compliance requirements without full platform rebuilds.
Transformer-based sentiment engines is modularizing into discrete components for entity extraction, emotion classification, and intent detection. Marketing agencies adopt these building blocks à la carte to assemble custom listening stacks. This decomposition is compressing vendor lock-in by enabling mix-and-match procurement across competing providers.
The EU AI Act's risk-tier framework imposes documentation burdens on automated sentiment systems influencing credit decisions. Vendors must maintain algorithmic audit trails that satisfy notified body scrutiny. High-risk classification is pushing financial services adopters toward explainable model architectures that sacrifice accuracy for interpretability.
Enterprise procurement committees now mandate proof-of-concept trials before multi-year commitments, replacing traditional pilot-to-production waterfalls. Marketing agencies run parallel vendor evaluations against identical crisis scenarios. This compression is most visible in the United States, where procurement cycle lengths have halved since 2023.
Social Business Intelligence Market Segmentation
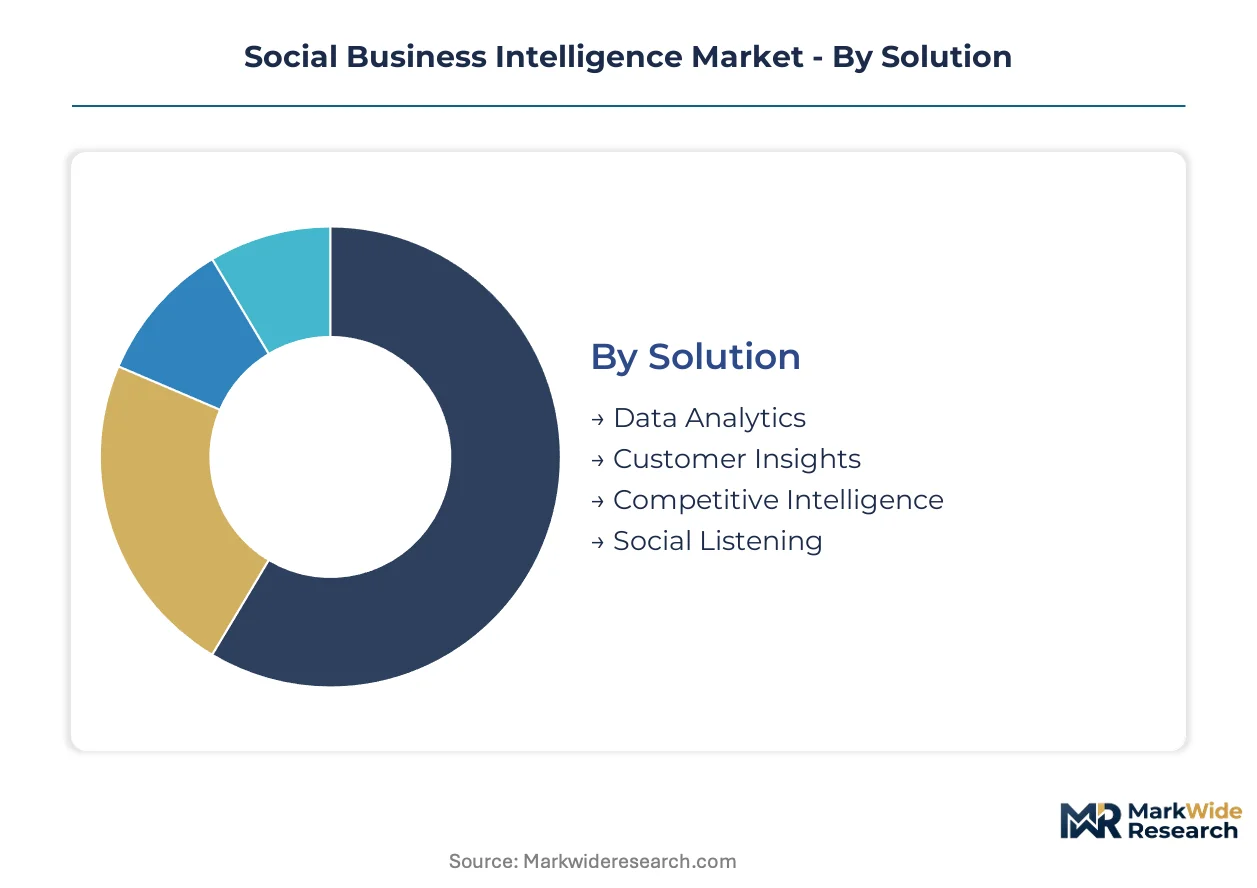
Segmentation in social business intelligence reveals how compliance burdens, infrastructure requirements, and functional sophistication stratify procurement decisions across buyer types. Vendors must architect distinct certification pathways for each segment cluster.
Solution:
ISO 27001 certification applies universally across all solution tiers, while FDA oversight specifically governs Customer Insights deployments in pharmaceutical marketing contexts.
- Customer Insights:Platforms correlating sentiment signals with lifetime value calculations and churn risk scoring. Financial services firms in the United States deploy these for real-time reputation threat detection during viral crisis events.
- Social Listening:Foundational data aggregation and keyword monitoring systems. Marketing agencies favor these for brand perception tracking, though API rate limiting from platform providers constrains real-time ingestion velocity.
- Data Analytics:Statistical processing engines for pattern recognition across social datasets.
- Competitive Intelligence:Rival monitoring tools for market positioning analysis.
Social Listening sits at the top of the volume ranking, with Customer Insights climbing the fastest.
Deployment Model:
Cost tiering separates hyperscale cloud elasticity from fixed-capital on-premises installations, with hybrid architectures occupying the middle pricing band.
- Cloud-based:Elastic compute architectures satisfying viral event spike demand. The EU AI Act's risk classification requirements for automated sentiment systems elevate engineering costs for European deployments.
- On-premises:Physical infrastructure for strict data sovereignty mandates. Banking and defense sectors in Germany require these for classified environment processing under BSI compliance.
- SaaS:Subscription-delivered software with vendor-managed infrastructure.
- Hybrid:Split architectures balancing latency sensitivity with cost optimization.
Cloud-based deployments dominate current adoption volumes, with hybrid configurations expanding most quickly among regulated industries.
End User:
Procurement sophistication varies sharply across organizational maturity, from enterprise committee-driven evaluations to startup self-service adoption.
- Enterprises:Multi-divisional deployments requiring custom middleware for legacy CRM integration. United States procurement committees now mandate proof-of-concept trials before multi-year commitments.
- Marketing Agencies:Project-based buyers running parallel vendor evaluations against identical crisis scenarios. These clients drive demand for modular sentiment engine components.
- Startups:Price-sensitive adopters prioritizing speed over compliance depth.
- Non-profits:Grant-funded implementations with restricted customization budgets.
Enterprises command the largest absolute spending, with marketing agencies gaining share fastest through compressed procurement cycles.
Feature Set:
Application criticality determines which features justify premium pricing versus commoditized baseline functionality.
- Sentiment Analysis:Natural language processing engines parsing multilingual emotion at scale. The EU AI Act imposes documentation burdens on systems influencing credit or employment outcomes in France and Germany.
- Trend Detection:Viral event identification algorithms requiring real-time compute scaling. Edge computing convergence is reducing latency for defense sector classified environments.
- Engagement Metrics:Quantified interaction measurement for campaign optimization.
- Reporting Tools:Visualization and dashboard exports for stakeholder communication.
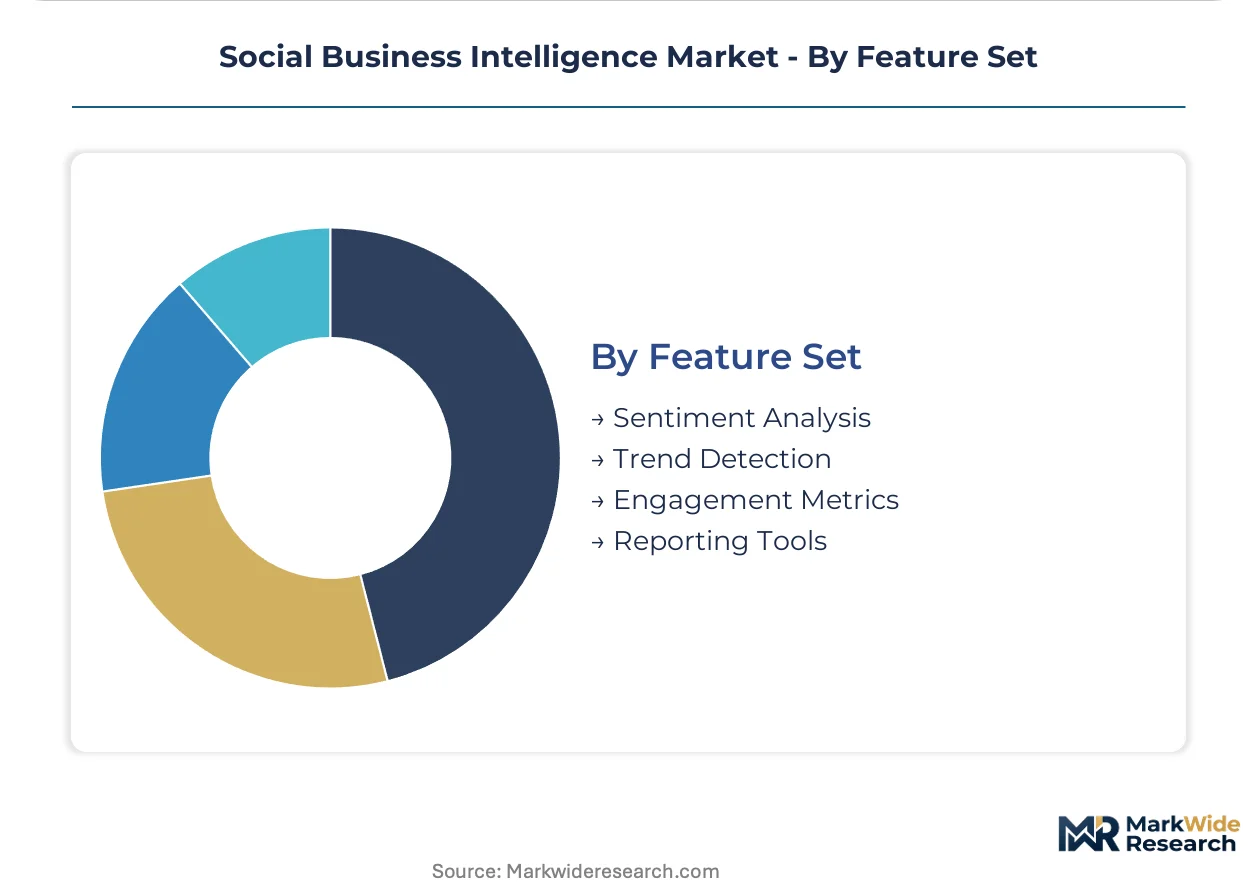
Sentiment Analysis leads feature adoption by volume, with Trend Detection showing the steepest expansion trajectory among crisis-conscious buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Social Business Intelligence industry emerged from early Silicon Valley data analytics clusters before expanding into European financial centers and Asia-Pacific enterprise hubs. Cloud infrastructure investments in the United States established the foundational architecture for real-time sentiment processing at scale. Regulatory divergence across jurisdictions now fragments deployment strategies.
United States
Enterprise software budgets and social media penetration rates concentrate demand among financial services and marketing agencies. The SEC and FTC impose disclosure requirements on automated sentiment tools used in investor communications. New York and San Francisco host the densest vendor ecosystems for crisis monitoring and brand perception analytics.
Germany
Banking and automotive sectors drive on-premises deployment demand for strict data sovereignty compliance. BSI and GDPR mandates require redundant infrastructure investments for European social data processing. Frankfurt and Munich anchor compliance-ready hosting clusters serving regulated industries across the DACH region.
United Kingdom
Marketing agencies and fintech startups favor modular sentiment engine components for rapid reconfiguration. The Information Commissioner's Office enforces GDPR-aligned accountability for automated decision systems. London's financial district sustains premium pricing for real-time reputation threat detection tools.
France
Luxury goods and pharmaceutical marketing create dual-track compliance demand for patient-reported outcome analytics. ANSM and CNIL impose documentation burdens on sentiment systems influencing consumer credit decisions. Paris hosts specialized vendors serving FDA-regulated pharmaceutical marketing workflows.
India
IT services outsourcing and startup ecosystems generate price-sensitive demand for cloud-native social listening platforms. The Digital Personal Data Protection Act is reshaping cross-border data transfer architectures for European clients. Bangalore and Hyderabad sustain delivery centers for multilingual NLP development and low-resource language model training.
Social Business Intelligence Market Competitive Environment
The competitive structure tilts toward hyperscale cloud providers with compliance-ready infrastructure. Consolidation pressures favor vendors integrating sentiment engines directly into enterprise software stacks. Three archetypes dominate: cloud-native platform builders, legacy enterprise software extenders, and specialized crisis-monitoring boutiques. Strategic moves center on API ecosystem expansion and jurisdiction-specific certification acquisition.
Among legacy enterprise software extenders, IBM Corporation, Oracle Corporation, and Microsoft Corporation exemplify the integration-heavy archetype. IBM's services heritage positions it within complex federal deployment contexts. Oracle anchors data warehouse connectivity for financial services procurement committees. Microsoft's Azure infrastructure sustains multi-jurisdictional compliance layers across European and North American deployments.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Oracle Corporation |
| Salesforce, Inc. |
| SAS Institute Inc. |
| Sprinklr, Inc. |
| Adobe, Inc. |
| Google LLC |
| Others |
Value Chain & Pricing Dynamics
Enterprise procurement committees in the United States anchor pricing power toward subscription-based SaaS tiers, compressing project-based consulting margins as cloud-native platforms scale compliance-ready infrastructure across multiple jurisdictions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the Social Business Intelligence landscape, with ISO 27001 certification grade and data residency configuration serving as the primary price differentiation drivers. Cost compression in the economy tier intensifies because hyperscale cloud providers bundle basic sentiment tools into existing enterprise agreements. Marketing agencies exhibit the highest price sensitivity, while banking procurement committees in Germany tolerate premium pricing for audited on-premises deployments with BSI compliance.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based GPU foundries supplying training infrastructure for transformer-based NLP engines. The supply chain draws from the United States for cloud hyperscaler capacity, Ireland for GDPR-compliant data hosting, and India for multilingual annotation labor. Tariff exposure on semiconductor components threatens margin stability for on-premises hardware vendors. Distribution runs through direct enterprise sales teams and systems integrators serving federal deployment contexts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Social Business Intelligence market compounds steadily as regulatory fragmentation across jurisdictions forces recurring compliance investment cycles that sustain vendor pricing power.
For Market Incumbents: Acquire specialized NLP boutiques with low-resource language capabilities to counter emerging cloud-native challengers. Deepen vertical integration into edge computing hardware for defense sector classified environments. ISO 27701 certification investment opens banking procurement committees in Germany and France. For New Entrants and Emerging Players: Marketing agencies in the United Kingdom represent the most accessible channel partner type for modular sentiment engine components. White-space concentration exists in patient-reported outcome analytics for FDA-regulated pharmaceutical marketing. A go-to-market angle through Salesforce AppExchange integration reduces implementation friction for mid-market CRM users. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, consolidating compliance-ready infrastructure stacks. The market supports long-term viability through sustained regulatory complexity. Target acquisition archetypes include boutique crisis-monitoring firms with federal security clearances. The signal to watch is EU AI Act enforcement velocity in France and Germany as inflection indicator for compliance module demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | IBM's services heritage positions it for complex federal deployment contexts requiring security clearance. |
| Platform Integration | Salesforce native CRM connectivity reduces implementation friction for marketing agency procurement cycles. |
| Geographic Expansion | Microsoft Azure sustains multi-jurisdictional compliance layers across European and North American deployments. |
| Product Launch | Oracle anchors data warehouse connectivity for financial services procurement committees in New York. |
| Strategic Partnership | Adobe's creative cloud ecosystem opens cross-sell pathways for sentiment-driven campaign optimization tools. |
Study Parameters
Direct dialogue with CTOs, IT procurement officers, platform engineers, and channel partners grounded the qualitative foundation, cross-referenced against SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and EU regulatory submission databases. Bottom-up deployment volume estimates triangulated with top-down enterprise software spend analysis.
Segmentation outputs across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern fed into the analytical framework. CAGRs were derived from elasticity-adjusted adoption curves incorporating viral event frequency and compliance cost trajectories. Industry-specific inputs included API rate limiting constraints from platform providers and multilingual NLP development timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement patterns and GDPR data residency mandate expansion. Forecasts reflect assumptions about cloud infrastructure cost curves and regulatory fragmentation persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Retail Analytics Software and Services Market
Analytics
Location Analytics Market
Analytics
Web Analytics Market
Analytics
Content Analytics Software Market
Analytics
Greece ICT Market
Analytics
Complex Event Processing Market
Analytics
App Analytics Tools Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Identity Analytics Market
Analytics
Application Analytics Market
Analytics
Global Performance Analytics Market
Analytics
China Contact Center Analytics Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Edge Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market