
 High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market | 2026-2036
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market Analysis
Cloud-native enterprises and sovereign government buyers is bifurcating demand in the HPC and HPDA landscape. NVIDIA Corporation dominates GPU-accelerated AI training clusters through its Grace-Hopper architecture and CUDA ecosystem lock-in. Microsoft Corporation extends its position via Azure HB-series VMs and deep integration with OpenAI workloads. IBM Corporation specializes in quantum-HPC hybrid orchestration and confidential computing for regulated financial modeling.
High Performance Computing and High Performance Data Analytics encompass parallel processing architectures operating at petaflop-to-exaflop scales, typically employing CPU-GPU heterogeneous nodes with high-bandwidth memory and low-latency InfiniBand or Slingshot interconnects for computationally intensive simulation, inference, and large-scale analytics. Cloud Computing deployment is accelerating fastest as burst-capacity and spot-pricing models reduce capital barriers for mid-scale users, while On-premises systems retain margin concentration in classified government and pharmaceutical molecular dynamics workloads. Supercomputers remain the prestige tier with longest sales cycles, whereas Machine Learning application demand is outpacing traditional Scientific Research in annual procurement growth.
FERC grid-interconnection standards, EU GDPR data-localization mandates, and US NIST post-quantum cryptography guidelines are reshaping procurement specifications and cross-border data governance for HPC facility operators. The US EPA energy-efficiency regulations for data centers above fifty megawatts are pressuring facility designs toward liquid cooling and renewable power purchase agreements. Stakeholders must weigh sovereign infrastructure commitments against cloud elasticity as exascale power requirements and export control regimes tighten supply options.
Market Dynamics
The HPC and HPDA market is bifurcating around sovereign infrastructure mandates and cloud-native elasticity, with EU AI Act compliance requirements forcing procurement teams to choose between on-premises verifiability and hyperscaler convenience.
Growth Catalysts
- EU AI Act Verification Mandates:Risk-classification rules for high-stakes AI systems are accelerating procurement of on-premises GPU clusters with auditable data lineage.
- Automotive Simulation Demand:German OEMs and tier-one suppliers are expanding petaflop-scale wind tunnel and crash simulation capacity to compress EV development cycles.
- Liquid Cooling Adoption:Direct-to-chip and immersion systems are extending facility power density limits beyond traditional air-cooled architectures.
Market Restraints
- Advanced Packaging Bottlenecks:CoWoS and HBM3 supply concentration in Taiwan is constraining GPU cluster delivery timelines.
- Export Control Friction:US Bureau of Industry and Security licensing requirements are fragmenting cross-border AI training collaborations.
- Interconnect Standards Proliferation:Competing InfiniBand, Slingshot, and Ultra Ethernet specifications are extending integration testing cycles.
Strategic Opportunities
- Quantum-HPC Hybrid Orchestration:Variational algorithms and quantum error mitigation are converging with classical supercomputing for molecular simulation.
- India Semiconductor Mission Incentives:Design-linked and production-linked schemes are attracting captive GPU packaging and system integration capacity.
- Confidential Computing Workloads:Financial regulators in Switzerland and Singapore are mandating encrypted-in-use processing for cross-border risk models.
Industry Challenges
- Systems Software Talent Scarcity:Expertise in MPI optimization, CUDA kernel tuning, and Slingshot fabric configuration is concentrating at national laboratories and hyperscalers.
- Legacy Fortran Codebases:Decades of physics simulation code require costly refactoring for GPU offload and cloud-native containerization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market |
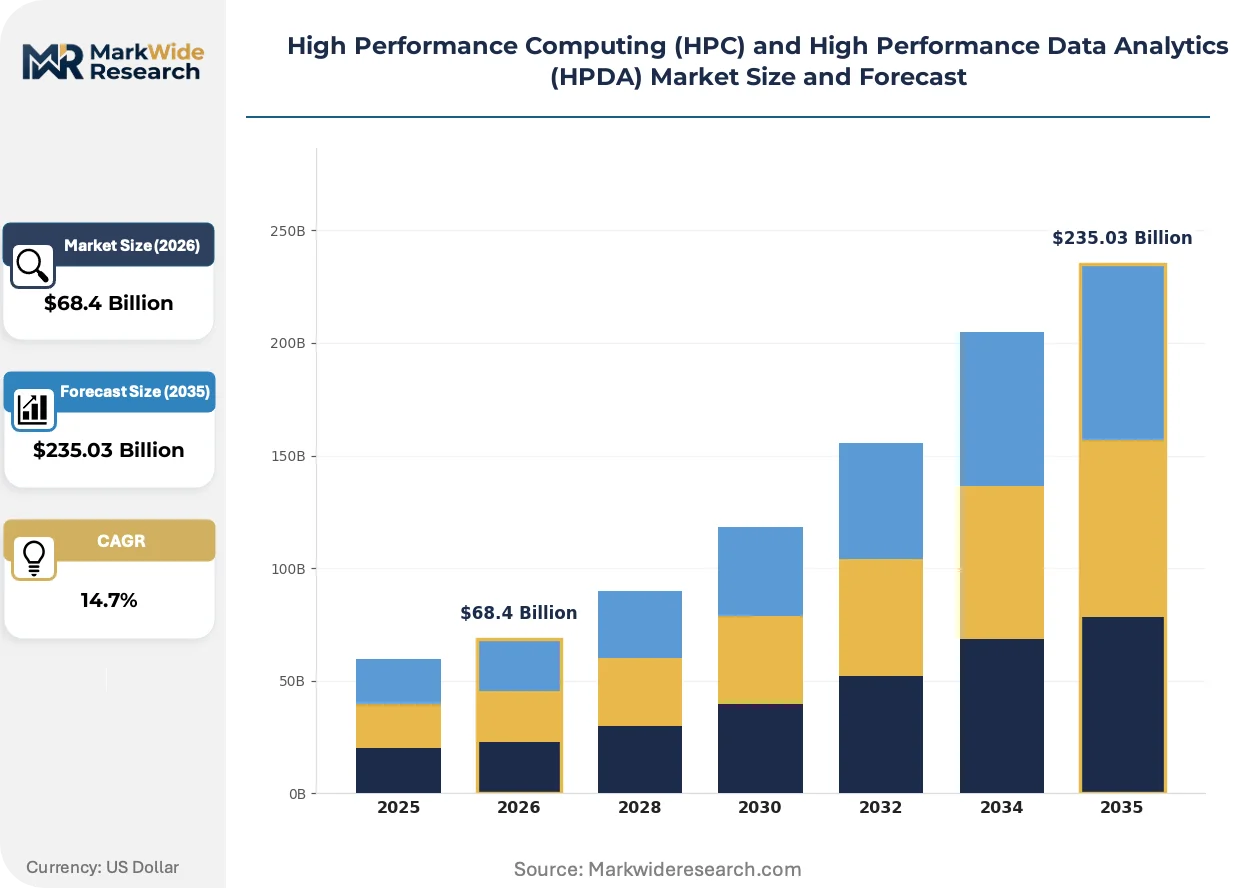
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $235.03 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Scientific Research, Financial Modeling, Weather Forecasting, Machine Learning Technology: Cluster Computing, Grid Computing, Supercomputers, Cloud Computing End User: Aerospace, Healthcare, Automotive, Government Deployment: On-premises, Hybrid Cloud, Public Cloud, Private Cloud |
| Companies Covered | Hewlett Packard Enterprise, Microsoft Corporation, NVIDIA Corporation, IBM Corporation, Dell Technologies, Lenovo Group Limited, Atos SE, Amazon Web Services, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market Emerging Trajectories
Computational architectures are converging around memory-centric designs and policy-driven data sovereignty, compressing traditional distinctions between simulation, analytics, and AI training infrastructure.
Optical interconnects are supplanting electrical copper backplanes in exascale node-to-node communication. Forschungszentrum Jülich and Lawrence Livermore National Laboratory are deploying co-packaged optics in 2024-2025 system generations. This shift is enabling sub-microsecond latency at hundred-meter rack scales while reducing per-bit power consumption.
EU GDPR data-localization mandates are forcing hyperscalers to establish region-bound sovereign cloud instances with cryptographic tenant isolation. Financial services regulators in Germany and France are now requiring proof of data residency for algorithmic trading risk calculations. Pharmaceutical sponsors are responding by procuring dedicated bare-metal partitions rather than shared multi-tenant infrastructure.
Consumption-based procurement is displacing capital-intensive ownership models among mid-scale research institutions. Spot-pricing and burst-capacity contracts from Azure and AWS are capturing molecular dynamics and genomics workloads previously executed on owned clusters. This pattern is most pronounced in Nordic countries where national research councils have consolidated purchasing through centralized cloud frameworks.
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market Segmentation
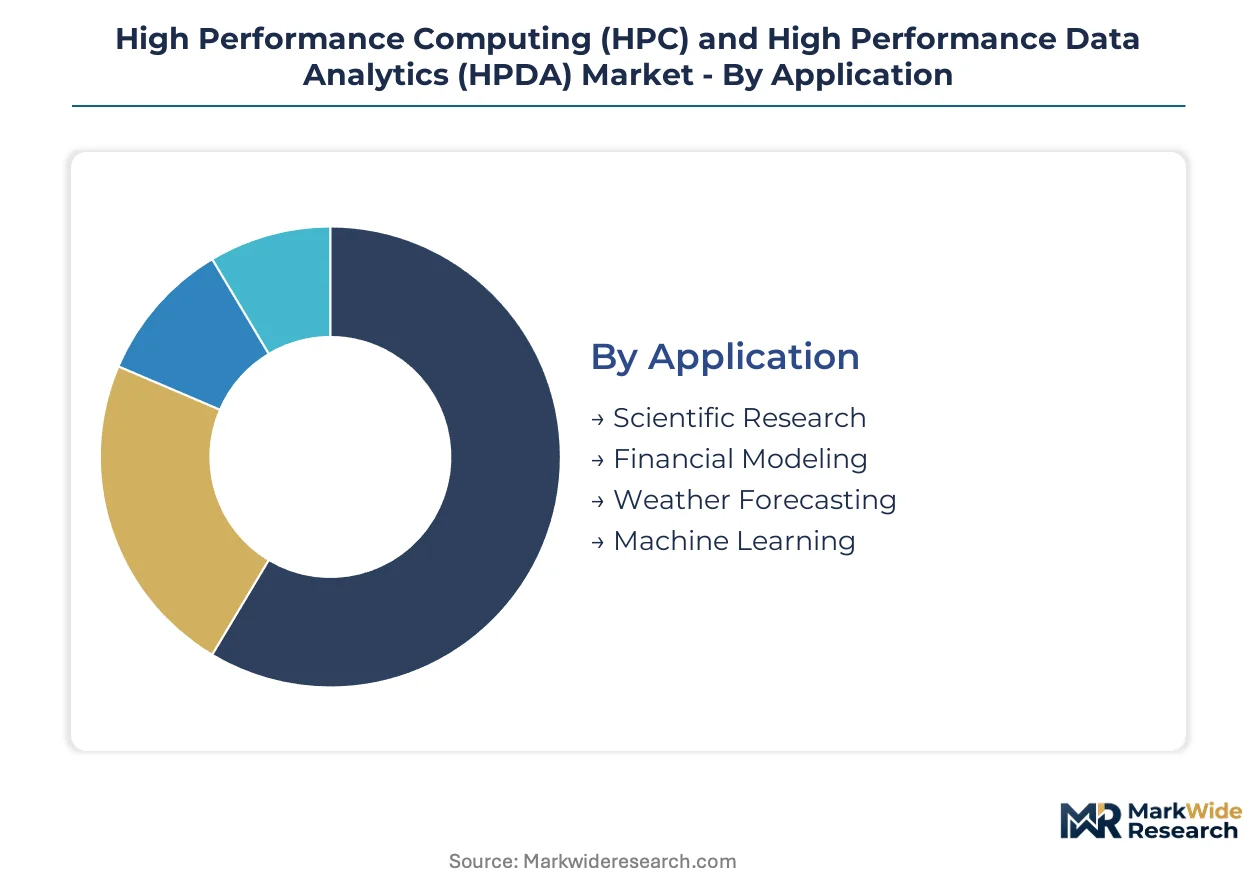
HPC and HPDA procurement patterns fragment sharply across workload types and operational models. Buyers optimize infrastructure choices against data sovereignty requirements, latency sensitivity, and burst-capacity needs.
Application:
Margin pools concentrate in algorithmic trading and AI training clusters where GPU density commands premium pricing.
- Scientific Research:Traditional simulation workloads in climate modeling and astrophysics rely on double-precision floating-point architectures. Lawrence Livermore National Laboratory and Forschungszentrum Jülich anchor demand for petascale capability.
- Machine Learning:Transformer training and inference at scale drives heterogeneous CPU-GPU node configurations with high-bandwidth memory. Financial services firms in Singapore and pharmaceutical sponsors in Switzerland are expanding cluster procurement for encrypted-in-use processing.
- Financial Modeling:Monte Carlo risk simulations and real-time derivatives pricing require deterministic latency guarantees.
- Weather Forecasting:Operational meteorology services run ensemble predictions on sovereign infrastructure with strict data residency requirements.
Scientific Research holds installed capacity. Machine Learning is rotating up the share rankings.
Technology:
Volume concentrates in distributed architectures that trade peak performance for operational flexibility and capital efficiency.
- Cloud Computing:Burst-capacity and spot-pricing models reduce capital barriers for mid-scale genomics and molecular dynamics users. Nordic national research councils have consolidated purchasing through centralized cloud frameworks.
- Supercomputers:Prestige-tier systems with longest sales cycles serve classified government workloads and pharmaceutical molecular dynamics. These installations retain margin concentration despite unit volume constraints.
- Cluster Computing:Department-scale deployments dominate university research environments with moderate parallelism requirements.
- Grid Computing:Federated resource sharing persists in high-energy physics collaborations with geographically distributed detector networks.
Supercomputers anchor sovereign capability. Cloud Computing is expanding most quickly among institutional buyers.
End User:
Customer type determines procurement channel and compliance burden more than raw compute specifications.
- Government:Defense contractors and intelligence agencies mandate on-premises verifiability with auditable data lineage under EU AI Act risk-classification rules.
- Automotive:German OEMs and tier-one suppliers are expanding petaflop-scale wind tunnel and crash simulation capacity to compress EV development cycles.
- Healthcare:Pharmaceutical sponsors procure dedicated bare-metal partitions with cryptographic tenant isolation to satisfy GDPR data-localization mandates.
- Aerospace:Satellite constellation operators and airframe manufacturers require classified facility access for aerothermal and structural certification workloads.
Government holds installed capacity. Automotive is rotating up the share rankings.
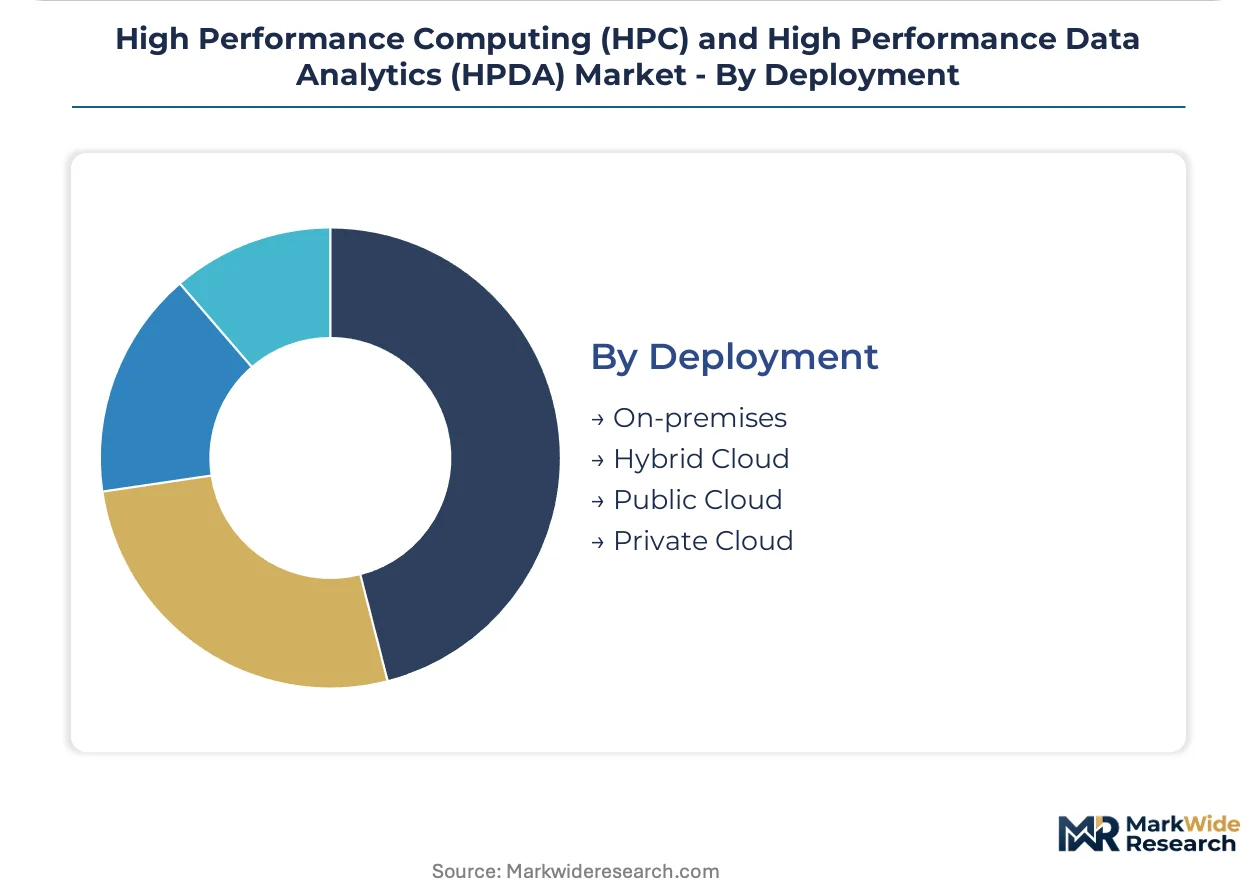
Deployment:
Operational model selection hinges on export control exposure and cross-border collaboration requirements.
- On-premises:Classified government and regulated financial modeling workloads retain margin concentration. Direct-to-chip liquid cooling extends facility power density beyond traditional air-cooled limits.
- Hybrid Cloud:Burst-capacity architectures allow sovereign core infrastructure with elastic overflow to hyperscaler partitions. This model captures molecular dynamics workloads previously executed on owned clusters.
- Private Cloud:Single-tenant dedicated infrastructure serves pharmaceutical sponsors requiring proof of data residency for algorithmic risk calculations.
- Public Cloud:Shared multi-tenant instances compete on spot-pricing for non-sensitive batch processing with relaxed latency requirements.
On-premises holds installed capacity. Hybrid Cloud is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU-accelerated systems manufactured in the United States flow primarily to European sovereign computing centers and Asian cloud operators. Cross-border procurement now navigates export licensing regimes and data-localization statutes that fragment traditional supply relationships.
United States
Lawrence Livermore National Laboratory and Oak Ridge National Laboratory anchor exascale deployment with classified simulation workloads. NIST post-quantum cryptography guidelines reshape procurement specifications for facilities handling sensitive government data. Austin, Texas and the San Francisco Bay Area concentrate system integrators serving defense contractors with air-gapped infrastructure requirements.
Germany
Forschungszentrum Jülich operates Europe's preeminent GPU-accelerated supercomputing facility for automotive and materials science applications. EU AI Act risk-classification rules mandate auditable data lineage for high-stakes AI training clusters. Stuttgart and Munich host OEM simulation centers expanding petaflop-scale wind tunnel capacity for compressed EV development cycles.
China
Domestic semiconductor packaging capacity scales under national technology self-sufficiency programs. MIIT standards and dual carbon goals pressure facility designs toward liquid cooling and renewable power sourcing. Shanghai and Beijing metropolitan clusters concentrate indigenous system integration for weather forecasting and genomic analytics workloads.
India
Design-linked and production-linked incentive schemes attract captive GPU packaging and system integration investments. The country's national technology regulator advances data-center energy-efficiency mandates for facilities above fifty megawatts. Bangalore and Hyderabad anchor cloud-native research computing adoption through centralized national research council frameworks.
Japan
Riken Center for Computational Science drives quantum-HPC hybrid orchestration for molecular simulation applications. METI industrial policy prioritizes domestic advanced packaging capacity to reduce Taiwan supply concentration exposure. Osaka and Kobe harbor maritime engineering clusters deploying sovereign infrastructure for tsunami and typhoon ensemble prediction systems.
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market Vendor Landscape
Listed leaders compete with private specialists across sovereign infrastructure and cloud-native deployment vectors. The vendor base stratifies between hyperscale cloud operators, traditional system integrators, and semiconductor architecture specialists. Three archetypes dominate: GPU-accelerated platform vendors, quantum-classical hybrid orchestrators, and confidential computing enclaves. Competitive moves concentrate on strategic partnerships for sovereign cloud instances and backward integration into advanced packaging capacity.
Within the GPU-accelerated tier, NVIDIA Corporation and AMD exemplify architecture specialists commanding premium positioning through proprietary interconnect ecosystems. Microsoft Corporation and Amazon Web Services occupy the cloud-native vector, leveraging burst-capacity pricing models to capture molecular dynamics workloads migrating from owned clusters. IBM Corporation anchors the quantum-HPC hybrid segment, representing the confidential computing archetype for regulated financial modeling applications.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Microsoft Corporation |
| NVIDIA Corporation |
| IBM Corporation |
| Dell Technologies |
| Lenovo Group Limited |
| Atos SE |
| Amazon Web Services |
| Google LLC |
| Others |
Supply Flow & Price Mechanics
US Bureau of Industry and Security licensing requirements gate both GPU cluster qualification and price differentiation, with compliant systems commanding substantial premiums over restricted-tier alternatives. This dual-gating mechanism compresses margins for non-compliant integrators while concentrating pricing power among licensed vendors serving sovereign computing centers.
Pricing Analysis
Grace-Hopper generation nodes price at multiples of prior-gen A100 clusters, while next-gen Blackwell systems carry further premiums for co-packaged optics and HBM3e memory. Three-tier pricing structure across exascale sovereign installations, departmental cluster deployments, and burst-capacity cloud instances reflects certification grade and data residency guarantees. Cost compression in mid-scale cloud segments is intensifying because spot-pricing competition from Azure and AWS captures molecular dynamics workloads migrating from owned infrastructure. Academic research councils exhibit highest price sensitivity, whereas defense contractors and intelligence agencies prioritize verifiability over unit economics.
Supply Chain Analysis
Inbound logistics costs through the Port of Kaohsiung and Yokohama fluctuate with container availability for advanced packaging equipment shipments from Taiwan and Japan. CoWoS and HBM3 supply concentrates in Taiwan, with South Korea anchoring HBM memory fabrication and the United States hosting GPU die production. Raw material dependencies span silicon wafers, advanced photoresists, and rare-earth elements for magnetic components in liquid cooling systems. Single-source vulnerability around TSMC advanced packaging capacity threatens delivery timelines for exascale deployments. Distribution runs through system integrators in Austin, Stuttgart, and Bangalore with direct-to-laboratory fulfillment for classified installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
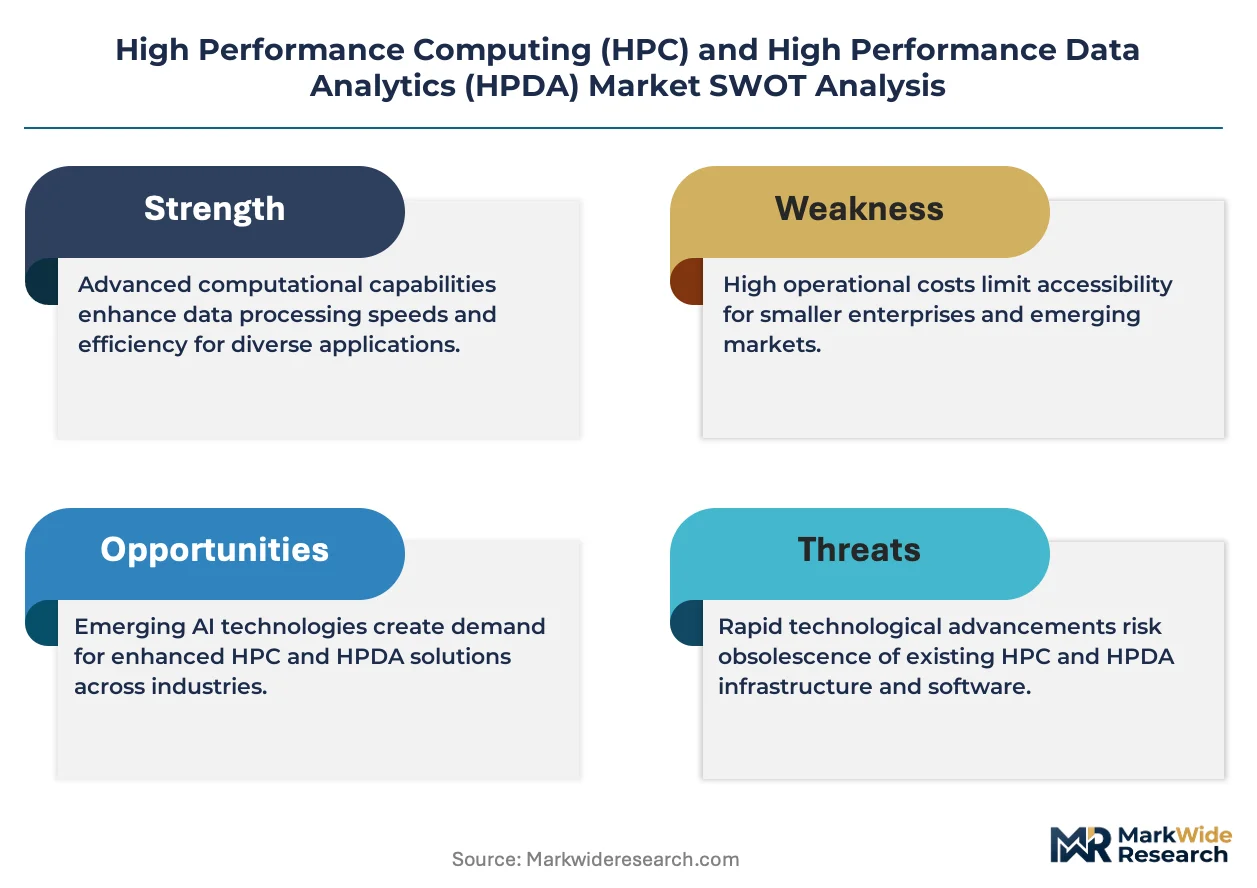
Cloud-native GPU instances represent a credible substitute threat to traditional on-premises cluster ownership, forcing incumbents to defend installed base through sovereign-cloud partnerships and compliance-integrated offerings.
For Market Incumbents: Fortify position through captive advanced packaging investments in India under Production-Linked Incentive schemes, reducing Taiwan supply concentration exposure. Deepen sovereign cloud partnerships with EU member states to satisfy GDPR data-localization mandates and EU AI Act verification requirements against hyperscaler substitution. For New Entrants and Emerging Players: Lead with confidential computing enclaves for Swiss and Singapore financial regulators mandating encrypted-in-use processing, a segment where established vendors lack specialized positioning. Target Nordic national research councils consolidating procurement through centralized cloud frameworks, offering consumption-based pricing without legacy Fortran codebase migration burdens. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across quantum-HPC hybrid orchestration platforms, where error mitigation software and cryogenic infrastructure requirements extend payback periods. Favor acquisition targets with established MPI optimization talent pools and Slingshot fabric configuration expertise concentrated at national laboratories. Watch optical interconnect adoption rates at Forschungszentrum Jülich and Lawrence Livermore National Laboratory as inflection indicators for co-packaged optics demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | EU AI Act compliance requirements in Germany and France mandate auditable data lineage for high-stakes AI training clusters. |
| Backward Integration into Advanced Packaging | India Semiconductor Mission incentives attract captive GPU packaging capacity to reduce Taiwan supply concentration. |
| Confidential Computing Certification | Swiss FINMA and Singapore MAS regulations require encrypted-in-use processing for cross-border risk model workloads. |
| Liquid Cooling Infrastructure Deployment | US EPA energy-efficiency regulations for data centers above fifty megawatts pressure facility designs toward direct-to-chip systems. |
| Quantum-HPC Hybrid Platform Launch | Riken Center for Computational Science drives variational algorithm convergence with classical supercomputing for molecular simulation. |
Methodological Framework
A spread of perspectives from supercomputing facility directors, GPU cluster procurement officers, hyperscaler platform engineers, and national laboratory systems architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through hyperscaler capex disclosures, national research council budget allocations, and SEC filings from listed system integrators. Bottom-up triangulation across deployment scale, technology generation, and end-user compliance requirements anchored volume estimates against top-down market sizing.
Segmentation dimensions modeled span application type, deployment model, technology architecture, and end-user regulatory burden across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating sovereign infrastructure commitments and cloud migration patterns. Forecast inputs include EU AI Act implementation timelines, US Bureau of Industry and Security licensing throughput, and advanced packaging capacity expansion announcements.
Underlying assumptions cover sustained export control friction and liquid cooling adoption rates, with deviation risk concentrated in Taiwan supply chain disruptions and quantum error correction breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
SME Big Data Market
Analytics
APAC Data Wrangling Market
Analytics
Europe Data Monetization Market
Analytics
Sweden ICT Market
Analytics
Web Analytics Market
Analytics
HR Analytics Market
Analytics
Global in-Memory Analytics Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Global Data Analysis Software Market
Analytics
Procurement Analytics Market
Analytics
Asia-Pacific Edge Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Global Clickstream Analytics Market
Analytics
Content Analytics Software Market
Analytics
Drone Analytics Software Market