
 Cyprus ICT Market | 2026-2036
Cyprus ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Cyprus ICT Market Insights
Modular service bundling is hardening as the dominant procurement pattern across Cypriot enterprises, pushing buyers toward integrated cloud-telecom-cybersecurity packages rather than standalone contracts. Cyta leverages its fixed-line infrastructure to anchor hybrid cloud offerings for government clients. Epic Ltd competes through aggressive mobile-first positioning in the consumer and SME segments. Intrasoft International specializes in EU-funded public sector digitalization projects, sustaining long-term revenue visibility through Brussels-backed programs.
Information and communications technology in Cyprus encompasses electronic systems for data processing, transmission, and storage operating across fiber-optic, 5G, and satellite networks with latency thresholds critical for real-time financial trading. Cloud Services dominate current revenue pools among service type segments, while Cybersecurity Solutions registers the fastest expansion as EU NIS2 directive compliance deadlines approach. Hybrid Cloud deployment models capture disproportionate margin contribution by addressing data sovereignty requirements of Limassol-based investment funds and shipping operators.
The Cyprus Securities and Exchange Commission imposes granular IT governance rules on regulated entities, while national alignment with EU GDPR and NIS2 frameworks elevates baseline cybersecurity spending across all sectors. The country's central bank reinforces operational resilience standards for payment service providers and electronic money institutions. Stakeholders must track how forthcoming EU AI Act implementation timelines intersect with Cyprus's existing fintech licensing regime to anticipate compliance cost trajectories.
Market Dynamics
EU NIS2 directive compliance deadlines are compressing procurement cycles across Cypriot enterprises, forcing accelerated cybersecurity investments and reshaping vendor selection criteria toward integrated service bundles.
Growth Catalysts
- NIS2 Transposition:Cyprus's national implementation of the EU cybersecurity directive mandates enhanced risk management frameworks for critical infrastructure operators, expanding managed security service contracts.
- Limassol Fintech Density:The concentration of investment funds and electronic money institutions in this coastal city generates sustained demand for low-latency connectivity and data sovereignty-compliant cloud architecture.
- EU Recovery Fund Access:Brussels-backed digitalization programs channel capital into public sector IT modernization, creating multi-year project pipelines for system integrators.
Market Restraints
- Skilled Labor Scarcity:Cyprus's domestic talent pool for certified cloud architects and cybersecurity specialists remains shallow relative to enterprise demand, inflating personnel costs.
- Submarine Cable Concentration:International connectivity depends heavily on a limited number of Mediterranean fiber routes, exposing data transmission to geopolitical and physical disruption risks.
- GDPR Enforcement Intensity:The country's data protection commissioner maintains aggressive audit schedules, elevating compliance overhead for data-intensive service providers.
Strategic Opportunities
- Paphos Smart City Infrastructure:Municipal digitalization initiatives in this western district remain underpenetrated relative to Nicosia and Limassol, offering first-mover positioning for integrated platform vendors.
- Maritime IoT Convergence:The shipping sector's adoption of satellite-terrestrial hybrid networks creates openings for vessel-to-shore data analytics and predictive maintenance services.
- EU AI Act Preparation:Early compliance advisory services for high-risk AI system classification are capturing premium pricing from fintech licensees anticipating 2025 implementation timelines.
Industry Challenges
- Legacy Core Banking Integration:Financial institutions face complex middleware requirements when connecting cloud-native applications to decades-old transactional systems.
- Multi-Cloud Orchestration Complexity:Enterprises struggle to maintain consistent security postures across heterogeneous environments spanning on-premises, private cloud, and hyperscaler infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyprus ICT Market |
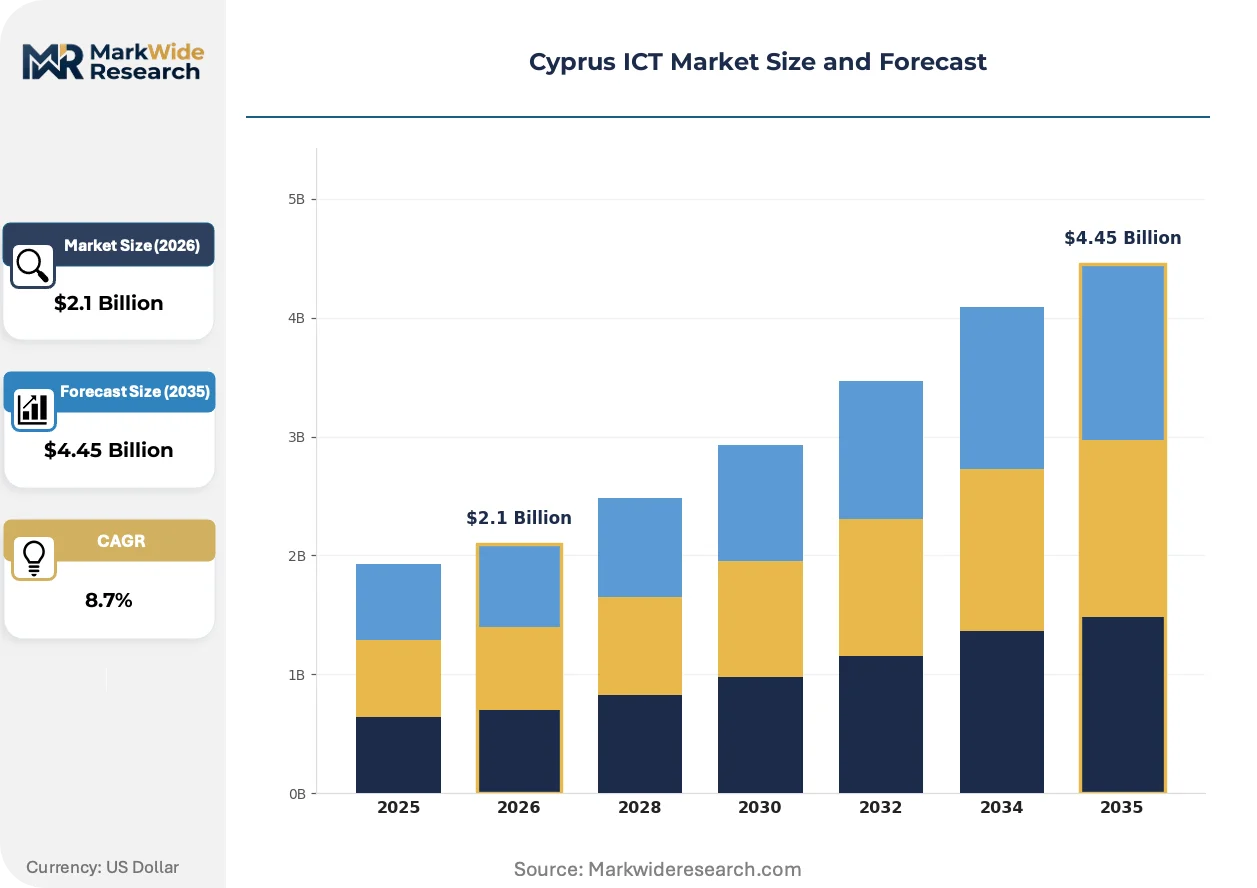
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Data Analytics, Cybersecurity Solutions, Application Development Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Government, SMEs, Large Enterprises, Educational Institutions Technology: Artificial Intelligence, Blockchain, Internet of Things, Big Data |
| Companies Covered | Cyta, Epic Ltd, PrimeTel Public Company Ltd, Logicom Public Ltd, MTN Cyprus, Cablenet Communication Systems Public Company Ltd, Microsoft Corporation, IBM, Intrasoft International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyprus ICT Market Trends and Innovations
Hybrid cloud architectures are displacing pure public cloud commitments as data sovereignty requirements harden, while regulatory compliance automation and modular service consumption reshape how Cypriot enterprises procure technology.
Software-defined wide area networking is consolidating branch connectivity across distributed financial services operations. Investment funds with Limassol headquarters are deploying SD-WAN to aggregate multiple underlay circuits into unified policy-controlled overlays. This technology is consolidating the previously fragmented managed network services market by collapsing routing, security, and application optimization into single-vendor contracts.
Cyprus's alignment with the EU AI Act is accelerating algorithmic governance investments among licensed payment institutions. The forthcoming high-risk system classification requirements are compelling fintechs to document training data provenance and establish human oversight protocols. Electronic money institutions with cross-border operations face the steepest compliance curves as they harmonize Cypriot licensing conditions with Brussels-mandated AI transparency standards.
Enterprise buyers are fragmenting historically bundled technology contracts into componentized service lines. Large Cypriot shipping groups now separately procure satellite connectivity, edge computing capacity, and cybersecurity monitoring rather than accepting monolithic packages. This unbundling is most pronounced in Larnaca's logistics corridor, where terminal operators demand granular cost visibility across multi-vendor stacks.
Cyprus ICT Market Segmentation
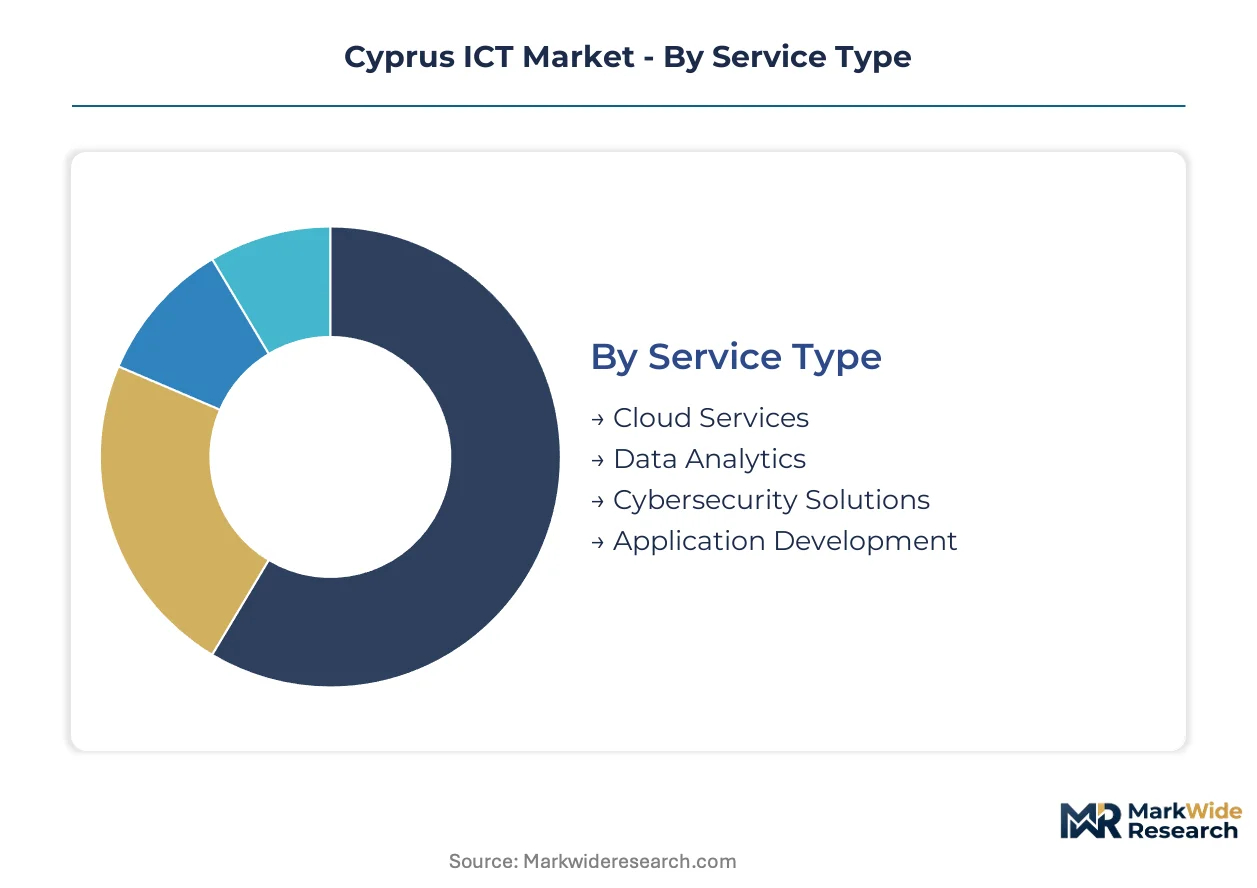
Segmentation reveals how procurement patterns diverge across Cyprus's concentrated enterprise base. Financial services firms in Limassol drive premium service tiers, while EU-funded public sector projects sustain standardized deployments.
Service Type:
Upgrade cycles for core infrastructure systems are compressing as NIS2 deadlines force wholesale platform replacements rather than incremental patching.
- Cloud Services:Encompasses infrastructure-as-a-service, platform-as-a-service, and software-as-a-service delivery models across hyperscaler and domestic data center footprints. Nicosia government clients favor sovereign cloud configurations that satisfy CySEC data residency requirements for regulated workloads.
- Cybersecurity Solutions:Span managed detection and response, identity and access management, and compliance automation tooling. Limassol fintech clusters drive disproportionate spending here as electronic money institutions race to meet EU directive mandates for critical infrastructure operators.
- Data Analytics:Business intelligence platforms and predictive modeling tools deployed across retail banking and shipping logistics verticals.
- Application Development:Custom software engineering and legacy modernization services for core banking system integration projects.
Cloud Services sits at the top of the volume ranking, with Cybersecurity Solutions climbing the fastest.
Deployment Model:
Cost tier differentiation separates commodity public cloud consumption from premium hybrid configurations that command sustained margin premiums.
- Hybrid Cloud:Combines on-premises private infrastructure with burst capacity from public hyperscalers, orchestrated through unified management planes. Investment funds and shipping operators in Limassol specify this architecture to maintain data sovereignty while accessing elastic compute for risk modeling and voyage optimization workloads.
- Private Cloud:Dedicated single-tenant environments hosted in domestic facilities or licensed colocation centers. Government ministries procuring through Cyta's framework agreements favor this model for citizen registry and tax administration systems requiring guaranteed jurisdictional control.
- Public Cloud:Shared multi-tenant infrastructure from global hyperscalers, adopted primarily by SMEs with limited compliance overhead.
- On-Premises:Legacy client-server and mainframe installations persisting in institutions with frozen capital budgets or extreme latency sensitivity.
Hybrid Cloud captures the steepest expansion trajectory as regulatory pressure hardens data localization requirements across regulated sectors.
End User:
Customer type determines contract structure, with government buyers favoring multi-year framework agreements while financial services demand flexible consumption terms.
- Government:Central ministries, municipal authorities, and regulatory bodies procuring through EU co-financed digitalization programs. Intrasoft International maintains dominant positioning here through Brussels-backed public sector modernization contracts with multi-year revenue visibility.
- Large Enterprises:Banking groups, shipping conglomerates, and telecom operators with dedicated procurement functions and complex multi-vendor orchestration requirements. These buyers are fragmenting historically bundled contracts into componentized service lines for granular cost visibility.
- SMEs:Mid-market professional services firms and regional retail chains prioritizing mobile-first, subscription-based consumption models.
- Educational Institutions:Universities and technical colleges with cyclical funding patterns and standardized collaboration platform requirements.
Government represents the largest committed revenue pool, with Large Enterprises gaining share fastest through unbundled procurement patterns.
Technology:
Maturity curves separate proven infrastructure technologies from emerging stacks requiring specialized integration expertise and compliance advisory services.
- Artificial Intelligence:Machine learning operations platforms, natural language processing APIs, and predictive analytics engines. Licensed payment institutions are deploying algorithmic governance frameworks to document training data provenance and establish human oversight protocols ahead of EU AI Act implementation.
- Internet of Things:Sensor networks, edge computing nodes, and satellite-terrestrial hybrid connectivity for vessel-to-shore data transmission. Maritime operators in Larnaca's logistics corridor are adopting predictive maintenance services based on engine telemetry and container tracking feeds.
- Big Data:Distributed storage and stream processing infrastructure for high-velocity transactional and operational data sets.
- Blockchain:Distributed ledger implementations for trade finance documentation and cross-border settlement verification.
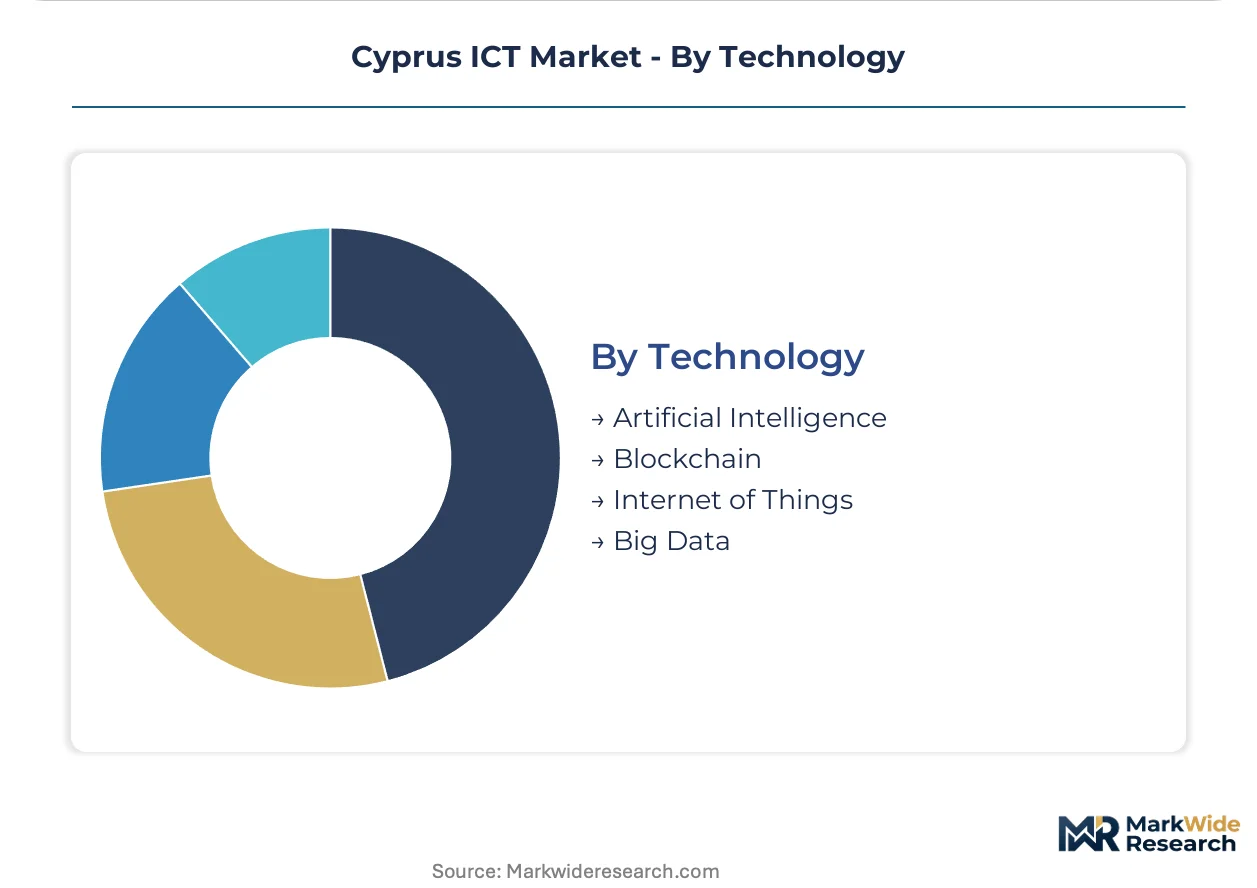
Internet of Things leads current infrastructure deployment value, with Artificial Intelligence expanding most quickly as compliance advisory services capture premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cyprus ICT sector traces its modern foundations to the island's emergence as a Mediterranean telecom hub during the 1990s liberalization of European telecommunications, with infrastructure investment accelerating after EU accession in 2004.
Nicosia
Government digitalization programs and central bank regulatory oversight drive enterprise software procurement. The Cyprus Securities and Exchange Commission mandates granular IT governance standards for licensed entities headquartered here. Ministries cluster around the capital's enterprise corridor, sustaining demand for sovereign cloud configurations and compliance-automation tooling.
Limassol
Investment funds and electronic money institutions generate concentrated demand for low-latency connectivity and data sovereignty-compliant architecture. The Cyprus Securities and Exchange Commission's licensing regime for fintech operators elevates baseline cybersecurity spending. The coastal city's fintech density supports premium service tiers across hybrid cloud and managed security segments.
Larnaca
Maritime logistics operators and shipping conglomerates anchor industrial IoT deployment for vessel-to-shore data transmission. EU NIS2 directive compliance deadlines are compressing procurement cycles for critical infrastructure operators. Terminal operators in this eastern logistics corridor are fragmenting bundled technology contracts into componentized service lines.
Paphos
Municipal smart city initiatives remain underpenetrated relative to established enterprise clusters. Cyprus's national digital transformation agenda channels EU Recovery Fund capital into western district infrastructure. First-mover positioning for integrated platform vendors is opening around predictive analytics and citizen service digitization.
Cyprus ICT Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the compliance-specialization spectrum, with integrated service bundlers commanding sustained pricing power over standalone vendors. The vendor base stratifies into three tiers: infrastructure incumbents with fixed-line heritage, mobile-first challengers, and EU-funded system integrators. Dominant competitive moves include strategic partnerships for hybrid cloud orchestration and portfolio diversification into cybersecurity advisory services.
Within the infrastructure-incumbent tier, Cyta leverages its fixed-line heritage to anchor government framework agreements, while Epic Ltd occupies a mobile-first position across consumer and SME segments. Intrasoft International exemplifies the EU-funded system integrator archetype, securing multi-year revenue visibility through Brussels-backed public sector digitalization programs.
| Leading Market Players |
|---|
| Cyta |
| Epic Ltd |
| PrimeTel Public Company Ltd |
| Logicom Public Ltd |
| MTN Cyprus |
| Cablenet Communication Systems Public Company Ltd |
| Microsoft Corporation |
| IBM |
| Intrasoft International |
| Others |
Pricing and Supply Chain Analysis
Compliance-grade divergence between NIS2-certified managed security bundles and commodity connectivity separates premium pricing from cost-driven procurement across Cypriot enterprises. This bifurcation concentrates margin capture among vendors with CySEC-aligned advisory capabilities while compressing returns for standalone infrastructure providers lacking regulatory integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement across government, large enterprise, and SME segments. Price differentiation rests on certification depth and data sovereignty guarantees, with hybrid cloud configurations commanding sustained premiums over public-only deployments. Cost compression in economy-tier connectivity is intensifying because mobile-first challengers are flooding the consumer and mid-market segments with undifferentiated bandwidth. SMEs exhibit the highest price sensitivity, while Limassol-based investment funds accept premium positioning for latency-critical infrastructure.
Supply Chain Analysis
Cyprus's national digital transformation agenda and EU funding access are reshaping sourcing toward Brussels-qualified system integrators and domestic data center operators. Hardware procurement draws from Germany, the Netherlands, and Taiwan for networking equipment, while hyperscaler cloud capacity feeds from Ireland, Frankfurt, and Amsterdam regions. Single-source vulnerability concentrates in submarine cable landing points, where Mediterranean fiber routes create geopolitical exposure for international data transmission. Distribution runs through Cyta's government framework agreements and direct enterprise sales teams, with channel partners serving fragmented SME demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
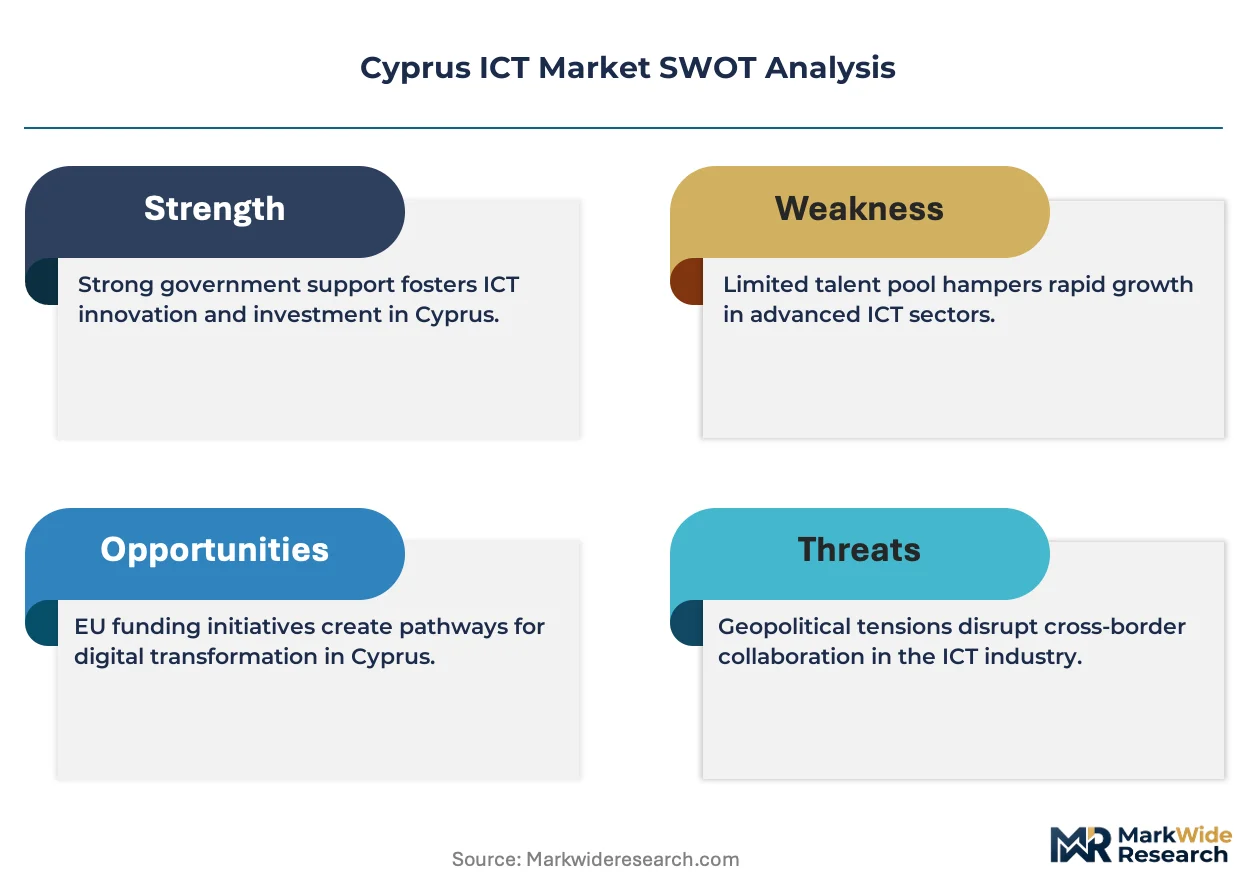
Cyprus's ICT market represents a late-cycle quality story where procurement is shifting toward integrated compliance-advisory bundles rather than standalone infrastructure. NIS2 deadlines and EU AI Act preparation are elevating specification floors across regulated sectors.
For Market Incumbents: Lock in multi-year framework agreements with central government ministries before EU Recovery Fund allocation windows close. Defensive positioning requires deepening cybersecurity advisory capabilities to offset margin erosion from commodity cloud pricing. Cyta's fixed-line heritage and Epic's mobile infrastructure must converge toward hybrid orchestration platforms to repel hyperscaler encroachment into sovereign cloud workloads.
For New Entrants and Emerging Players: The mid-market gap between premium Limassol fintech services and economy SME bundles offers white-space positioning for compliance-automation specialists. Paphos municipal smart city infrastructure remains underpenetrated relative to Nicosia and Limassol corridors. Targeted entry through EU co-financed digitalization programs provides revenue visibility without competing head-to-head against entrenched incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where NIS2 compliance costs exceed standalone operational scale for regional cybersecurity boutiques. Long-term viability favors platform players with Brussels-backed public sector pipelines and recurring managed service revenue. The signal to watch is EU AI Act implementation timelines intersecting with CySEC licensing renewals, which will force algorithmic governance investments among electronic money institutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Orchestration Partnership | Combines Cyta's domestic infrastructure with hyperscaler elasticity for sovereign-compliant deployments. |
| NIS2 Compliance Advisory Service Launch | Captures premium pricing from Limassol fintech clusters facing directive deadlines. |
| EU Recovery Fund Project Capture | Secures multi-year revenue visibility through Brussels-backed public sector digitalization. |
| Maritime IoT Platform Integration | Addresses Larnaca shipping operators' vessel-to-shore data analytics requirements. |
| AI Act Preparation Consulting | Targets electronic money institutions harmonizing Cypriot licensing with Brussels transparency standards. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers at Limassol investment funds, CySEC regulatory affairs leads, and public sector digitalization directors with secondary validation. Sources included SEC filings from listed technology vendors, hyperscaler capex disclosures, EU Recovery Fund allocation databases, and CySEC licensing registers. Bottom-up project pipelines and top-down macroeconomic indicators underwent cross-triangulation to anchor market sizing.
Historical reference periods established baseline procurement patterns across government framework agreements and enterprise unbundling trends. The projection horizon incorporates modeled segmentation across service type, deployment model, end user, and technology maturity curves. CAGRs were derived from elasticity analysis of EU funding inflows and regulatory compliance cost trajectories. Forecast inputs include NIS2 transposition timelines and EU AI Act implementation schedules specific to Cyprus's fintech licensing regime.
The model assumes a particular technology adoption path; alternative pathways for generative AI governance would alter the outlook for compliance advisory services. Forecasts reflect assumptions about EU funding continuity and submarine cable resilience. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Israel ICT Market
Analytics
Germany Geospatial Analytics Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
United Kingdom Geospatial Imagery Analytics Market
Analytics
Advanced Analytics Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
HR Analytics Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Middle East Geospatial Analytics Market
Analytics
Global Digital Intelligence Platform Market
Analytics
UK Video Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Weather Data Services Market
Analytics
UAE Geospatial Analytics Market
Analytics
Sales Intelligence Market
Analytics
Global Sales Performance Management Market