
 Global Network Analytics Market | 2026-2036
Global Network Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Analytics Market Foresight
Enterprise buyers are unwinding legacy telecom-centric procurement as cloud-native service providers gain budget share for network observability. Cisco Systems leverages its installed base of routing hardware to embed analytics at the network edge. Broadcom sustains competitive pressure through silicon-level telemetry integration across switching portfolios. Juniper Networks differentiates with intent-based networking platforms that automate anomaly detection in multi-cloud environments.
Network analytics encompasses software systems that ingest packet-level metadata, flow records, and SNMP telemetry to model traffic patterns, predict congestion, and isolate security incidents in real time. These systems process NetFlow, IPFIX, and sFlow feeds at line rates exceeding 100 Gbps to maintain operational visibility across distributed infrastructures. Cloud-based deployment is capturing the fastest expansion as organizations abandon capital-intensive appliance refresh cycles for elastic SaaS consumption models. Security analytics solutions command premium positioning within the solution stack, reflecting enterprise prioritization of threat detection over passive performance monitoring. Managed service providers represent an emerging demand vector, outsourcing network intelligence to specialists rather than building internal competencies.
FCC net neutrality rulings in the United States, GDPR data governance requirements in Europe, and China's GB standards for critical information infrastructure collectively reshape product architecture and geographic market access for network analytics vendors. The EU AI Act imposes additional conformity obligations on automated network decision systems that classify traffic or enforce policies without human review. Stakeholders must evaluate whether their analytics architectures satisfy emerging cross-border data localization rules before committing to centralized cloud processing strategies.
Market Dynamics
Telecom operators are dismantling hardware-centric observability stacks as cloud-native telemetry pipelines absorb capital budgets previously reserved for appliance refresh cycles. This infrastructure pivot compresses vendor margins while elevating software-defined analytics platforms.
Growth Catalysts
- 5G Standalone Core Deployments:Mobile network operators in South Korea, Japan, and Germany are instrumenting packet cores with real-time analytics to manage network slicing orchestration.
- GDPR Article 35 Impact Assessments:European enterprises must document automated decision systems, creating mandatory procurement of explainable traffic classification tools.
- Federal Zero-Trust Mandates:United States government agencies require continuous network verification, driving agency-level contracts for microsegmentation analytics.
Market Restraints
- Silicon Supply Concentration:Merchant switch ASIC production concentrates among three foundry-dependent suppliers, creating 18-month lead time volatility for telemetry-enabled hardware.
- EU AI Act Conformity Costs:Automated policy enforcement systems face third-party audit requirements that add 14-22% to platform development budgets.
- Skilled Workforce Scarcity:Packet-level analysis expertise pools narrowly in Tel Aviv, Bangalore, and San Jose metro clusters, inflating specialist compensation.
Strategic Opportunities
- India Critical Infrastructure Protection:CEA cybersecurity directives for power grid operators create first-mover advantage for anomaly detection vendors establishing local data residency.
- Observability-DevOps Convergence:Site reliability engineering teams are merging network telemetry with application performance monitoring, opening unified platform contracts.
- Managed Detection and Response Extension:Security service providers are bundling network analytics into MDR offerings, creating indirect channel volume.
Industry Challenges
- Multivendor Correlation Complexity:Enterprises operating Cisco, Arista, and Juniper equipment simultaneously struggle to normalize disparate telemetry formats into coherent incident timelines.
- Cloud Egress Cost Volatility:NetFlow export to centralized SaaS analytics platforms accumulates unpredictable cross-region data transfer charges that erode budget predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Analytics Market |
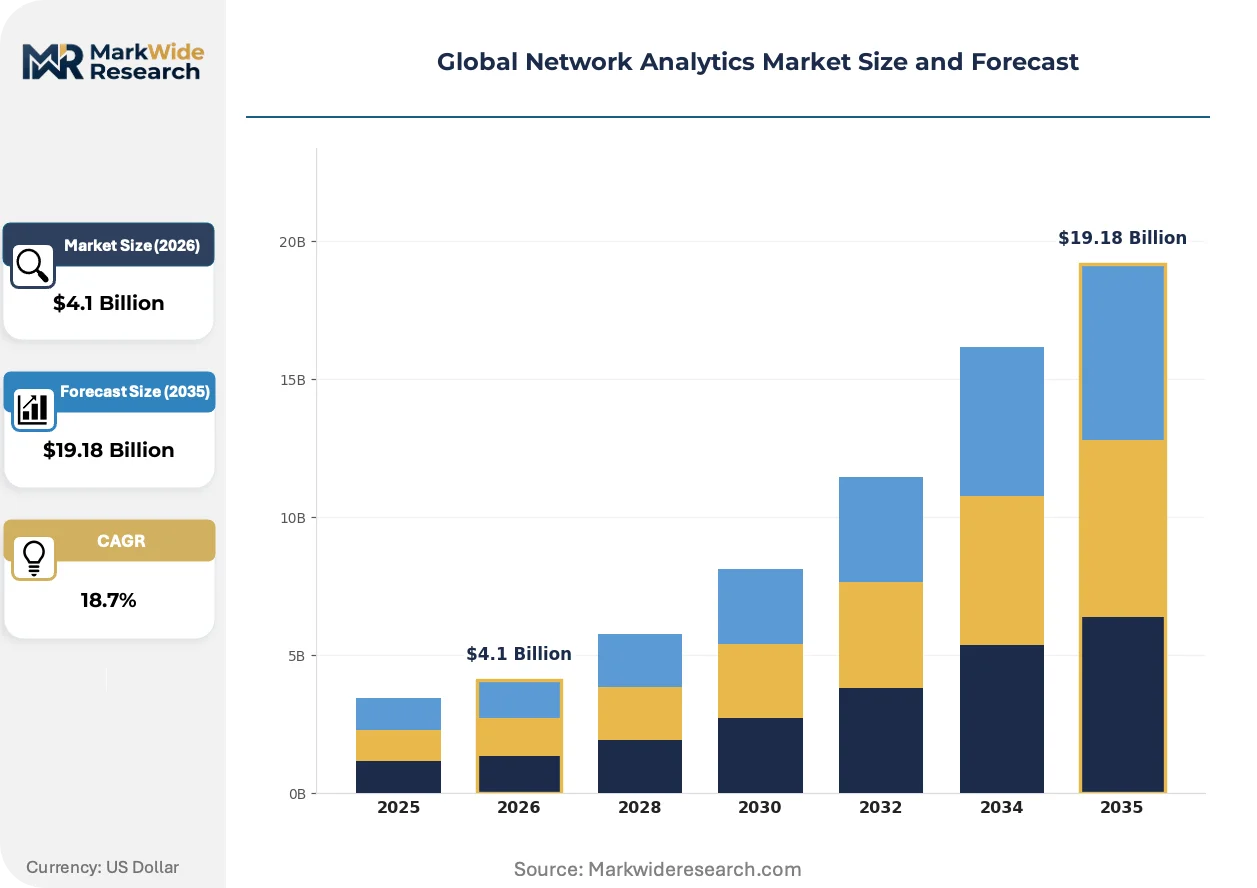
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $19.18 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge, Distributed Solution: Traffic Analysis, Performance Monitoring, Fault Management, Security Analytics, Capacity Planning Use Case: Bandwidth Optimization, Threat Detection, User Experience Management, Network Compliance, Resource Allocation End User: Telecommunication Providers, Internet Service Providers, Data Centers, Managed Service Providers, Enterprises |
| Companies Covered | Cisco Systems, Inc., Broadcom, Inc., IBM Corporation, Hewlett Packard Enterprise Development LP, Juniper Networks, Inc., Huawei Technologies Co., Ltd., Ciena Corporation, Fortinet, Inc., SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Analytics Market Shifts & Advancements
eBPF kernel instrumentation is collapsing the boundary between host and network observability, enabling single-agent architectures that previously required separate endpoint and traffic analysis tools.
In-memory stream processing engines are displacing batch-oriented analytics architectures that relied on hours-old flow records. Financial services institutions in Singapore and Switzerland deploy these engines for sub-second fraud detection. Latency compression is forcing incumbent vendors to rewrite data plane software or cede high-frequency use cases.
The EU AI Act's risk classification framework is redefining product roadmaps for automated traffic shaping systems. Vendors must now embed human-in-the-loop checkpoints for policy decisions affecting critical infrastructure. German automotive manufacturers and French energy utilities are piloting explainable classification models to preempt regulatory scrutiny.
Enterprise buyers are consolidating network and security operations center tooling under single procurement umbrellas. Mid-market manufacturers in the United States Midwest and automotive suppliers in Stuttgart are rejecting point solutions in favor of platform contracts spanning visibility, detection, and response. Vendor sales cycles lengthen as economic buyers demand cross-functional ROI documentation.
Global Network Analytics Market Segmentation
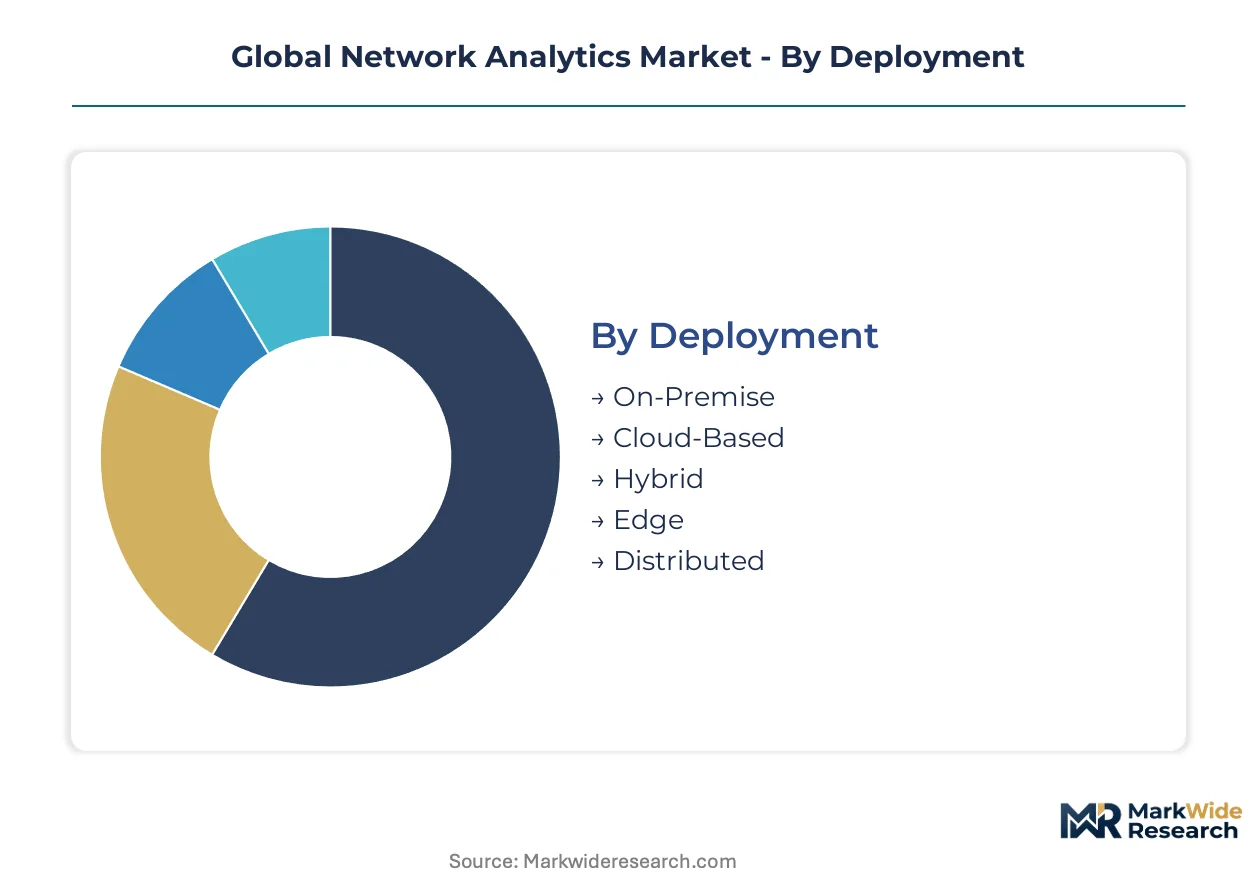
Network analytics procurement diverges sharply across deployment architectures and operational maturity levels. Buyers select modalities based on telemetry latency requirements, data sovereignty constraints, and existing infrastructure amortization schedules.
Deployment:
Channel mix varies by latency sensitivity and capital cycle positioning, with hyperscaler marketplaces capturing cloud-native workloads while systems integrators retain on-premise complexity.
- On-Premise:Hardware appliances process NetFlow and IPFIX feeds within customer-controlled data centers. Financial services institutions in Switzerland and defense contractors in the United States maintain these deployments to satisfy data residency mandates.
- Cloud-Based:SaaS platforms ingest telemetry through agentless API integrations, eliminating capital expenditure cycles. Elastic consumption models attract mid-market enterprises in Germany and Singapore seeking to avoid appliance refresh commitments.
- Hybrid:Split architectures retain sensitive packet analysis on-premise while offloading historical trending to cloud reservoirs. This configuration dominates among European manufacturers navigating GDPR Article 44 transfer restrictions.
- Edge:Lightweight analytics engines deploy at 5G base stations and factory floors to enable sub-50 millisecond response times. South Korean mobile operators and Japanese automotive plants drive specialized procurement here.
- Distributed:Federated learning architectures train models across geographically separated nodes without centralizing raw telemetry. Research consortia in the Netherlands and energy grid operators in Australia pilot these privacy-preserving deployments.
On-Premise dominates installed base. Cloud-Based is where expansion concentrates.
Solution:
Application context determines solution prioritization, with security-led procurement commanding premium pricing against operational efficiency use cases.
- Traffic Analysis:Deep packet inspection and flow correlation engines classify application signatures across encrypted and plaintext streams. Telecommunication providers in Japan instrument these tools to enforce quality-of-service tiers for network slicing.
- Security Analytics:Behavioral baselining and threat intelligence integration detect lateral movement and data exfiltration patterns. United States federal agencies mandate these capabilities under zero-trust architecture directives.
- Performance Monitoring:Synthetic transaction testing and path analysis visualize end-to-end service delivery. E-commerce platforms in India and logistics operators in Germany rely on these for customer-facing SLA enforcement.
- Fault Management:Root cause analysis engines correlate syslog events with topology changes to accelerate mean-time-to-repair. Legacy enterprise networks in France and Italy maintain substantial deployments.
- Capacity Planning:Predictive models forecast bandwidth exhaustion using seasonal traffic patterns and growth projections. Cloud service providers in Ireland and Singapore utilize these for data center expansion timing.
Security Analytics commands pricing premiums. Traffic Analysis is climbing the fastest.
Use Case:
Volume concentration tracks infrastructure investment cycles, with bandwidth-intensive applications preceding security hardening in procurement sequences.
- Bandwidth Optimization:Traffic shaping and compression algorithms reduce transit costs for content-heavy workloads. Video streaming platforms in Brazil and gaming distributors in South Korea deploy these aggressively.
- Threat Detection:Anomaly detection identifies command-and-control communications and cryptocurrency mining within east-west traffic. Healthcare networks in the United States and critical infrastructure in Saudi Arabia prioritize this use case.
- User Experience Management:Application response time decomposition isolates degradation to network, server, or client tiers. SaaS providers in Sweden and financial exchanges in Switzerland optimize here.
- Network Compliance:Automated policy verification ensures segmentation and access controls satisfy regulatory frameworks. EU AI Act conformity drives European adoption.
- Resource Allocation:Dynamic bandwidth reservation matches network slices to application priority levels. 5G standalone core deployments in Germany and Australia utilize these capabilities.
Bandwidth Optimization holds legacy volume. Threat Detection is gaining share fastest.
End User:
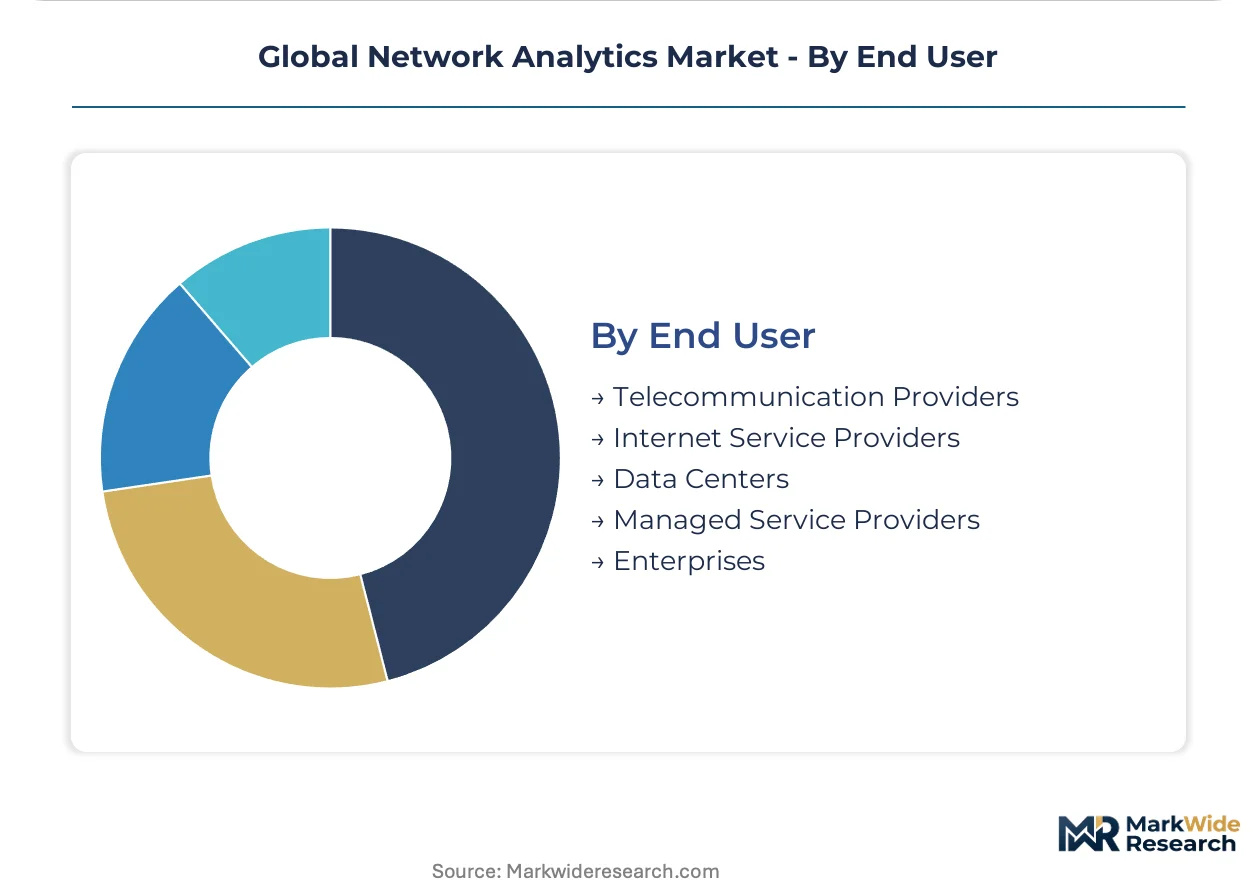
Customer type shapes packaging and support models, with service provider accounts demanding carrier-grade scale while enterprises prioritize integration simplicity.
- Telecommunication Providers:National carriers instrument packet cores and radio access networks for subscriber quality management. SK Telecom, Deutsche Telekom, and Verizon represent reference deployments.
- Data Centers:Colocation and hyperscale facilities monitor interconnection fabrics and cross-connect performance. Cloud regions in Virginia, Frankfurt, and Mumbai concentrate procurement.
- Managed Service Providers:Outsourced network operations teams aggregate multi-tenant analytics for mid-market clients. British and Australian MSPs expand these offerings fastest.
- Enterprises:Manufacturing, healthcare, and financial institutions build internal observability competencies. German automotive suppliers and United States hospital systems represent mature adopters.
- Internet Service Providers:Regional broadband operators optimize last-mile congestion and peering relationships. Indian and Indonesian ISPs drive emerging market volume.
Telecommunication Providers anchor revenue concentration. Managed Service Providers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ashburn-Loudoun data center corridor in Northern Virginia anchors North American network analytics procurement, processing over 70% of global internet traffic through its fiber-dense infrastructure. This concentration shapes vendor deployment strategies and federal contracting patterns.
United States
Federal zero-trust architecture mandates from NIST and OMB drive agency-level procurement for microsegmentation analytics. FCC net neutrality rulings reshape how carriers instrument traffic management systems. The Northern Virginia data center cluster concentrates hyperscaler demand for real-time flow analysis at 100+ Gbps line rates.
Germany
Deutsche Telekom's 5G standalone core deployments instrument packet cores with real-time analytics for network slicing orchestration. The EU AI Act imposes conformity obligations on automated traffic classification systems, forcing explainability features into product roadmaps. Stuttgart's automotive supplier ecosystem pilots human-in-the-loop checkpoints for policy enforcement.
South Korea
SK Telecom's nationwide 5G infrastructure demands edge-deployed analytics engines for sub-50 millisecond response times. The country's Critical Information Infrastructure Protection Act mandates anomaly detection for power and transport networks. Seoul's Pangyo Techno Valley hosts specialized telemetry processing clusters serving gaming and streaming platforms.
Japan
NTT Docomo's radio access network instrumentation prioritizes subscriber quality management through predictive congestion modeling. METI's cybersecurity framework for critical infrastructure drives procurement of behavioral baselining tools. Nagoya's automotive manufacturing corridor deploys factory-floor analytics for deterministic network performance.
India
CEA cybersecurity directives for power grid operators create first-mover advantage for vendors establishing local data residency. TRAI's quality-of-service regulations mandate transparent traffic management disclosure by broadband providers. Mumbai's financial district and Bangalore's technology corridor concentrate enterprise demand for cloud-native observability platforms.
Global Network Analytics Market Competitive Landscape
Concentration sits with infrastructure-embedded incumbents who leverage routing and switching hardware relationships to bundle analytics software. The vendor landscape tiers into three strategic archetypes: silicon-integrated telemetry providers, intent-based networking platform vendors, and cloud-native observability specialists. Competitive moves center on API ecosystem expansion and managed service provider channel development rather than direct enterprise sales acceleration.
Within the infrastructure-embedded tier, Cisco Systems exemplifies the hardware-leverage archetype through its routing installed base, while Broadcom occupies a position representing silicon-level telemetry integration. Juniper Networks anchors the intent-based networking segment with platforms automating anomaly detection. These three entities collectively represent the competitive fault lines determining procurement outcomes across telecommunication providers and federal agencies.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Broadcom, Inc. |
| IBM Corporation |
| Hewlett Packard Enterprise Development LP |
| Juniper Networks, Inc. |
| Huawei Technologies Co., Ltd. |
| Ciena Corporation |
| Fortinet, Inc. |
| SAS Institute Inc. |
| Others |
Supply & Pricing Matrix
Eighteen-month lead times for merchant switch ASICs concentrate procurement leverage among three foundry-dependent suppliers, compressing vendor margins while elevating pricing power for telemetry-enabled hardware. This supply rigidity feeds directly into SaaS platform economics, where cloud-native providers absorb capital budget shifts through elastic consumption models that bypass appliance refresh cycles entirely.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with security analytics commanding premiums against passive performance monitoring tiers. Price differentiation rests on certification grade—EU AI Act conformity for automated policy enforcement—and volume scale for multi-tenant MSP deployments. Cost compression in the standard tier is intensifying because hyperscaler marketplaces disintermediate traditional channel markups. Mid-market enterprises exhibit highest price sensitivity, while federal agencies under zero-trust mandates show lowest elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes inflate inbound logistics costs for silicon-dependent hardware components. Manufacturing concentrates in Taiwan, South Korea, and the United States for merchant switch ASICs. Raw material dependencies span silicon wafers, specialized memory modules, and high-speed optical transceivers. Single-source vulnerability in foundry capacity creates structural risk. Distribution runs through hyperscaler marketplaces for cloud-native workloads and systems integrators for on-premise complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk classification framework for automated network decision systems creates a regulatory inflection that will reshape competitive positioning across the analysis window.
For Market Incumbents: Shield embedded hardware relationships through silicon-level telemetry integration that cloud-native entrants cannot replicate without foundry partnerships. Deepen backward integration into ASIC design to secure supply continuity against foundry concentration. Prioritize certification investment for EU AI Act conformity to maintain access to European critical infrastructure procurement. For New Entrants and Emerging Players: CE marking fast-track for explainable traffic classification tools opens immediate access to German automotive and French energy utility pilots. White-space sits with managed service providers in British and Australian markets, where multi-tenant analytics outsourcing expands fastest. Target edge-deployed analytics for 5G standalone core deployments in South Korea and Japan, where sub-50 millisecond latency requirements favor lightweight architectures. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because enterprise buyers are unwinding point-solution procurement in favor of unified network-security operations center contracts. Acquisition targets should feature eBPF-based single-agent architectures that collapse host-network observability boundaries. Watch for hyperscaler marketplace traction as the signal indicating which cloud-native entrants achieve escape velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified network-security operations center tooling captures enterprise procurement consolidation in Stuttgart and the United States Midwest. |
| Strategic Partnership | Managed detection and response bundling with security service providers creates indirect channel volume for telemetry vendors. |
| Acquisition of Specialist Firm | eBPF kernel instrumentation expertise collapses host-network observability boundaries faster than organic development cycles permit. |
| Geographic Expansion | Local data residency establishment in India captures CEA cybersecurity directives for power grid anomaly detection. |
| Product Launch | Human-in-the-loop checkpoints for EU AI Act conformity preempt regulatory scrutiny in German automotive manufacturing corridors. |
Research Methodology
Desk research of hyperscaler capex disclosures, SEC filings, and telecommunications regulatory filings preceded structured interviews with network operations executives, cloud infrastructure architects, and managed service provider portfolio directors. Primary fieldwork with these stakeholders validated secondary estimates of deployment architecture shifts and procurement timeline compression. Bottom-up segment sizing triangulated against top-down market envelope checks from trade association data and customs records.
Variance decomposition across deployment model, organization size, and vertical adoption pattern anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated 5G standalone core deployment schedules, federal zero-trust architecture implementation timelines, and EU AI Act conformity cost assumptions for automated policy enforcement systems.
Underlying assumptions cover sustained hyperscaler cloud expansion, stable foundry capacity allocation for merchant silicon, and progressive EU AI Act enforcement, with deviation risk concentrated in semiconductor supply volatility and cross-border data localization rule changes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
India Geospatial Analytics Market
Analytics
Global Marketing Attribution Software Market
Analytics
Data Visualization Market
Analytics
Global Subscription Analytics Software Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Location Analytics Market
Analytics
UK Geospatial Analytics Market
Analytics
Capacity Management Analytics Market
Analytics
Pandemic Analytics Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Prescriptive Analytics Market
Analytics
Workforce Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
Brazil Big Data Analytics Market
Analytics
Analytics As a Service (Aaas) Market