
 Cognitive Analytics Solutions Market | 2026-2036
Cognitive Analytics Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Analytics Solutions Market Outlook
The EU AI Act is rebalancing compliance budgets across the cognitive analytics value chain, forcing vendors to embed conformity-by-design into platform architectures. IBM Corporation leverages its Watson governance toolkit to anchor enterprise trust in regulated sectors. Microsoft Corporation sustains competitive density through Azure AI's integrated responsible-AI dashboards. Amazon Web Services differentiates via specialized healthcare and financial services modules that preempt audit scrutiny.
Cognitive analytics solutions fuse machine learning, natural language processing, and predictive modeling to extract actionable intelligence from unstructured enterprise data streams, typically processing petabyte-scale inputs through distributed cloud architectures. Their primary purpose centers on automating complex decision workflows in customer service, risk assessment, and operational forecasting. Software and platform segments dominate current revenue as enterprises prioritize embedded analytics over standalone services, while edge deployment configurations represent the fastest-expanding infrastructure category as latency-sensitive manufacturing and retail use cases multiply. Natural language processing applications command premium positioning within the technology stack due to specialized talent scarcity and enterprise demand for conversational interfaces.
GDPR, the EU AI Act, and HIPAA collectively constrain how cognitive analytics platforms handle personal data, mandating explainability thresholds that elevate engineering costs for cross-border deployments. The FDA and EMA impose additional validation requirements on clinical decision-support tools, segmenting market access between regulated and unregulated application domains. Stakeholders must monitor emerging algorithmic accountability legislation in multiple jurisdictions to anticipate compliance-driven procurement shifts.
Market Dynamics
The EU AI Act's conformity requirements are forcing cognitive analytics vendors to rebuild platform architectures around explainability-by-design, diverting engineering resources from feature development toward audit-ready documentation systems.
Growth Catalysts
- Diagnostic Pattern Recognition:Healthcare providers deploy cognitive analytics for radiology and pathology workflows, with HIPAA-mandated data security accelerating procurement of on-premise inference engines.
- GDPR Article 22:Automated decision-making restrictions in Europe create procurement pull for human-in-the-loop cognitive systems that satisfy legal contestability requirements.
- Petabyte-Scale Unstructured Data:Manufacturing enterprises generate sensor and maintenance logs that exceed conventional BI capacity, forcing adoption of NLP-enabled analytics platforms.
Market Restraints
- GPU Supply Concentration:Training infrastructure for large language models depends on advanced semiconductor fabrication concentrated in Taiwan and South Korea, creating input cost volatility and procurement delays.
- Cross-Border Data Localization:China's Personal Information Protection Law and Russia's data sovereignty requirements fragment cloud deployment architectures, elevating compliance engineering costs.
- Explainability Thresholds:The EU AI Act's risk-classification system mandates algorithmic transparency for high-risk applications that current neural network architectures cannot satisfy without accuracy trade-offs.
Strategic Opportunities
- Edge Deployment Configurations:Latency-sensitive retail and manufacturing use cases in Germany and Japan are driving demand for on-device inference that reduces cloud egress costs.
- Converged NLP-Computer Vision:Multimodal cognitive systems that process clinical notes alongside medical imaging are opening diagnostic applications previously requiring separate vendor relationships.
- India's Digital Health Mission:The country's national health stack creates procurement pathways for cognitive analytics vendors that achieve CDSCO software-as-medical-device registration.
Industry Challenges
- Specialized Talent Scarcity:MLOps engineers capable of deploying production-grade transformer models command compensation premiums that compress vendor margins.
- Legacy System Integration:Enterprise ERP and clinical data repositories use incompatible data schemas that require expensive middleware development before cognitive analytics deployment.
- FDA 510(k) Validation Timelines:Clinical decision-support tools face extended review cycles that delay revenue recognition and elevate regulatory capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Analytics Solutions Market |
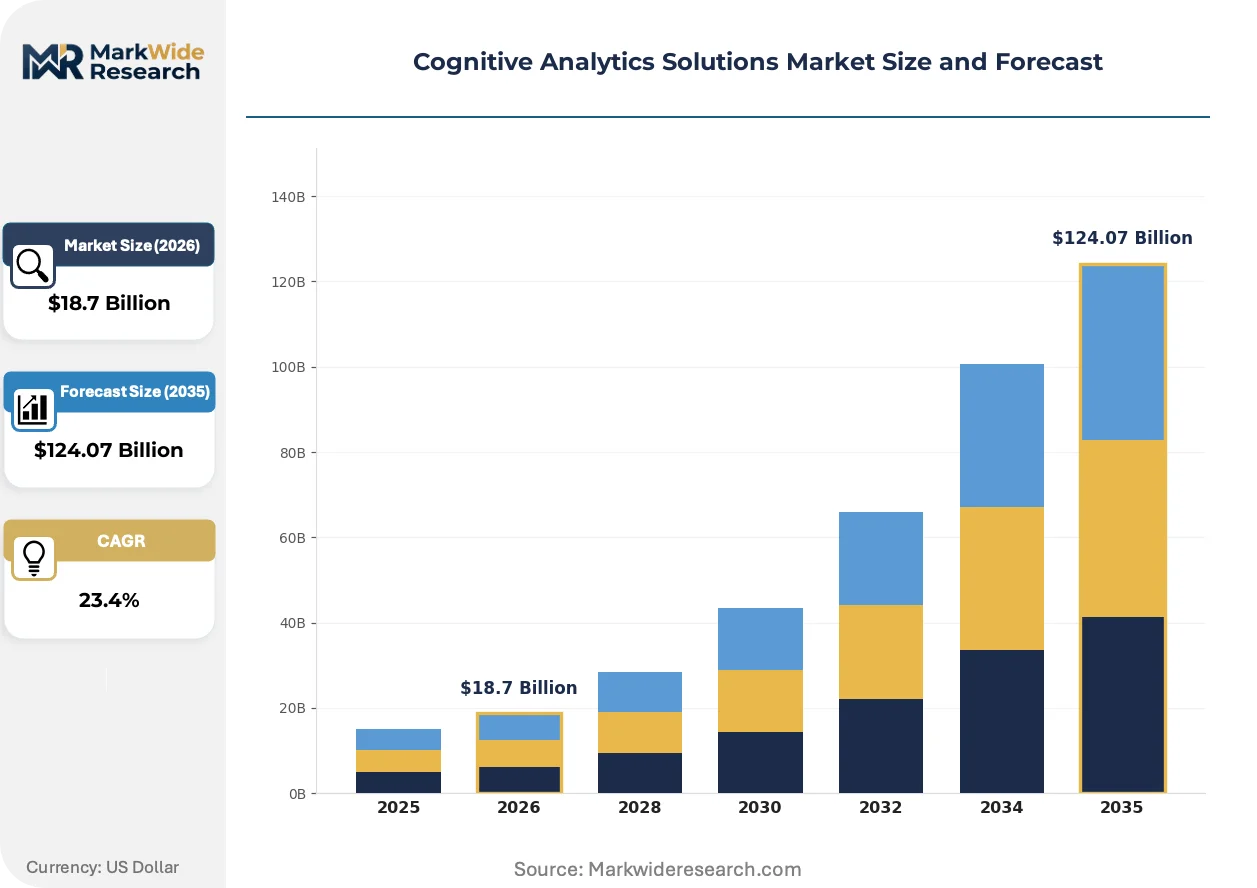
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Service, Application End User: Retail, Healthcare, Manufacturing, BFSI Deployment: On-Premises, Cloud, Hybrid, Edge Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Others |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAS Institute Inc., Cisco Systems Inc., Amazon Web Services, Google LLC, Hewlett Packard Enterprise, Accenture plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Analytics Solutions Market Strategic Shifts
Foundation model architectures are compressing development cycles for cognitive analytics applications, enabling vendors to fine-tune pre-trained systems rather than building domain-specific models from initialization.
Retrieval-augmented generation is overtaking fine-tuning as the dominant adaptation method for enterprise knowledge bases. Healthcare systems and financial services firms adopt RAG pipelines to ground LLM outputs in proprietary document corpora without exposing training data. This approach is overtaking parameter-efficient fine-tuning in procurement evaluations because it preserves model provider liability shields while improving factual accuracy.
The EU AI Act's risk-tier classification system is restructuring product roadmaps across the cognitive analytics value chain. High-risk application categories—including credit scoring and recruitment tools—now require conformity assessments that add documentation burdens. Vendors serving regulated European sectors are responding by bifurcating product lines into auditable and non-auditable variants.
Enterprise buyers are consolidating vendor relationships around integrated platform stacks rather than point solutions. Procurement committees in United States healthcare systems now require cognitive analytics modules to demonstrate interoperability with existing EHR infrastructure. This pattern is most visible in hospital networks modernizing data infrastructure under value-based care contracts.
Cognitive Analytics Solutions Market Segmentation
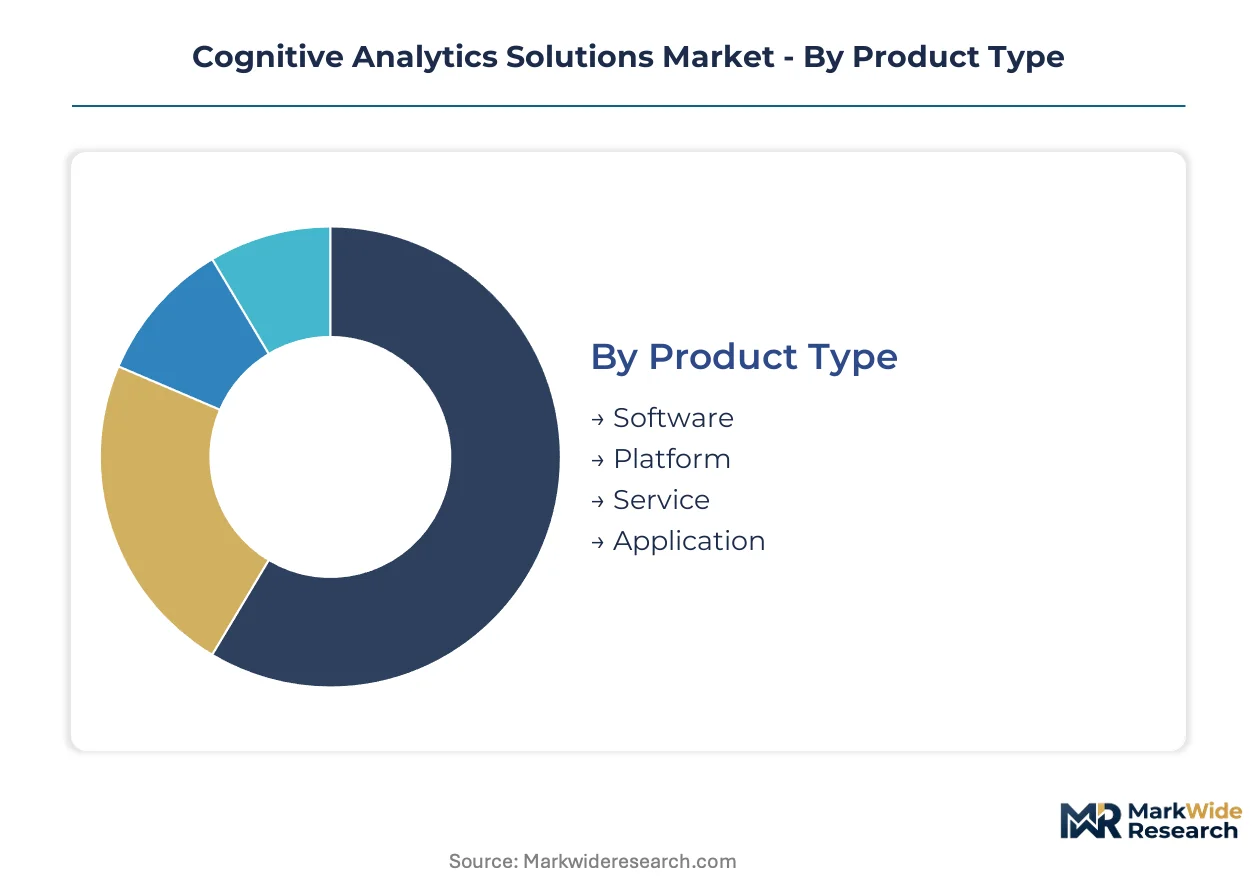
Cognitive analytics solutions fragment across four structural dimensions that determine procurement economics and implementation complexity. Each segmentation axis carries distinct upgrade-cycle dynamics, vendor margin profiles, and integration requirements that shape enterprise buying behavior.
Product Type:
Replacement cycles vary dramatically across product tiers, with platform renewals occurring every 3-5 years versus annual service renegotiations.
- Software:Standalone cognitive analytics applications deploy via perpetual licensing or subscription models, processing structured and unstructured data through embedded ML pipelines. Healthcare systems in the United States prioritize HIPAA-compliant software modules for clinical decision support, driving procurement of on-premise inference engines with audit trails.
- Platform:Integrated development environments combine data ingestion, model training, and deployment orchestration within unified architectures. Enterprise buyers in Germany and Japan modernizing ERP infrastructure favor platform consolidation over point solutions to reduce middleware complexity.
- Service:Managed implementation and support offerings address talent scarcity through external MLOps expertise.
- Application:Pre-configured vertical solutions target specific use cases without customization overhead.
Volume placements concentrate in Platform; the faster expansion belongs to Application.
End User:
Customer-type segmentation reveals divergent technical maturity and procurement authority structures across sectors.
- Healthcare:Diagnostic pattern recognition for radiology and pathology workflows demands FDA-validated algorithms and HIPAA-mandated data security. Hospital networks under value-based care contracts in the United States accelerate procurement of clinical decision-support tools.
- BFSI:Credit scoring and fraud detection applications face EU AI Act high-risk classification, forcing conformity-by-design investments. European banks prioritize human-in-the-loop architectures to satisfy GDPR Article 22 contestability requirements.
- Retail:Customer sentiment analysis and demand forecasting applications process petabyte-scale transaction logs.
- Manufacturing:Predictive maintenance and quality control systems integrate sensor data with NLP-enabled maintenance logs.
Healthcare captures the largest deployment base; BFSI shows the steepest compliance-driven upgrade trajectory.
Deployment:
Architecture choices trade latency performance against capital intensity and regulatory exposure.
- Cloud:Scalable compute resources support training workloads for large language models through distributed GPU clusters. Enterprise buyers prioritize cloud for non-regulated workloads where data residency requirements permit.
- Edge:On-device inference reduces latency for manufacturing quality control and retail inventory management. Germany and Japan drive demand for edge configurations that minimize cloud egress costs.
- On-Premises:Air-gapped deployments satisfy data sovereignty requirements in China and Russia.
- Hybrid:Split architectures train models in cloud environments while executing inference locally.
Cloud retains the dominant volume position; edge configurations are climbing the fastest.
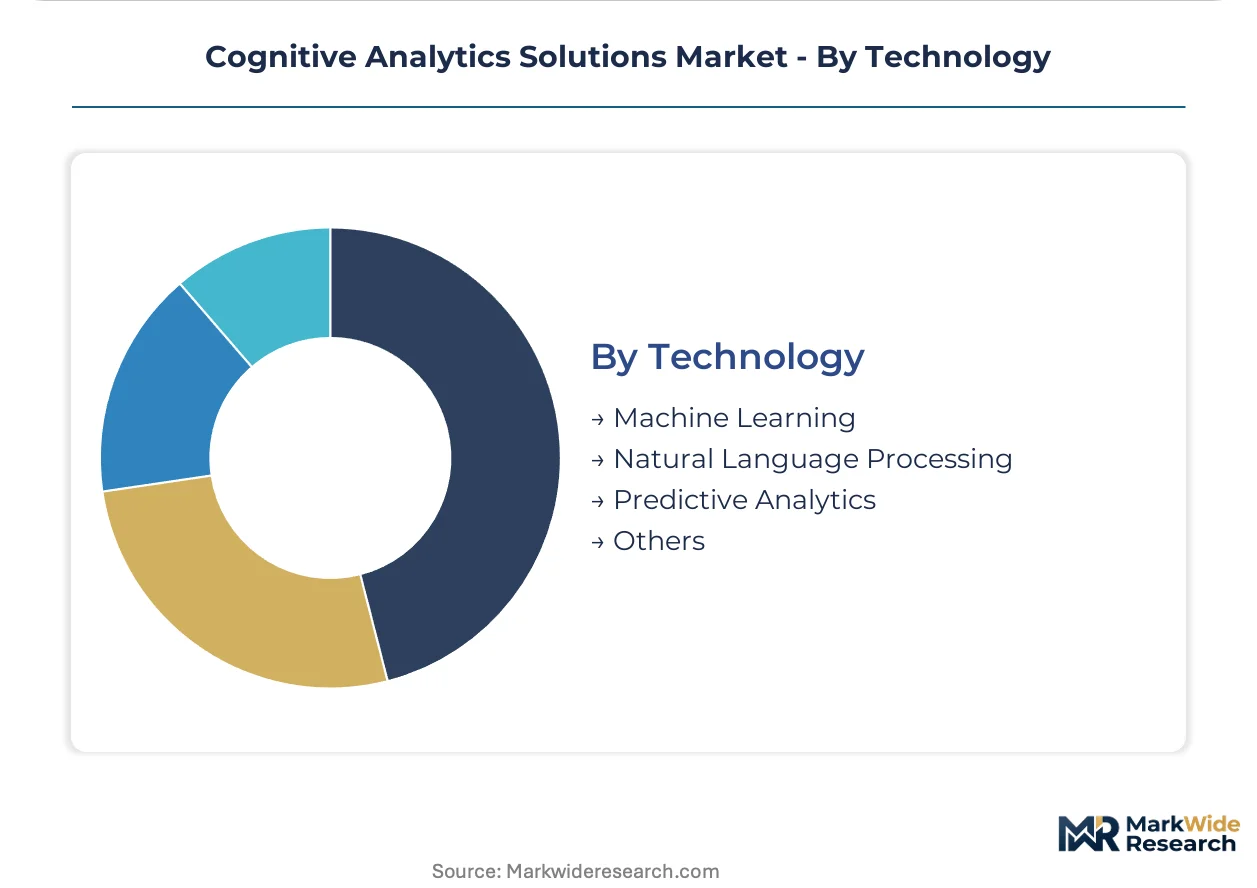
Technology:
Capability-layer segmentation reflects talent scarcity premiums and integration complexity differentials.
- Natural Language Processing:Transformer-based systems extract intelligence from clinical notes, legal contracts, and maintenance logs. Specialized NLP engineering talent commands compensation premiums that elevate platform pricing.
- Machine Learning:Supervised and unsupervised learning pipelines underpin predictive maintenance, demand forecasting, and risk scoring applications across manufacturing and BFSI sectors.
- Predictive Analytics:Statistical modeling tools forecast operational outcomes with lower computational overhead than deep learning alternatives.
- Others:Computer vision and multimodal fusion technologies enable converged diagnostic systems processing imaging alongside text.
NLP commands premium positioning; multimodal fusion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and similar innovation zones across the United States concentrate cognitive analytics R&D through federal tax incentives and university partnerships. Enterprise procurement clusters around these zones as vendors co-locate with healthcare systems and financial institutions modernizing data infrastructure.
United States
Hospital networks under value-based care contracts accelerate procurement of clinical decision-support tools. HIPAA mandates air-gapped deployments for protected health information, elevating on-premise inference engine demand. The Boston-Cambridge corridor hosts concentrated NLP talent pools serving pharmaceutical and biotech clients.
Germany
Industrial manufacturers in Baden-Württemberg deploy predictive maintenance systems processing sensor and maintenance logs. The EU AI Act forces conformity-by-design investments for high-risk applications. Munich-based automotive suppliers integrate cognitive analytics into quality control workflows.
United Kingdom
Financial services firms in London prioritize human-in-the-loop architectures to satisfy GDPR Article 22 contestability requirements. The Financial Conduct Authority scrutinizes algorithmic trading systems. Edinburgh and Manchester emerge as secondary hubs for regulatory technology development.
Japan
Manufacturing enterprises in the Chubu region generate petabyte-scale unstructured data exceeding conventional BI capacity. METI promotes AI adoption through regulatory sandboxes for industrial applications. Tokyo-based trading houses deploy NLP-enabled platforms for contract analysis.
India
The Digital Health Mission creates procurement pathways for cognitive analytics vendors achieving CDSCO software-as-medical-device registration. State-level IT parks in Karnataka and Telangana host development centers serving global healthcare clients. Hyderabad and Bengaluru concentrate MLOps engineering talent.
Cognitive Analytics Solutions Market Competitive Environment
United States technology conglomerates anchor the platform tier; European specialists hold positions in regulated vertical applications. The vendor base fragments across three tiers: hyperscale cloud providers with integrated AI stacks, enterprise software incumbents with governance toolkits, and vertical specialists with domain-specific validation. Strategic moves center on conformity-by-design architecture investments and edge deployment capability expansion.
Within the enterprise software tier, IBM Corporation and Microsoft Corporation exemplify platform consolidation strategies. IBM Corporation leverages governance toolkits to anchor enterprise trust in regulated sectors. Microsoft Corporation sustains competitive density through integrated responsible-AI dashboards. Amazon Web Services occupies a position among cloud-native providers differentiating via specialized healthcare and financial services modules.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAS Institute Inc. |
| Cisco Systems Inc. |
| Amazon Web Services |
| Google LLC |
| Hewlett Packard Enterprise |
| Accenture plc |
| Others |
Value Chain & Pricing Dynamics
GPU cluster provisioning costs cascade through cognitive analytics platform tiers, with NVIDIA H100 allocation premiums compressing margins for training-intensive workloads while edge inference hardware subsidies from Taiwan-based manufacturers subsidize entry-level deployment pricing for latency-sensitive manufacturing buyers in Germany and Japan.
Pricing Analysis
Short lead-time premiums dominate enterprise procurement negotiations, with healthcare systems in the United States paying surcharges for FDA-validated modules delivered within ninety-day windows versus standard six-month implementation cycles. Three-tier pricing structure across premium, standard, and economy levels separates air-gapped on-premise deployments with full audit documentation from cloud-native SaaS tiers with shared infrastructure. Cost compression in the economy tier is intensifying because hyperscaler volume commitments are commoditizing baseline NLP capabilities. Hospital purchasing committees exhibit highest price sensitivity, while BFSI compliance officers prioritize conformity certification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing for advanced AI accelerator fabrication, creating procurement bottlenecks that propagate through training infrastructure lead times. Supply concentrates in Taiwan, South Korea, and the United States for GPU and specialized AI silicon, while memory module production draws from South Korea and China. Supply chain risk centers on export control restrictions affecting high-bandwidth memory and advanced packaging equipment. Distribution runs through direct enterprise sales teams for platform-tier contracts and hyperscaler marketplaces for self-service developer adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
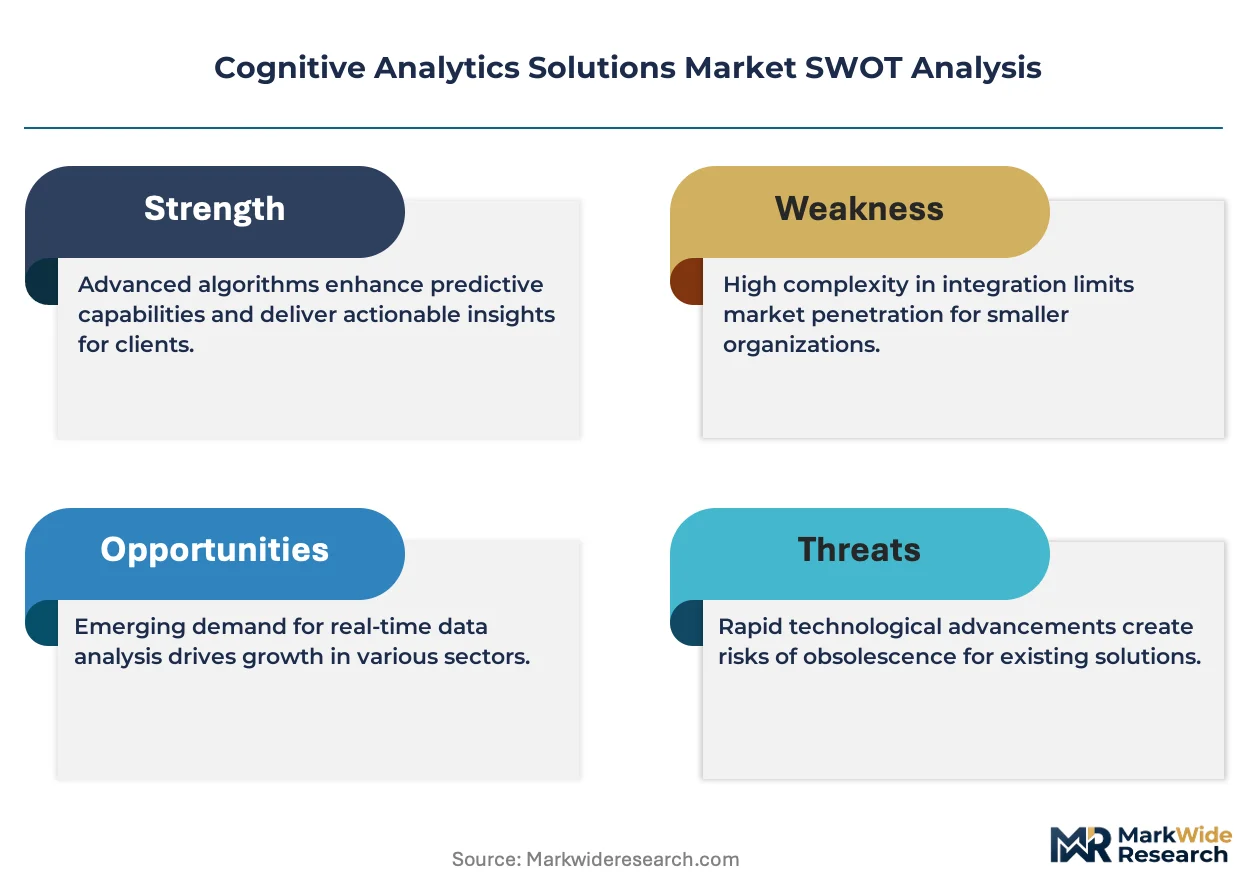
Cognitive analytics platform consolidation is accelerating as EU AI Act compliance engineering costs force subscale vendors toward strategic exit, rewarding incumbents with governance-ready architectures and punishing point-solution providers lacking audit documentation capabilities.
For Market Incumbents: Extend conformity-by-design investments into pre-validated vertical modules that preempt FDA and EMA scrutiny, locking out emerging competitors lacking regulatory capital reserves. Acquire edge deployment specialists in Germany and Japan to capture manufacturing latency requirements before cloud-native challengers adapt. The priority lever rests on embedding responsible-AI documentation into platform APIs, creating switching costs that cement multi-year enterprise relationships. For New Entrants and Emerging Players: Multimodal diagnostic systems processing clinical notes alongside medical imaging represent the most penetrable white-space, as incumbent platforms remain siloed between NLP and computer vision engineering teams. Target India's Digital Health Mission procurement pathways by achieving CDSCO software-as-medical-device registration ahead of global competitors. A channel partnership strategy with established hospital IT distributors accelerates credibility without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: CDSCO registration announcements are the leading indicator that Indian health-tech targets have cleared regulatory capital barriers sufficient to justify premium valuations. The five-to-ten year viability window favors platforms with embedded governance toolkits over standalone application vendors facing margin compression. Acquisition targets should demonstrate edge deployment capabilities in at least two manufacturing-heavy geographies, signaling technical breadth beyond cloud-native architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Conformity-by-Design Platform Architecture | EU AI Act documentation requirements elevate engineering costs that filter subscale competitors from procurement shortlists. |
| Edge Deployment Capability Expansion | German automotive suppliers and Japanese manufacturers prioritize on-device inference that reduces cloud egress fees. |
| Vertical Specialist Acquisition | FDA-validated clinical decision-support modules command premium positioning in hospital network modernization cycles. |
| Retrieval-Augmented Generation Pipeline Launch | Financial services firms in London adopt RAG to ground LLM outputs in proprietary document corpora without training data exposure. |
| CDSCO Registration Pathway Investment | India's Digital Health Mission creates procurement channels for software-as-medical-device vendors achieving national validation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across platform engineering directors, hospital procurement committee members, MLOps implementation leads, and regulatory affairs specialists at FDA and EMA. Secondary validation drew from FDA 510(k) submission databases, EU AI Act implementation guidance, hospital GPO contract disclosures, and hyperscaler AI infrastructure capex reports. Bottom-up deployment volume estimates triangulated against top-down platform revenue aggregation.
Granularity-level modeling segmented the cognitive analytics market by product tier, end-user vertical, deployment architecture, and technology capability layer, with additional disaggregation by regulatory risk classification and integration complexity. CAGRs derived from fitted growth curves applied to base-year estimates, cross-checked against vendor-reported booking trends and enterprise IT budget surveys. Forecast inputs incorporated EU AI Act implementation timelines, GPU supply constraints from Taiwan and South Korea, and edge hardware cost reduction trajectories.
Several conditions sit outside the modeled scope, including unforeseen algorithmic accountability legislation, acute semiconductor supply disruptions, and breakthrough foundation model architectures that displace current fine-tuning economics. Forecasts reflect documented assumptions about regulatory enforcement intensity and enterprise cloud migration velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Analytics Sandbox Market
Analytics
Learning Analytics Solution Market
Analytics
Identity Analytics Market
Analytics
North America Mobile Analytics Market
Analytics
HR Analytics Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Global People and HR Analytics Software Market
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Business Analytics Market
Analytics
Europe Location Data Analytics Market
Analytics
Web Analytics Market
Analytics
Global Industrial Analytics Market
Analytics
Europe Edge Analytics Market
Analytics
Global Wi-Fi Analytics Market
Analytics
Global Operational Analytics Market
Analytics
Europe Crowd Analytics Market