
 Lead Intelligence Software Market | 2026-2036
Lead Intelligence Software Market Size, Share, and Industry Trends Forecast 2026-2036
Lead Intelligence Software Market Foresight
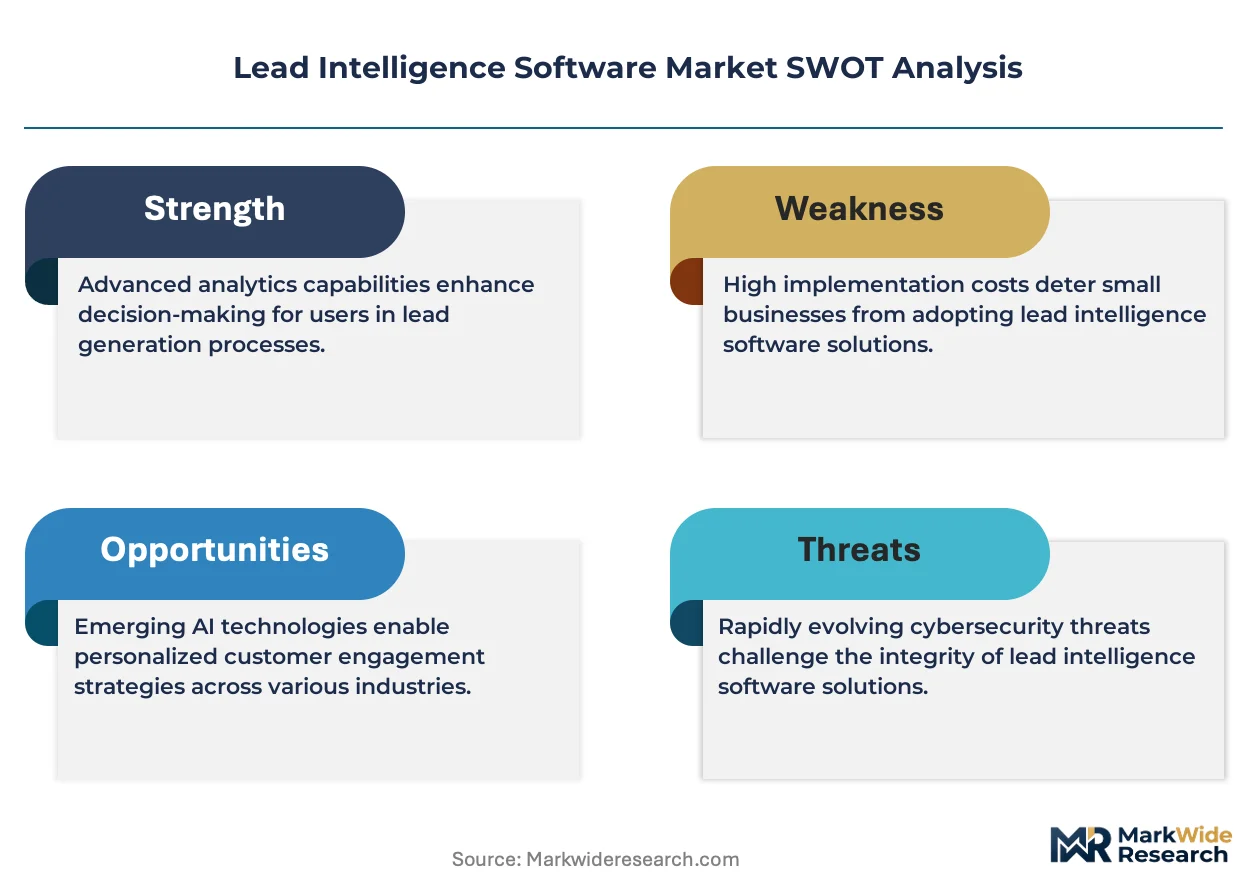
The divergence between premium intent-data platforms and commodity contact-database tools is realigning how vendors allocate engineering resources and price their offerings. ZoomInfo sustains dominance through its proprietary data graph and direct-source verification infrastructure, while 6sense differentiates via AI-driven predictive scoring and account-based orchestration capabilities. Apollo competes aggressively on price-accessibility and workflow automation depth, capturing mid-market teams that prioritize volume over precision.
Lead intelligence software encompasses platforms that aggregate, verify, and analyze prospect data to identify buying signals and prioritize sales engagement, typically processing billions of behavioral and firmographic data points through machine learning pipelines to output scored lead lists and enriched contact records. Cloud-based SaaS deployment now leads structural growth due to faster implementation cycles and native CRM connectivity, while data enrichment solutions command disproportionate margin pools as buyers treat verified contact accuracy as a premium capability rather than a baseline feature. On-premises and hybrid models retain footholds in regulated European and financial services verticals where data residency requirements constrain cloud migration.
The EU AI Act and GDPR impose strict constraints on automated profiling and cross-border data transfers, forcing vendors to architect region-specific processing nodes and consent-management layers into their platforms. In the United States, the absence of comprehensive federal privacy legislation leaves a patchwork of state-level frameworks—California's CCPA and emerging laws in Virginia and Colorado—that complicate nationwide product standardization. Stakeholders must monitor whether the FTC's evolving commercial surveillance rules will trigger a compliance escalation cycle comparable to Europe's, reshaping competitive moats around data governance investments rather than raw data volume.
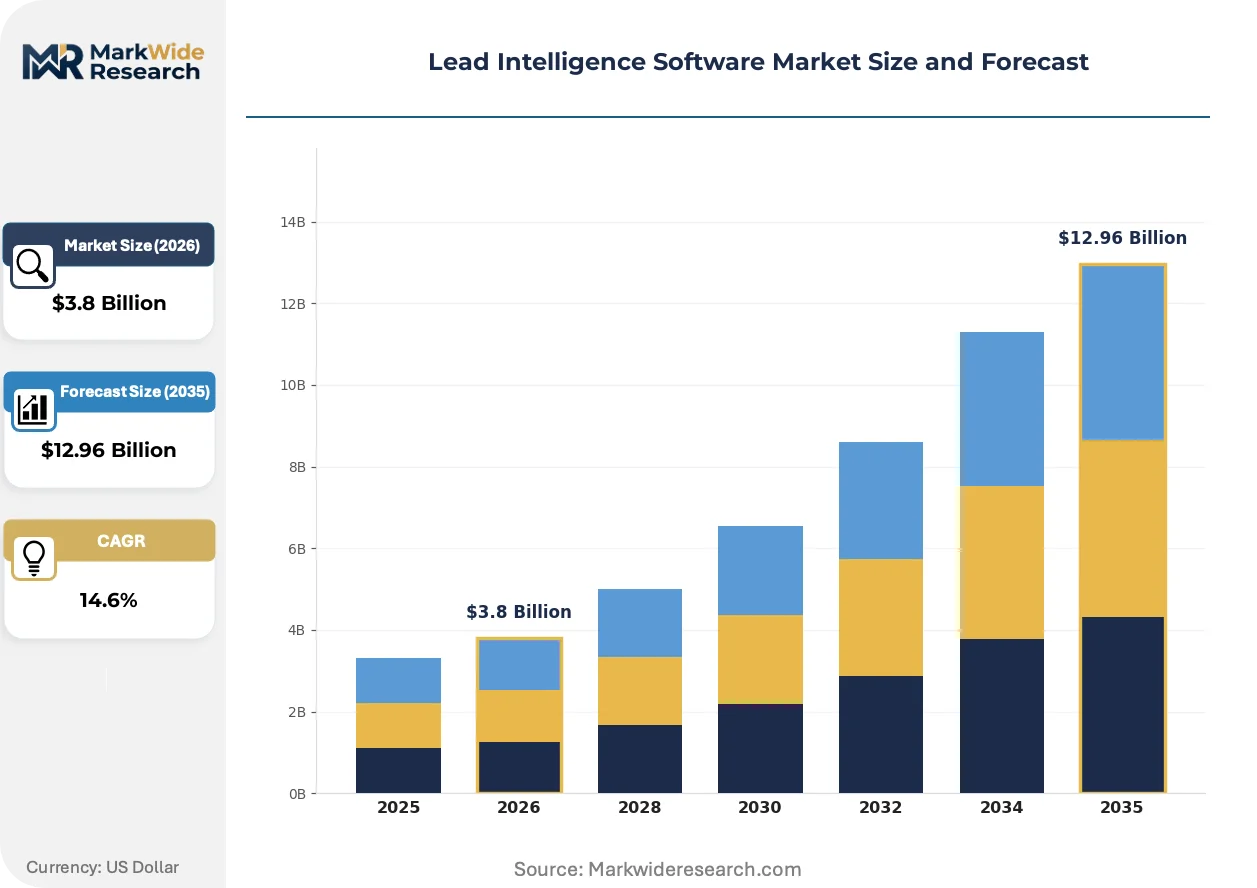
Market Dynamics
The central structural force in lead intelligence software is the collision between intent-data commoditization and algorithmic differentiation, as vendors race to build proprietary data graphs while regulators tighten constraints on automated profiling and cross-border data flows.
Growth Catalysts
- EU AI Act compliance mandates:The EU AI Act's risk-based classification system for automated decision-making is forcing enterprise buyers to prioritize vendors with built-in algorithmic transparency, creating procurement pull for compliant platforms.
- B2B technology vendor expansion:Sales teams at SaaS companies and cloud infrastructure providers are deploying intent-based prospecting as core pipeline strategy, driving platform subscriptions.
- Real-time data enrichment APIs:Native CRM connectivity and instant contact verification are compressing sales cycle initiation times, embedding lead intelligence deeper into workflow automation stacks.
Market Restraints
- GDPR cross-border transfer friction:The European Data Protection Board's evolving adequacy decisions create legal uncertainty for US-based vendors operating European data lakes, forcing redundant infrastructure investment.
- Contact database commoditization:Low-cost aggregators are eroding pricing power for basic firmographic data, compressing margins in the entry tier of the market.
- Model training data scarcity:High-quality labeled behavioral signals for predictive scoring remain concentrated among a handful of vendors with direct publisher partnerships.
Strategic Opportunities
- Mid-market workflow automation:Sales teams with 50-200 representatives remain underserved by enterprise-focused orchestration platforms, creating white space for accessible tooling.
- Consent-management layer integration:The EU AI Act and GDPR are converging to mandate granular consent tracking for profiling, opening embedded compliance software attach rates.
- Vertical-specific intent models:Healthcare and financial services buyers require sector-tuned signal detection, rewarding vendors that build specialized training datasets.
Industry Challenges
- Machine learning operations talent scarcity:Vendors struggle to hire data engineers capable of maintaining real-time inference pipelines at billion-record scale.
- Legacy CRM integration complexity:On-premises Salesforce and Microsoft Dynamics instances at regulated enterprises require custom middleware development, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lead Intelligence Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Lead Management, Data Enrichment, Analytics, CRM Integration Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Marketing Agencies Pricing Model: Subscription-Based, One-Time License, Freemium, Pay-As-You-Go |
| Companies Covered | ZoomInfo, Cognism, Apollo, Lusha, Clearbit, Leadfeeder, Seamless AI, 6sense, LeadIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lead Intelligence Software Market Shifts & Advancements
Three active shifts are restructuring how lead intelligence platforms capture value: AI infrastructure is modularizing into composable components, regulatory jurisdictions are fragmenting compliance architectures, and buyer procurement patterns are compressing vendor evaluation cycles.
Natural language processing for unstructured intent detection is modularizing from monolithic scoring engines into discrete microservices that buyers can embed selectively. Mid-market revenue operations teams are adopting these components faster than full-platform replacements, enabling best-of-breed stack construction. This modularity is compressing vendor lock-in and forcing incumbents to expose APIs that interoperate with competing workflow tools.
The EU AI Act's risk classification framework is mandating human-in-the-loop review for high-risk automated profiling systems used in B2B prospecting. European enterprise procurement teams are now requiring algorithmic impact assessments as standard vendor due diligence. Vendors serving EU-headquartered multinationals are responding by building regional processing nodes and documentation workflows that satisfy national supervisory authorities.
Revenue operations leaders are consolidating vendor relationships from an average of four point solutions toward integrated platforms that span data enrichment, scoring, and orchestration. This consolidation is displacing standalone contact database subscriptions in favor of bundled offerings with native CRM connectivity. The shift is most visible in United States venture-backed SaaS companies, where procurement teams prioritize implementation speed over feature depth.
Lead Intelligence Software Market Segmentation
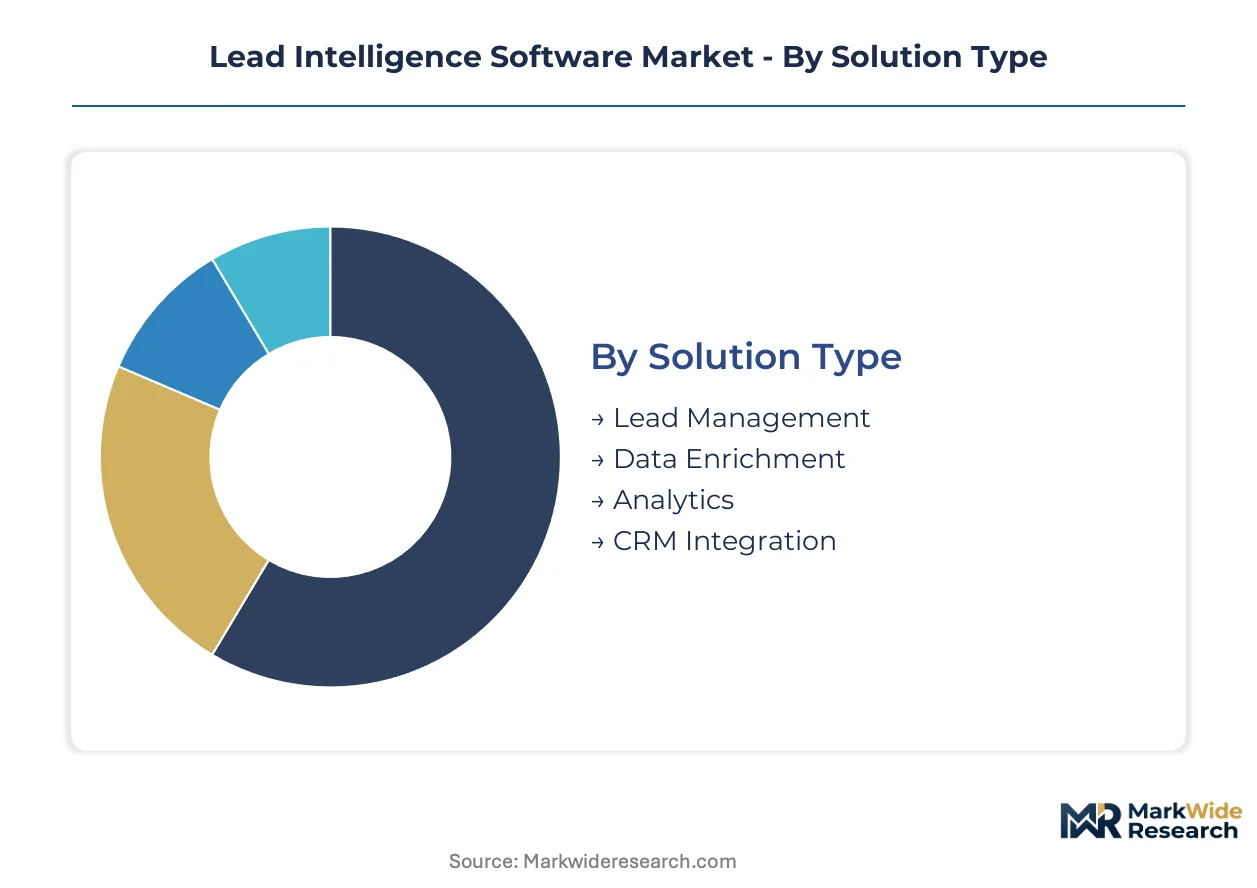
Lead intelligence software segments diverge sharply by integration depth, with standalone tools serving tactical use cases while embedded platforms reshape enterprise workflow architecture. Vendors allocate engineering resources based on which segments command premium pricing versus volume scalability.
Solution Type:
Standalone modules compete against embedded suites based on how deeply buyers prioritize native CRM connectivity over best-of-breed specialization.
- Lead Management:Core platforms that centralize prospect tracking, scoring workflows, and sales pipeline visualization through unified dashboards. Demand concentrates in United States venture-backed SaaS companies where RevOps teams prioritize implementation speed over feature depth. GDPR Article 22 constraints on automated profiling are forcing European deployments to add human-in-the-loop review layers.
- Data Enrichment:Real-time contact verification and firmographic append services that ingest fragmented signals to output validated prospect records. United States enterprise procurement budgets treat verified accuracy as a premium capability, creating disproportionate margin pools for vendors with direct-source verification infrastructure. EU AI Act risk classifications are mandating algorithmic transparency documentation for automated scoring pipelines.
- Analytics:Predictive scoring engines and intent-signal processing modules.
- CRM Integration:Native connectors and API middleware for Salesforce, HubSpot, and Microsoft Dynamics.
Lead Management leads volumes today; Data Enrichment is gaining share fastest.
Deployment Model:
Cost tier stratification separates rapid-deployment cloud offerings from compliance-driven infrastructure investments.
- Cloud-Based:Multi-tenant SaaS architectures with sub-48-hour provisioning and automatic feature updates. United States mid-market sales teams with 50-200 representatives adopt these fastest due to minimal IT overhead and per-seat pricing flexibility.
- SaaS:Single-tenant managed instances with custom configuration layers.
- Hybrid:Split architectures processing sensitive data on-premises while leveraging cloud inference for non-regulated workloads. German financial services and French healthcare verticals require these configurations to satisfy national data residency mandates under GDPR.
- On-Premises:Fully air-gapped installations at regulated enterprises.
Cloud-Based deployments dominate new bookings; Hybrid configurations are expanding most quickly in regulated European verticals.
End User:
Customer type determines feature complexity requirements and sales cycle length across the vendor base.
- Large Corporations:Global deployments with 500+ sales representatives requiring multi-language intent models and regional compliance orchestration. Procurement teams at EU-headquartered multinationals now mandate algorithmic impact assessments as standard due diligence.
- Medium Enterprises:50-200 representative teams underserved by enterprise platforms.
- Small Enterprises:Founder-led sales operations prioritizing price accessibility.
- Marketing Agencies:Multi-client management needs driving white-label and sub-account architectures.
Large Corporations anchor revenue concentration today; Medium Enterprises present the steepest expansion trajectory for accessible tooling.
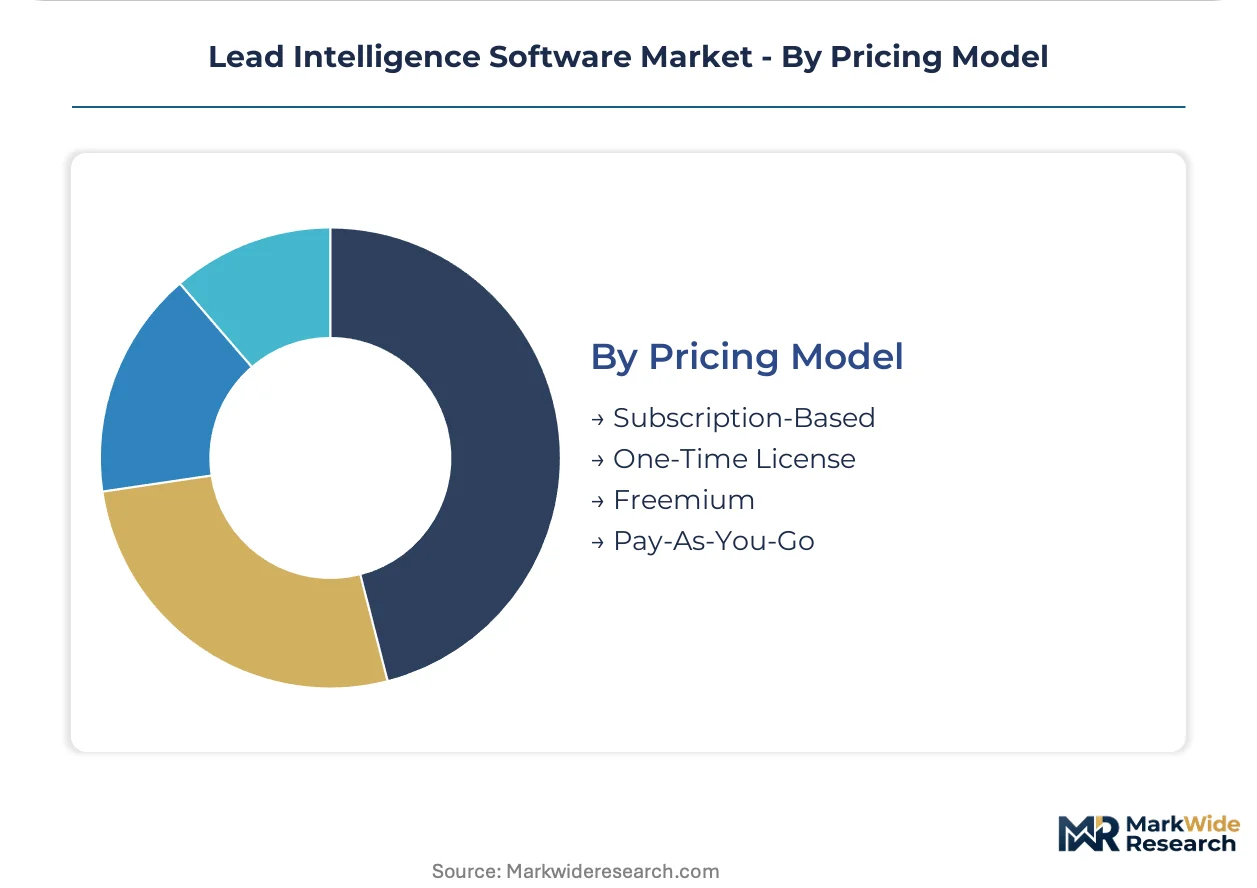
Pricing Model:
Margin structure varies by predictability of revenue recognition and customer lifetime value profiles.
- Subscription-Based:Annual or multi-year contracts with committed seat counts and tiered feature access. United States enterprise SaaS procurement patterns favor these arrangements for budget planning certainty.
- Freemium:Self-serve entry tiers with usage limits and upgrade gates.
- Pay-As-You-Go:Consumption-based API pricing for enrichment and scoring calls.
- One-Time License:Perpetual deployments with maintenance add-ons.
Subscription-Based models dominate vendor revenue today; Freemium adoption is climbing fastest among product-led growth entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise SaaS procurement intensity in the United States outpaces European deployment velocity by a significant margin, while regulatory fragmentation in Europe forces architectural complexity that US vendors rarely encounter. This divergence shapes where vendors invest compliance engineering versus sales acceleration resources.
United States
Venture-backed SaaS companies in San Francisco and New York Metro drive concentrated demand for intent-data platforms with native CRM connectivity. The FTC's evolving commercial surveillance rules create compliance uncertainty that vendors monitor against California's CCPA baseline. Austin and Boston clusters host emerging sales-tech startups that pressure incumbents on workflow automation depth.
Germany
Industrial manufacturing and automotive sales teams in Bavaria and Baden-Württemberg require hybrid deployment models satisfying GDPR data residency mandates. The KBA and federal data protection authorities enforce strict algorithmic transparency documentation for automated profiling systems. Frankfurt's financial services hub demands air-gapped processing nodes for sensitive prospect data.
United Kingdom
London's fintech and professional services sectors prioritize real-time enrichment APIs compressing sales cycle initiation times. The Information Commissioner's Office post-Brexit adequacy negotiations create parallel compliance tracks for EU and non-EU data transfers. Manchester and Edinburgh clusters are expanding faster than southeast England for mid-market sales tooling adoption.
India
Bangalore and Hyderabad's technology services exporters deploy lead intelligence for outbound US and European client acquisition at scale. The Digital Personal Data Protection Act is maturing enforcement frameworks around consent management for cross-border prospect data. Mumbai's financial services sales operations are emerging as a testing ground for localized intent models.
Japan
Enterprise technology vendors in Tokyo and Osaka prioritize integration depth with legacy on-premises CRM instances over cloud-native velocity. METI's guidance on AI utilization in commercial contexts shapes vendor documentation requirements for automated scoring transparency. Nagoya's manufacturing sales teams are adopting intent-based prospecting slower than software verticals.
Lead Intelligence Software Market Competitive Landscape
Top-tier vendors anchor the premium intent-data segment, while mid-market accessibility players compete aggressively on per-seat pricing and workflow automation depth. The vendor base stratifies across three tiers: proprietary data graph operators, AI-driven predictive scoring specialists, and price-accessible volume platforms. Dominant competitive moves include regional compliance infrastructure investment and API modularization enabling best-of-breed stack construction.
Within the proprietary data infrastructure tier, ZoomInfo exemplifies vendors sustaining dominance through direct-source verification networks. Apollo and 6sense occupy differentiated positions representing alternative strategic archetypes: one competing on price-accessible automation depth, the other on AI-driven account-based orchestration capabilities. These three anchors illustrate how vendor resource allocation diverges between data volume, algorithmic sophistication, and workflow integration priorities.
| Leading Market Players |
|---|
| ZoomInfo |
| Cognism |
| Apollo |
| Lusha |
| Clearbit |
| Leadfeeder |
| Seamless AI |
| 6sense |
| LeadIQ |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams in the United States are consolidating vendor relationships from fragmented point solutions toward integrated platforms, forcing suppliers to bundle data enrichment, scoring, and orchestration capabilities and compressing margin structures for standalone contact database providers.
Pricing Analysis
Capacity additions in cloud infrastructure regions are reshaping price floors for SaaS delivery, enabling vendors to offer per-seat subscription tiers that undercut on-premises alternatives. Three-tier pricing structure across premium, standard, and economy levels separates vendors with proprietary data graphs from commodity aggregators. Price differentiation rests on verified contact accuracy and native CRM connectivity depth. Mid-market sales teams with 50-200 representatives exhibit highest price sensitivity, while large corporations prioritize implementation speed over per-seat cost.
Supply Chain Analysis
Data provenance verification and algorithmic audit trails are creating reverse-logistics flows where vendors must reconstruct consent chains and revalidate historical records to satisfy EU AI Act documentation requirements. Raw data sourcing concentrates in the United States, Ireland, and Germany where publisher partnerships and direct verification networks anchor supply. The supply chain draws from behavioral signal feeds, firmographic databases, and third-party cookie deprecation is intensifying reliance on first-party data partnerships. Single-source vulnerability exists for high-quality labeled training datasets. Distribution runs through API-first platforms embedding directly into Salesforce, HubSpot, and Microsoft Dynamics instances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a stable compounder where regulatory compliance mandates create durable procurement pull for algorithmically transparent platforms, sustaining vendor pricing power across economic cycles.
For Market Incumbents: Hedge against contact database commoditization by deepening proprietary data graph investments and accelerating regional compliance infrastructure in Germany and France. The EU AI Act's risk classification system threatens margin compression for non-compliant vendors. Backward integration into direct publisher verification networks anchors differentiation. For New Entrants and Emerging Players: The price-point gap between ZoomInfo's premium data infrastructure and Apollo's accessible automation tier creates white-space for mid-market workflow specialists. Target 50-200 representative sales teams in Austin and Boston clusters underserved by enterprise orchestration platforms. Product-led growth with freemium enrichment APIs offers lowest-friction customer acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with vendors combining consent-management layer integration with vertical-specific intent models for healthcare and financial services. Long-term viability favors platforms with regional processing nodes satisfying GDPR data residency mandates. Monitor FTC commercial surveillance rulemaking for compliance escalation signals comparable to Europe's trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and HubSpot connectors compress implementation timelines for United States mid-market teams. |
| Acquisition of Specialist Firm | Vertical intent model providers in healthcare and financial services command premium attach rates. |
| Geographic Expansion | Frankfurt and Dublin processing nodes satisfy GDPR Article 44 cross-border transfer constraints. |
| Strategic Partnership | Direct publisher data partnerships insulate against third-party cookie deprecation headwinds. |
| Product Launch | Modular NLP microservices for unstructured intent detection enable best-of-breed stack construction. |
Research Methodology
Multiple input streams — executive interviews with revenue operations leaders, technical assessments with platform engineers, and procurement pattern analysis with IT buyers — were reconciled against SEC filings, hyperscaler capex disclosures, and EU regulatory documentation. Bottom-up sizing of vendor subscription revenue and top-down validation against enterprise SaaS procurement budgets anchored volume estimates.
Historical growth trajectories were cross-referenced against panel input from sales technology practitioners to calibrate projection assumptions across the analysis window. Segmentation dimensions modeled include deployment architecture, organization scale, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for compliance-driven procurement acceleration in European markets.
Caveats apply where FTC commercial surveillance rulemaking or European Data Protection Board adequacy decisions could materially shift the outlook for cross-border data flows. Practitioners should monitor algorithmic impact assessment requirements and consent-management enforcement patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Recommendation Engine Market
Analytics
Cyprus ICT Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
Active Data Warehousing Market
Analytics
Big Data Analytics in Retail Market
Analytics
Analytics As a Service (Aaas) Market
Analytics
Customer Data Platform Market
Analytics
Behavior Analytics Market
Analytics
Brazil Geospatial Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Geospatial Imagery Analytics Market
Analytics
Global Performance Analytics Market
Analytics
Predictive Analytics Market
Analytics
Content Analytics and Search Software Market
Analytics
Global in-Store Analytics Market
Analytics
Location Analytics Market