
 Digital Payment in Healthcare Market | 2026-2036
Digital Payment in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Payment in Healthcare Market Intelligence
The increasing patient preference for outpatient and telehealth services is recalibrating the traditional hospital-centric revenue cycle management model. This shift places a premium on flexible, consumer-friendly payment solutions. In this environment, InstaMed leverages its deeply integrated network connecting providers and payers. Waystar specializes in automating complex billing workflows for clinics and health systems. Meanwhile, Optum competes by embedding its payment solutions within a broader ecosystem of health analytics and administrative services, creating a comprehensive offering for large enterprise clients.
Digital payment in healthcare involves electronic platforms that facilitate financial transactions between patients, providers, and insurers. These systems rely on secure APIs and data tokenization to protect sensitive financial and health information during transmission. The primary purpose is to streamline the billing process, reduce administrative overhead for providers, and offer patients transparent, convenient payment options. While Patient Billing remains the dominant application, solutions for Telemedicine Payment represent the fastest-growing segment. Cloud-based deployment is becoming the standard over on-premises systems due to scalability and lower upfront costs.
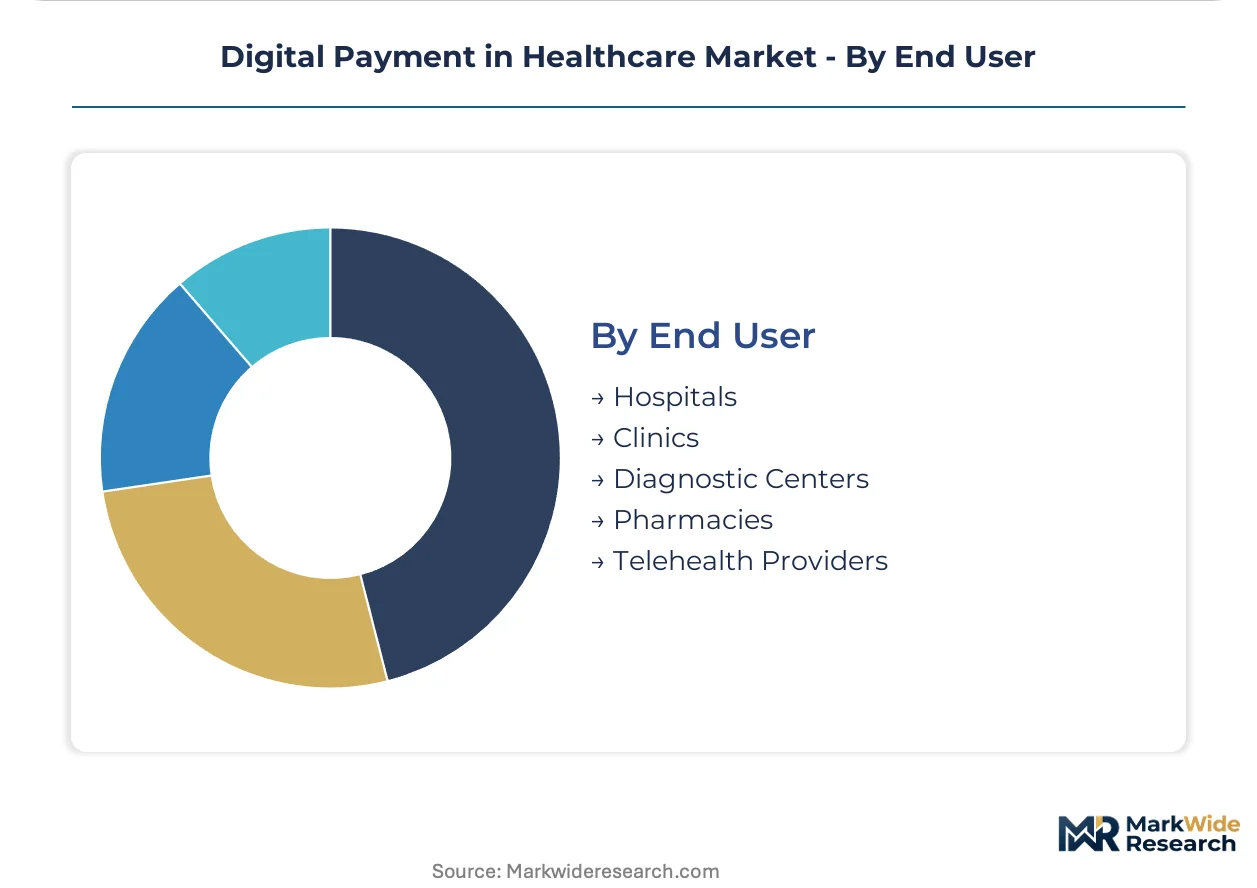
Regulatory frameworks are a primary force shaping market development and product design. In the United States, the Health Insurance Portability and Accountability Act (HIPAA) sets strict standards for protecting patient health information, including financial data. Similarly, the General Data Protection Regulation (GDPR) in Europe imposes stringent data privacy and consent requirements that influence how payment platforms operate across the continent. Providers and platform vendors must continuously navigate the balance between offering a seamless user experience and complying with evolving cybersecurity and data privacy mandates.
Market Dynamics
The convergence of consumer finance expectations with healthcare delivery models is the central force shaping the market. Patient demand for transparent, on-demand payment options, amplified by the expansion of telehealth, is compelling providers to overhaul legacy billing systems.
Growth Catalysts
- Telehealth Expansion:The rapid adoption of telehealth services by providers in countries like India and Brazil necessitates integrated digital payment solutions to manage financial transactions for remote consultations and follow-up care.
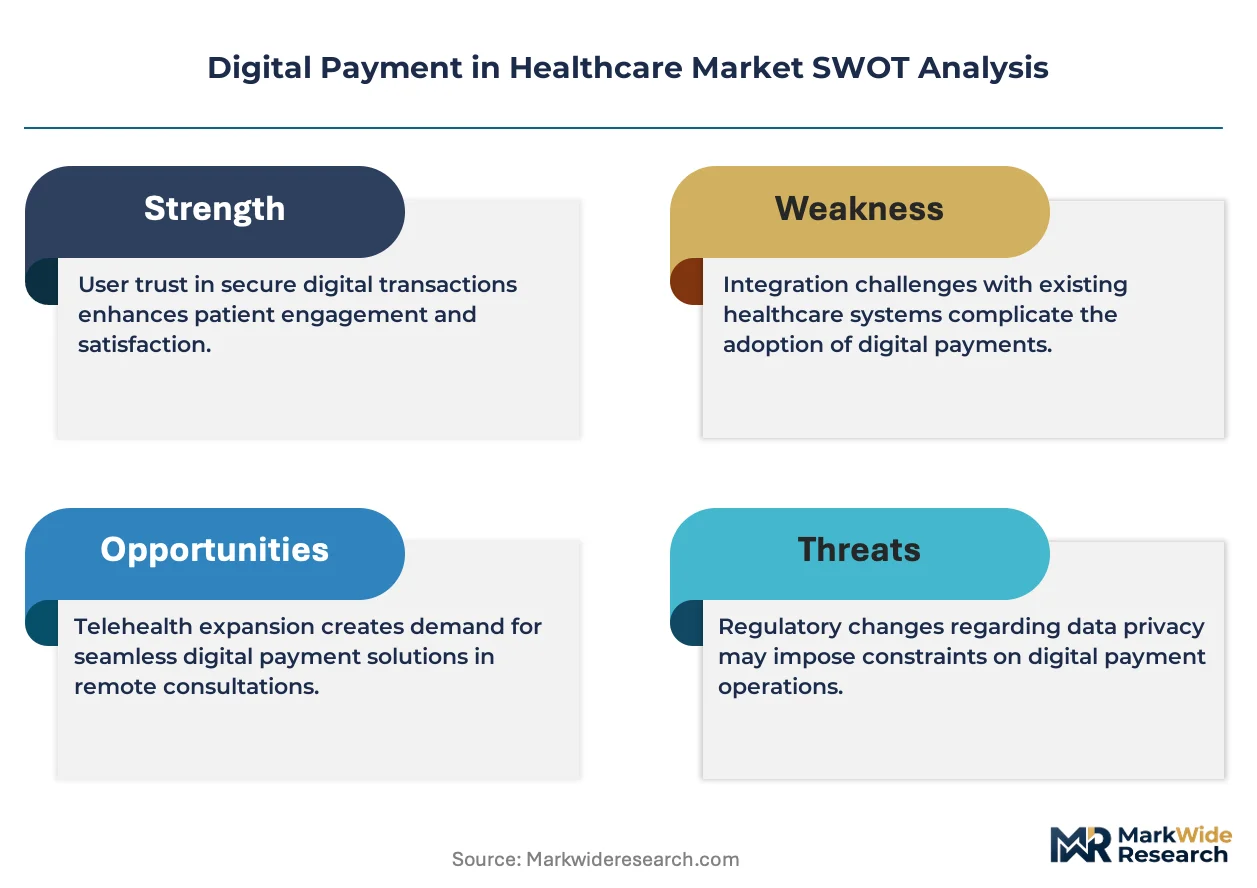
- Regulatory Mandates:Data privacy regulations such as GDPR in Europe require platforms to provide patients with greater control over their personal and financial data, spurring development of compliant and secure systems.
- API Proliferation:The increasing availability of secure Application Programming Interfaces (APIs) enables smoother integration between Electronic Health Record (EHR) platforms and third-party payment gateways, reducing implementation friction for healthcare providers.
Market Restraints
- Integration Complexity:The high cost and technical difficulty of integrating modern payment platforms with entrenched legacy systems, such as older Hospital Information Systems (HIS), create significant barriers for many healthcare organizations.
- Data Security Risks:The persistent threat of cyberattacks targeting Protected Health Information (PHI) elevates compliance costs and liability risks for providers and platform vendors under frameworks like HIPAA in the United States.
- Interoperability Gaps:A lack of universal data exchange standards between disparate payer and provider IT systems results in processing delays, manual reconciliation work, and increased administrative overhead for billing departments.
Strategic Opportunities
- Underserved Clinic Segment:Small and medium-sized clinics in emerging economies represent a significant growth area as they begin to digitize administrative functions and seek affordable, scalable cloud-based payment solutions.
- Value-Based Care Models:Developing specialized payment platforms tailored for value-based care arrangements can address the complex transaction and data-sharing requirements between payers and providers in these new reimbursement structures.
- AI-Powered Estimation:The convergence of AI-driven claims analytics with patient payment portals allows for the creation of real-time cost estimators, which can reduce billing disputes and improve the patient financial experience.
Industry Challenges
- Specialized Talent Scarcity:A shortage of professionals with dual expertise in both financial technology security protocols and complex healthcare regulations like HIPAA impedes product development and secure implementation for platform vendors.
- Legacy System Migration:Providers face significant operational disruption risks when migrating data and critical workflows from established on-premises billing systems to new cloud-based digital payment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Payment in Healthcare Market |
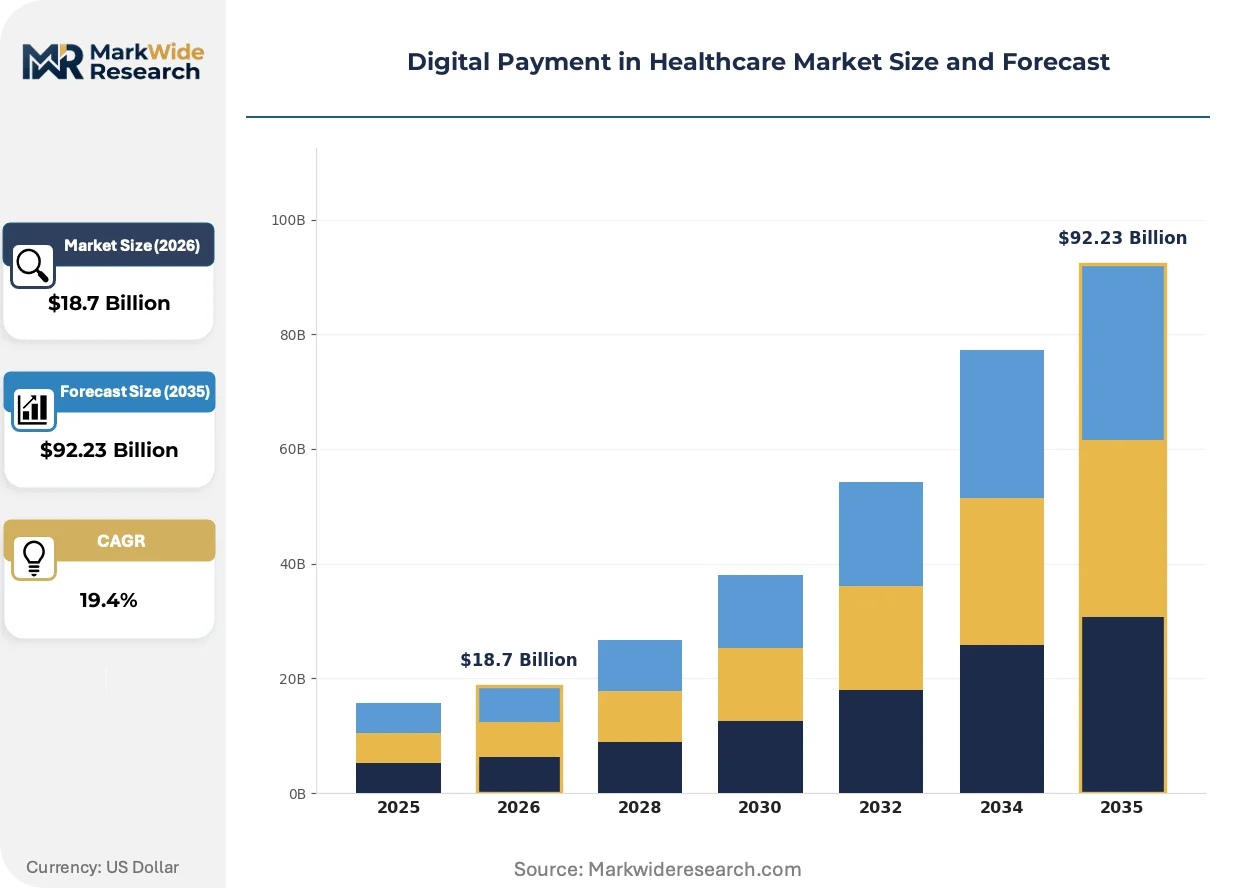
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Mobile Wallets, Contactless Payment, Point of Sale Terminals, Online Payment Gateways, Bank Transfers Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Services Application: Patient Billing, Insurance Claims, Telemedicine Payment, Pharmacy Transactions, Medical Equipment Financing End User: Hospitals, Clinics, Diagnostic Centers, Pharmacies, Telehealth Providers |
| Companies Covered | InstaMed, NextGen Healthcare, Cedar, R1 RCM, Athenahealth, PatientPay, Optum, Ensemble Health Partners, Waystar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Payment in Healthcare Market Strategic Shifts & Innovations
Digital payment platforms are evolving from transactional utilities into core components of patient financial engagement. This shift is driven by the need for providers to manage complex revenue cycles while meeting consumer demands for price transparency and flexible payment methods.
Artificial Intelligence (AI) and machine learning (ML) algorithms are being embedded into payment platforms to predict patient payment behavior and optimize collection strategies. Large health systems and specialty clinics are adopting these tools to reduce days in accounts receivable. This technology is automating the previously manual tasks of claims follow-up and patient-responsibility estimation, improving cash flow for providers.
The No Surprises Act in the United States mandates greater price transparency and protections against unexpected medical bills. This legislation compels providers and insurers to provide good-faith estimates and clear billing information. The provider segment, particularly hospitals and emergency services, is most affected, driving investment in platforms that can accurately calculate and communicate patient cost-sharing upfront.
A behavioral shift toward subscription-based payment models is emerging, particularly for primary care and chronic disease management. This disrupts the traditional fee-for-service billing cycle by offering predictable, recurring revenue streams for providers. This trend is most visible in the direct primary care (DPC) sector in the United States and is gaining traction in specialized wellness clinics.
Digital Payment in Healthcare Market Segmentation
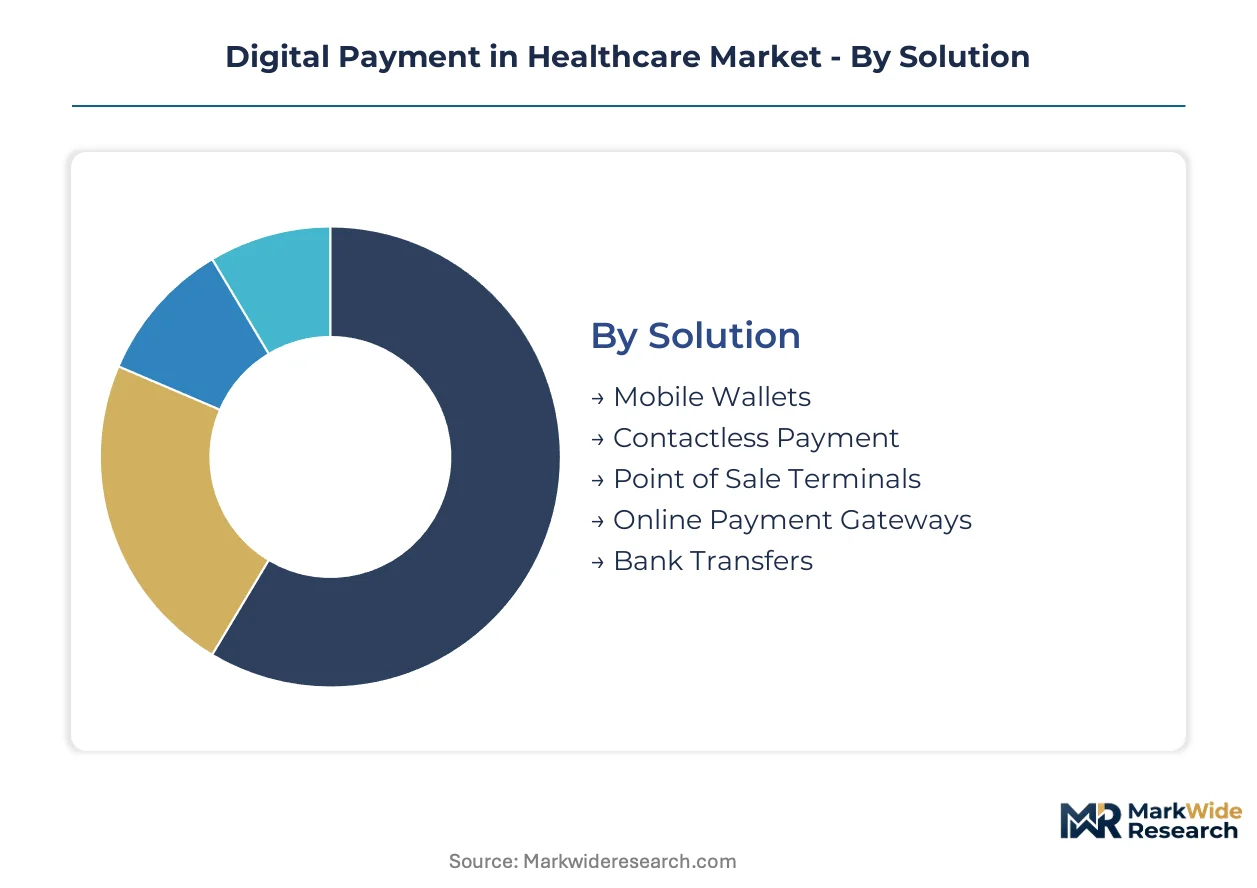
The digital payment in healthcare market differentiates across several key dimensions, reflecting diverse operational needs of providers and evolving patient expectations. Understanding these segments clarifies where investment is concentrating and how technology adoption varies.
Solution:
The digital payment solution landscape ranges from highly integrated systems to standalone transactional tools, each enhancing transaction efficiency across the patient financial journey.
- Mobile Wallets:These platforms facilitate secure, in-app or tap-to-pay transactions using tokenized card information, offering patients a convenient method for settling medical bills. Consumer preference in the United States drives integration.
- Online Payment Gateways:These systems securely process credit and debit card transactions via web interfaces, foundational for patient self-service billing and telehealth. Adoption by clinics in Germany streamlines remote payment.
- Contactless Payment:Utilizing NFC technology, these solutions enable quick, secure payments by tapping a device or card, useful in high-volume settings.
- Point of Sale Terminals:Physical devices process card payments directly at healthcare facilities, serving as a primary transaction point for in-person services.
- Bank Transfers:Direct electronic transfers between patient and provider bank accounts offer a secure, lower-cost alternative for larger medical expenses.
Volume placements concentrate in Online Payment Gateways; the faster expansion belongs to Mobile Wallets.
Deployment:
Deployment models reflect operational maturities and infrastructure capabilities, balancing scalability, data control, and upfront investment for healthcare organizations.
- Cloud-Based:Hosted on remote servers, these platforms offer scalability, automatic updates, and reduced upfront infrastructure costs. Telehealth providers in India favor cloud solutions for rapid deployment.
- On-Premises:Software on local servers provides maximum data control and customization, preferred by large hospital systems. Legacy systems in Brazilian hospitals rely on on-premises setups.
- Hybrid:Combines cloud and on-premises elements, allowing organizations to maintain sensitive data locally while leveraging cloud flexibility.
- Hosted Services:A third-party vendor manages digital payment infrastructure, providing a turnkey solution reducing internal IT burden for clinics.
The market dynamics favor Cloud-Based solutions due to scalability, while On-Premises deployments maintain a strong presence for data control.
Application:
Digital payment applications span critical financial touchpoints, with varying transaction volumes and complexity, addressing distinct revenue cycle management challenges.
- Patient Billing:This segment encompasses all transactions related to patient responsibility after insurance, representing the largest volume of digital payments. Providers globally prioritize efficient patient billing to improve cash flow.
- Telemedicine Payment:Solutions tailored for remote consultations enable seamless financial transactions for telehealth providers, experiencing rapid expansion driven by increased service adoption. This segment expands most quickly.
- Insurance Claims:Digital platforms streamline claims submission and processing between providers and payers, accelerating reimbursement cycles.
- Pharmacy Transactions:These payments cover prescription purchases and over-the-counter medications, often integrating with point-of-sale systems.
- Medical Equipment Financing:Digital payment options facilitate installment plans or direct purchases for medical devices.
Patient Billing drives a substantial portion of transaction value, with Telemedicine Payment showing significant transactional growth.
End User:
Digital payment solutions are tailored to the distinct operational needs and patient volumes of various healthcare end-users, influencing platform features and integration priorities.
- Hospitals:Large acute care facilities require robust, integrated payment systems to manage high volumes of complex transactions, including inpatient and emergency services. These institutions prioritize solutions integrating with existing EHR systems.
- Telehealth Providers:These entities specialize in remote patient care, necessitating flexible, user-friendly digital payment solutions for virtual consultations and subscriptions. Their rapid expansion drives demand for scalable platforms.
- Clinics:Smaller outpatient facilities and specialty practices seek affordable, easy-to-implement digital payment solutions to streamline billing and enhance patient experience.
- Diagnostic Centers:Imaging centers and laboratories utilize digital payment systems for services like X-rays, MRIs, focusing on efficient patient check-out.
- Pharmacies:Retail and hospital pharmacies employ digital payment methods for prescription fulfillment and over-the-counter sales, integrating with point-of-sale systems.
The operational requirements of Hospitals dictate specific platform functionalities, while Telehealth Providers represent a rapidly expanding user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rapid adoption of telehealth services across key geographies drives the concentration of digital payment solutions. This trend necessitates integrated financial transaction management for remote consultations and follow-up care. Providers are overhauling legacy billing systems to meet these demands.
United States
Consumer preference for mobile wallets and telehealth services drives demand for digital payment platforms. HIPAA mandates strict data security, influencing platform development and provider compliance. Silicon Valley fosters health tech innovation, particularly in secure payment processing for enterprise clients.
Germany
Clinics increasingly adopt online payment gateways to streamline billing and improve administrative efficiency. GDPR regulations impose stringent data privacy requirements, shaping platform operations across the nation. Berlin's burgeoning health tech scene contributes to new digital payment solutions tailored for the European market.
India
Telehealth expansion and rapid cloud-based solution deployment fuel demand for integrated digital payment systems. The Reserve Bank of India (RBI) influences digital payment infrastructure, promoting secure, accessible transaction methods. Bengaluru serves as a hub for health tech innovation, developing scalable payment solutions for remote consultations.
Brazil
Upgrading financial transaction infrastructure within urban healthcare systems drives demand for modern digital payment solutions. Brazil's LGPD imposes data privacy standards, influencing platform design and data handling. São Paulo, a major economic center, concentrates investment in digital health and payment system upgrades.
Singapore
The nation's advanced digital infrastructure and "Smart Nation" initiatives boost digital payment integration in healthcare. Singapore's Personal Data Protection Act (PDPA) ensures robust data privacy, impacting how payment platforms manage sensitive information. Health City Novena exemplifies concentrated healthcare innovation, including payment system modernization.
Digital Payment in Healthcare Market Key Industry Players
Top-tier vendors anchor comprehensive solutions for large healthcare enterprises, while specialized providers target specific segments like clinics or telehealth. The market structure features integrated network solutions, automated billing workflow specialists, and broader health analytics ecosystems. Strategic archetypes include platform integrators, workflow optimizers, and holistic administrative service providers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the integrated network tier, InstaMed exemplifies platforms connecting providers and payers through deeply embedded solutions, enhancing transaction efficiency. Waystar represents specialists automating complex billing workflows for clinics and health systems, focusing on administrative overhead reduction. Optum, a subsidiary of UnitedHealth Group, anchors a comprehensive offering by embedding payment solutions within a broader ecosystem of health analytics and administrative services, catering to large enterprise clients. These entities focus on streamlining financial transactions and enhancing the patient financial experience.
| Leading Market Players |
|---|
| InstaMed |
| NextGen Healthcare |
| Cedar |
| R1 RCM |
| Athenahealth |
| PatientPay |
| Optum |
| Ensemble Health Partners |
| Waystar |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure costs, a foundational element for digital payment platforms, cascade into tiered pricing structures for healthcare providers. This relationship influences the cost of service delivery and the final pricing models offered to patients and payers.
Pricing Analysis
Rapid deployment premiums characterize pricing for digital payment platforms, with discounts often available for longer-term implementation schedules. SaaS-tiered models dominate, offering varying feature sets based on subscription levels. Customization level and transaction volume act as primary differentiation drivers for solution pricing. Pricing pressure stems from increasing competition and the commoditization of basic payment gateway functionalities. Small and medium-sized clinics typically exhibit the highest price sensitivity, seeking cost-effective, scalable solutions.
Supply Chain Analysis
Global data center networks form the primary distribution layer for digital payment solutions in healthcare. Supply concentration for core technology components centers around key innovation hubs in the United States, Germany, and India. Raw material dependencies include secure Application Programming Interfaces (APIs) and robust cloud computing services. Data breach vulnerability represents a significant structural risk across the digital payment supply chain. The dominant distribution model involves direct-to-customer SaaS delivery, often integrated into existing Electronic Health Record (EHR) systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with cloud-based platforms rapidly displacing legacy on-premises billing systems.
For Market Incumbents: To counter agile fintech disruptors, incumbents must strategically acquire specialized payment processing firms to integrate advanced functionalities. Investment in AI-driven analytics can optimize revenue cycle management and fraud detection. Deep integration with existing Electronic Health Record (EHR) systems remains a critical lever for retaining large hospital clients. Consolidating market share through M&A in specific regional markets offers defensive advantages.
For New Entrants and Emerging Players: Electronic Health Record (EHR) vendors represent a key channel partner type for digital payment solution providers. Underserved small and medium-sized clinics in emerging economies offer significant white-space targets. Developing specialized platforms for value-based care models also provides a growth avenue. Offering bundled solutions with practice management software can serve as an effective go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized payment platform providers in the United States, particularly those with strong cloud-native architectures. The market demonstrates long-term viability, driven by persistent demand for efficiency and patient convenience over the coming decade. Agile cloud-native platforms with robust data security protocols represent attractive acquisition targets. Increased regulatory clarity on AI in healthcare payments serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI-Powered Billing Startups | Integrates advanced automation and predictive analytics into existing revenue cycle management systems. |
| Develop Telehealth-Specific Payment Modules | Addresses the unique financial transaction requirements of rapidly expanding remote patient care services. |
| Invest in API Security Frameworks | Enhances data protection for sensitive financial and health information transmitted between systems. |
| Form Partnerships with EHR Vendors | Expands market reach and streamlines integration for healthcare providers utilizing established software. |
| Expand Cloud-Based Infrastructure | Ensures scalability and reduces operational costs for delivering digital payment solutions globally. |
Research Approach
Independent corroboration across industry whitepapers, regulatory body publications, and financial news archives underwrites the qualitative findings presented in this analysis. Primary research involved structured interviews with healthcare IT directors, payment solution architects, regulatory compliance officers, and telehealth executives. Secondary validation drew from HIPAA enforcement data, GDPR guidance documents, central bank digital payment reports, and medical association surveys, triangulating insights from both bottom-up and top-down perspectives.
The analytical framework decomposes market dynamics to project rates of change across the analysis window, modeling key segmentation dimensions. These include solution type, deployment model, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market shifts, considering inputs such as telehealth adoption rates and digital health investment levels.
Caveats apply where new data privacy legislation or major cyber-security incidents could materially shift the outlook. Forecasts reflect assumptions regarding technological advancements in payment security and the evolving regulatory landscape. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Remote Deposit Capture Market
Payments
Clearing Houses and Settlements Market
Payments
Spain Payments Market
Payments
Medical Payment Fraud Detection Market
Payments
United Arab Emirates Real Time Payments Market
Payments
France POS Terminal Market
Payments
Spain Mobile Payment Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
United States Payments Market
Payments
Biometric Payment Market
Payments
Global Real-Time Payments Market
Payments
Epayment System Market
Payments
France Mobile Payment Market
Payments
GCC Payment Gateway Market
Payments
Mexico Real Time Payments Market