
 Asia-Pacific Payment Analytics Software Market | 2026-2036
Asia-Pacific Payment Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Payment Analytics Software Market Analytics
Singapore's fintech sandbox expansion is narrowing the gap between traditional banks and agile payment startups. Adobe leverages its creative cloud data architecture to extend analytics capabilities into merchant payment workflows. ACI Payment Systems anchors enterprise-grade transaction processing across ASEAN corridors. HiPay competes on localized fraud scoring for European-Asia cross-border merchants.
Asia-Pacific payment analytics software encompasses data processing platforms that ingest, normalize, and visualize transaction streams across multiple payment rails, operating through real-time API connections to card networks, bank ledgers, and digital wallets to detect anomalies and optimize acceptance rates. Cloud-based deployment dominates new installations among mid-market retailers seeking elastic compute for seasonal transaction spikes. Fraud detection solutions command premium pricing from financial institutions managing real-time authorization volumes. On-premises installations persist among Japanese megabanks with stringent data residency mandates.
India's Reserve Bank mandates granular transaction reporting through its payments vision framework, forcing domestic banks to upgrade legacy reconciliation engines. Australia's Consumer Data Right, enforced by the ACCC, compels open banking data sharing that feeds analytics dashboards. Singapore's MAS technology risk management guidelines prescribe audit trails for payment system operators. Stakeholders must weigh sovereign data localization rules against multi-tenant cloud economics when architecting regional delivery models.
Market Dynamics
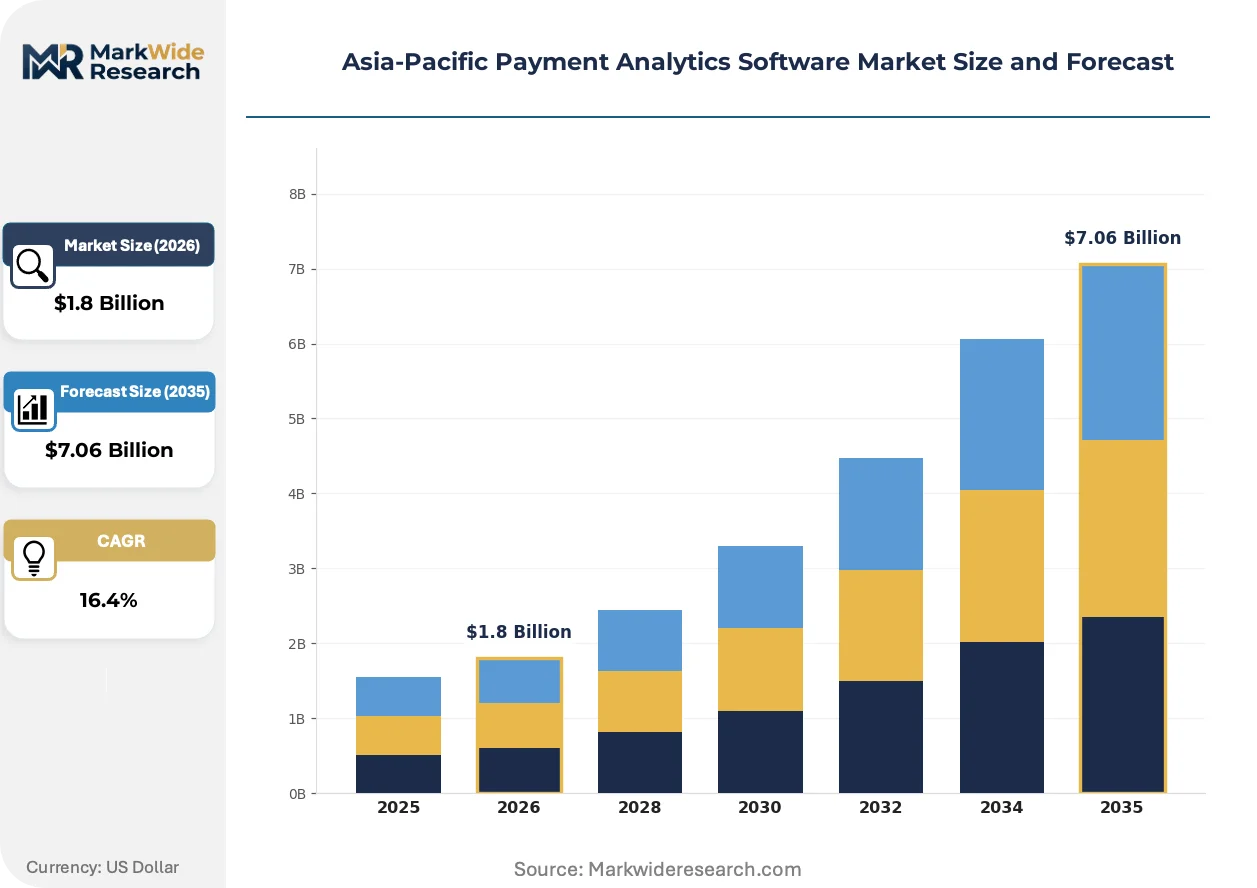
India's unified payments interface infrastructure and Australia's open banking framework are forcing financial institutions across Southeast Asia to rebuild analytics stacks around real-time data ingestion and sovereign data residency requirements.
Growth Catalysts
- RBI Payments Vision Framework:India's central bank mandates granular transaction reporting that forces domestic banks to upgrade legacy reconciliation engines with modern analytics platforms.
- Merchant payments ecosystem:India's retail payment volume surge creates sustained procurement pull for fraud detection and acceptance optimization tools.
- Cloud-native architectures:Elastic compute deployments allow mid-market retailers to handle seasonal transaction spikes without permanent infrastructure overhang.
Market Restraints
- Data localization mandates:Japanese megabanks face stringent residency requirements that block multi-tenant cloud economics and inflate deployment costs.
- Legacy system entrenchment:Regional banks in Thailand and Indonesia operate on decades-old core banking platforms that resist API-based analytics integration.
- Skill scarcity in real-time data engineering:The talent pool for stream processing and distributed ledger analytics remains concentrated in Singapore and Bangalore.
Strategic Opportunities
- Vietnam's underpenetrated merchant acquiring market:Rapid digital wallet adoption outpaces analytics vendor presence, creating first-mover positioning for localized fraud scoring.
- MAS technology risk management guidelines:Singapore's prescribed audit trails for payment system operators open consulting and software bundling opportunities.
- Cross-border ASEAN corridors:Real-time retail payment linkages between Singapore, Thailand, Malaysia and Indonesia require harmonized analytics across multiple central bank technical standards.
Industry Challenges
- ACCC Consumer Data Right compliance timelines:Australian banks face compressed deadlines to operationalize open banking data feeds into customer-facing analytics dashboards.
- Multi-rail transaction normalization:Vendors must reconcile disparate data formats from card networks, bank ledgers, QR-code wallets and buy-now-pay-later platforms into unified analytical models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Payment Analytics Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Platform Deployment: Public Cloud, Private Cloud, Multi-Tenant, Single-Tenant End User: Retailers, Financial Institutions, E-Commerce, Travel Services Solution: Fraud Detection, Customer Insights, Compliance Management, Risk Assessment |
| Companies Covered | Adobe, BlueSnap Corporate, Databox, Payfirma, Yapstone, HiPay, ProfitWell, CashNotify, ACI Payment Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Payment Analytics Software Market Evolving Landscape
Real-time stream processing architectures and sovereign cloud deployments are compressing the traditional batch-analytics cycle that dominated Asia-Pacific financial infrastructure for decades.
Embedded analytics engines are collapsing the boundary between transaction processing and business intelligence layers. Tier-2 banks in the Philippines and Indonesia now deploy in-memory computing to authorize payments and generate merchant insights within single-digit millisecond windows. This convergence eliminates the historical lag between operational data stores and analytical warehouses, forcing vendors to rearchitect around event-driven microservices rather than scheduled ETL pipelines.
Singapore's MAS technology risk management guidelines now prescribe granular audit trails for payment system operators handling retail flows above defined volume thresholds. Financial institutions must implement immutable logging with cryptographic verification, shifting procurement criteria toward vendors with proven tamper-evident infrastructure. Australian banks subject to ACCC Consumer Data Right enforcement face parallel requirements for consent-tracked data sharing that feeds external analytics dashboards.
Merchant acquirers across India and Southeast Asia now demand outcome-based pricing tied to fraud reduction metrics rather than per-seat software licenses. Large retail chains in Australia negotiate contracts where vendor fees scale with measured improvement in authorization approval rates. This restructures vendor revenue models toward shared-risk arrangements and compresses traditional upfront implementation fees into performance-contingent fee streams.
Asia-Pacific Payment Analytics Software Market Segmentation
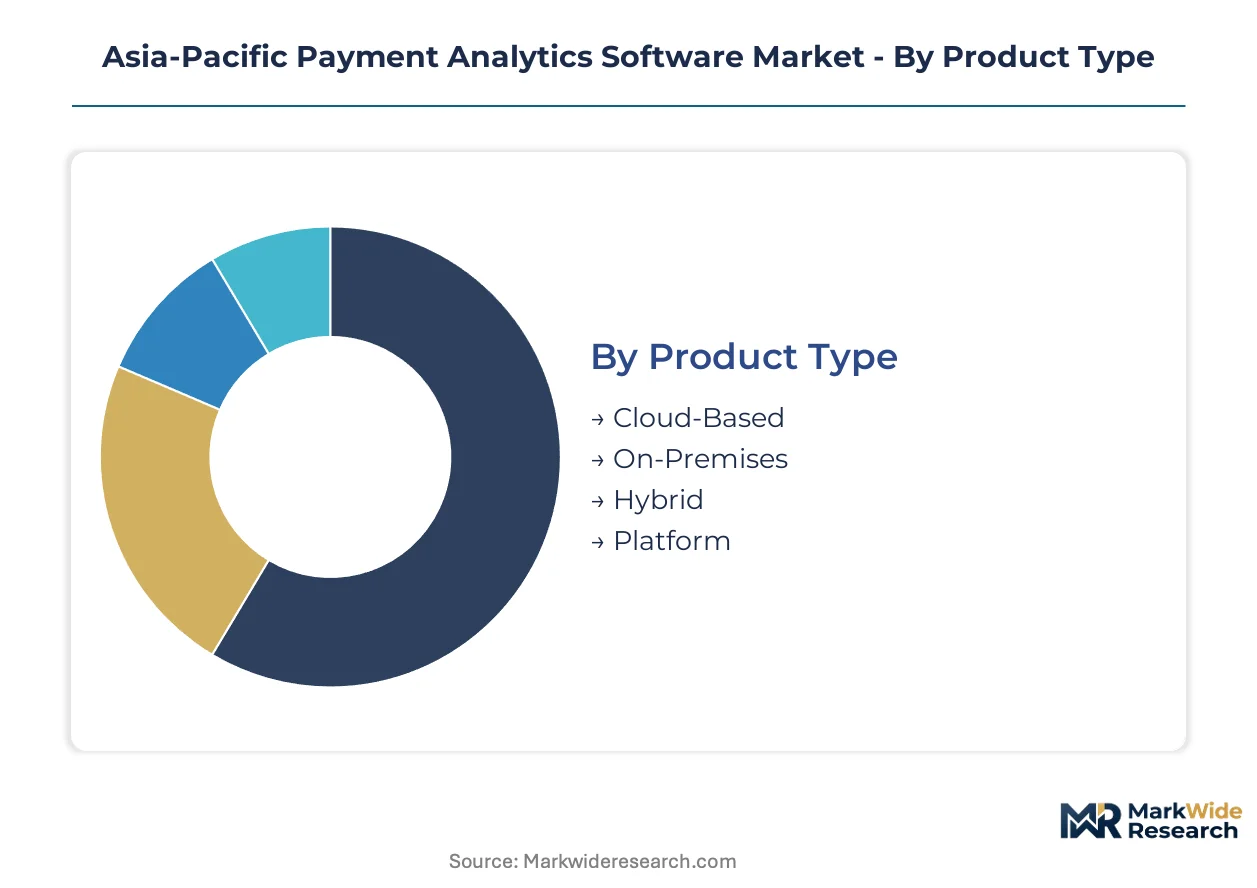
Payment analytics software segments reflect divergent infrastructure requirements across Asia-Pacific's fragmented regulatory environment. Deployment choices carry compliance consequences that reshape vendor economics and customer switching costs.
Product Type:
After-sales service intensity varies dramatically across product architectures, with cloud-based deployments demanding continuous platform updates and on-premises installations requiring specialized field engineering.
- Cloud-Based:Elastic compute architectures enable mid-market retailers to scale processing capacity during seasonal transaction surges without permanent infrastructure commitments. India's merchant payments ecosystem drives procurement pull, though data localization mandates in Japan and Australia constrain multi-tenant economics.
- On-Premises:Dedicated hardware installations serve Japanese megabanks with stringent residency requirements and legacy system dependencies. Deployment costs inflate substantially compared to cloud alternatives, creating vendor margin pressure and extended sales cycles.
- Hybrid:Split architectures balance sovereignty compliance with cloud scalability for regional banks navigating mixed regulatory jurisdictions.
- Platform:Integrated suites bundle analytics engines with transaction processing cores for large-scale merchant acquirers.
Cloud-based deployments hold the largest share; momentum sits with hybrid configurations as regulatory complexity intensifies.
Deployment:
Cost tier differentiation separates enterprise financial institutions willing to absorb premium single-tenant infrastructure from cost-sensitive mid-market retailers.
- Public Cloud:Shared infrastructure delivers lowest unit economics for transaction volume spikes, attracting Southeast Asian digital wallet operators and Australian retail chains. RBI-mandated granular reporting requirements force domestic Indian banks toward compliant public cloud configurations.
- Private Cloud:Dedicated virtual environments satisfy Singapore MAS technology risk management guidelines for payment system operators above volume thresholds. Australian banks subject to ACCC Consumer Data Right enforcement deploy private instances for consent-tracked data sharing.
- Multi-Tenant:Shared logical partitions enable software vendors to spread R&D costs across customer bases, though Japanese data residency rules block adoption.
- Single-Tenant:Isolated environments command premium pricing from institutions managing cross-border ASEAN corridor transactions with harmonized compliance requirements.
Public cloud captures volume leadership; private cloud climbs the fastest as sovereign computing mandates proliferate.
End User:
Application maturity diverges sharply, with financial institutions operating decades-old reconciliation engines while e-commerce platforms deploy greenfield stream processing.
- Retailers:Large retail chains in Australia negotiate outcome-based contracts where vendor fees scale with measured authorization approval rate improvements. Seasonal transaction volatility drives demand for elastic analytics capacity.
- Financial Institutions:Domestic banks across India and Thailand face compressed deadlines to operationalize real-time data feeds into customer-facing dashboards. Legacy core banking platforms resist API-based integration, inflating implementation timelines.
- E-Commerce:Digital-native merchants deploy embedded analytics engines collapsing transaction processing and business intelligence layers into single-digit millisecond windows.
- Travel Services:Cross-border payment volumes require fraud scoring calibrated to multi-currency, multi-timezone transaction patterns.
Financial institutions dominate current procurement; e-commerce represents the steepest expansion trajectory as digital wallet adoption accelerates.
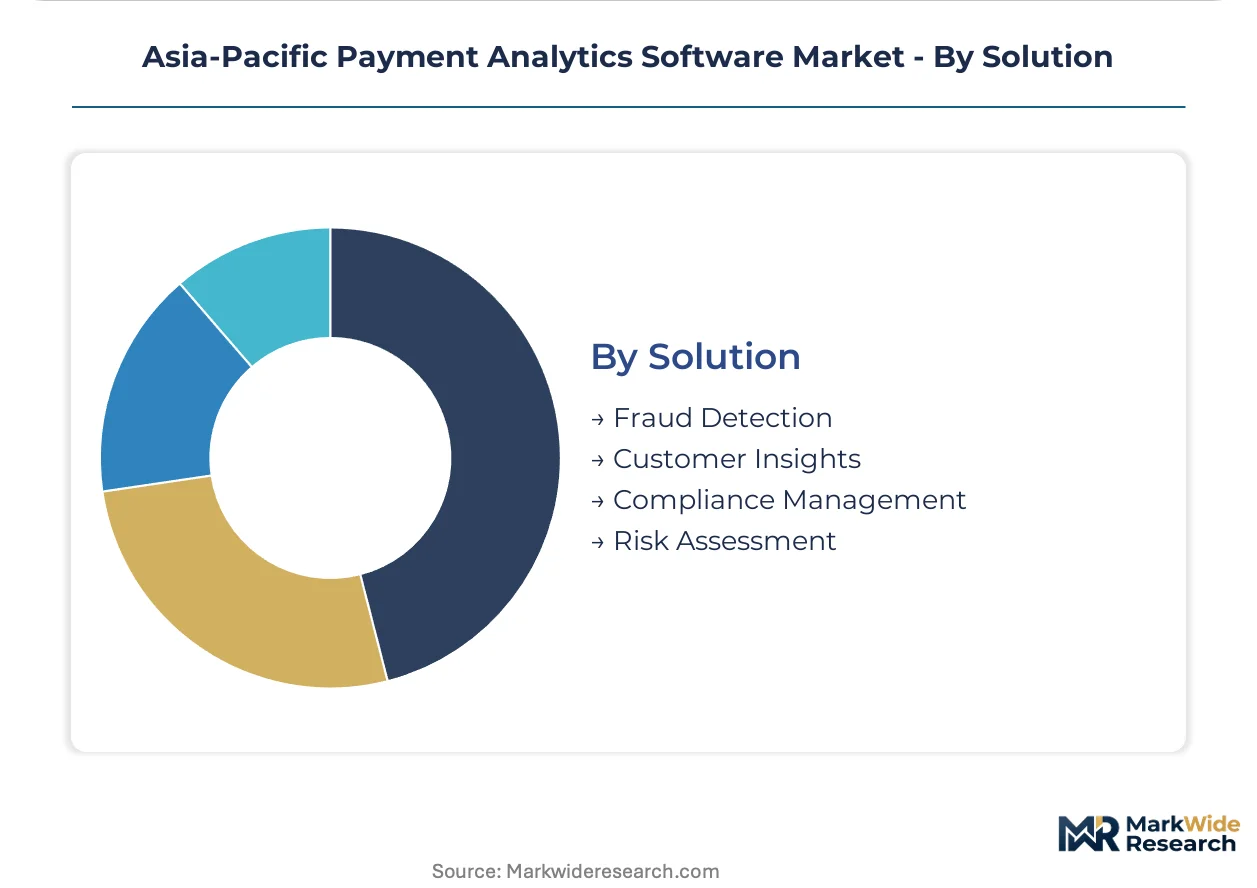
Solution:
Customer type segmentation separates compliance-driven procurement from performance-optimized purchasing, with risk assessment commanding premium pricing from institutions managing real-time authorization volumes.
- Fraud Detection:Real-time anomaly detection platforms ingest transaction streams across card networks, bank ledgers, and QR-code wallets to block unauthorized flows. Merchant acquirers across India demand outcome-based pricing tied to fraud reduction metrics rather than per-seat licenses.
- Customer Insights:Behavioral analytics engines normalize disparate data formats from buy-now-pay-later platforms and digital wallets into unified merchant intelligence. Australian open banking frameworks feed external analytics dashboards with consent-tracked data sharing.
- Compliance Management:Audit trail platforms implement immutable logging with cryptographic verification per Singapore MAS guidelines for payment system operators.
- Risk Assessment:Predictive models score transaction authorization probability, optimizing acceptance rates for revenue-sensitive merchants.
Fraud detection holds the largest share; customer insights gains share fastest as merchant acquiring competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI mandates granular transaction reporting that forces Indian banks to rebuild reconciliation engines around real-time data ingestion. Singapore's MAS guidelines prescribe audit trails for payment system operators. Australia's ACCC enforces open banking data sharing that feeds external analytics dashboards.
India
Domestic banks face compressed deadlines to upgrade legacy systems for UPI transaction volume surges. The Reserve Bank's Payments Vision framework mandates granular reporting that forces reconciliation engine modernization. Mumbai and Bangalore clusters concentrate vendor engineering talent for stream processing architectures.
Singapore
Financial institutions deploy private cloud instances to satisfy MAS technology risk management guidelines for operators above volume thresholds. The fintech sandbox expansion narrows positioning gaps between traditional banks and payment startups. The city-state anchors regional R&D centers for ASEAN corridor harmonization.
Australia
Retail banks operationalize ACCC Consumer Data Right enforcement into customer-facing analytics dashboards. Open banking frameworks compel consent-tracked data sharing that feeds external merchant intelligence. Sydney and Melbourne house the primary compliance consulting clusters for dashboard deployment.
Japan
Megabanks maintain on-premises installations to satisfy stringent data residency requirements that block multi-tenant cloud economics. METI guidelines influence technology procurement criteria for tamper-evident infrastructure. Tokyo concentrates the regional headquarters for legacy system integration specialists.
Vietnam
Rapid digital wallet adoption outpaces analytics vendor presence in merchant acquiring markets. The State Bank of Vietnam issues circulars governing payment intermediary licensing that shape vendor entry requirements. Ho Chi Minh City clusters fintech startups demanding localized fraud scoring capabilities.
Asia-Pacific Payment Analytics Software Market Competitive Landscape
Enterprise-grade transaction processors and creative cloud data architects split the market between operational infrastructure and merchant workflow integration. Consolidation pressures concentrate procurement decisions among financial institutions with multi-rail normalization requirements. Three archetypes dominate: legacy payment infrastructure specialists, cloud-native analytics platforms, and cross-border fraud scoring boutiques. Geographic expansion and API-based partnership networks constitute the dominant competitive moves for vendor positioning.
Within the enterprise infrastructure tier, ACI Payment Systems and Adobe occupy positions representing operational processing depth and creative cloud data architecture extension respectively. HiPay sits within the cross-border specialization segment. These three exemplify the strategic divergence between transaction processing anchoring, workflow analytics integration, and localized fraud scoring for European-Asia merchant corridors.
| Leading Market Players |
|---|
| Adobe |
| BlueSnap Corporate |
| Databox |
| Payfirma |
| Yapstone |
| HiPay |
| ProfitWell |
| CashNotify |
| ACI Payment Systems |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure concentration in Singapore and Sydney data centers anchors margin capture for payment analytics vendors serving ASEAN corridors. Japanese megabanks absorb premium single-tenant deployment costs that compress vendor margins while Australian mid-market retailers exploit elastic public cloud economics.
Pricing Analysis
Japan-Australia pricing spreads reach threefold multiples between on-premises sovereign installations and multi-tenant cloud subscriptions. SaaS-tiered pricing dominates mid-market procurement, with fraud detection modules commanding premium fees against compliance management baselines. Cost compression in cloud infrastructure tiers is intensifying because hyperscaler competition drives compute pricing downward. Mid-market retailers exhibit highest price sensitivity; Japanese financial institutions demonstrate lowest elasticity due to regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between US semiconductor suppliers and Singapore assembly facilities dominates hardware procurement risk for on-premises installations. Component sourcing concentrates in Taiwan for GPU accelerators, South Korea for high-bandwidth memory, and China for commodity server chassis. Real-time stream processing architectures rest on specialized networking hardware from single-source vendors. Distribution runs through systems integrators with MAS certification credentials for Singapore financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment analytics incumbents face substitution pressure from embedded finance platforms that collapse transaction processing and business intelligence into unified API layers. Defense requires repositioning around irreplaceable regulatory compliance depth.
For Market Incumbents: Insulate core relationships through vertical integration into sovereign cloud infrastructure, capturing data residency compliance as a moat against cloud-native entrants. Deepen API standardization investments for UPI and NPP rail harmonization. The threat of bank-led captive analytics development demands preemptive platform embedding.
For New Entrants and Emerging Players: Vietnam's merchant acquiring white-space, where digital wallet penetration exceeds analytics vendor presence by substantial margins, represents the most penetrable entry point. Australian open banking dashboard deployment, compressed by ACCC enforcement timelines, offers second-mover positioning. Go-to-market through MAS-certified systems integrators accelerates credibility transfer.
For Investors and Strategic Acquirers: Capital is best deployed toward cross-border fraud scoring boutiques with proven ASEAN corridor calibration. Long-term viability hinges on regulatory data localization mandates persisting across the analysis window. Watch for consolidation signals when tier-2 banks in Indonesia and the Philippines exhaust internal engineering capacity for real-time stack rebuilds.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | MAS-compliant infrastructure captures Japanese megabank procurement locked out of multi-tenant alternatives. |
| API-First Platform Integration | Native UPI and NPP connectivity eliminates reconciliation lag for Indian and Australian financial institutions. |
| Cross-Border Fraud Consortium | Shared scoring models across Singapore-Thailand-Malaysia corridors reduce false-positive rates for multi-rail merchants. |
| Outcome-Based Contracting | Fraud reduction guarantees restructure vendor economics toward performance-contingent revenue streams. |
| Embedded Analytics Acquisition | In-memory computing specialists collapse millisecond windows between authorization and merchant insight generation. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with payment technology executives, fraud risk officers, and regulatory compliance leads at financial institutions across India, Singapore, Australia, and Japan; and secondary validation through RBI circulars, MAS technology risk guidelines, ACCC Consumer Data Right determinations, and hyperscaler regional capex disclosures. Bottom-up transaction volume estimates triangulated against top-down software spend allocations.
Forecast inputs span deployment model, institution size tier, integration complexity, and regulatory jurisdiction cluster. CAGRs derive from elasticity-adjusted adoption curves across the projection horizon. Modeled variables include UPI transaction growth trajectories, open banking consent API penetration, and sovereign cloud capacity buildouts.
Macroeconomic conditions sit as an overlay; deviation in regional interest rate cycles, currency volatility against USD-denominated cloud contracts, or sudden regulatory relaxation of data localization would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Payment Processing Solutions Market
Payments
Retail POS Terminals Market
Payments
Payment Service Provider Market
Payments
Europe Payment Gateways Market
Payments
Electronic Cash Register Market
Payments
Instant Payments Market
Payments
India Payment Gateway Market
Payments
South Korea Real Time Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
North America POS Terminal Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Digital Transfer Services Market
Payments
Mexico POS Terminals Market
Payments
Mexico Payments Market
Payments
Sweden Payments Market
Payments
Digital Transaction Management Market