
 In-Vehicle Payment Services Market | 2026-2036
In-Vehicle Payment Services Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle Payment Services Market Analysis
Subscription bundling of fuel, parking, and toll payments into unified in-vehicle wallets is consolidating buyer choice around all-in-one platforms rather than discrete transactional apps. BMW leverages its Operating System 8 architecture to embed payment credentials directly into vehicle identity modules, while Mercedes-Benz Group AG sustains premium positioning through exclusive partnerships with fuel-station networks. Ford Motor Company anchors its strategy in commercial-fleet volume, competing on transaction-fee scale rather than consumer-facing brand premium.
In-vehicle payment services encompass secure, tokenized financial transaction systems embedded within automotive telematics and infotainment architectures, utilizing near-field communication, cellular V2X protocols, or dedicated short-range communications to authenticate and settle purchases without driver-initiated mobile device interaction. The primary commercial purpose is to reduce friction in recurring automotive expenditures—fuel, charging, parking, tolls—while generating recurring revenue streams for OEMs and service providers. Mobile wallet integration currently leads transaction volume among payment methods, though contactless payment infrastructure at fuel retailers is expanding fastest in deployment velocity. Electric vehicle segments concentrate margin pools in charging-network roaming agreements, whereas passenger cars dominate absolute transaction frequency.
The European Banking Authority's PSD3 framework and the United States Federal Trade Commission's emerging data-protection oversight are tightening consent requirements for vehicle-generated payment data, directly shaping OEM API-access policies and third-party fintech integration pathways. China's SAMR and Japan's METI have each issued distinct guidelines on automotive financial-data localization that fragment cross-border platform architecture. Stakeholders must monitor regulatory divergence on data-sovereignty rules as a decisive factor in platform build-versus-partner decisions across jurisdictions.
Market Dynamics
The Payment Services Directive framework is fragmenting platform architectures as automotive OEMs face divergent data-localization mandates across their operating jurisdictions.
Growth Catalysts
- PSD3 Consent Architecture:The European Banking Authority's tightened authentication standards are accelerating tokenized credential deployment across vehicle identity modules.
- Fleet Digitization:Commercial vehicle operators in the United States are consolidating fuel and toll expenditures into unified telematics dashboards.
- Cellular V2X Protocols:DSRC-to-C-V2X migration is enabling real-time payment authorization without driver mobile device interaction.
Market Restraints
- Data-Sovereignty Compliance Costs:China's SAMR and Japan's METI localization rules force redundant infrastructure builds for cross-border platforms.
- Retailer Network Fragmentation:Contactless terminal penetration at fuel stations remains uneven across rural United States corridors.
- Electric Charging Interoperability:Roaming agreement complexity between competing EV network operators delays transaction settlement standardization.
Strategic Opportunities
- Subscription Wallet Bundling:Unified fuel-parking-toll platforms are displacing discrete single-purpose applications among United States passenger vehicle owners.
- Embedded Insurance Integration:Real-time driving data streams enable usage-based policy pricing tied directly to in-vehicle payment rails.
- Commercial Fleet Telematics:Germany's logistics operators are piloting automated expense reconciliation through vehicle-integrated procurement systems.
Industry Challenges
- API Access Governance:OEMs must balance third-party fintech integration against FTC data-protection oversight requirements.
- Tokenization Latency:Edge-computing infrastructure gaps in older vehicle architectures delay payment authentication responses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle Payment Services Market |
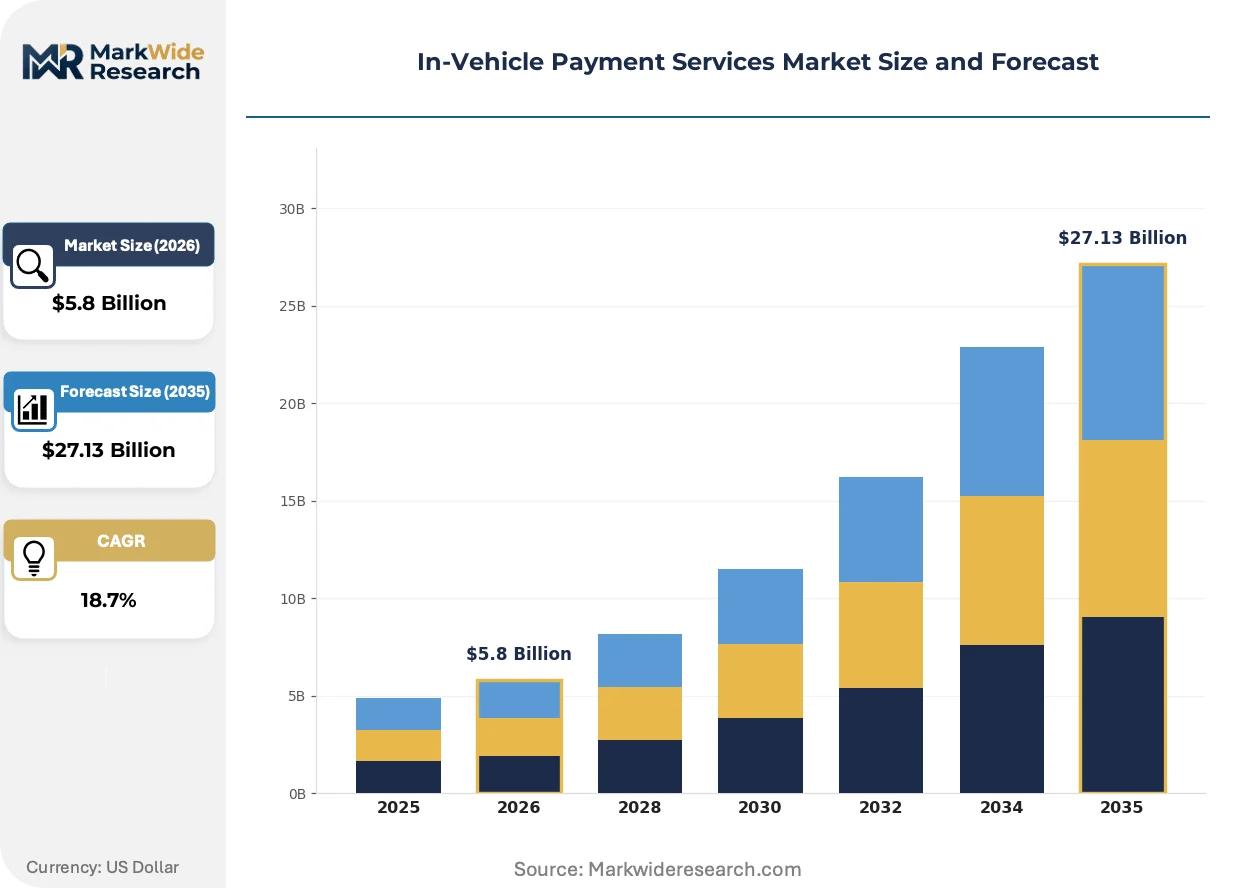
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $27.13 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Mobile Wallet, Contactless Payment, Cryptocurrency Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles Service Provider: Payment Processors, Automotive OEMs, Fintech Companies, Banks User Type: Individual Consumers, Fleet Operators, Ride-Sharing Services, Delivery Services |
| Companies Covered | BMW, Jaguar Land Rover Automotive, Honda Motor, General Motors, ZF, Ford Motor Company, Volkswagen, Mercedes-Benz Group AG, Hyundai Motor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle Payment Services Market Emerging Trajectories
Payment credential architecture is shifting from smartphone-dependent workflows toward embedded vehicle-native identity systems.
Software-defined vehicle platforms are modularizing payment service delivery. BMW's Operating System 8 and comparable architectures from Mercedes-Benz Group AG embed financial credentials directly into hardware security modules. Automotive OEMs are adopting this approach to capture recurring transaction-fee revenue streams previously retained by mobile wallet providers.
GDPR and emerging FTC data-protection oversight are tightening consent requirements for vehicle-generated payment telemetry. The European Banking Authority's PSD3 framework mandates explicit user authorization for each data-sharing instance with third-party fintech providers. OEMs are responding by restricting API access tiers and building captive payment ecosystems.
Fleet procurement managers are consolidating vendor relationships around all-in-one mobility expense platforms. Discrete fuel-card, toll-transponder, and parking-app subscriptions are contracting into unified subscription wallets. This concentration is most visible among United States commercial operators managing mixed internal-combustion and electric vehicle fleets.
In-Vehicle Payment Services Market Segmentation
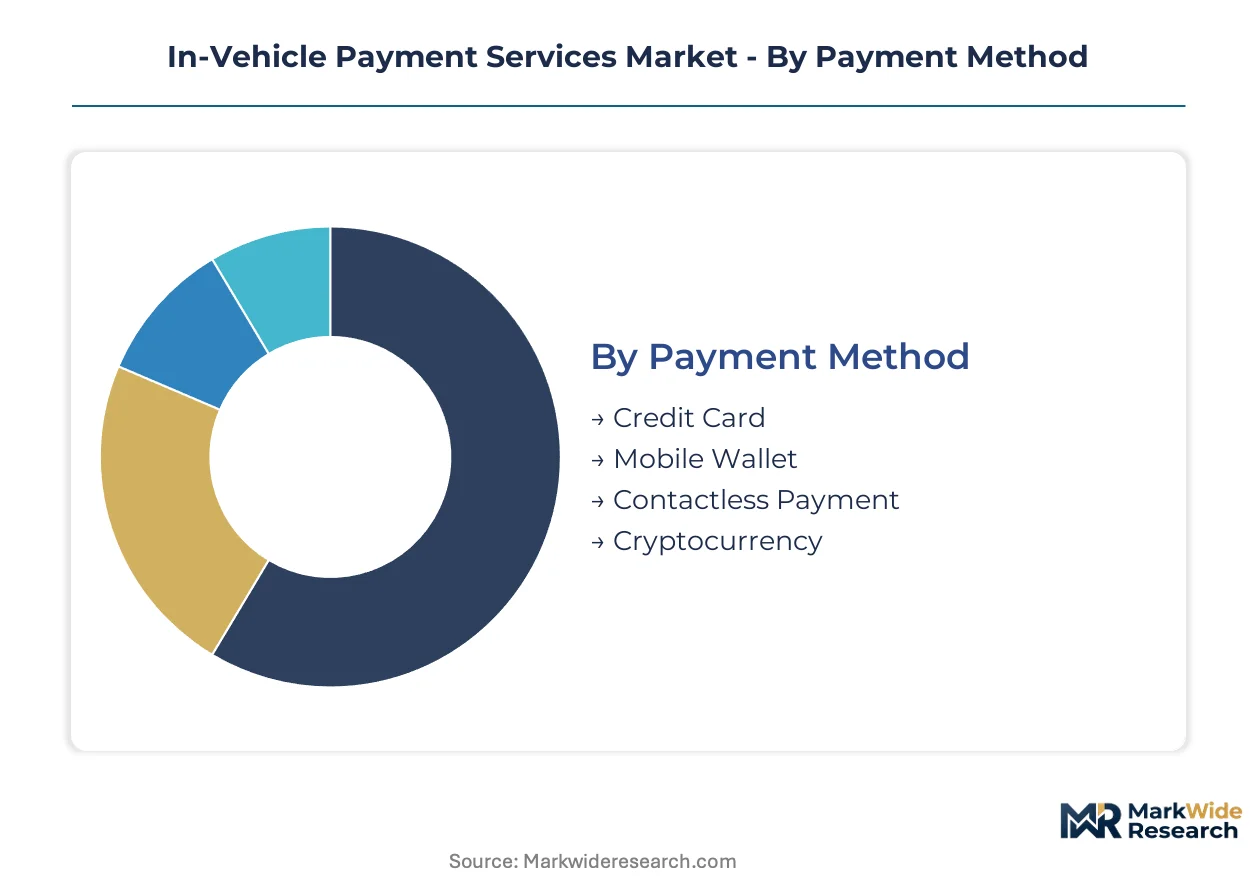
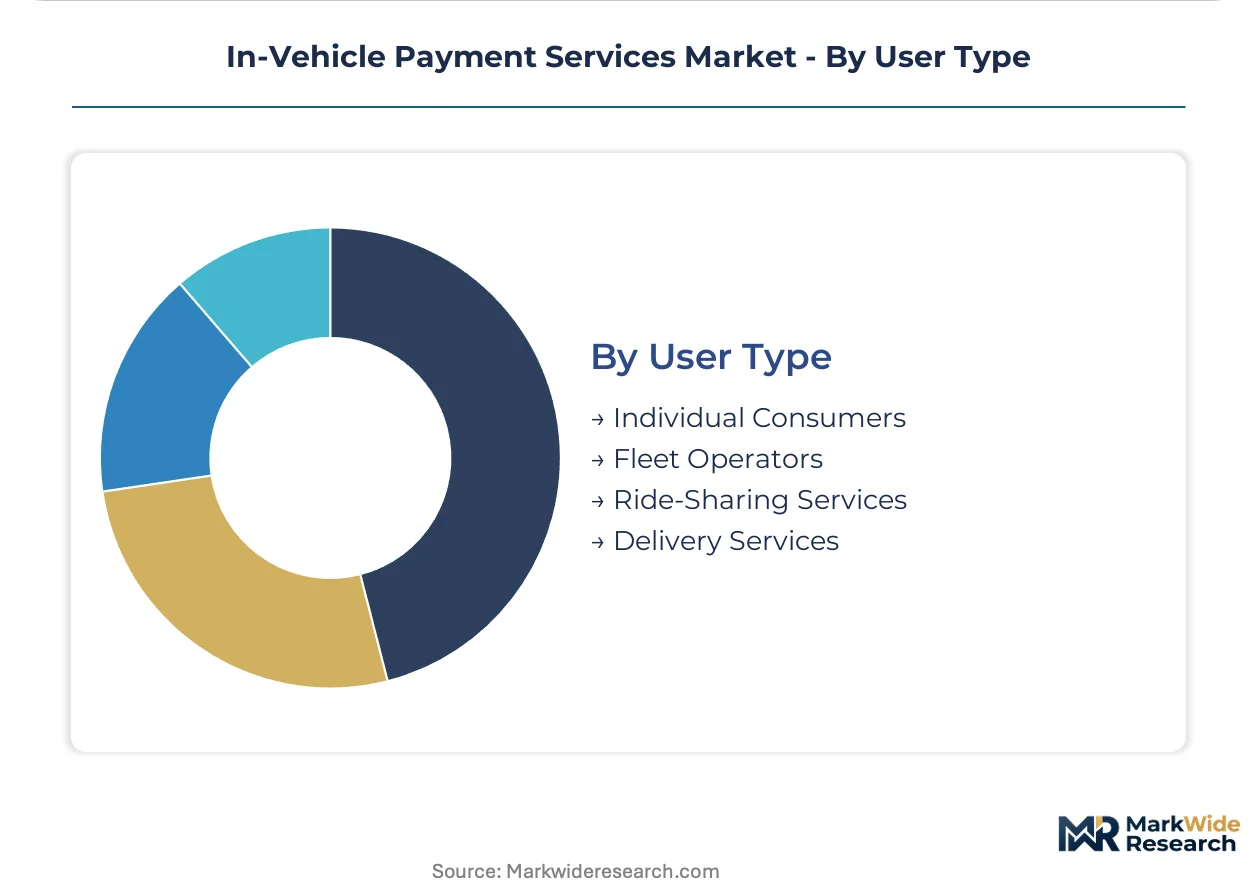
In-vehicle payment services fragment across four distinct dimensions that shape platform architecture, revenue models, and regulatory exposure. Payment method and vehicle type determine hardware integration requirements, while service provider and user type govern go-to-market strategies and data governance frameworks.
Payment Method:
Buyer differentiation in this category hinges on authentication friction, tokenization infrastructure, and retailer terminal compatibility.
- Mobile Wallet:Smartphone-tethered credential storage dominates transaction volume through Apple Pay and Google Pay integrations. United States passenger vehicle owners concentrate demand here due to existing mobile payment habit formation and minimal OEM-side infrastructure investment.
- Credit Card:Direct card-on-file provisioning into vehicle identity modules enables recurring billing without device dependency. Fleet operators in Germany prioritize this method for automated expense reconciliation and centralized procurement controls.
- Contactless Payment:Near-field communication terminals at fuel retailers are expanding fastest in deployment velocity across urban United States corridors. NFC credential transmission eliminates manual authentication steps for fuel and parking transactions.
- Cryptocurrency:Blockchain-based settlement remains experimental, with limited pilot programs among luxury vehicle segments seeking differentiated ownership experiences. Regulatory uncertainty from the SEC and European Banking Authority constrains mainstream adoption.
Mobile wallet leads volumes today; contactless payment infrastructure is gaining share fastest.
Vehicle Type:
Powertrain architecture and price positioning create divergent margin structures and charging-network integration requirements.
- Electric Vehicles:Roaming agreements between competing charging network operators concentrate margin pools in interoperability fees and subscription bundling. China's SAMR data-localization mandates force redundant platform builds for cross-border EV charging transactions.
- Passenger Cars:Absolute transaction frequency remains highest in this segment, driven by fuel purchases, parking, and toll payments. United States market penetration of connected-vehicle telematics supports embedded payment credential deployment.
- Commercial Vehicles:Fleet digitization in the United States consolidates fuel and toll expenditures into unified telematics dashboards. Ford Motor Company anchors strategy here, competing on transaction-fee scale rather than consumer brand premium.
- Luxury Vehicles:Exclusive fuel-station network partnerships sustain premium positioning through differentiated service tiers. BMW's Operating System 8 and Mercedes-Benz architectures embed credentials directly into hardware security modules.
Passenger cars anchor absolute transaction counts; electric vehicles command the steepest expansion trajectory in platform investment.
Service Provider:
Control over customer data and API access tiers determines competitive positioning against regulatory tightening.
- Automotive OEMs:BMW, Mercedes-Benz, and Ford embed financial credentials into vehicle-native identity systems to capture recurring transaction-fee revenue. FTC data-protection oversight and PSD3 consent requirements are restricting third-party fintech API access.
- Fintech Companies:Specialized providers compete on user experience and cross-platform wallet portability. European Banking Authority authentication standards are accelerating tokenized credential deployment partnerships with OEMs.
- Payment Processors:Visa and Mastercard network infrastructure underpins settlement rails across all vehicle-integrated transaction types. Processor relationships determine cross-border transaction cost structures.
- Banks:Traditional financial institutions leverage existing customer relationships and regulatory compliance frameworks. Open-banking mandates in multiple jurisdictions are accelerating interoperability standard adoption.
OEMs control the fastest-growing share of customer relationships; payment processors retain settlement infrastructure dominance.
User Type:
Transaction scale and procurement centralization separate enterprise buyers from fragmented individual demand.
- Fleet Operators:Commercial vehicle managers in North America and Europe consolidate vendor relationships around all-in-one mobility expense platforms. Unified fuel-parking-toll subscriptions displace discrete single-purpose applications.
- Individual Consumers:Subscription bundling of recurring automotive expenditures is consolidating buyer choice around unified wallet platforms rather than discrete transactional apps.
- Ride-Sharing Services:High-frequency transaction volumes and driver reimbursement workflows demand automated expense categorization and real-time settlement. Platform economics favor low per-transaction cost structures.
- Delivery Services:Last-mile logistics operators prioritize fuel cost optimization and route-integrated payment authorization. Vehicle-integrated procurement systems are piloting automated reconciliation in Germany.
Fleet operators are expanding most quickly as an adopter category; individual consumers retain the largest absolute user base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The in-vehicle payment services industry traces its commercial origins to early toll-collection automation in the United States during the 1990s, with European and Asian markets subsequently developing distinct regulatory frameworks for automotive-integrated commerce.
United States
Connected-vehicle penetration and fuel-retailer network digitization drive concentrated demand. The FTC's emerging data-protection oversight tightens consent requirements for vehicle-generated payment telemetry. Detroit's automotive cluster anchors embedded credential deployment through hardware security module integration.
Germany
Logistics operators pilot automated expense reconciliation through vehicle-integrated procurement systems. The EU's Payment Services Directive mandates explicit user authorization for data-sharing with third-party fintech providers. Stuttgart and Munich host competing OEM strategies around premium fuel-station network partnerships.
China
Electric vehicle charging-network roaming agreements concentrate margin pools in interoperability fees. SAMR data-localization rules force redundant infrastructure builds for cross-border platform architecture. Shanghai's Yangtze River Delta cluster dominates EV charging payment standard development.
Japan
Luxury vehicle segments experiment with differentiated ownership experiences through blockchain settlement pilots. METI guidelines on automotive financial-data localization shape domestic platform architecture decisions. Nagoya's Chubu region sustains hardware security module manufacturing for embedded credential systems.
United Kingdom
Open-banking frameworks accelerate interoperability standards for automotive-integrated transactions. The Financial Conduct Authority implements PSD3 authentication requirements for tokenized credential deployment. London's fintech corridor drives mobile wallet integration partnerships with automotive OEMs.
In-Vehicle Payment Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across hardware-software integration depth. The vendor base stratifies between captive OEM ecosystems and third-party fintech portability specialists. Three archetypes dominate: integrated automotive OEMs with operating system control, specialized payment processors with network infrastructure, and cross-platform wallet providers with user experience focus. Strategic moves concentrate on API access tier restriction and subscription wallet bundling consolidation.
Among Germany-based automotive groups, Mercedes-Benz Group AG and BMW exemplify premium-tier positioning through exclusive fuel-station network partnerships and embedded credential architecture. Ford Motor Company anchors the commercial-fleet volume segment, competing on transaction-fee scale. These three entities represent divergent strategic vectors: captive ecosystem control, premium service tiering, and fleet-oriented cost efficiency.
| Leading Market Players |
|---|
| BMW |
| Jaguar Land Rover Automotive |
| Honda Motor |
| General Motors |
| ZF |
| Ford Motor Company |
| Volkswagen |
| Mercedes-Benz Group AG |
| Hyundai Motor |
| Others |
Supply Flow & Price Mechanics
Captive credential integration through hardware security modules anchors supply positioning for automotive OEMs while concentrating pricing power in embedded transaction-fee structures. Germany's automotive clusters and United States semiconductor fabrication facilities feed this vertical control architecture, with tokenization infrastructure costs passed through subscription-tier pricing models.
Pricing Analysis
Subscription-based wallet bundling stratifies across premium, standard, and economy service tiers based on credential storage location and after-sales support depth. Price differentiation hinges on hardware security module certification grade and transaction volume scale commitments from fleet operators. Cost compression in the standard tier intensifies because payment processors compete for network infrastructure contracts. Fleet operators exhibit highest price sensitivity due to per-transaction fee accumulation across thousand-vehicle deployments, while luxury vehicle owners absorb premium tiers for exclusive fuel-station network access.
Supply Chain Analysis
Reverse-logistics flows for obsolete telematics hardware and decommissioned vehicle identity modules create secondary refurbishment channels in Japan and South Korea. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with hardware security module assembly tethered to Nagoya's Chubu region and Stuttgart's automotive corridor. Single-source vulnerability runs through advanced chip lithography equipment. Distribution runs through Tier 1 automotive suppliers integrating payment modules into infotainment head units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in in-vehicle payment services rests on tokenization infrastructure cost-down curves and fleet-operator premium-tier migration toward unified subscription wallets.
For Market Incumbents: Cement API access tier restrictions against third-party fintech encroachment under FTC data-protection oversight. Expand hardware security module capacity in Germany to capture premium credential deployment. Defensive consolidation through exclusive fuel-station network partnerships insulates against payment processor disintermediation. For New Entrants and Emerging Players: Begin with commercial fleet telematics integration in the United States, where unified expense platform penetration remains incomplete. White-space concentration sits in automated expense reconciliation for mixed internal-combustion and electric vehicle fleets. Go-to-market leverage rests on low per-transaction cost structures against Ford Motor Company's volume-scale positioning. For Investors and Strategic Acquirers: Roll-up economics work for specialized fintech wallet providers because PSD3 consent architecture fragments platform architectures and creates acquisition targets with stranded API access agreements. Long-term viability favors entities with embedded insurance integration capabilities. Monitor cellular V2X protocol deployment velocity as inflection indicator for real-time payment authorization market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Integration | BMW's Operating System 8 embeds credentials directly into vehicle-native identity systems, capturing recurring transaction-fee revenue from mobile wallet providers. |
| Fleet Telematics Consolidation | Ford Motor Company anchors commercial strategy in unified fuel-parking-toll dashboards, competing on transaction-fee scale across North American logistics operators. |
| Charging Network Roaming Agreements | Electric vehicle interoperability fees concentrate margin pools in China, where SAMR data-localization rules force redundant infrastructure builds. |
| PSD3 Consent Architecture Compliance | European Banking Authority authentication standards accelerate tokenized credential deployment across vehicle identity modules in Germany. |
| Subscription Wallet Bundling | United States passenger vehicle owners consolidate buyer choice around all-in-one platforms, displacing discrete fuel-card and parking-app subscriptions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary data collection engaged automotive OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, payment processor network strategists, and regulatory compliance officers at financial authorities. Secondary validation drew from SEC filings by listed automotive groups, European Banking Authority PSD3 consultation documents, FTC data-protection guidance releases, and vehicle production databases. Bottom-up transaction volume estimates triangulated against top-down market sizing from connected-vehicle penetration forecasts.
Segment-weighting approaches distributed value across payment method, vehicle type, service provider, and user type dimensions. The analytical framework modeled propulsion architecture shifts, credential storage migration patterns, and fleet digitization trajectories across the projection horizon. CAGRs derived from regression analysis of historical transaction velocity against telematics deployment curves. Industry-specific inputs included cellular V2X protocol adoption timelines and open-banking framework implementation schedules.
Several conditions sit outside the modeled scope, including cryptocurrency settlement regulatory clarity, quantum-resistant encryption standard transitions, and autonomous vehicle payment authorization without human oversight. Forecasts reflect assumptions about PSD3 implementation consistency and FTC enforcement intensity. Practitioners should monitor roaming agreement standardization between competing EV network operators and edge-computing infrastructure buildout in legacy vehicle architectures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Clearing Houses and Settlements Market
Payments
Philippines Remittance Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
Electronic Cash Register Market
Payments
Master Recharge API Market
Payments
Crypto Payment Gateway Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Global Payment Monitoring Market
Payments
Australia Payments Market
Payments
India Real Time Payments Market
Payments
United States Payment Gateways Market
Payments
United States Real Time Payments Market
Payments
Online Payment Gateway Market
Payments
Smart Payment Market
Payments
Africa Virtual Cards Market
Payments
Japan Virtual Cards Market