
 South Korea Mobile Payment Market | 2026-2036
South Korea Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Mobile Payment Market Analytics
Seoul's fintech corridor is rewriting how domestic payment infrastructure scales across East Asia. Kakao Pay leverages its messaging super-app origin to sustain merchant lock-in across transportation and retail verticals. Samsung Electronics anchors hardware-integrated payment security through Knox-enabled tokenization, while Viva Republica competes via specialized credit and investment products embedded within its Toss platform.
A mobile payment system constitutes a digital financial transaction mechanism enabling fund transfer through near-field communication, tokenized credentials, host card emulation, or QR-based authentication protocols, primarily facilitating commercial exchange without physical currency. The technology serves retail settlement, peer-to-peer remittance, and subscription billing through encrypted credential vaulting and real-time authorization networks. Mobile wallet and QR code payment types command dominant transaction flow due to their minimal merchant hardware requirements and seamless integration with loyalty programs. Platform type segmentation reveals Android's entrenched position given Samsung's domestic manufacturing scale, though iOS maintains premium user monetization through Apple Pay's concentrated high-value transaction base.
MFDS oversight of biometric authentication standards, BIS certification for payment terminal security, and FSC open banking directives collectively shape product compliance requirements and market access conditions for new entrants. The Personal Information Protection Act imposes stringent data localization mandates that increase infrastructure costs for foreign platform operators seeking Korean consumer access. Stakeholders must monitor evolving central bank digital currency pilot frameworks and real-time settlement system interoperability rules to anticipate competitive displacement risks.
Market Dynamics
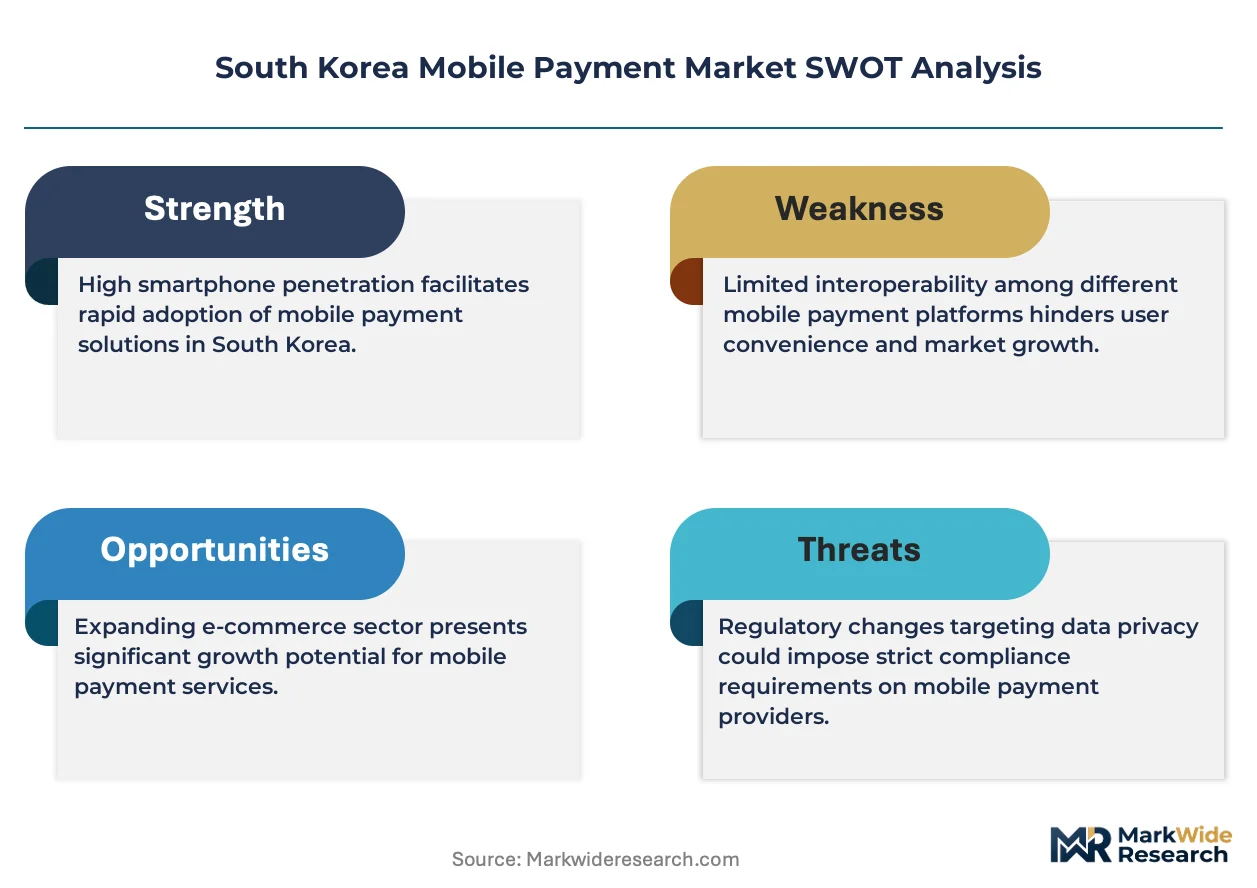
The Financial Services Commission's open banking mandate has forced domestic platforms to dismantle proprietary silos, creating interoperability requirements that reshape competitive moats across the Seoul metropolitan corridor.
Growth Catalysts
- Zero-rating policy:The FSC's exemption of financial apps from data caps eliminates friction for rural user acquisition. Mobile wallet penetration accelerates in secondary cities previously constrained by connectivity costs.
- Small and medium enterprise digitization:Merchant onboarding subsidies from the Korea SMEs and Startups Agency compress hardware investment barriers. Street vendors and neighborhood retailers abandon cash settlement at unprecedented velocity.
- Tokenized credential vaulting:Host card emulation technology embedded in Samsung Knox security architecture enables offline transaction authorization. Transportation networks and convenience chains deploy contactless terminals without dedicated network infrastructure.
Market Restraints
- Data localization mandates:The Personal Information Protection Act requires domestic server deployment for biometric authentication data. Foreign platform operators face infrastructure cost premiums exceeding comparable ASEAN markets.
- Android OS concentration:Samsung's domestic manufacturing scale entrenches single-ecosystem dependency. iOS penetration remains structurally capped in the premium segment, limiting platform diversification.
- Biometric certification timelines:MFDS authentication standards impose extended validation cycles for facial recognition payment systems. Product launch windows compress against regulatory review queues.
Strategic Opportunities
- Central bank digital currency integration:The Bank of Korea's wholesale CBDC pilot creates settlement infrastructure for platform operators. Early participants capture interoperability advantages in future retail digital won distribution.
- Busan fintech cluster:The city's regulatory sandbox exemptions enable experimental cross-border remittance corridors. Southeast Asian worker remittance flows represent underpenetrated transaction volume.
- Embedded finance convergence:Mobility-as-a-service platforms integrate ride-hailing, parking, and transit payments into unified wallet experiences. Transportation verticals become customer acquisition channels for credit and investment products.
Industry Challenges
- Legacy core banking integration:Regional banks maintain COBOL-based transaction processing systems. API connectivity to modern mobile front-ends requires middleware development with specialized system integrators.
- Cross-platform token standardization:Competing QR code formats between Kakao Pay, Naver Pay, and Toss fragment merchant terminal requirements. Retailers deploy multiple scanning hardware or sacrifice transaction completion rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Mobile Payment Market |
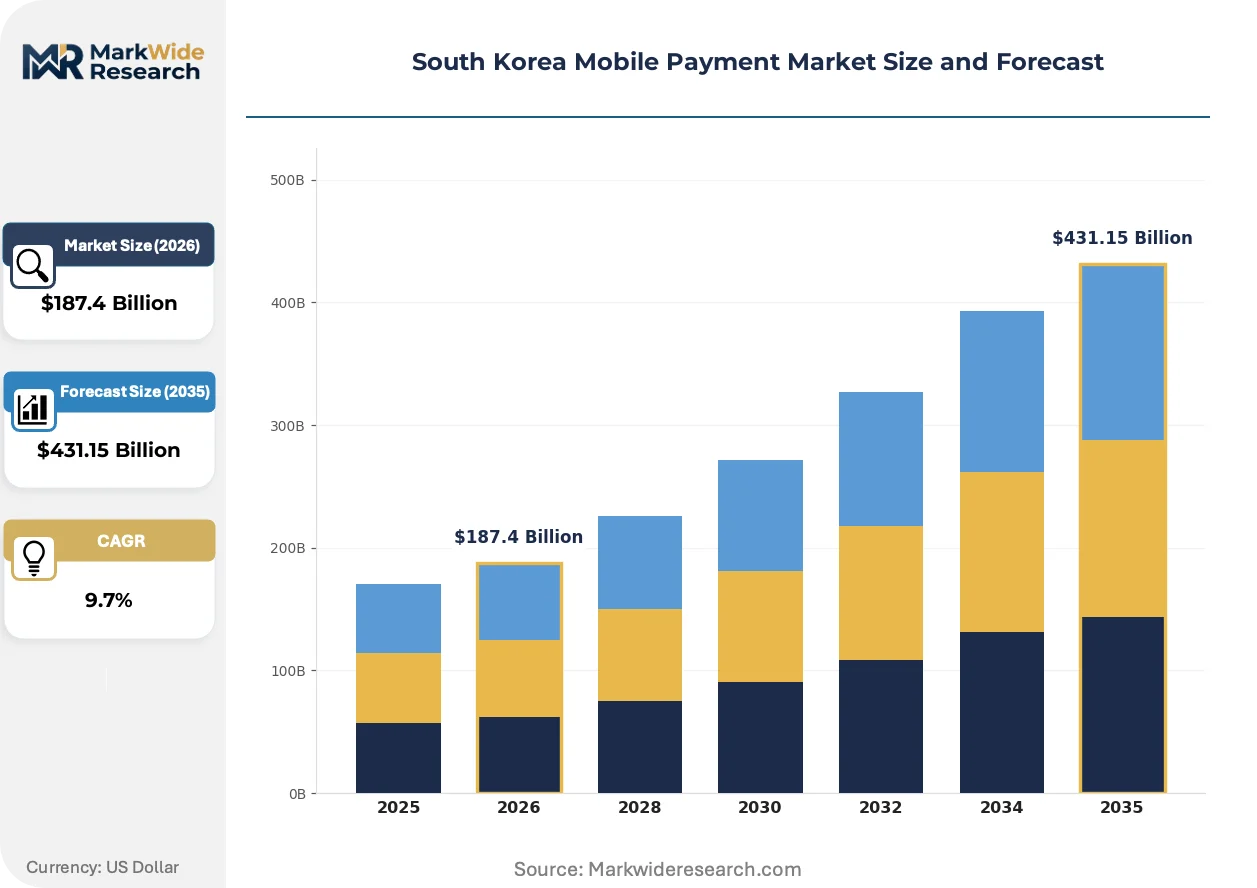
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Card, Debit Card, Mobile Wallet, QR Code User Demographic: Millennials, Gen Z, Business Professionals, Seniors Transaction Volume: Low Volume, Medium Volume, High Volume, Very High Volume Platform Type: iOS, Android, Web, Others |
| Companies Covered | Viva Republica, Apple, Kakao Pay, Visa, Google, Naver Corporation, NHN PAYCO, MasterCard, Samsung Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Mobile Payment Market Evolving Landscape
Payment authentication architecture is migrating from hardware-dependent security models toward software-based cryptographic enclaves, compressing the traditional smart card supply chain while elevating platform operator control over credential lifecycle management.
Host card emulation technology is migrating from NFC-only deployment toward multi-protocol stacks supporting both contactless and QR-based authentication. Transit authorities in Gyeonggi Province and Daegu Metropolitan City are adopting unified terminals that accept both credential types, reducing infrastructure duplication. The technology is migrating from premium smartphone models toward mid-tier Android devices, expanding addressable user bases beyond early adopter demographics.
The FSC's open banking directive mandates standardized API disclosure for account aggregation services. Financial institutions must expose transaction history and balance data to licensed third-party providers, eroding data monopolies that historically protected incumbent payment platforms. Retail banking divisions are responding by accelerating proprietary super-app development, embedding non-payment services to maintain customer engagement.
Merchant acquisition patterns are rotating from hardware-heavy POS terminal deployment toward software-only QR acceptance. Convenience store chains and quick-service restaurants in Seoul's commercial districts now prioritize tableside and counter-top QR displays over integrated payment devices. The behavioral shift concentrates most visibly in the food delivery vertical, where rider-mediated cash collection has collapsed in favor of in-app prepaid settlement.
South Korea Mobile Payment Market Segmentation
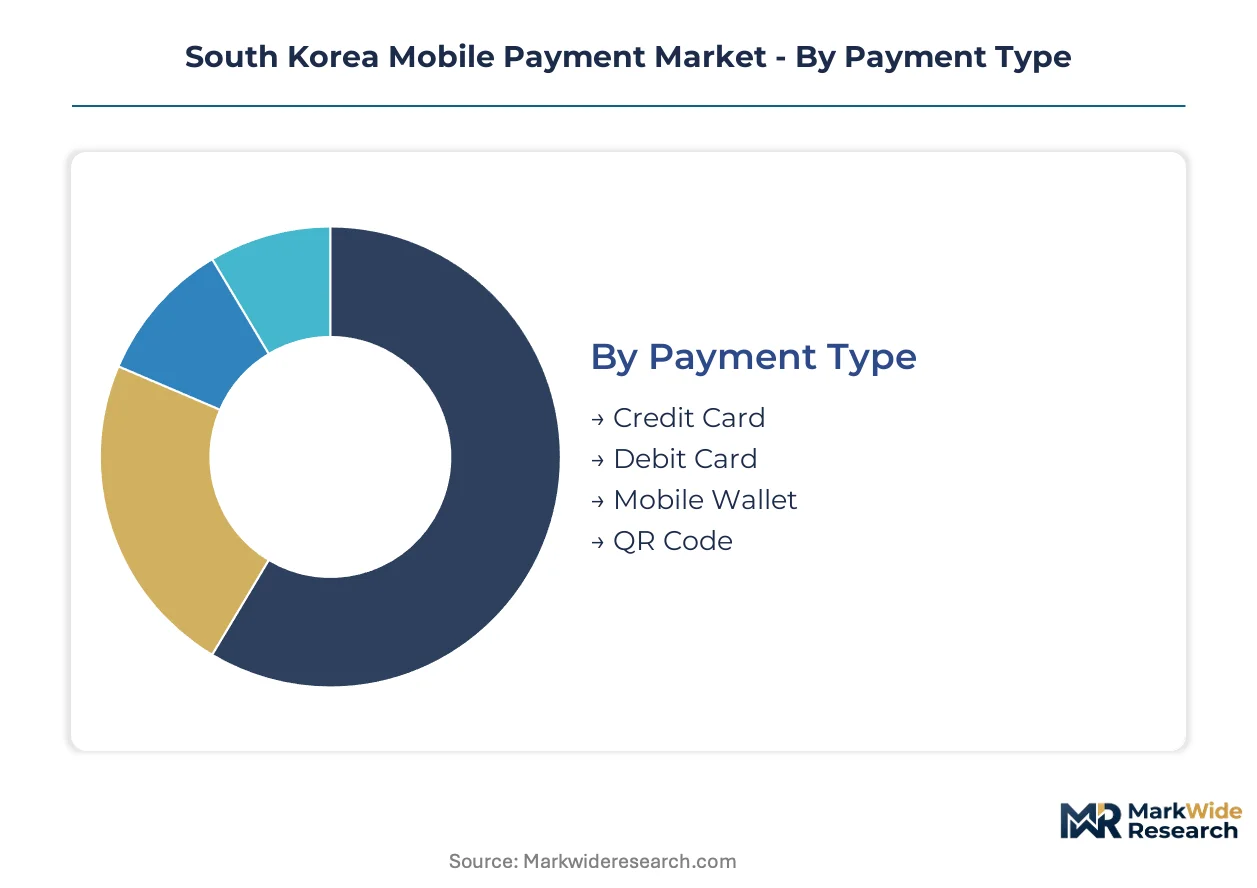
Segmentation in South Korea's mobile payment market reveals how transaction behavior fragments across credential types, generational adoption curves, and platform ecosystems. These divisions expose where infrastructure investments concentrate and which user cohorts drive monetization velocity.
Payment Type:
Mobile wallets and QR code settlements turn over transaction volumes fastest as merchants abandon hardware-dependent terminals, while credit card tokenization maintains slower refresh cycles tied to credential reissuance timelines.
- Mobile Wallet:Software-based credential vaulting enables peer-to-peer transfers, transit payments, and merchant settlement through host card emulation. Seoul's convenience store chains and quick-service restaurants deploy QR acceptance at counter-top displays, eliminating dedicated POS hardware. Small and medium enterprises in Gyeonggi Province accelerate adoption through Korea SMEs and Startups Agency subsidy programs.
- QR Code:Optical authentication protocols minimize merchant infrastructure requirements through static or dynamic barcode generation. Street vendors and neighborhood retailers across the Seoul metropolitan corridor replace cash handling with smartphone-based acceptance. FSC zero-rating policies on financial apps remove data cost barriers for rural merchant onboarding.
- Credit Card:Tokenized PAN credentials embedded in secure elements enable high-value transaction authorization with issuer liability protection.
- Debit Card:Direct account-linked settlement avoids revolving credit infrastructure, concentrating demand among budget-conscious demographics and subscription billing verticals.
Mobile Wallet anchors the volume base while QR Code gains share at the steepest rate.
User Demographic:
Generational adoption curves separate digital-native cohorts with seamless super-app integration from demographic segments requiring simplified interfaces and assisted onboarding pathways.
- Gen Z:Native super-app users conduct transactions within embedded messaging, gaming, and social commerce environments without conscious platform switching. Busan fintech cluster sandbox programs target this cohort with experimental cross-border remittance features for Southeast Asian worker communities.
- Millennials:Primary household financial managers balance convenience against credit optimization, driving demand for integrated loyalty aggregation and subscription management tools.
- Business Professionals:Expense reporting integration and corporate card program compatibility shape platform selection criteria for reimbursed commercial spending.
- Seniors:Simplified authentication flows and voice-guided interfaces address biometric certification barriers under MFDS oversight timelines.
Millennials sustain the revenue core while Gen Z expands most quickly through embedded finance convergence.
Transaction Volume:
Volume tiering distinguishes micropayment infrastructure optimized for speed and low friction from high-value settlement requiring enhanced authentication and regulatory reporting compliance.
- High Volume:Frequent low-value transactions across transportation, convenience retail, and food delivery verticals demand sub-second authorization latency. Transit authorities in Daegu Metropolitan City deploy unified terminals accepting both contactless and QR credentials without network dependency.
- Very High Volume:Merchant aggregators and platform operators process batched settlements across thousands of micro-transactions, requiring real-time gross settlement system integration with Bank of Korea infrastructure.
- Medium Volume:Periodic utility billing, insurance premiums, and subscription renewals dominate this tier with scheduled pull authorization patterns.
- Low Volume:Infrequent discretionary purchases and trial conversions concentrate customer acquisition cost sensitivity and onboarding friction challenges.
High Volume dominates transaction count while Very High Volume climbs fastest through merchant aggregator consolidation.
Platform Type:
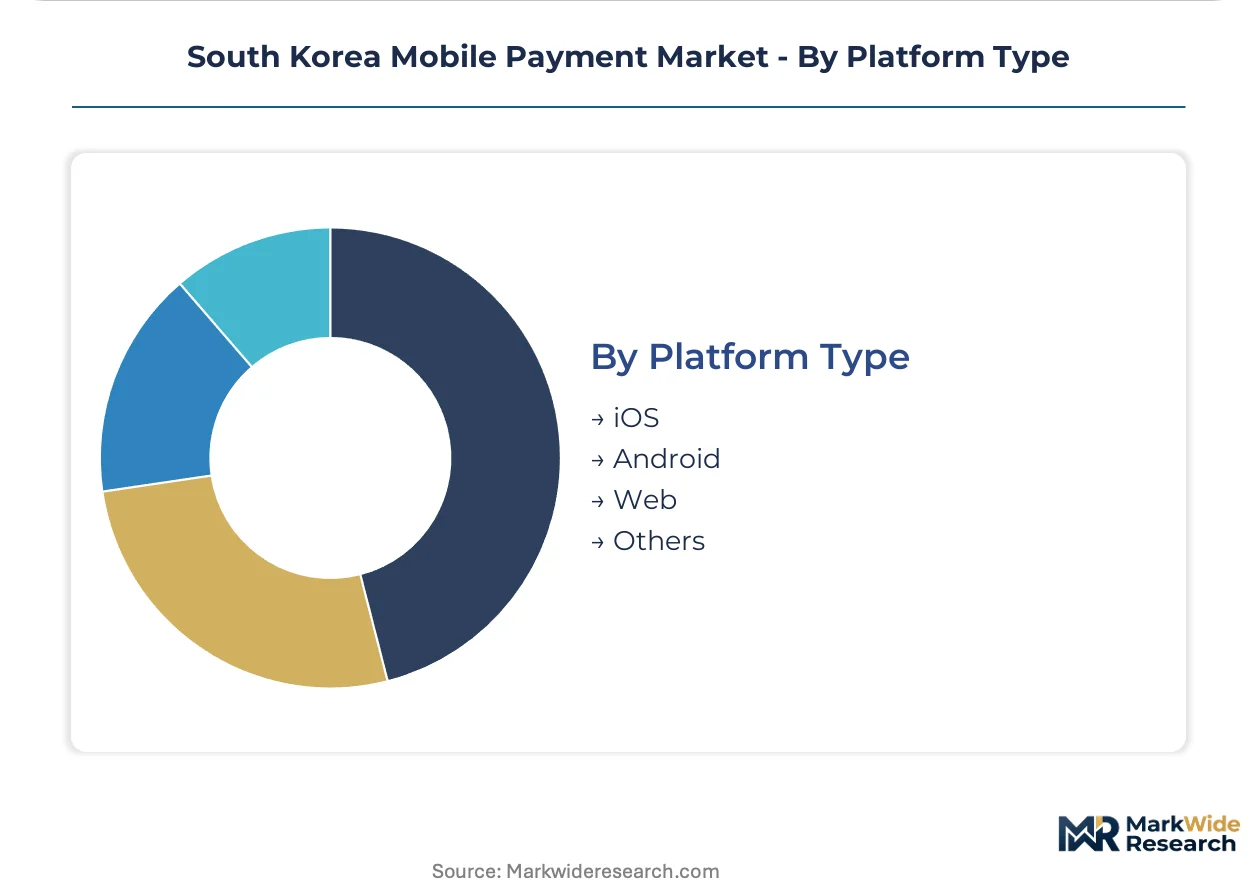
Operating system concentration reflects Samsung's domestic manufacturing scale against Apple's premium segment capture, with web-based settlement addressing interoperability gaps.
- Android:Knox-enabled hardware security modules and host card emulation dominate mid-tier device deployment across transportation and retail terminal networks. Samsung Electronics' domestic production entrenchment creates single-ecosystem dependency with limited iOS diversification.
- iOS:Premium user monetization concentrates in high-value transactions with Apple Pay's biometric authentication and device-specific tokenization. Personal Information Protection Act data localization mandates increase infrastructure costs for foreign platform operators relative to domestic competitors.
- Web:Browser-based settlement bridges platform fragmentation for cross-device consistency and merchant portal integration.
- Others:Proprietary embedded systems and IoT device payment modules serve specialized vending and unattended retail environments.
Android anchors installed base volume while iOS captures premium transaction value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure investment clusters heavily in the Seoul metropolitan corridor, with Busan and Daegu emerging as secondary fintech nodes through regulatory sandbox exemptions and specialized transit payment deployments.
Seoul Capital Area
Super-app ecosystems and merchant aggregator platforms concentrate transaction volume across Gyeonggi Province and Incheon. The Financial Services Commission's open banking mandates force interoperability between Kakao Pay, Naver Pay, and Toss. Songdo International Business District hosts testbeds for central bank digital currency integration with retail settlement rails.
Busan-Ulsan
Southeast Asian worker remittance corridors drive specialized cross-border payment demand through the Busan fintech cluster. FSC sandbox exemptions enable experimental blockchain settlement pilots for migrant financial services. Haeundae district merchant networks adopt QR-first acceptance for tourism and hospitality verticals.
Daegu-Gyeongbuk
Transit authority modernization programs deploy unified NFC-QR terminals across metropolitan rail and bus networks. MFDS biometric certification timelines slow facial recognition payment rollout in regional banking branches. Daegu Metropolitan City partners with platform operators for offline-capable host card emulation in subway stations.
Daejeon-Sejong
Government complex proximity attracts regulatory technology firms serving MFDS and FSC compliance automation. Sejong City's planned administrative functions generate public sector procurement for integrated payment and identification systems. Korea SMEs and Startups Agency subsidies accelerate merchant digitization in neighboring rural counties.
Gwangju-Honam
Agricultural cooperative banking networks lag in API connectivity to mobile front-ends. Zero-rating policies on financial apps remove data cost barriers for farmer and fishery cooperative members. Honam region convenience chains prioritize software-only QR acceptance over integrated POS hardware deployment.
South Korea Mobile Payment Market Competitive Landscape
Domestic super-app operators and global technology platforms split the market along ecosystem control and premium hardware integration vectors. Samsung Electronics anchors hardware-integrated security through Knox-enabled tokenization, while Kakao Pay and Toss compete via messaging-origin merchant lock-in and specialized credit products. Consolidation pressure concentrates around open banking interoperability mandates and central bank digital currency pilot participation.
Within the domestic platform tier, Kakao Pay, Toss operator Viva Republica, and Naver Corporation exemplify super-app convergence strategies embedding payment, credit, and investment functions within high-frequency consumer touchpoints. Samsung Electronics occupies a position at the hardware-integrated end through device-native security architecture and transportation network terminal deployments. Global technology platforms Apple and Google sit within the premium and mid-tier device ecosystem layers respectively, constrained by Personal Information Protection Act data localization requirements that inflate infrastructure costs relative to domestic competitors.
| Leading Market Players |
|---|
| Viva Republica |
| Apple |
| Kakao Pay |
| Visa |
| Naver Corporation |
| NHN PAYCO |
| MasterCard |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Samsung Electronics' domestic Knox security module production concentrates hardware-integrated credential vaulting capabilities within South Korea, anchoring margin pools in device-native tokenization services rather than standalone software licensing. This upstream concentration forces payment platform operators to negotiate access terms for biometric authentication enclaves, compressing pricing power for pure-play wallet providers while elevating hardware-anchored revenue streams.
Pricing Analysis
The Personal Information Protection Act dictates the pricing tier structure across South Korea's mobile payment infrastructure, imposing domestic server deployment costs that stratify platform economics. Three-tier pricing structure across premium biometric-authenticated, standard tokenized, and economy QR-code settlement levels separates merchants by transaction value and compliance burden. Price differentiation rests on MFDS certification timelines and FSC open banking API access tiers. Cost compression in the economy QR tier is intensifying because zero-rating policies eliminate data friction for rural merchant onboarding. Small street vendors exhibit highest price sensitivity, while Seoul metropolitan transportation authorities demonstrate lowest sensitivity due to offline-capable host card emulation requirements.
Supply Chain Analysis
Upstream semiconductor feedstock for secure element chips draws from South Korea, Taiwan, and Japan, with Samsung Foundry and TSMC anchoring wafer fabrication for Knox-enabled devices. Raw material dependencies center on silicon wafers, cryptographic processor IP cores, and NFC antenna substrates. Single-source vulnerability concentrates in Samsung's domestic manufacturing scale for mid-tier Android devices, creating ecosystem lock-in risks. Distribution runs through electronics retail chains, carrier subsidy programs, and direct OEM preloads onto smartphones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's mobile payment market fragments along regulatory compliance tiers and generational adoption curves, with SME digitization and embedded finance convergence creating addressable niches for specialized entrants.
For Market Incumbents: Insulate merchant lock-in through deeper integration with Korea SMEs and Startups Agency subsidy programs, accelerating proprietary super-app development before open banking mandates erode data monopolies. Vertical integration into transportation network terminal deployments anchors hardware-anchored revenue against pure-play wallet competitors. Prioritize MFDS biometric certification investment to compress product launch windows against regulatory review queues. For New Entrants and Emerging Players: Pursue Busan fintech cluster sandbox exemptions for experimental cross-border remittance corridors targeting Southeast Asian worker communities, the most penetrable segment given underdeveloped incumbent coverage. Embedded finance convergence in mobility-as-a-service platforms offers a second white-space target, integrating parking and transit payments with credit products. A go-to-market angle through agricultural cooperative banking networks in Gwangju-Honam leverages zero-rating policy advantages for rural user acquisition. For Investors and Strategic Acquirers: Capital is best deployed toward platform operators with early central bank digital currency pilot participation and open banking API licensing, positioning for interoperability advantages in retail digital won distribution. Long-term viability across a multi-year horizon hinges on regulatory technology automation capabilities serving FSC compliance mandates. The signal to watch is Bank of Korea wholesale CBDC settlement infrastructure announcements indicating retail distribution partner selection.| Strategic Initiative | Industry Significance |
|---|---|
| CBDC Integration Partnership | Early Bank of Korea pilot participation captures future retail digital won distribution interoperability. |
| Open Banking API Licensing | FSC-mandated standardized disclosure erodes data monopolies while creating platform aggregation opportunities. |
| Biometric Certification Investment | MFDS facial recognition validation compresses product launch timelines against regulatory review queues. |
| SME Merchant Acquisition Program | Korea SMEs and Startups Agency subsidies accelerate street vendor digitization away from cash handling. |
| Cross-Border Remittance Corridor | Busan fintech cluster sandbox enables experimental blockchain settlement for Southeast Asian worker flows. |
Research Methodology
Cross-validation between primary interviews with payment platform executives, FSC regulatory affairs specialists, and transportation authority procurement managers anchors the qualitative findings against secondary validation from Financial Services Commission policy filings, Bank of Korea CBDC pilot disclosures, and MFDS biometric authentication standards documentation. Bottom-up merchant adoption modeling triangulates against top-down transaction volume estimates from platform operator aggregate disclosures.
Calibration against historical open banking mandate implementation timelines and zero-rating policy penetration curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include payment type, user demographic, transaction volume tier, and platform ecosystem, with CAGRs derived from SME digitization velocity and embedded finance convergence rates. Host card emulation deployment timelines and regional transit authority modernization programs serve as industry-specific forecast inputs.
Sensitivities concentrate around Bank of Korea CBDC retail distribution framework announcements, FSC open banking API standard revisions, and Personal Information Protection Act enforcement intensity against foreign platform operators. Cross-checking against Financial Supervisory Service payment system statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Remittance Service Market
Payments
Japan Mobile Payments Market
Payments
France Virtual Cards Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Contactless Payment Terminals Market
Payments
Transaction Monitoring Market
Payments
Middle East & North Africa Digital Payments Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Payment Card Market
Payments
M Commerce Payment Market
Payments
Argentina Payments Market
Payments
Denmark Payments Market
Payments
Vietnam Payments Market
Payments
Denmark Mobile Payments Market
Payments
Qatar Payments Market
Payments
India Payment Gateway Market