
 China Virtual Cards Market | 2026-2036
China Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
China Virtual Cards Market Insights
Asset-light banking-as-a-service models are reshaping competitive dynamics in China's virtual card sector, allowing non-bank platforms to enter without legacy infrastructure burdens. Ant Group leverages its super-app ecosystem to anchor consumer-facing virtual card distribution at massive scale. Tencent Holdings sustains payment integration across social and commerce layers, competing through embedded finance ubiquity. China UnionPay dominates the domestic card network rails, controlling interoperability standards that all virtual issuers must navigate.
Virtual cards in China are digitally generated payment credentials with dynamic card numbers, tokenized security parameters, and real-time spending controls, designed primarily to reduce fraud exposure and streamline online transaction workflows. Prepaid cards occupy the largest volume pool among product types, reflecting regulatory comfort with limited-balance instruments and their popularity among younger consumers. Virtual corporate cards represent the fastest-expanding segment, as businesses seek centralized expense management with granular authorization rules. Mobile wallets lead technology deployment, while blockchain integration remains nascent but attracts R&D investment from major platforms.
SAMR enforces anti-monopoly and data governance rules that constrain how virtual card providers aggregate and monetize transaction data. The People's Bank of China oversees third-party payment licensing and reserve requirements, directly determining which entities can issue virtual payment products. PBOC's digital yuan pilots introduce a state-backed parallel infrastructure that virtual card stakeholders must monitor for competitive displacement or partnership pathways.
Market Dynamics
Asset-light banking-as-a-service models are compressing capital requirements for virtual card issuance, allowing technology platforms to bypass traditional banking infrastructure and compete directly with licensed institutions.
Growth Catalysts
- Super-app ecosystem integration:Digital platforms embed virtual card issuance within commerce and social interfaces, reducing customer acquisition friction.
- Anti-Monopoly Law enforcement:SAMR's data governance mandates prevent dominant platforms from monopolizing transaction data, creating entry points for specialized virtual card providers.
- Corporate expense digitization:Enterprises in Shanghai's digital finance corridor adopt virtual corporate cards to centralize spend controls and eliminate reimbursement workflows.
Market Restraints
- Third-party payment licensing:PBOC's reserve requirements and capital thresholds constrain non-bank entities from obtaining virtual card issuance rights.
- Digital yuan infrastructure:State-backed CBDC pilots create parallel payment rails that may displace private virtual card transaction volumes.
- Tokenization standard dependency:China UnionPay controls domestic interoperability protocols, forcing all virtual issuers to navigate network gatekeeping.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area:Cross-border commerce corridors present underpenetrated demand for multi-currency virtual card products.
- Blockchain-tokenized credentials:Convergence of distributed ledger technology with dynamic card generation enables programmable spending logic for B2B applications.
- Green finance incentives:Dual carbon goals policies reward digital payment instruments that displace physical card plastic production and distribution.
Industry Challenges
- Legacy core banking integration:Virtual card APIs must reconcile with state-owned banks' decades-old transaction processing architectures.
- Real-time fraud detection talent:Shortage of machine learning engineers with payment-specific risk modeling expertise constrains product rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Virtual Cards Market |
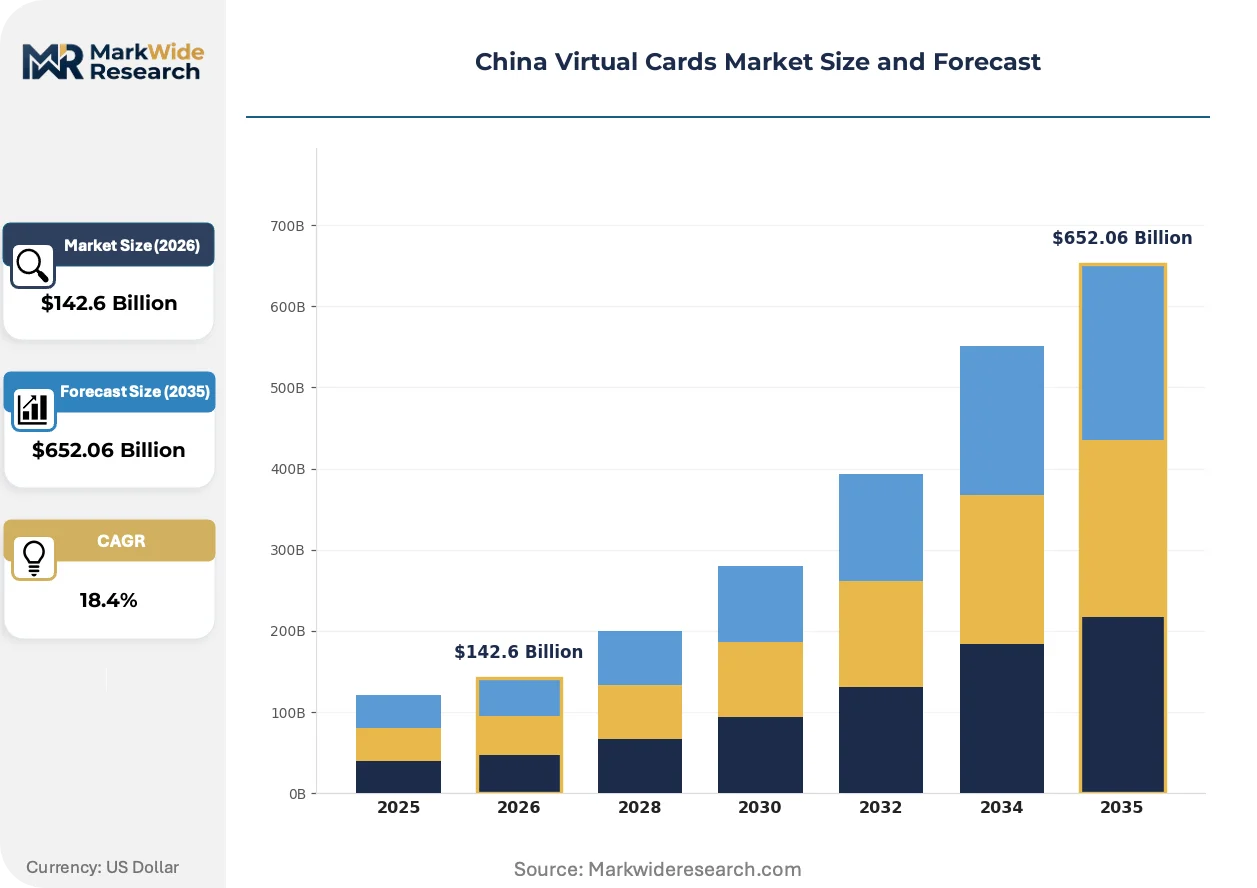
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $652.06 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepaid Cards, Credit Cards, Debit Cards, Virtual Corporate Cards End User: Consumers, Businesses, E-commerce Platforms, Financial Institutions Technology: Mobile Wallets, Blockchain Integration, QR Code Payments, Contactless Technology Distribution Channel: Online, Retail Stores, Financial Apps, Banking Websites |
| Companies Covered | Ant Group, Tencent Holdings, China UnionPay, JD.com, Mastercard, Visa, Industrial and Commercial Bank of China, China Merchants Bank, Airwallex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Virtual Cards Market Trends and Innovations
Virtual card infrastructure is migrating from static credential generation toward dynamic, context-aware payment instruments that adapt authorization parameters to transaction risk profiles.
Dynamic CVV2 and device-bound tokenization is migrating from premium corporate offerings to mass-market consumer products. E-commerce merchants in Hangzhou and Shenzhen are piloting these credentials to reduce chargeback rates. The technology is migrating from fraud prevention toward checkout abandonment reduction.
SAMR's Anti-Monopoly Law amendments now mandate data portability and interoperability standards for dominant payment platforms. These rules force ecosystem gatekeepers to open virtual card interfaces to third-party fintech providers. Specialized B2B issuers in Beijing's Zhongguancun cluster are leveraging this regulatory opening to bypass super-app distribution bottlenecks.
Enterprise procurement departments are unbundling travel and expense management from bundled corporate banking relationships. Mid-market companies in Jiangsu province now source virtual card programs through software vendors rather than traditional bank RFPs. This behavior shift concentrates purchasing authority with CFOs and procurement heads rather than treasury relationship managers.
China Virtual Cards Market Segmentation
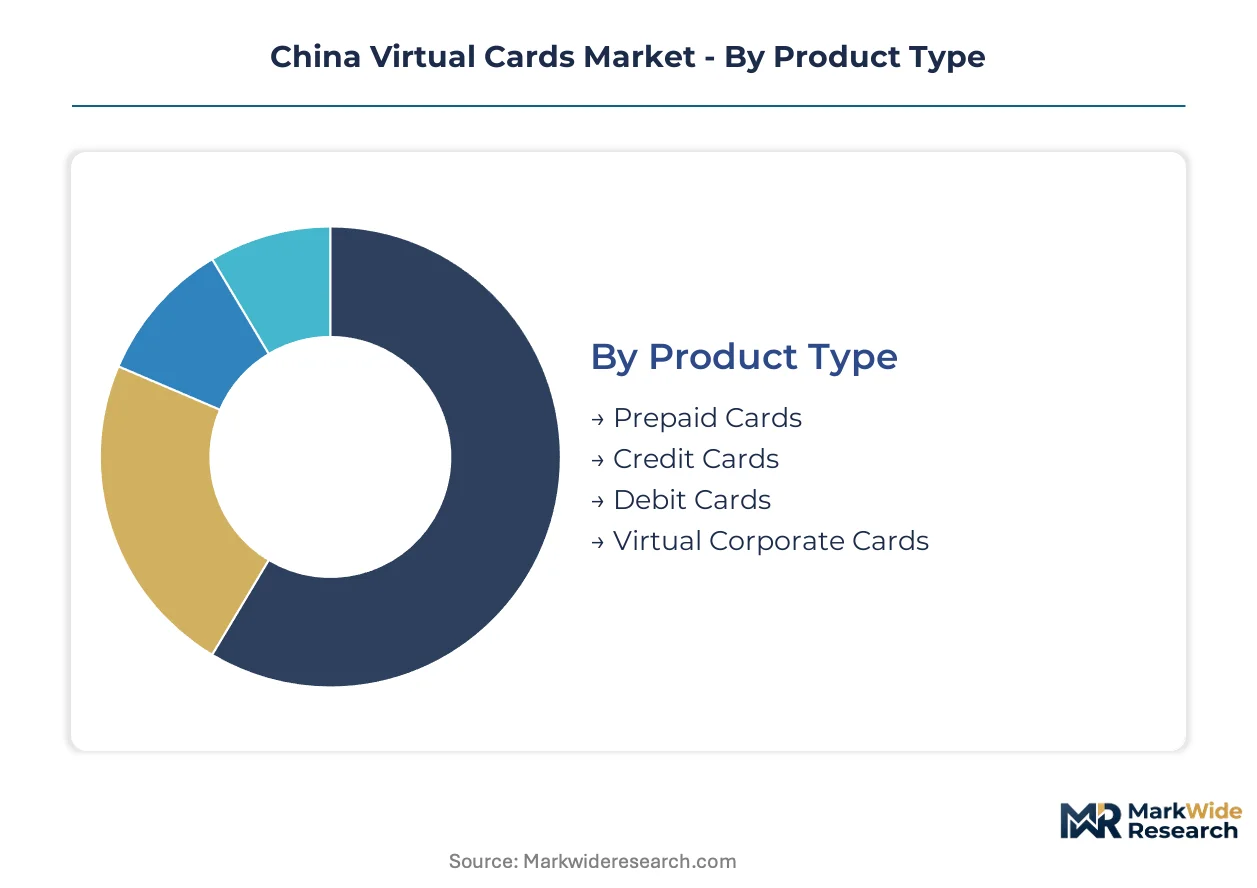
Virtual card segmentation in China reflects regulatory boundaries around payment licensing and the dominance of super-app distribution ecosystems. Product architecture choices determine compliance pathways, while technology deployment varies sharply between consumer convenience and enterprise control requirements.
Product Type:
Mature prepaid infrastructure anchors mass-market penetration, while emerging corporate solutions reshape B2B payment workflows.
- Prepaid Cards:Limited-balance instruments with capped storage values and restricted fund flows. Demand concentrates among younger consumers in Shanghai's digital finance corridor, driven by regulatory comfort with contained risk exposure and parental control features for minor account holders.
- Virtual Corporate Cards:Dynamic credential generation with granular authorization rules and real-time spend tracking. Enterprises in Jiangsu and Guangdong provinces adopt these for centralized expense management, eliminating reimbursement friction while satisfying SAMR audit trail requirements.
- Credit Cards:Tokenized revolving credit credentials integrated with Ant Group and Tencent credit scoring systems.
- Debit Cards:Direct-linked virtual credentials drawing from demand deposit accounts at state-owned banks.
Prepaid cards retain volume leadership; virtual corporate cards hold the steepest expansion curve.
End User:
Customer archetypes span from individual transaction convenience to institutional procurement transformation.
- Consumers:Individual users seeking fraud protection and subscription management through dynamic card numbers. Adoption clusters in first-tier cities where super-app wallet penetration exceeds national averages.
- E-commerce Platforms:Merchant-side deployment for supplier payments and cross-border settlement. Hangzhou and Shenzhen marketplaces pilot these credentials to reduce chargeback exposure on high-value transactions.
- Businesses:Mid-market companies unbundling travel and expense management from traditional banking relationships.
- Financial Institutions:Licensed banks and payment providers issuing white-label virtual card infrastructure to third-party platforms.
Consumers dominate transaction volume; e-commerce platforms are gaining share fastest through merchant-side deployment.
Technology:
Deployment modalities range from ubiquitous mobile infrastructure to experimental distributed ledger architectures.
- Mobile Wallets:Super-app embedded credential management with biometric authentication and tokenized transaction routing. Ant Group and Tencent ecosystems process the overwhelming majority of virtual card initiations through this channel.
- Blockchain Integration:Distributed ledger-based credential issuance with programmable spending logic. Beijing's Zhongguancun fintech cluster hosts R&D pilots exploring smart contract-enforced B2B payment terms.
- QR Code Payments:Static and dynamic code generation for merchant-presented and customer-presented transaction flows.
- Contactless Technology:NFC-enabled virtual credentials for proximity payments at physical terminals.
Mobile wallets command near-universal adoption; blockchain integration shows the most rapid capability advancement despite limited production deployment.
Distribution Channel:
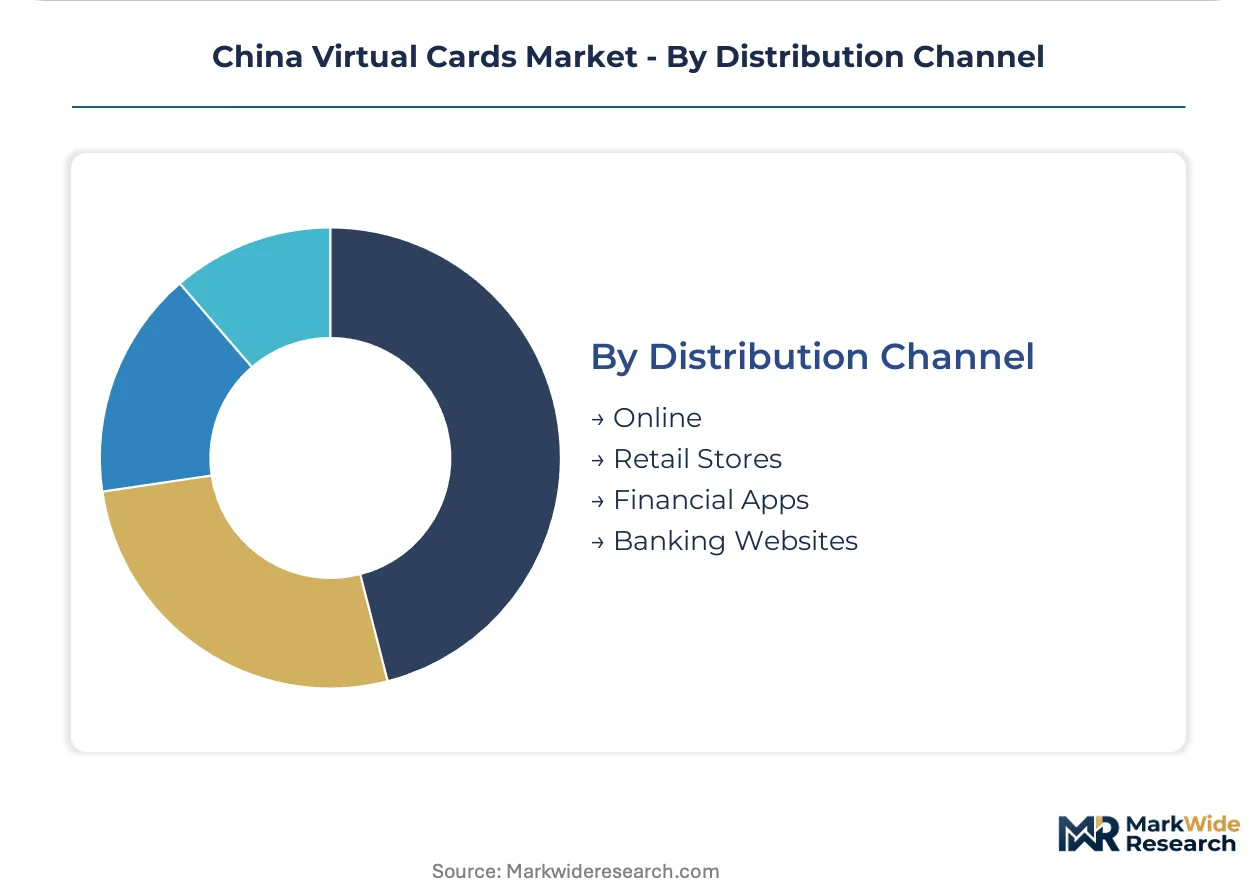
Channel strategy reflects the tension between super-app gatekeeping and regulatory pressure for interoperability.
- Financial Apps:Standalone fintech applications distributing virtual cards outside dominant ecosystems. SAMR's Anti-Monopoly Law data portability mandates create entry points for specialized B2B issuers bypassing super-app bottlenecks.
- Banking Websites:Traditional institution direct issuance through digital channels. State-owned banks leverage existing customer relationships to deploy virtual credentials alongside physical card portfolios.
- Online:Browser-based application flows and API-embedded issuance.
- Retail Stores:Physical point-of-sale enrollment for prepaid virtual products with cash loading.
Financial apps are expanding most quickly following regulatory opening; banking websites maintain established customer access advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's virtual cards market exhibits pronounced internal trade dynamics, with coastal provinces generating surplus fintech capacity while inland regions absorb payment infrastructure imports through state-backed digital inclusion programs.
Yangtze River Delta
Shanghai anchors national transaction volume through its digital finance corridor, where Ant Group and Tencent process the majority of virtual card initiations. SAMR's Anti-Monopoly Law enforcement here prevents super-app data monopolization, creating regulatory openings for specialized B2B issuers. Hangzhou's e-commerce clusters pilot dynamic CVV2 credentials to reduce merchant chargeback exposure on high-value cross-border settlements.
Pearl River Delta
Shenzhen's hardware-software convergence drives mobile wallet penetration rates exceeding national averages, with device manufacturers embedding tokenized payment capabilities at the chipset level. PBOC's third-party payment licensing framework constrains non-bank entrants through capital reserve requirements. Guangzhou's procurement departments unbundle travel and expense management from traditional banking relationships, sourcing virtual corporate cards through software vendors.
Beijing-Tianjin-Hebei
Zhongguancun's fintech cluster hosts R&D pilots exploring blockchain-tokenized credentials with programmable spending logic for enterprise procurement. The central government's dual carbon goals policies reward digital payment instruments that displace physical card plastic production. State-owned banks in Beijing leverage existing customer relationships to deploy virtual credentials alongside legacy physical card portfolios.
Sichuan-Chongqing
Western China's expanding consumer base drives demand for prepaid virtual products with parental control features for minor account holders. PBOC's digital yuan pilots in Chengdu introduce state-backed parallel infrastructure that virtual card stakeholders monitor for competitive displacement pathways. Chongqing's manufacturing enterprises adopt virtual corporate cards to centralize supplier payments with granular authorization rules.
Shandong Peninsula
Jiangsu province's mid-market companies source virtual card programs through CFO-led procurement decisions rather than treasury relationship managers. SAMR's data portability mandates force ecosystem gatekeepers to open virtual card interfaces to third-party fintech providers. Qingdao's port logistics operators pilot multi-currency virtual credentials for cross-border trade settlement efficiency.
China Virtual Cards Market Competitive Landscape
On the supply side, the industry is consolidating around super-app ecosystems that control distribution rails, while specialized B2B providers exploit regulatory openings to bypass gatekeeper bottlenecks. Three archetypes dominate: ecosystem-anchored platforms with massive consumer reach, state-backed card networks controlling interoperability standards, and foreign payment networks seeking limited partnership pathways. Competitive moves concentrate on API-based banking-as-a-service licensing and strategic positioning around PBOC's digital yuan infrastructure.
Among ecosystem-anchored platforms, Ant Group and Tencent Holdings exemplify the super-app distribution model that processes overwhelming virtual card volume through embedded finance ubiquity. China UnionPay occupies a position as the domestic network gatekeeper whose tokenization standards all virtual issuers must navigate. These three entities anchor the competitive structure while foreign networks like Mastercard and Visa sit within a restricted-access tier dependent on partnership negotiations with domestic license holders.
| Leading Market Players |
|---|
| Ant Group |
| Tencent Holdings |
| China UnionPay |
| JD.com |
| Mastercard |
| Visa |
| Industrial and Commercial Bank of China |
| China Merchants Bank |
| Airwallex |
| Others |
Pricing and Supply Chain Analysis
PBOC's third-party payment licensing chokepoint determines both pricing tier spreads and supply chain shape, compressing margins for non-bank issuers while concentrating infrastructure control among state-licensed entities. SAMR's data portability mandates force ecosystem gatekeepers to open interfaces, creating pricing pressure on super-app distribution premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in China's virtual card market. Premium tiers bundle dynamic CVV2 capabilities and real-time fraud monitoring; standard tiers offer basic tokenization through mobile wallets; economy tiers provide limited-balance prepaid credentials with restricted functionality. Cost compression in the economy tier is intensifying because state-owned banks leverage legacy infrastructure to undercut fintech entrants on issuance fees. Mid-market enterprises in Jiangsu province demonstrate highest price sensitivity, while multinational corporations in Shanghai's digital finance corridor prioritize compliance-grade audit trails over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for virtual card infrastructure rests on Ant Group's and Tencent's proprietary tokenization engines, with China UnionPay controlling domestic interoperability protocols as the network gatekeeper. Geographic supply concentration centers on China for mobile wallet deployment, Hong Kong for cross-border settlement infrastructure, and Singapore for regional cloud hosting redundancy. Raw material dependencies include semiconductor chips for secure element manufacturing, cryptographic modules for token generation, and cloud compute capacity for real-time authorization processing. Single-source vulnerability around China UnionPay's network standards creates systemic risk for all virtual issuers. Distribution runs through super-app ecosystems for consumer products and software vendor channels for corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's virtual cards market sits in early-cycle expansion, with corporate expense digitization and SAMR-mandated interoperability opening penetration pathways that did not exist three years ago.
For Market Incumbents: Insulate core distribution advantages by deepening API-based banking-as-a-service partnerships with state-owned banks, neutralizing the threat of PBOC digital yuan infrastructure displacement through co-development pilots. Prioritize vertical integration into blockchain-tokenized credential R&D at Beijing's Zhongguancun cluster to maintain technology leadership against specialized B2B challengers. For New Entrants and Emerging Players: Build out white-label virtual corporate card infrastructure for mid-market software vendors in Jiangsu and Guangdong provinces, where procurement departments have already unbundled travel and expense management from traditional banking relationships. Target the Guangdong-Hong Kong-Macao Greater Bay Area cross-border corridor as the most penetrable geography, leveraging multi-currency capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors specialized B2B issuers with SAMR-compliant audit architectures over consumer-facing super-app dependents. Long-term viability hinges on regulatory licensing moats and enterprise customer retention metrics. Watch PBOC digital yuan pilot expansion velocity as the critical inflection signal for competitive displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| API-Based Banking-as-a-Service Licensing | Enables non-bank platforms to bypass PBOC capital thresholds through partnership structures. |
| Blockchain-Tokenized Credential Development | Positions issuers for programmable B2B payment logic in Zhongguancun R&D corridors. |
| Cross-Border Multi-Currency Product Launch | Captures Greater Bay Area commerce flows underserved by domestic-only virtual products. |
| Dynamic CVV2 Mass-Market Deployment | Reduces merchant chargeback exposure for Hangzhou and Shenzhen e-commerce clusters. |
| SAMR Compliance Architecture Investment | Creates audit-trail differentiation as data governance enforcement intensifies. |
Research Methodology
Operator-level perspectives from virtual card product managers at licensed payment institutions, SAMR regulatory affairs specialists, corporate treasury executives in Jiangsu and Guangdong, and API integration engineers at banking-as-a-service platforms anchored the qualitative base. Secondary validation drew from PBOC third-party payment licensing disclosures, SAMR Anti-Monopoly Law enforcement bulletins, China UnionPay tokenization standard documentation, and enterprise software vendor procurement case studies. Bottom-up transaction volume estimates and top-down fintech infrastructure investment flows were triangulated to establish market sizing boundaries.
Scenario-bracketing around PBOC digital yuan adoption curves, SAMR enforcement intensity gradients, and super-app ecosystem openness parameters structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, end-user procurement authority level, technology deployment modality, and regional regulatory cluster. CAGRs were derived from adoption rate differentials between consumer and corporate use cases, with inputs from mobile wallet penetration trajectories and blockchain-tokenized credential R&D investment flows.
Stress conditions across PBOC licensing restriction tightening, digital yuan transaction volume displacement, and China UnionPay interoperability fee restructuring were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and technology adoption S-curves. Cross-checking against PBOC official payment statistics and SAMR market concentration indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Blockchain Payments Software Market
Payments
Fuel Cards Market
Payments
South Korea Mobile Payment Market
Payments
Digital Money Transfer Market
Payments
Asia-Pacific Payments Market
Payments
Mobile Payment Market
Payments
Third Party Payment Market
Payments
Digital Remittance Service Market
Payments
Mexico Digital Wallet Market
Payments
South Korea POS Terminals Market
Payments
India RTP Market
Payments
Indonesia Prepaid Cards Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market
Payments
Middle East Gift Card and Incentive Card Market