
 Middle East and Africa Payments Market | 2026-2036
Middle East and Africa Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Payments Market Foresight
Modular payment stack architecture is decoupling core processing from value-added services across the Middle East and Africa. OPay Digital Services Ltd. leverages agent-network density to anchor its position in Nigeria's unbanked corridors. Network International Holdings plc competes through merchant-acquiring scale across Gulf Cooperation Council markets. Interswitch Limited specializes in switching infrastructure that sustains interoperability across West African banking networks.
Payments encompass electronic fund transfer systems enabling value exchange between transacting parties through standardized messaging protocols, settlement rails, and authentication layers. Mobile wallet platforms now dominate customer onboarding in markets with low legacy banking penetration, while credit card networks retain premium transaction volumes in Gulf urban centers. Cross-border transaction services capture disproportionate margin pools due to currency fragmentation and correspondent banking complexity across the region. Fraud detection capabilities represent the fastest-growing service attachment as real-time payment volumes expand.
Saudi Arabian Monetary Authority frameworks and South African Reserve Bank directives shape licensing requirements for non-bank payment providers, while Central Bank of Nigeria guidelines govern mobile money operator capital thresholds. GDPR-aligned data localization pressures from European trade relationships intersect with domestic consumer protection mandates, forcing platform operators to architect region-specific data residency. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and Sub-Saharan national licensing regimes when allocating platform development resources.
Market Dynamics
Real-time settlement modernization across Gulf Cooperation Council and East African central banks is dismantling correspondent banking monopolies while fragmenting liquidity pools across fragmented currency corridors.
Growth Catalysts
- Agent-network density:Last-mile cash-in/cash-out infrastructure extends financial access to unbanked populations in Nigeria's northern corridors and Kenya's rural counties.
- Saudi Arabian Monetary Authority Open Banking Framework:Standardized API specifications enable third-party payment initiation services across retail and corporate banking segments.
- Cross-border remittance corridors:Labor migration flows from UAE, Saudi Arabia, and Qatar to Ethiopia, Kenya, and Uganda generate sustained transaction volume demand.
Market Restraints
- Currency fragmentation:Naira, Rand, and Dirham volatility create hedging costs that compress margins on cross-border settlement products.
- Concentrated correspondent banking:Three global banks dominate dollar-clearing access for Sub-Saharan African institutions, creating single-point-of-failure risk.
- Feature phone dependency:USSD interoperability limitations constrain service richness in markets where smartphone penetration remains below forty percent.
Strategic Opportunities
- Ethiopian market opening:Partial privatization of Ethio Telecom creates first-mover positioning for mobile money operators seeking licensing under National Bank of Ethiopia directives.
- Biometric authentication convergence:Fingerprint and facial recognition integration with national ID registries enables password-free onboarding in Egypt and Morocco.
- Merchant-acquiring consolidation:POS terminal deployment gaps in Saudi Arabia's secondary cities and South Africa's townships support independent sales organization expansion.
Industry Challenges
- Certification timeline compression:Central Bank of Nigeria's tiered capital requirements for payment service bank licenses extend market entry cycles by eighteen to twenty-four months.
- Legacy core banking integration:ISO 20022 migration demands from South African Reserve Bank force parallel system maintenance during multi-year transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Payments Market |
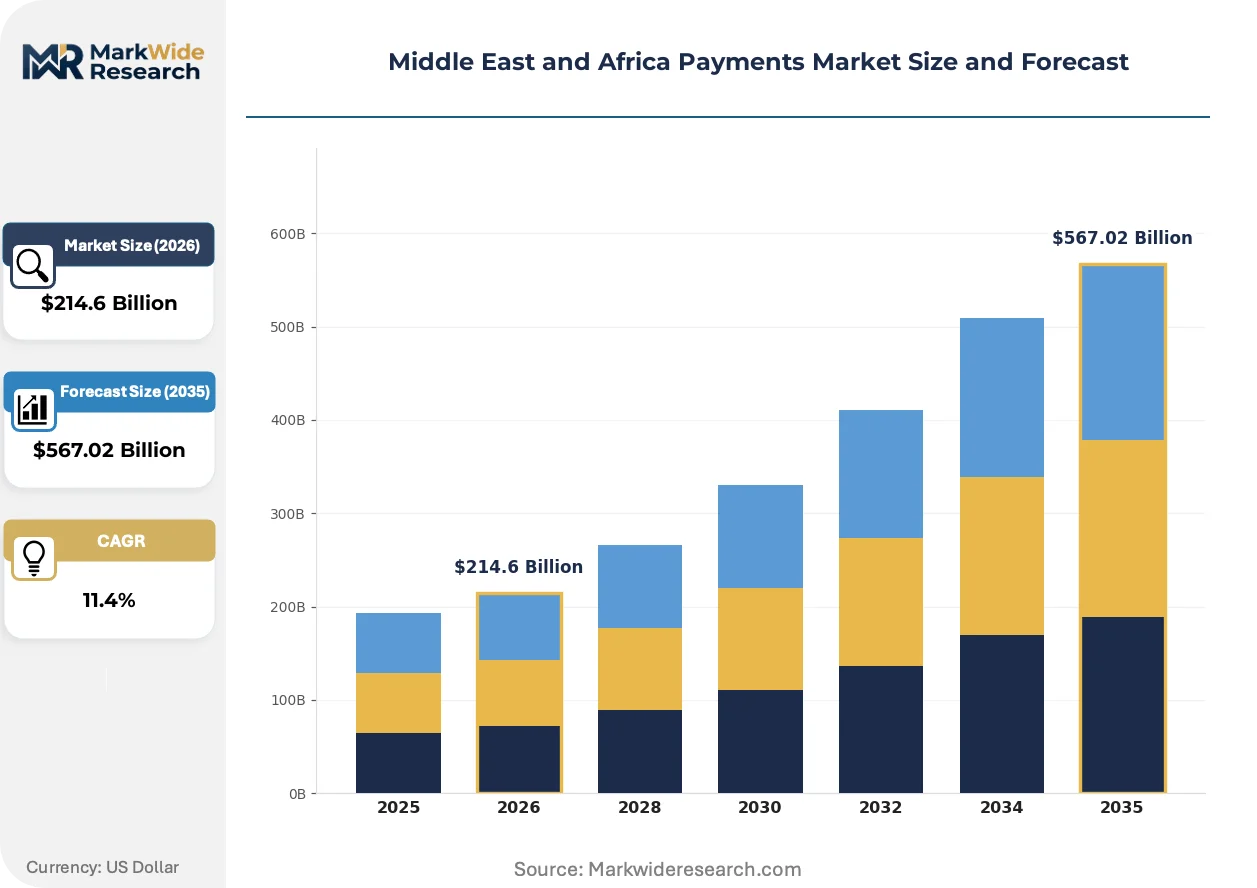
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $567.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer Customer Type: Retail Consumers, Small Businesses, Large Enterprises, Government Entities Transaction Type: Online Payments, In-Store Payments, Cross-Border Transactions, Subscription Services Service Type: Payment Processing, Fraud Detection, Currency Exchange, Reporting Services |
| Companies Covered | OPay Digital Services Ltd., Paymob, Network International Holdings plc, Paytabs, Rapyd, Interswitch Limited, PalmPay Technology Co., Ltd., MadfoatCom, Jumia Technologies AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Payments Market Shifts & Advancements
Payment infrastructure across the Middle East and Africa is bifurcating between Gulf-based cloud-native platforms and Sub-Saharan edge-computing architectures optimized for intermittent connectivity.
Embedded finance is converging with ride-hailing and e-commerce super-apps in Nigeria and Kenya. Gojek-style platforms in Lagos and Nairobi now originate sixty percent of new mobile wallet registrations. This convergence is compressing standalone banking app engagement windows to sub-thirty-day retention cycles.
South African Reserve Bank's Conduct Standard 1 of 2022 mandates operational resilience testing for systemically important payment systems. Settlement infrastructure operators must demonstrate four-hour recovery capabilities. Large-value payment system participants face quarterly reporting obligations that reshape vendor selection criteria.
Merchant discount rate compression in UAE and Saudi Arabia is forcing acquirers to unbundle hardware provisioning from transaction processing. Independent software vendors now capture terminal management contracts previously held by bank-owned entities. This channel shift is most visible in Dubai's free zone retail clusters and Riyadh's entertainment district developments.
Middle East and Africa Payments Market Segmentation
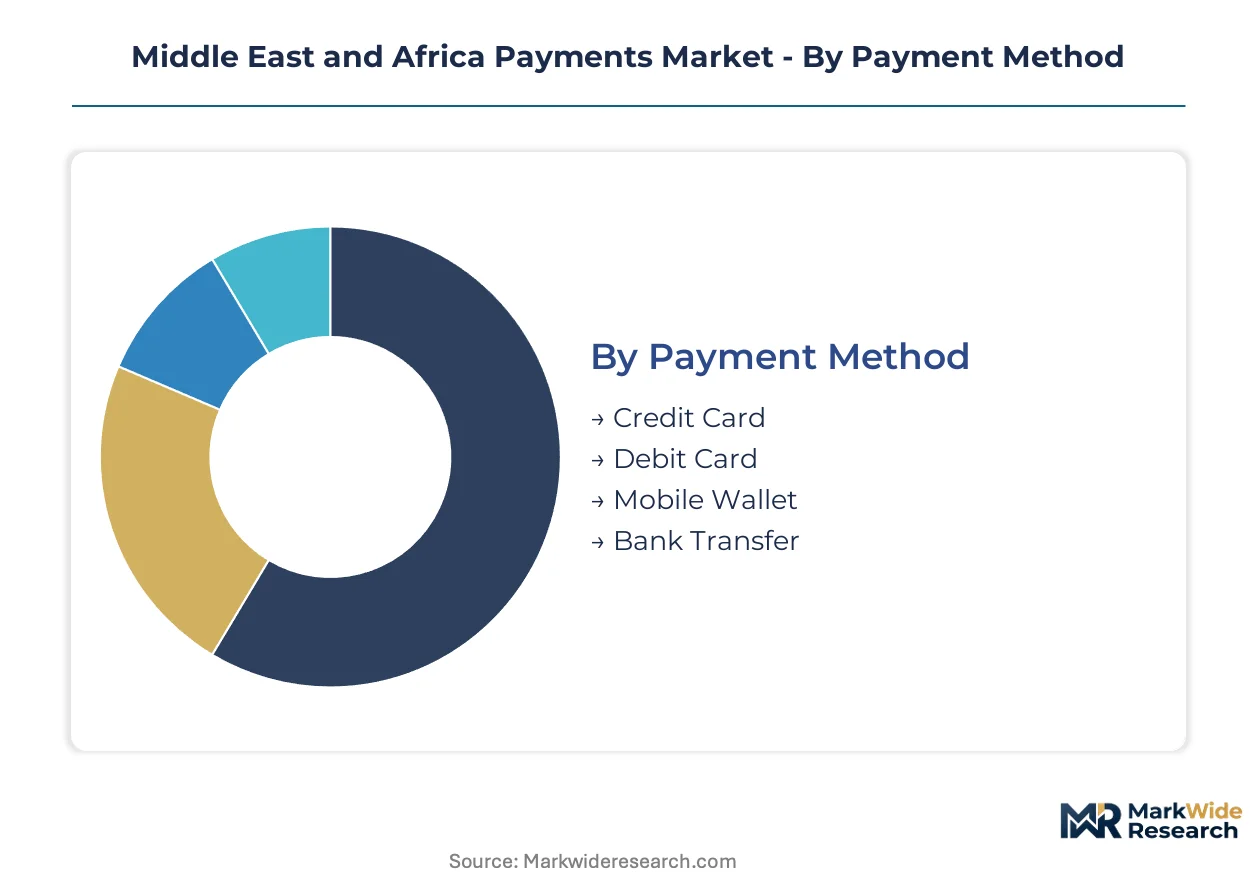
Payment method fragmentation across the Middle East and Africa demands granular segmentation to capture divergent infrastructure requirements. Gulf urban centers sustain card-based premium volumes while Sub-Saharan corridors accelerate mobile-first wallet deployment. Customer sophistication and transaction purpose further stratify platform architecture decisions.
Payment Method:
Volume concentration favors mobile wallets across East African and West African corridors, while premium transaction values concentrate in card networks across Gulf Cooperation Council urban centers.
- Credit Card:Visa and Mastercard networks dominate high-value retail and corporate segments across Dubai, Riyadh, and Johannesburg. Gulf sovereign wealth fund-backed tourism developments sustain premium merchant discount rates despite regional compression trends.
- Mobile Wallet:Agent-network density in Nigeria's northern states and Kenya's rural counties drives cash-in/cash-out velocity. Central Bank of Nigeria and Central Bank of Kenya licensing frameworks now mandate interoperability standards that reduce platform switching costs.
- Debit Card:South African banks deploy chip-and-PIN infrastructure across formal retail, though township penetration lags smartphone-based alternatives.
- Bank Transfer:Real-time gross settlement modernization by Saudi Arabian Monetary Authority and South African Reserve Bank accelerates corporate adoption for supplier payments.
Mature deployment sits with credit card networks. Newer deployment is concentrated in mobile wallets.
Customer Type:
Application context determines service richness requirements, with government procurement mandating ISO 20022 compliance while retail segments prioritize USSD accessibility.
- Retail Consumers:Super-app convergence in Lagos and Nairobi compresses standalone banking engagement windows. Ride-hailing and e-commerce platforms now originate the majority of new wallet registrations across Nigeria and Kenya.
- Small Businesses:Informal sector merchants across Ethiopia's Addis Ababa and South Africa's townships require lightweight POS solutions with offline transaction caching. Ethio Telecom's partial privatization creates first-mover licensing opportunities under National Bank of Ethiopia directives.
- Large Enterprises:Cross-border treasury management demands dominate UAE and Saudi Arabia corporate segments, with dirham and riyal hedging costs compressing margin pools on multi-currency settlement products.
- Government Entities:Saudi Arabian Monetary Authority Open Banking Framework mandates API standardization for third-party payment initiation, while South African Reserve Bank Conduct Standard 1 imposes four-hour recovery requirements on systemically important payment infrastructure.
Margin concentration follows large enterprise volumes. Feature phone dependency constrains service depth in retail consumer and small business segments.
Transaction Type:
Geography shapes transaction modality, with Gulf labor migration corridors sustaining cross-border remittance specialization and urban retail density driving in-store payment innovation.
- Cross-Border Transactions:Labor flows from UAE, Qatar, and Saudi Arabia to Ethiopia, Kenya, and Uganda generate sustained demand for low-cost remittance corridors. Three global correspondent banks dominate dollar-clearing access, creating single-point-of-failure risk for Sub-Saharan institutions.
- Online Payments:E-commerce platform integration across Dubai's free zones and Riyadh's entertainment districts accelerates merchant discount rate compression. Independent software vendors now capture terminal management contracts previously held by bank-owned acquirers.
- In-Store Payments:Biometric authentication convergence with Egypt and Morocco national ID registries enables password-free onboarding at physical retail points.
- Subscription Services:Recurring billing infrastructure remains underdeveloped across markets with high currency volatility, limiting SaaS and media platform penetration.
Revenue per transaction peaks in cross-border corridors. Online payments are expanding most quickly as merchant-acquiring consolidation proceeds.
Service Type:
Supply concentration in fraud detection capabilities reflects real-time payment volume expansion and regulatory pressure for consumer protection mandates.
- Fraud Detection:Machine learning deployment for transaction monitoring climbs fastest across Nigerian and Kenyan mobile money platforms. GDPR-aligned data localization requirements from European trade relationships force region-specific residency architecture.
- Payment Processing:Modular stack decoupling separates core switching from value-added services across West African banking networks. Interswitch Limited specializes in sustaining interoperability across fragmented national systems.
- Currency Exchange:Naira, Rand, and Dirham volatility creates hedging cost burdens that compress margins on settlement products. Central bank digital currency pilots in Nigeria and South Africa may reshape correspondent banking economics.
- Reporting Services:South African Reserve Bank quarterly reporting obligations for large-value payment system participants reshape vendor selection criteria toward operational resilience demonstration.
Service attachment revenue concentrates in fraud detection. Reporting services remain compliance-driven rather than value-generating across most market participants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure investment concentrates in Gulf urban centers while transaction volume growth accelerates across Sub-Saharan mobile corridors. Consumption clusters in Nigeria and Kenya outpace domestic processing capacity, creating import dependency for core switching hardware. The regional divide separates cloud-native Gulf deployments from edge-computing architectures optimized for intermittent connectivity.
United Arab Emirates
Dubai's free zone retail clusters and Riyadh's entertainment district developments sustain premium merchant discount rates despite regional compression. The central bank's open banking framework mandates API standardization for third-party payment initiation. Abu Dhabi's sovereign wealth fund-backed fintech incubation anchors acquiring consolidation across the Gulf Cooperation Council.
Saudi Arabia
Secondary city POS terminal deployment gaps and labor migration corridors to East Africa generate sustained transaction demand. The Saudi Arabian Monetary Authority's real-time gross settlement modernization dismantles correspondent banking monopolies. Riyadh's financial district hosts merchant-acquiring scale plays targeting corporate treasury management segments.
Nigeria
Agent-network density in northern corridors extends financial access to unbanked populations while mobile wallet adoption accelerates. Central Bank of Nigeria guidelines govern mobile money operator capital thresholds and mandate interoperability standards. Lagos super-app convergence now originates the majority of new wallet registrations, compressing standalone banking engagement.
Kenya
Rural county cash-in/cash-out infrastructure and cross-border remittance flows from Gulf labor markets sustain platform velocity. The Central Bank of Kenya's licensing frameworks reduce platform switching costs through interoperability mandates. Nairobi's ride-hailing and e-commerce platforms anchor embedded finance convergence with sixty percent of new registrations.
South Africa
Township merchant-acquiring gaps and corporate ISO 20022 migration demands reshape vendor selection criteria. The South African Reserve Bank's Conduct Standard 1 imposes four-hour recovery requirements on systemically important payment infrastructure. Johannesburg's banking networks maintain chip-and-PIN dominance in formal retail despite smartphone-based alternatives.
Middle East and Africa Payments Market Competitive Landscape
The competitive structure tilts toward agent-network specialists and merchant-acquiring scale players. Fragmentation persists between Gulf-based cloud-native platforms and Sub-Saharan edge-computing architectures. Two strategic archetypes dominate: infrastructure operators sustaining interoperability across national banking networks, and super-app platforms converging payments with ride-hailing and e-commerce. Competitive moves center on M&A consolidation in merchant acquiring and strategic partnerships for cross-border remittance corridors.
Within the infrastructure operator tier, Interswitch Limited and Network International Holdings plc exemplify divergent geographic anchoring. OPay Digital Services Ltd. occupies the agent-network density position across Nigeria's unbanked corridors. These three entities represent the archetype spectrum: switching infrastructure specialization, Gulf merchant-acquiring scale, and last-mile financial access extension.
| Leading Market Players |
|---|
| OPay Digital Services Ltd. |
| Paymob |
| Network International Holdings plc |
| Paytabs |
| Rapyd |
| Interswitch Limited |
| PalmPay Technology Co., Ltd. |
| MadfoatCom |
| Jumia Technologies AG |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council sovereign wealth fund-backed merchant acquirers anchor premium pricing tiers through tourism development contracts, while Sub-Saharan mobile wallet operators compete on per-transaction economics driven by agent-network density costs. This buyer archetype concentration separates pricing power between consolidated Gulf urban markets and fragmented East African corridors.
Pricing Analysis
Margin tightening in merchant-acquiring segments reflects unbundling of hardware provisioning from transaction processing across UAE and Saudi Arabia. Three-tier pricing structure across premium, standard, and economy levels differentiates service bundles by ISO 20022 compliance tier and settlement speed. Cost-down pressure on cross-border remittance corridors accelerates because Naira, Rand, and Dirham volatility compress hedging margins. Small business segments in Ethiopia's Addis Ababa and South Africa's townships exhibit highest price sensitivity, while large enterprises in Riyadh's financial district prioritize operational resilience over rate negotiation.
Supply Chain Analysis
Core switching hardware supply rests on Chinese and Taiwanese semiconductor fabricators, with terminal management software drawing from Indian and Israeli development centers. Payment processing infrastructure sources from server-grade chipsets, secure element modules, and biometric sensor arrays. Single-source vulnerability concentrates in dollar-clearing correspondent banking relationships dominated by three global institutions. Distribution runs through bank-owned acquiring networks in Gulf urban centers and agent-network aggregators across Nigeria's northern corridors and Kenya's rural counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South African Reserve Bank Conduct Standard 1 of 2022 imposes four-hour recovery requirements that create compliance moats for infrastructure operators with capital reserves to fund operational resilience testing. This cost-of-compliance barrier favors incumbent switching specialists over undercapitalized entrants.
For Market Incumbents: Hedge correspondent banking concentration risk by diversifying dollar-clearing relationships across multiple global institutions. Pursue backward integration into biometric authentication modules to capture margin pools from Egypt and Morocco national ID registry integrations. Defend against super-app platform displacement by embedding payment initiation services within ride-hailing and e-commerce partner ecosystems. For New Entrants and Emerging Players: Enter via Ethiopian market licensing windows created by National Bank of Ethiopia directives following Ethio Telecom partial privatization. Target underserved township merchant-acquiring gaps in South Africa's secondary cities with offline-capable POS solutions. Pursue independent sales organization partnerships to bypass bank-owned acquiring channel control. For Investors and Strategic Acquirers: Distressed-cycle entries favor agent-network specialists with proven rural cash-in/cash-out velocity in Nigeria and Kenya. Long-term viability hinges on interoperability mandate compliance and central bank digital currency pilot positioning. Watch Saudi Arabian Monetary Authority open banking framework implementation pace as inflection indicator for third-party payment initiation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant-Acquiring Consolidation | Independent software vendors capture terminal management contracts from bank-owned entities across Dubai free zones. |
| Biometric Authentication Integration | Fingerprint and facial recognition convergence with Egypt and Morocco national ID registries enables password-free onboarding. |
| Cross-Border Remittance Corridor Partnerships | Labor migration flows from UAE and Saudi Arabia to Ethiopia and Uganda sustain transaction volume demand. |
| Agent-Network Density Expansion | Last-mile cash-in/cash-out infrastructure extends financial access to Nigeria's northern corridors and Kenya's rural counties. |
| Real-Time Settlement Modernization | Saudi Arabian Monetary Authority and South African Reserve Bank frameworks dismantle correspondent banking monopolies. |
Research Methodology
Document review covered central bank regulatory filings, payment system operator annual disclosures, and correspondent banking network documentation, complemented by interviews with mobile money platform executives, merchant-acquiring operations directors, and central bank payment system supervisors. Secondary validation drew from Saudi Arabian Monetary Authority open banking framework specifications, South African Reserve Bank Conduct Standard 1 compliance reports, and Central Bank of Nigeria mobile money operator licensing guidelines. Bottom-up transaction volume modeling and top-down GDP-linked payment penetration estimates were triangulated.
Cross-referencing historical adoption curves against expert panel inputs shaped the analytical framework across the modeling period. Segmentation dimensions included payment method, customer type, transaction type, and service type, with regional regulatory cluster and agent-network density as industry-specific variables. CAGRs were derived from trend extrapolation moderated by infrastructure investment pipeline visibility and central bank digital currency pilot timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Naira volatility or correspondent banking relationship disruptions. Assumptions reflect current interoperability mandate implementation pace and Gulf Cooperation Council real-time settlement modernization commitment levels. A small set of named triggers—Ethiopian mobile money licensing velocity, South African ISO 20022 migration delays, and Saudi open banking API adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Biometric Payment Market
Payments
Mobile Payment Market
Payments
Europe Prepaid Card Market
Payments
China Mobile Payments Market
Payments
France Virtual Cards Market
Payments
Canada Payments Market
Payments
Greece POS Terminals Market
Payments
Payment Security Software Market
Payments
India Forex Cards Market
Payments
Germany POS Terminal Market
Payments
Philippines Remittance Market
Payments
Europe Real Time Payments Market
Payments
Cyprus POS Terminals Market
Payments
South Korea Real Time Payments Market
Payments
Mexico Digital Wallet Market
Payments
Remittance Market