
 Australia Luxury Residential Real Estate Market | 2026-2036
Australia Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Luxury Residential Real Estate Market Outlook
Green Star certification from the Green Building Council of Australia is bifurcating the competitive landscape between developers who meet stringent sustainability benchmarks and those who do not. Gurner leverages its vertically integrated development model to control design-to-delivery timelines for ultra-premium apartment towers. Meriton Group anchors its portfolio scale across Sydney and Brisbane with consistent branding and in-house construction management. Lendlease competes through its master-planned community expertise, applying precinct-level sustainability credentials that exceed baseline code requirements.
Australia luxury residential real estate comprises freehold and strata-titled dwellings priced in the top decile of regional transaction values, typically featuring bespoke architectural design, premium material specifications, integrated smart building systems, and concierge-level amenities. These properties serve as primary residences, portfolio diversification assets, and generational wealth preservation vehicles for affluent domestic and international buyers. The property type dimension shows apartments and penthouses capturing accelerated interest from Asian capital sources, while the market trend dimension reveals sustainable homes and smart homes as the fastest-growing category where margin pools deepen through technology integration and operational efficiency. Villas remain the mature, high-ticket segment where transaction velocity slows but per-unit profitability sustains.
TGA does not regulate residential construction, so the National Construction Code administered by the Australian Building Codes Board shapes structural and energy standards, while the Foreign Investment Review Board governs overseas purchaser eligibility and conditions. ASIC and AUSTRAC oversight of real estate fund structures and anti-money laundering compliance adds transactional friction that filters speculative capital. Stakeholders must monitor how FIRB threshold adjustments and state-level foreign purchaser surcharge variations reshape bidder composition at premium price points.
Market Dynamics
The National Construction Code's energy efficiency mandates are compressing development timelines while elevating capital requirements, forcing developers to pre-commit to sustainability benchmarks before design finalization.
Growth Catalysts
- Foreign Investment Review Board thresholds:FIRB scrutiny filters speculative capital, concentrating demand from Singaporean and mainland Chinese investors with demonstrated holding capacity for waterfront apartments in Sydney and Melbourne.
- Green Star certification:The Green Building Council of Australia's rating system creates preference premiums for developers who achieve 5- and 6-star ratings, compressing sales cycles for certified stock.
- Penthouse demand from Asian capital:Ultra-high-net-worth buyers from Hong Kong and Shanghai are concentrating purchases in Sydney's Eastern Suburbs and Melbourne's inner-ring precincts, sustaining liquidity at the apex price tier.
Market Restraints
- Construction input volatility:Structural steel and glazing costs fluctuate with global commodity markets, compressing margin predictability for fixed-price development contracts.
- Foreign purchaser surcharge stacking:New South Wales and Victoria impose cumulative stamp duty surcharges on non-resident buyers, elevating effective transaction costs above competing jurisdictions.
- Heritage overlay complexity:Local council heritage protections in established premium precincts constrain demolition and redevelopment options, extending approval timelines.
Strategic Opportunities
- Brisbane penthouse undersupply:Queensland's luxury apartment pipeline remains thin relative to Sydney and Melbourne, creating white space for developers with established delivery track records.
- Smart home integration convergence:The intersection of building management systems and residential IoT platforms enables developers to capture recurring service revenue beyond initial sale.
- Precinct-scale sustainability:Master-planned communities that exceed baseline National Construction Code requirements can access institutional capital pools with mandated ESG allocation.
Industry Challenges
- Certified passive house detailing:The specialized skill set for high-performance envelope construction remains scarce, constraining delivery velocity for code-compliant premium stock.
- ASIC fund structure compliance:Real estate investment vehicle formation faces heightened disclosure and investor protection requirements, extending capital-raising timelines.
- Anti-money laundering verification:AUSTRAC-mandated identity and source-of-funds checks add transactional friction for international purchasers, compressing conversion rates at the contract stage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Luxury Residential Real Estate Market |
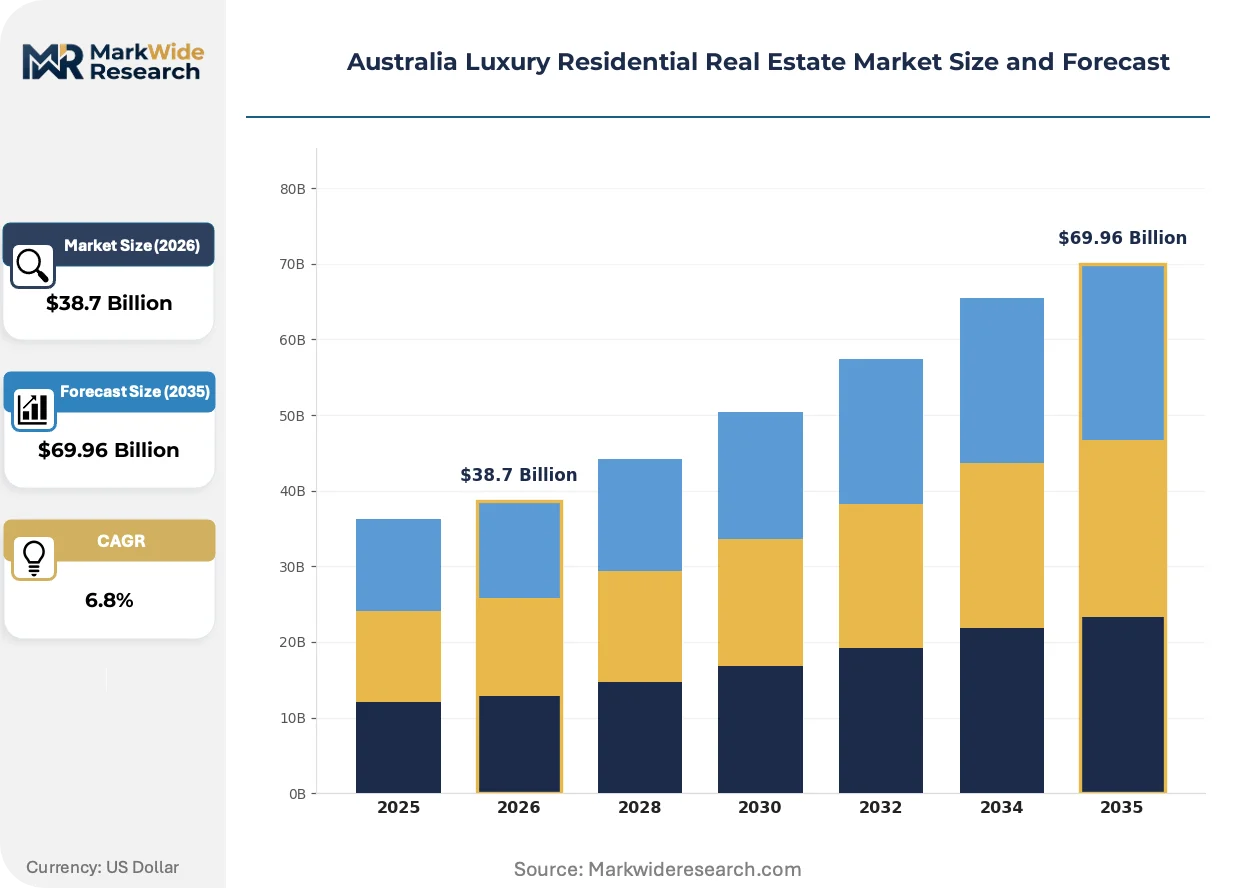
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Apartments, Townhouses, Penthouses Client Type: High Net Worth Individuals, Foreign Investors, Developers, Real Estate Funds Market Trend: Luxury Development, Renovation Projects, Sustainable Homes, Smart Homes Investment Stage: Pre-Construction, Under Construction, Completed, Secondary Market |
| Companies Covered | Gurner, Meriton Group, Lendlease, Stockland, Sekisui House Australia, Mirvac, Frasers Property Australia, Sunland Group, Crown Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Luxury Residential Real Estate Market Strategic Shifts
Technology integration and regulatory stringency are compressing traditional development cycles while elevating buyer expectations for operational performance transparency.
Electrochromic glazing is fragmenting the premium window specification market. High-net-worth buyers in Sydney's Eastern Suburbs now expect dynamic tinting as standard in penthouses above the twentieth floor. This specification is fragmenting supplier relationships, forcing developers to bypass traditional glazing contractors for direct manufacturer partnerships.
The National Construction Code's 2022 energy efficiency provisions administered by the Australian Building Codes Board mandate minimum thermal performance ratings for all new residential construction. Developers must now commit to NatHERS ratings above 7 stars before securing development approval. Premium projects in Melbourne's inner-ring precincts are responding by integrating phase-change materials into concrete slabs to meet the threshold without sacrificing floor-to-ceiling glazing ratios.
Direct developer-to-buyer digital platforms are compressing traditional agency commission structures. Off-the-plan sales in Brisbane and Perth increasingly transact through proprietary sales portals that bypass conventional residential agency networks. This channel shift is most visible among Singaporean and Hong Kong purchasers who complete entire acquisition workflows remotely, from virtual inspection to electronic contract execution.
Australia Luxury Residential Real Estate Market Segmentation
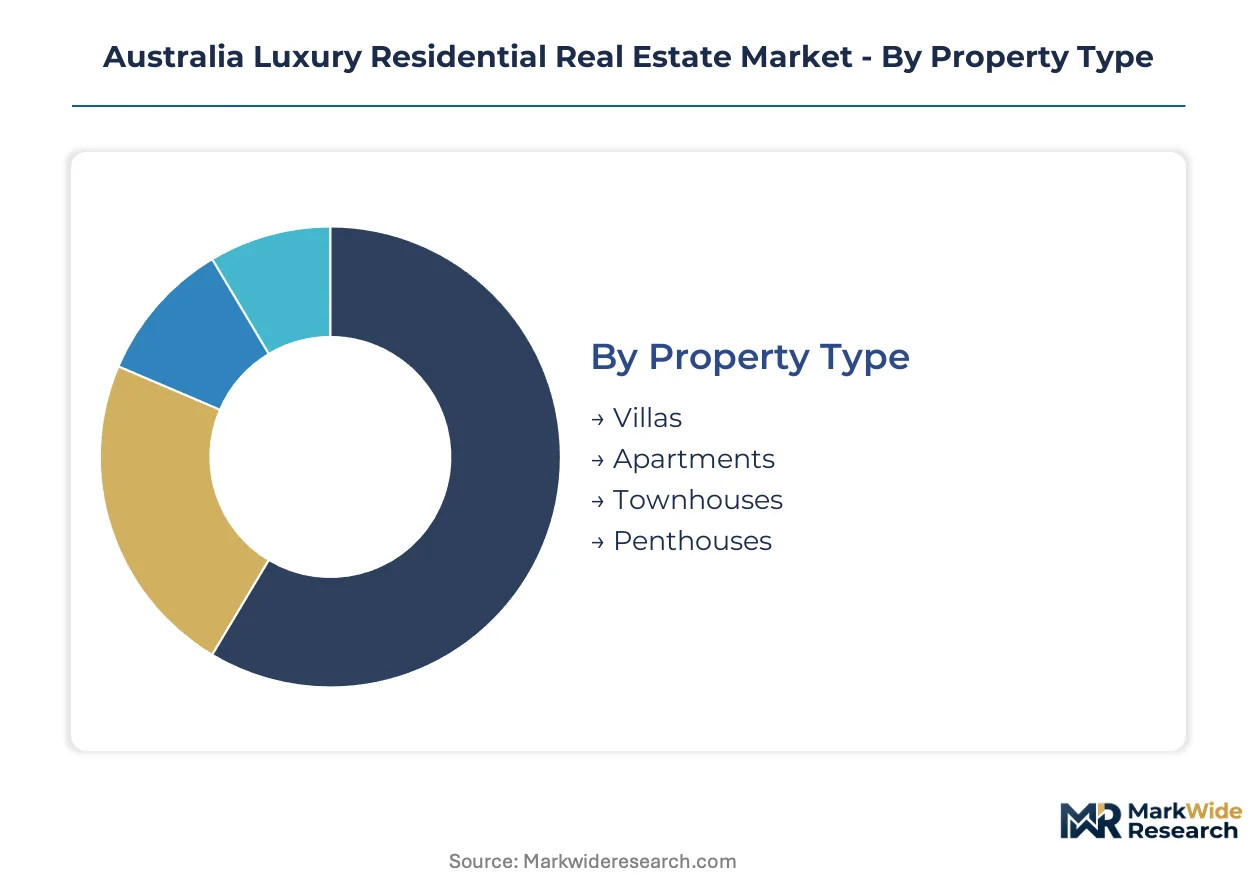
Segmentation in Australian luxury residential real estate reveals how regulatory frameworks and capital sources reshape competitive dynamics. The Foreign Investment Review Board's threshold adjustments and state-level foreign purchaser surcharges create divergent profitability profiles across property types and client categories.
Property Type:
The National Construction Code's energy efficiency mandates administered by the Australian Building Codes Board impose differential compliance burdens across structural forms, compressing development timelines for high-performance envelopes.
- Apartments:Strata-titled vertical dwellings with integrated building management systems. Demand concentrates in Sydney's Eastern Suburbs and Melbourne's inner-ring precincts from Singaporean and mainland Chinese capital seeking waterfront exposure.
- Penthouses:Apex-floor configurations featuring bespoke architectural specifications and concierge-level amenities. Ultra-high-net-worth buyers from Hong Kong and Shanghai sustain liquidity at this tier, with electrochromic glazing now standard above twentieth-floor elevations.
- Villas:Freehold detached dwellings representing the mature, high-ticket segment where transaction velocity slows but per-unit profitability sustains through generational wealth preservation demand.
- Townhouses:Medium-density attached dwellings bridging apartment efficiency with villa autonomy, constrained by heritage overlay complexity in established premium precincts.
Established volume favors villas; emerging adoption favors apartments.
Client Type:
Capital source differentiation determines holding capacity and regulatory exposure, with AUSTRAC-mandated identity verification creating transactional friction that filters bidder composition.
- Foreign Investors:Non-resident purchasers from Singapore and mainland China subject to FIRB scrutiny and cumulative state-level stamp duty surcharges. These buyers demonstrate demonstrated holding capacity for waterfront apartments in Sydney and Melbourne.
- High Net Worth Individuals:Domestic affluent households acquiring primary residences and portfolio diversification assets. This segment responds to Green Star certification premiums with compressed sales cycles for 5- and 6-star rated stock.
- Real Estate Funds:Institutional vehicles governed by ASIC disclosure requirements and investor protection mandates, accessing precinct-scale sustainability projects that exceed baseline National Construction Code requirements.
- Developers:Vertically integrated operators controlling design-to-delivery timelines, with Gurner and Meriton Group leveraging in-house construction management to anchor portfolio scale across Sydney and Brisbane.
Transaction velocity concentrates with high net worth individuals; capital depth concentrates with real estate funds.
Market Trend:
Technology integration and sustainability stringency are elevating buyer expectations for operational performance transparency while fragmenting supplier relationships.
- Smart Homes:Residential IoT platforms converging with building management systems enable developers to capture recurring service revenue beyond initial sale. This category is expanding most quickly as margin pools deepen through technology integration.
- Sustainable Homes:NatHERS ratings above 7 stars achieved through phase-change materials in concrete slabs and high-performance envelope construction. Certified passive house detailing remains scarce, constraining delivery velocity.
- Luxury Development:Ground-up construction of premium stock with bespoke material specifications and integrated smart building systems, facing construction input volatility in structural steel and glazing costs.
- Renovation Projects:Adaptive reuse of existing premium stock, constrained by local council heritage protections in established precincts that extend approval timelines.
Margin stability favors luxury development; technology differentiation favors smart homes.
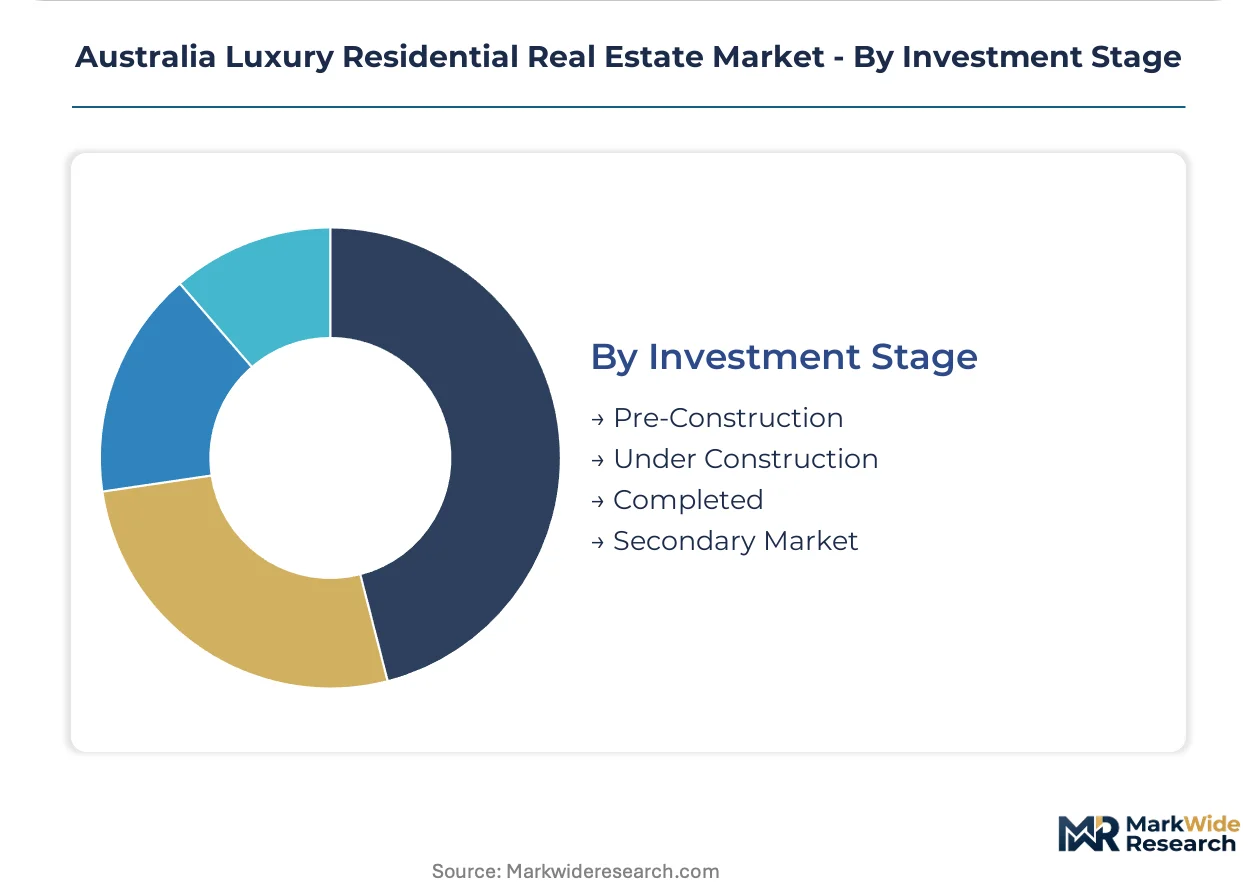
Investment Stage:
Capital commitment timing determines risk exposure to construction cost fluctuations and regulatory threshold adjustments.
- Pre-Construction:Off-the-plan acquisitions transacting through direct developer-to-buyer digital platforms that bypass conventional residential agency networks, particularly visible among Singaporean and Hong Kong purchasers completing remote workflows.
- Completed:Standing stock delivering immediate income or occupancy, with Brisbane penthouse undersupply creating white space for developers with established delivery track records.
- Under Construction:Partially delivered assets subject to fixed-price contract margin compression from commodity market volatility in structural inputs.
- Secondary Market:Resale transactions with established title clarity, though foreign purchaser surcharge stacking in New South Wales and Victoria elevates effective transaction costs above competing jurisdictions.
Liquidity depth favors completed stock; yield compression favors pre-construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Foreign Investment Review Board's threshold adjustments and state-level foreign purchaser surcharges are redistributing capital flows across Australian jurisdictions. New South Wales and Victoria impose the heaviest cumulative transaction burdens, accelerating developer interest toward Queensland and Western Australia.
New South Wales
Singaporean capital concentrates in Sydney's Eastern Suburbs waterfront apartments. The state's foreign purchaser stamp duty surcharge stacks with FIRB application fees, elevating effective transaction costs. Barangaroo and Circular Quay precincts attract ultra-high-net-worth buyers seeking harbor exposure with concierge-level amenities.
Victoria
Mainland Chinese investors sustain penthouse demand in Melbourne's inner-ring precincts including Southbank and Docklands. The National Construction Code's energy efficiency mandates compress development timelines for premium apartment towers. Phase-change materials in concrete slabs enable NatHERS ratings above 7 stars without sacrificing glazing ratios.
Queensland
Brisbane's luxury apartment pipeline remains thin relative to southern capitals, creating white space for established developers. The state's lighter foreign purchaser surcharge burden attracts Singaporean and Hong Kong capital seeking penthouse exposure. Fortitude Valley and New Farm precincts concentrate emerging ultra-premium stock.
Western Australia
Perth's prestige market recovers from prolonged softness as mining wealth regenerates domestic high-net-worth demand. Local council heritage protections in established riverside precincts constrain demolition options. Swan River waterfront villas in Peppermint Grove and Dalkeith sustain generational wealth preservation transactions.
South Australia
Adelaide's luxury residential market attracts Melbourne and Sydney capital seeking relative value in detached villa stock. The state's absence of foreign purchaser surcharges positions it competitively for FIRB-approved international buyers. North Adelaide and the Adelaide Hills concentrate prestige transactions with vineyard and hillside exposure.
Australia Luxury Residential Real Estate Market Competitive Environment
Listed leaders compete with private specialists across capital commitment horizons and risk tolerance profiles. The Australian luxury residential development sector exhibits tiered concentration, with vertically integrated private developers controlling design-to-delivery timelines while listed entities access institutional capital pools. Three archetypes dominate: scale-driven diversified developers, boutique ultra-premium specialists, and master-planned community operators. Competitive intensity manifests through direct-to-buyer digital platform deployment and sustainability certification racing.
Within the vertically integrated tier, Gurner exemplifies the private specialist archetype through its control of design-to-delivery timelines for ultra-premium apartment towers. Meriton Group anchors the scale-driven position across Sydney and Brisbane with consistent branding and in-house construction management. Lendlease occupies the master-planned community vector, applying precinct-level sustainability credentials that exceed baseline National Construction Code requirements.
| Leading Market Players |
|---|
| Gurner |
| Meriton Group |
| Lendlease |
| Stockland |
| Sekisui House Australia |
| Mirvac |
| Frasers Property Australia |
| Sunland Group |
| Crown Group |
| Others |
Value Chain & Pricing Dynamics
Scale economies in high-performance glazing and structural steel fabrication concentrate supplier power among a handful of Australian and Asian manufacturers, compressing margin predictability for developers while establishing price floors that reflect capacity utilization across the construction cycle.
Pricing Analysis
Certification level creates the primary spread across the Australian luxury residential market, with Green Star 5- and 6-star rated stock commanding preference premiums that compress sales cycles relative to uncertified equivalents. Pricing stratifies across premium, standard, and economy tiers based on NatHERS rating achievement and smart home integration depth. Cost compression in fixed-price development contracts is intensifying because structural steel and glazing costs fluctuate with global commodity markets. High net worth individuals demonstrate lowest price sensitivity, responding to sustainability premiums, while foreign investors face cumulative stamp duty surcharges that elevate effective transaction costs and constrain bidder composition.
Supply Chain Analysis
Inventory cycles for electrochromic glazing and phase-change materials extend lead times by 12-18 weeks, forcing developers to pre-commit specifications before design finalization. Supply concentrates in China, South Korea, and Japan for advanced glazing systems, while domestic Australian producers dominate structural steel and concrete inputs. The supply chain rests on single-source vulnerability for certified passive house envelope components, where specialized skill scarcity constrains delivery velocity. Distribution runs through vertically integrated developers with in-house construction management, bypassing traditional contractor networks for direct manufacturer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among ultra-high-net-worth purchasers from Singapore and mainland China, with FIRB scrutiny and foreign purchaser surcharge stacking filtering speculative capital and consolidating demand among holders with demonstrated acquisition capacity.
For Market Incumbents: Secure design-to-delivery timeline control through backward integration into high-performance envelope construction, addressing certified passive house skill scarcity that constrains delivery velocity. Anchor portfolio scale across Sydney and Brisbane with consistent branding and in-house construction management, defending against emerging developers deploying direct-to-buyer digital platforms that bypass conventional agency networks.
For New Entrants and Emerging Players: Differentiate on precinct-scale sustainability credentials that exceed baseline National Construction Code requirements, accessing institutional capital pools with mandated ESG allocation. Target Brisbane penthouse undersupply, where Queensland's luxury apartment pipeline remains thin relative to southern capitals, and deploy proprietary sales portals that enable remote acquisition workflows for Singaporean and Hong Kong purchasers.
For Investors and Strategic Acquirers: Boutique ultra-premium specialists with established Green Star delivery track records represent the most attractive acquisition archetype, given their control of preference premiums in supply-constrained precincts. Monitor Foreign Investment Review Board threshold adjustments as the inflection indicator for capital flow redistribution across Australian jurisdictions, with lighter surcharge burdens in Queensland and South Australia attracting redirected foreign capital.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Star Certification Investment | Developers achieving 5- and 6-star ratings from the Green Building Council of Australia capture preference premiums that compress sales cycles. |
| Direct-to-Buyer Digital Platform Deployment | Proprietary sales portals bypass conventional residential agency networks, enabling remote acquisition workflows for Asian capital sources. |
| Smart Home Integration Convergence | Residential IoT platforms converging with building management systems enable developers to capture recurring service revenue beyond initial sale. |
| Precinct-Scale Sustainability Development | Master-planned communities exceeding baseline National Construction Code requirements access institutional capital pools with mandated ESG allocation. |
| High-Performance Envelope Skill Acquisition | Certified passive house detailing capability addresses specialized construction skill scarcity that constrains delivery velocity for premium stock. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with development directors, project architects, foreign investment advisory specialists, and luxury residential sales agents. Secondary validation drew from Australian Bureau of Statistics construction data, Foreign Investment Review Board approval records, Green Building Council of Australia certification databases, and state-level stamp duty revenue disclosures. Bottom-up project pipeline analysis and top-down macroeconomic indicator triangulation informed market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning property type, client category, market trend, and investment stage, with CAGRs derived from historical transaction velocity patterns and forward-looking supply pipeline assessments. Forecast inputs incorporated National Construction Code energy efficiency mandate compliance timelines, FIRB threshold adjustment scenarios, and foreign purchaser surcharge stacking variations across New South Wales, Victoria, Queensland, and South Australia.
The analysis sits within stated boundaries; outcomes outside sustained foreign capital inflow, stable construction input costs, or unchanged regulatory surcharge regimes would require recalibration. Forecasts reflect documented assumptions regarding FIRB scrutiny intensity and Green Star certification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market