
 Vietnam Luxury Residential Real Estate Market | 2026-2036
Vietnam Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Luxury Residential Real Estate Market Analytics
Wealthy domestic buyers is collapsing the historical reliance on foreign investor demand that shaped earlier development cycles in Vietnam's premium property sector. Vingroup JSC leverages its integrated ecosystem of retail, education, and healthcare amenities to anchor buyer loyalty across its Vinhomes portfolio. Nomura Real Estate Vietnam sustains Japanese engineering standards and precision construction timelines that differentiate its projects in the competitive metropolitan core. CapitaLand Development (Vietnam) competes through Singaporean fund-management discipline and selective land-banking in transit-oriented locations.
Vietnam luxury residential real estate comprises high-end dwellings priced at multiples of median household income, typically featuring reinforced concrete frames, imported facade materials, centralized climate systems, and smart building management platforms designed for capital preservation and lifestyle elevation. Condominiums dominate transaction volume in Ho Chi Minh City and Hanoi where land scarcity pushes vertical development, while villas command the deepest margin pools in satellite townships with golf course and marina adjacencies. Smart home installations within the market trend dimension are accelerating fastest as buyers expect integrated security, energy management, and remote access as baseline specifications rather than premium upgrades.
Vietnam's Ministry of Construction and provincial People's Committees shape project approval timelines, while the National Assembly's Land Law revisions determine foreign ownership quotas and leasehold structures that directly constrain demand composition. The State Bank of Vietnam's credit growth directives and mortgage lending caps influence liquidity conditions for domestic purchasers seeking leveraged entry into premium segments. Stakeholders must monitor regulatory drafting around special economic zone designations and infrastructure bond financing that could unlock new supply corridors beyond current urban boundaries.
Market Dynamics
Vietnam's revised Land Law is restructuring the market's demand composition by tightening foreign ownership quotas and accelerating the rotation toward wealthy domestic buyers as the primary transaction volume driver.
Growth Catalysts
- Smart home integration:Buyers now expect centralized building management platforms, integrated security systems, and remote access controls as baseline specifications rather than premium upgrades. This technology pull is accelerating pre-sales velocity across Ho Chi Minh City's premium condominium pipeline.
- Southern economic corridor concentration:Infrastructure investment and industrial zone expansion across Ho Chi Minh City and surrounding provinces are concentrating high-net-worth household formation in this geography. Developers align supply to this demand cluster.
- State Bank credit directives:Mortgage lending caps and credit growth directives influence liquidity conditions for domestic purchasers seeking leveraged entry into premium segments. Regulatory clarity on lending parameters stabilizes buyer confidence.
Market Restraints
- Land scarcity in metropolitan cores:Vertical development constraints in Ho Chi Minh City and Hanoi push development costs upward and compress project margins. Land banking competition intensifies among established developers.
- Foreign ownership quota friction:The National Assembly's leasehold structure limitations and ownership caps constrain demand composition and complicate capital repatriation for international investors. Transaction velocity suffers from screening complexity.
- Construction input volatility:Reinforced concrete frame costs and imported facade material pricing fluctuate with currency movements and global supply chain disruptions. Project budgeting faces margin erosion from input unpredictability.
Strategic Opportunities
- Special economic zone corridors:Regulatory drafting around infrastructure bond financing and SEZ designations could unlock new supply corridors beyond current urban boundaries. Early land positioning in these corridors offers first-mover returns.
- Wellness amenity convergence:Integration of healthcare, education, and retail ecosystems within residential masterplans creates sticky buyer loyalty and recurring revenue streams. Vingroup's integrated ecosystem model demonstrates this convergence potential.
- Satellite township villa development:Golf course and marina-adjacent land in surrounding provinces commands the deepest margin pools. Horizontal development escapes metropolitan land scarcity constraints.
Industry Challenges
- Project approval timeline uncertainty:Provincial People's Committees and the Ministry of Construction wield discretionary authority over development permits. Regulatory unpredictability stretches pre-construction phases and capital lockup periods.
- Smart building system integration complexity:Legacy building management infrastructure in renovation projects resists seamless integration with new centralized climate and security platforms. Technical interoperability gaps inflate commissioning costs.
- Skilled construction labor scarcity:Japanese engineering standards and precision construction timelines require specialized workforce capabilities. Training pipeline inadequacy constrains quality execution at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Luxury Residential Real Estate Market |
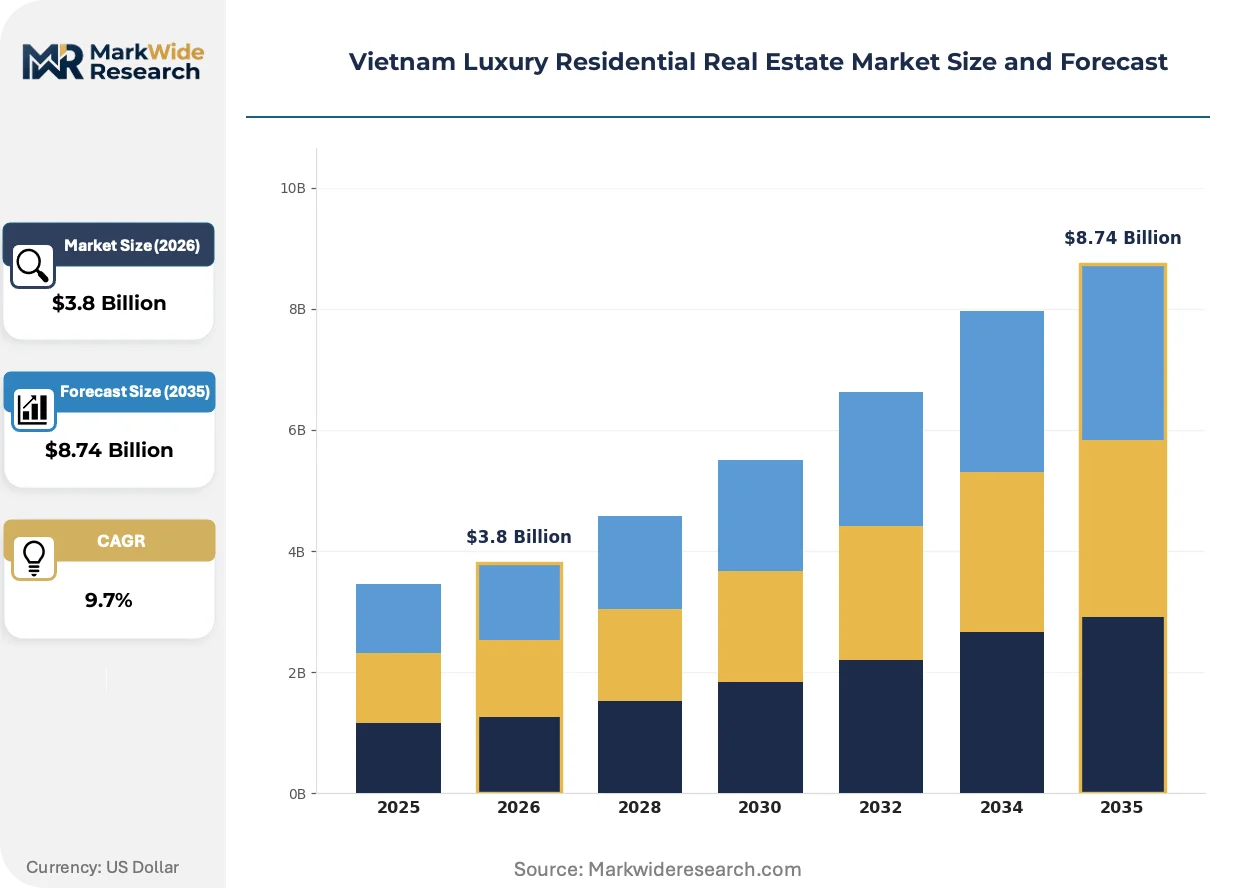
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached Houses, Villas, Condominiums, Penthouses Buyer Profile: Wealthy Individuals, Foreign Investors, Expats, Developers Interior Design Style: Modern, Contemporary, Minimalist, Traditional Market Trend: Smart Homes, Eco-Friendly Design, Luxury Amenities, Gated Communities |
| Companies Covered | Vingroup JSC, Nomura Real Estate Vietnam, CapitaLand Development (Vietnam), Dat Xanh Group, NovaLand Group, Masterise Homes, SonKim Land Corporation, Phu Long Real Estate Corporation, Gamuda Land Vietnam, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Luxury Residential Real Estate Market Evolving Landscape
Technology integration, regulatory recalibration, and buyer behavior rotation are simultaneously reshaping Vietnam's luxury residential competitive landscape. These forces compress traditional development cycles and elevate baseline product specifications.
Centralized building management platforms incorporating IoT-enabled energy monitoring, biometric access control, and predictive maintenance algorithms are displacing standalone legacy systems in premium condominium developments. Domestic buyers with international exposure now reject projects lacking integrated smart infrastructure. This technology pull is compressing the competitive set to developers with in-house digital capability or established technology partnerships.
Vietnam's Ministry of Construction is drafting enhanced building energy efficiency standards that will mandate solar-ready infrastructure and thermal performance thresholds in new premium developments. These codes will elevate construction costs and disqualify developers lacking technical compliance capacity. The southern economic corridor, with its concentration of flagship projects, faces the steepest compliance timeline pressure.
Buyer evaluation criteria have pivoted toward total-cost-of-ownership calculations encompassing maintenance fees, energy consumption, and amenity access rather than upfront unit pricing alone. Sales channels are restructuring around immersive digital showrooms and virtual unit customization tools that compress the decision cycle. Ho Chi Minh City's premium segment exhibits this behavioral shift most acutely, with domestic buyers demanding transparent lifecycle cost disclosures before commitment.
Vietnam Luxury Residential Real Estate Market Segmentation
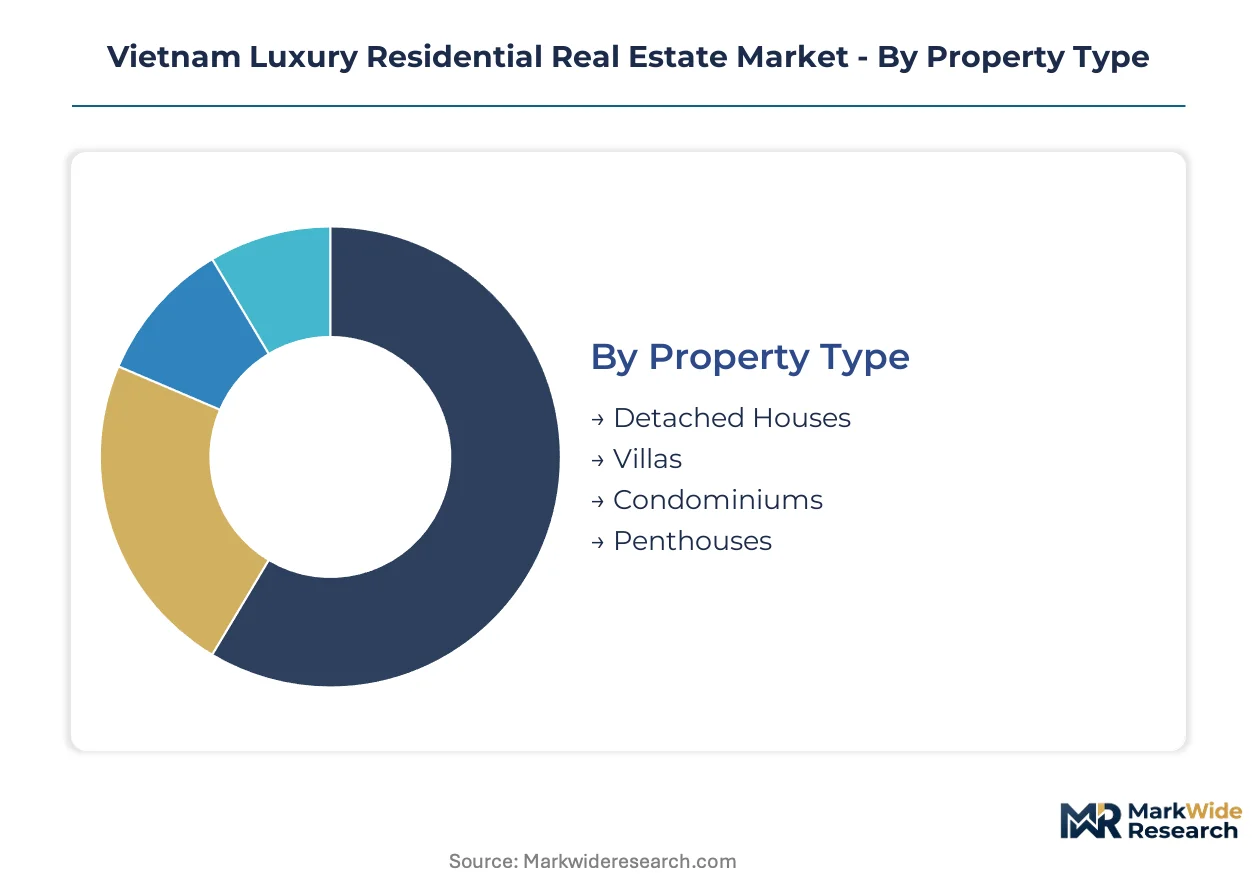
Property type, buyer composition, and technology integration define how developers allocate capital across Vietnam's luxury pipeline. Segmentation clarity reveals where pre-sales velocity concentrates and which amenity bundles command premium pricing.
Property Type:
Channel distribution varies sharply by vertical form, with condominiums flowing through brokerage networks and villas transacting via direct developer relationships and private banking referrals.
- Condominiums:Reinforced concrete towers with centralized climate systems and smart building management platforms dominate transaction volume in Ho Chi Minh City and Hanoi. Demand clusters in the southern economic corridor where land scarcity pushes vertical development and wealthy domestic buyers expect integrated security and energy management as baseline specifications.
- Villas:Horizontal developments on golf course and marina-adjacent land in surrounding provinces command the deepest margin pools. These projects escape metropolitan land scarcity constraints while offering developers recurring revenue through maintenance and amenity management contracts.
- Detached Houses:Standalone structures on individual land titles appeal to buyers seeking full ownership control and customization flexibility. Transactions concentrate in satellite townships where infrastructure bond financing is unlocking new supply corridors.
- Penthouses:Upper-floor units in premium towers combine vertical living efficiency with expanded private outdoor space. Buyers evaluate total-cost-of-ownership calculations encompassing maintenance fees and amenity access rather than upfront unit pricing alone.
Condominiums dominate installed base. Villas are where expansion concentrates.
Buyer Profile:
Cost tier stratification separates leveraged domestic purchasers from all-cash international capital, with each cohort accessing distinct financing channels and legal structures.
- Wealthy Individuals:Vietnamese high-net-worth households are rotating into the market as the primary transaction volume driver under revised Land Law screening. This cohort leverages State Bank of Vietnam credit directives and mortgage lending caps to structure leveraged entry into premium segments.
- Foreign Investors:International capital faces tighter ownership quotas and leasehold structure limitations that constrain demand composition and complicate capital repatriation. Transaction velocity suffers from National Assembly screening complexity and regulatory unpredictability.
- Expats:Long-term foreign residents seek quality-of-life elevation through proximity to international schools and healthcare infrastructure. Demand aligns with Vingroup's integrated ecosystem model combining retail, education, and residential amenities.
- Developers:Corporate purchasers acquire land positions and unfinished inventory for portfolio assembly or strategic blocking. This segment concentrates in early positioning around special economic zone corridors and infrastructure bond financing unlocks.
Wealthy individuals now drive transaction velocity. Foreign investors face structural friction.
Interior Design Style:
Application context determines specification intensity, with investment properties prioritizing durability and owner-occupier units emphasizing personalization.
- Modern:Clean lines, open floor plans, and imported facade materials characterize this specification tier. Ho Chi Minh City's premium condominium pipeline exhibits this style most acutely as domestic buyers with international exposure reject dated aesthetics.
- Contemporary:Evolving interpretations of current trends with flexible spatial configurations accommodate changing household structures. This approach dominates renovation projects where legacy building management infrastructure resists seamless smart system integration.
- Minimalist:Reduced visual complexity and concealed storage systems align with wellness-focused buyer priorities. The style gains traction among buyers calculating total-cost-of-ownership through reduced maintenance and energy consumption.
- Traditional:Vietnamese architectural references and natural material palettes appeal to heritage-conscious purchasers. Demand concentrates in villa developments where horizontal form permits greater stylistic expression.
Modern specifications dominate new construction. Contemporary is climbing fastest in renovation activity.
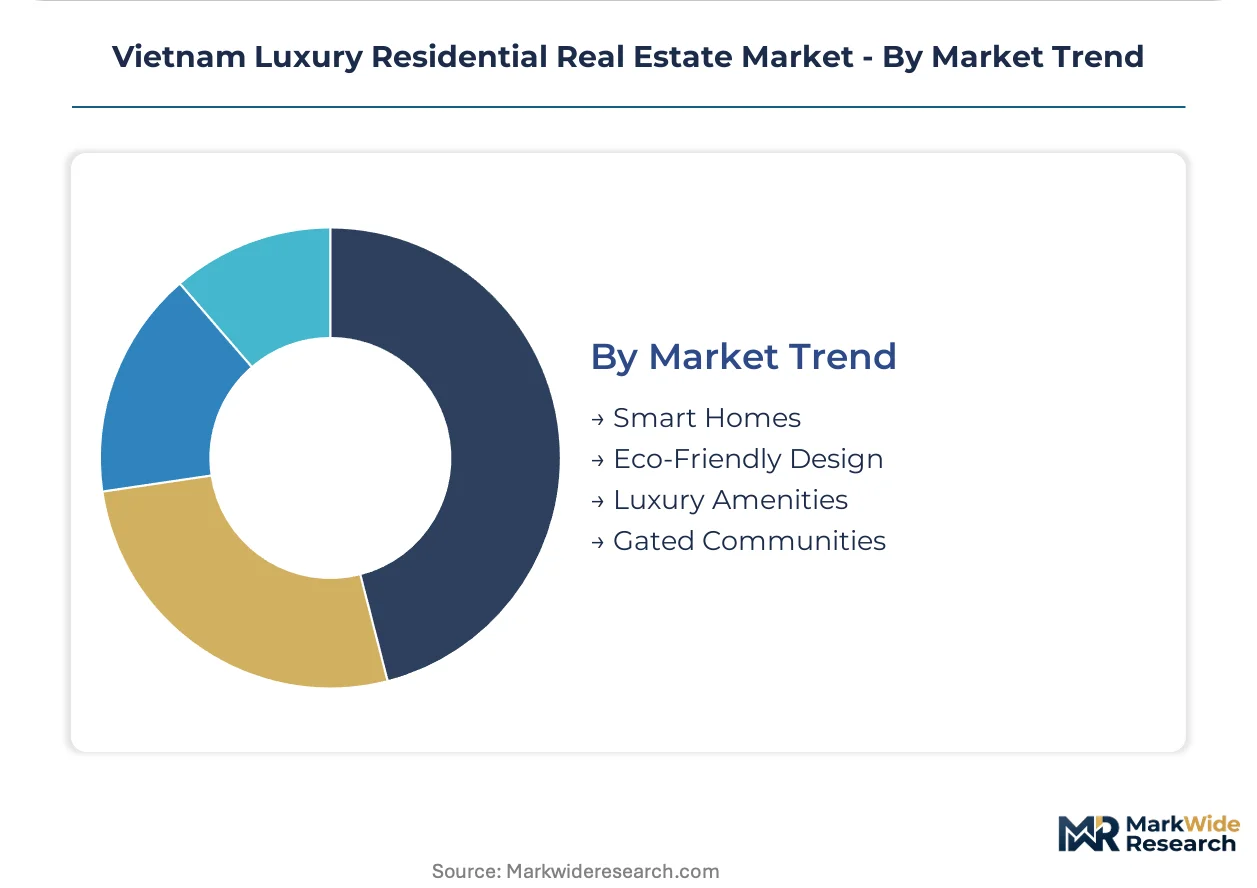
Market Trend:
Maturity differentiation separates established amenity categories from emerging technology integrations that reshape baseline buyer expectations.
- Smart Homes:IoT-enabled energy monitoring, biometric access control, and predictive maintenance algorithms are displacing standalone legacy systems. This trend is accelerating pre-sales velocity across Ho Chi Minh City's premium condominium pipeline as buyers reject projects lacking integrated digital infrastructure.
- Eco-Friendly Design:Solar-ready infrastructure and thermal performance thresholds are gaining mandatory status through Ministry of Construction drafting. These codes will elevate construction costs and disqualify developers lacking technical compliance capacity.
- Luxury Amenities:Private cinemas, wine cellars, and wellness facilities remain standard competitive requirements in premium developments. Margin pressure intensifies as amenity arms races compress developer returns.
- Gated Communities:Masterplanned enclaves with integrated security and controlled access appeal to privacy-conscious buyers. Satellite township developments in surrounding provinces leverage this format to escape metropolitan land scarcity constraints.
Smart home integration dominates buyer evaluation. Eco-friendly design is gaining regulatory momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports luxury residential development expertise and capital flows toward Ho Chi Minh City and Hanoi as primary destination markets, with satellite provinces absorbing spillover demand from land-constrained metropolitan cores.
Southern Economic Corridor
Ho Chi Minh City and surrounding provinces Binh Duong, Dong Nai, and Long An concentrate high-net-worth household formation and premium condominium supply. The Ministry of Construction's building energy efficiency drafting mandates solar-ready infrastructure and thermal performance thresholds that elevate compliance costs. Developers prioritize smart home integration across Vinhomes Central Park and comparable flagship projects to capture domestic buyer rotation.
Red River Delta
Hanoi and adjacent Bac Ninh, Hung Yen, and Hai Duong provinces exhibit accelerating villa development on golf course and marina-adjacent land. Provincial People's Committees exercise discretionary authority over project approvals, stretching pre-construction timelines. The State Bank of Vietnam's credit growth directives influence leveraged entry conditions for wealthy domestic purchasers in this northern cluster.
Central Coast
Da Nang and Khanh Hoa province attract expatriate and second-home demand through integrated resort-residential hybrids. Foreign ownership quota friction under National Assembly Land Law revisions constrains transaction velocity and complicates capital repatriation. Nomura Real Estate Vietnam's precision construction standards anchor quality execution in this tourism-linked corridor.
Mekong Delta Fringe
Can Tho and An Giang province emerge as secondary luxury nodes as infrastructure bond financing unlocks new supply corridors beyond traditional urban boundaries. Special economic zone regulatory drafting could accelerate land positioning returns for early movers. Horizontal villa formats escape metropolitan land scarcity constraints while offering recurring amenity revenue streams.
Vietnam Luxury Residential Real Estate Market Competitive Landscape
Listed leaders compete with private specialists across capital access and land-banking velocity, creating a tiered structure where scale-driven conglomerates face agile boutique developers. The market fragments across integrated ecosystem builders, foreign joint-venture platforms, and domestic specialists with provincial relationships. Three archetypes dominate: conglomerate-affiliated developers with captive retail and healthcare assets; Japanese-engineered precision builders; and Singaporean fund-management disciplined operators. Competitive moves concentrate on strategic land-banking in transit-oriented locations and technology partnerships for smart building integration.
Within the conglomerate-affiliated tier, Vingroup JSC exemplifies integrated ecosystem development through its Vinhomes portfolio combining residential, retail, education, and healthcare amenities. Nomura Real Estate Vietnam occupies a position representing Japanese engineering standards and construction timeline discipline. CapitaLand Development (Vietnam) anchors the foreign joint-venture segment with Singaporean fund-management approaches to selective land-banking.
| Leading Market Players |
|---|
| Vingroup JSC |
| Nomura Real Estate Vietnam |
| CapitaLand Development (Vietnam) |
| Dat Xanh Group |
| NovaLand Group |
| Masterise Homes |
| SonKim Land Corporation |
| Phu Long Real Estate Corporation |
| Gamuda Land Vietnam |
| Others |
Value Network & Pricing Analysis
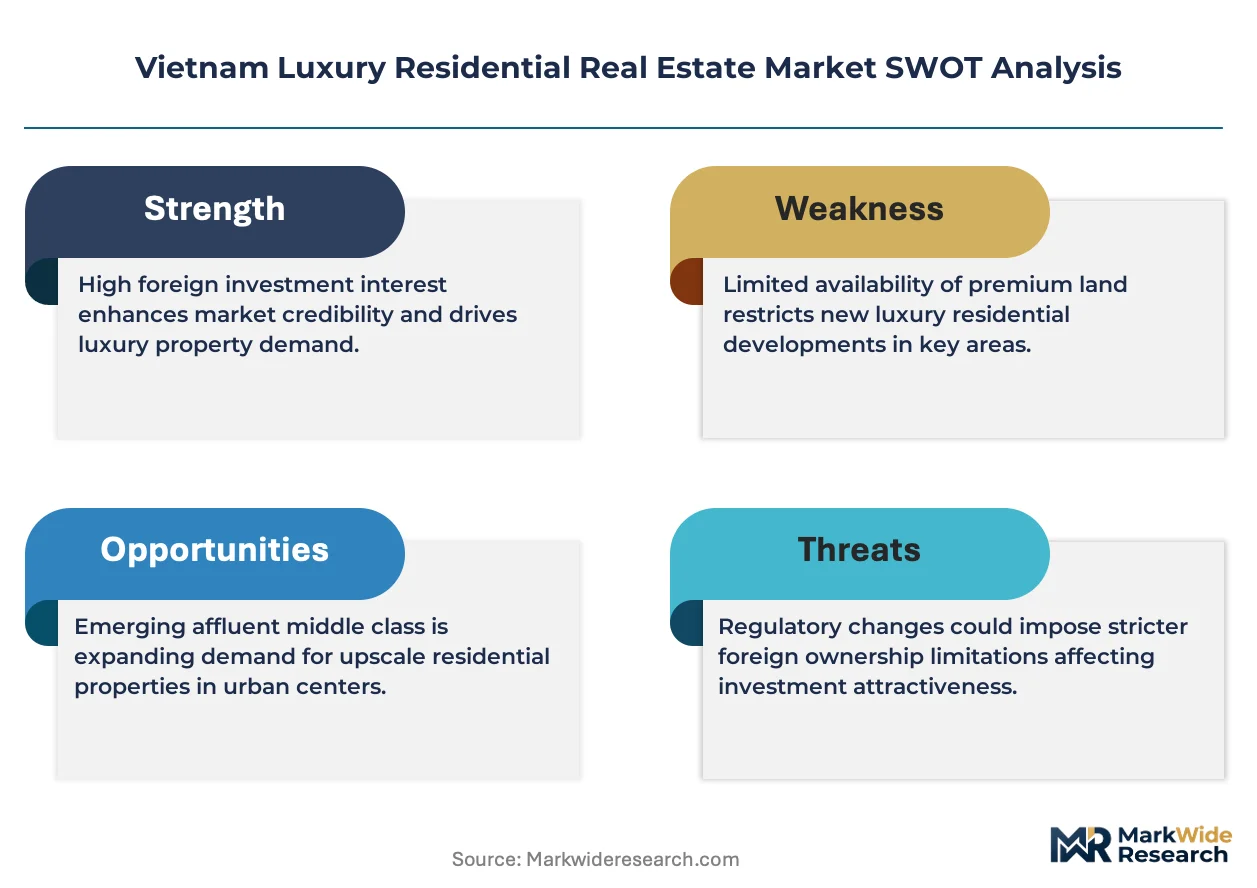
Ministry of Construction energy efficiency drafting gates both developer qualification and unit price differentiation simultaneously. Projects lacking solar-ready infrastructure and thermal compliance capacity face disqualification from premium pricing tiers while compliant developers capture margin premiums.
Pricing Analysis
Smart building technology generations stratify pricing across legacy-specification, current-integrated, and next-generation predictive platforms. Three-tier pricing separates fully automated towers from semi-smart mid-tier developments and basic legacy inventory. Price differentiation rests on certification grade against Ministry of Construction standards and vertical integration of building management systems. Pricing pressure stems from construction input volatility in reinforced concrete and imported facade materials. Leveraged domestic purchasers exhibit highest price sensitivity through mortgage lending cap constraints, while all-cash villa buyers absorb premium positioning.
Supply Chain Analysis
Hai Phong port congestion and customs clearance velocity chokepoints tether project timelines to logistics infrastructure capacity. Reinforced concrete frame production centers on Vietnam, China, and South Korea, while smart building management platforms draw from Singaporean and Japanese technology providers. Raw material dependencies span steel rebar, imported facade ceramics, and IoT sensor arrays. Single-source vulnerability concentrates in specialized climate control equipment from Japanese suppliers. Distribution runs through direct developer sales channels for villas and brokerage networks for condominium inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's luxury residential market sits in cyclical recovery as wealthy domestic buyer rotation accelerates pre-sales velocity. State Bank credit directive clarity stabilizes leveraged entry conditions for this demand cohort.
For Market Incumbents: Secure land-banking positions in special economic zone corridors before regulatory drafting finalizes infrastructure bond financing unlocks. Defend against margin compression by deepening captive supply of smart building management platforms through technology partnerships rather than third-party procurement. Consolidate maintenance and amenity management contracts into recurring revenue streams that stabilize cash flow across development cycles.
For New Entrants and Emerging Players: Differentiate on Japanese-engineered precision construction timelines that established developers struggle to replicate at scale. Target satellite township villa development in golf course-adjacent land surrounding Ho Chi Minh City, where horizontal formats escape metropolitan land scarcity and foreign ownership quota friction constrains incumbent expansion. Pursue direct private banking referral channels that bypass competitive brokerage networks.
For Investors and Strategic Acquirers: National Assembly Land Law revision implementation reshapes the acquisition landscape by compressing foreign investor transaction velocity and elevating domestic buyer-dependent assets. Five-to-ten year viability favors integrated ecosystem developers with captive retail, education, and healthcare amenities that generate sticky recurring revenue. Monitor State Bank of Vietnam mortgage lending cap adjustments as the primary inflection signal for leveraged demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Technology Partnership | Establishes baseline IoT infrastructure compliance against Ministry of Construction drafting mandates. |
| Special Economic Zone Land Positioning | Captures first-mover returns as infrastructure bond financing unlocks new supply corridors beyond urban boundaries. |
| Integrated Ecosystem Development | Replicates Vingroup's model combining residential, retail, education, and healthcare amenities for buyer loyalty. |
| Japanese Engineering Standards Adoption | Differentiates quality execution against competitors facing skilled construction labor scarcity constraints. |
| Satellite Township Villa Expansion | Escapes metropolitan land scarcity while accessing deepest margin pools in golf course-adjacent developments. |
Research Methodology
Operator-level perspectives from project development directors, provincial People's Committee planning officers, mortgage lending executives at State Bank-regulated institutions, and smart building technology integration specialists anchored the qualitative base. Secondary validation drew from Ministry of Construction regulatory filings, National Assembly Land Law revision documentation, State Bank of Vietnam credit growth directive circulars, and provincial infrastructure bond financing prospectuses. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic absorption modeling.
Sensitivity analysis tested forecast robustness across mortgage lending cap adjustment scenarios, foreign ownership quota implementation variants, and construction input cost volatility assumptions. Segmentation dimensions spanned property type, buyer profile, interior design specification, and technology integration tier across the projection horizon. CAGRs derived from historical absorption velocity patterns adjusted for regulatory regime change impacts. Forecast inputs incorporated special economic zone designation probability and smart building mandate compliance timeline acceleration.
The analysis sits within stated boundaries; outcomes outside State Bank credit directive continuity or Ministry of Construction code implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding wealthy domestic buyer rotation persistence and foreign investor screening complexity stability. Practitioners should keep alternative scenarios live as National Assembly regulatory drafting and infrastructure bond financing mechanics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market