
 Connected Distribution Center Market | 2026-2036
Connected Distribution Center Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Distribution Center Market Analytics
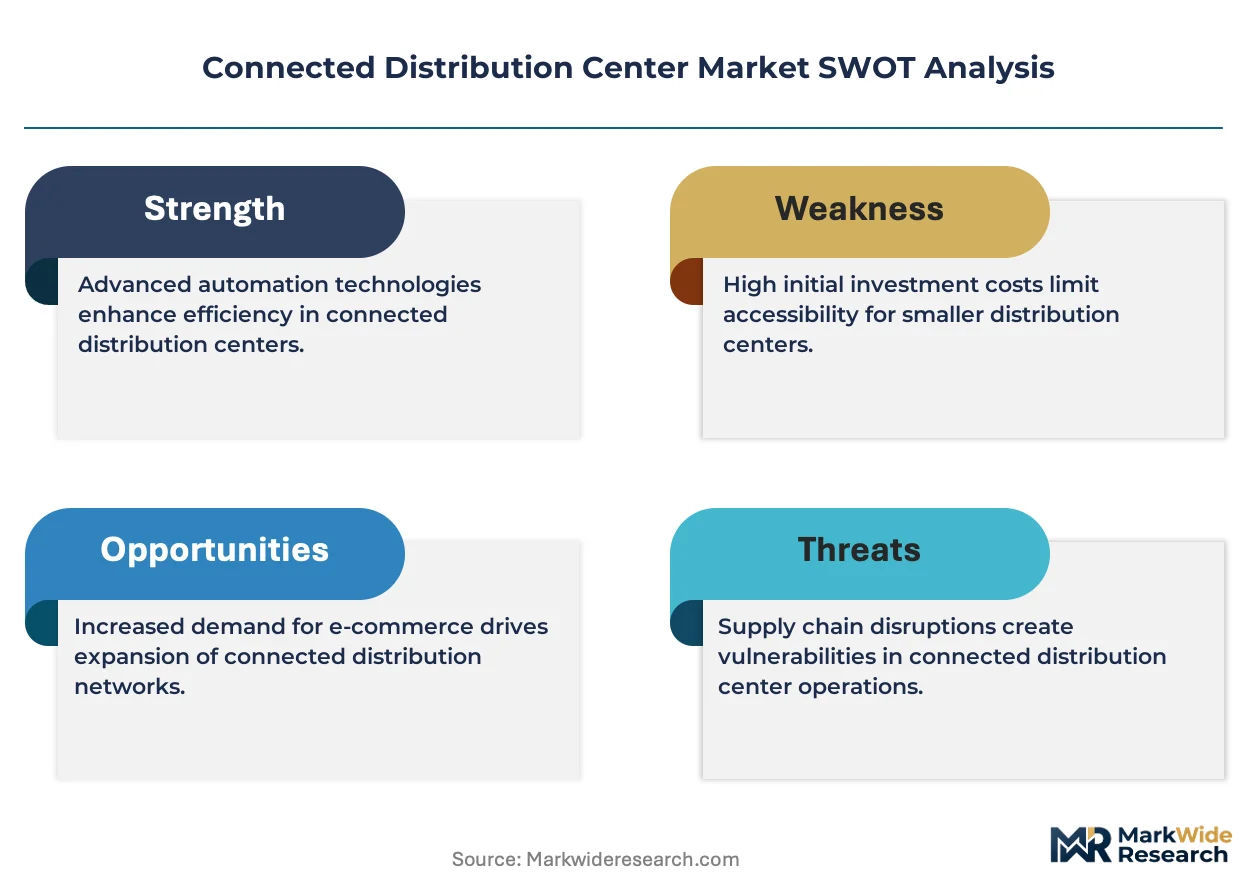
REACH is decoupling chemical traceability requirements from legacy warehouse management architectures. Honeywell International Inc leverages its sensor portfolio to anchor real-time environmental monitoring in pharmaceutical distribution corridors. SAP SE competes through embedded ERP-to-warehouse data pipelines that synchronize inventory records across multi-node networks. Robert Bosch GmbH specializes in edge-computing hardware that processes pallet-level telemetry without cloud dependency.
A connected distribution center integrates IoT sensors, automated material handling equipment, and cloud-native software platforms to synchronize inventory movement, labor allocation, and transportation scheduling across fulfillment nodes. The architecture relies on sub-second latency between edge devices and warehouse management systems to enable dynamic slotting and predictive replenishment. IoT Solutions and Warehouse Management Systems capture the dominant share of technology spending as operators prioritize visibility infrastructure over physical automation. Cloud-based deployments are expanding fastest among mid-market third-party logistics providers seeking to avoid capital-intensive on-premise installations. Maintenance services generate recurring revenue streams that software vendors increasingly bundle with platform subscriptions.
The EU AI Act, FDA track-and-trace mandates, and OSHA warehouse safety standards collectively elevate compliance costs for operators deploying autonomous systems. ECHA substance registration requirements intersect with inventory software as distributors must link chemical batch records to storage location telemetry. Stakeholders must weigh regulatory fragmentation against platform consolidation as jurisdictions diverge on algorithmic accountability and data residency rules.
Market Dynamics
Latency compression between edge devices and warehouse management systems is forcing operators to rebuild network architectures around sub-second telemetry loops rather than retrofitting legacy infrastructure.
Growth Catalysts
- E-commerce fulfillment networks:Third-party logistics providers in Germany are expanding IoT-enabled distribution corridors to handle same-day delivery windows. Stuttgart and Munich industrial clusters anchor this buildout.
- EU AI Act compliance mandates:Automated decision-making systems in European logistics facilities now require algorithmic accountability documentation. This drives replacement of opaque legacy automation with auditable platforms.
- Edge computing hardware:Pallet-level telemetry processing without cloud dependency reduces bandwidth costs and enables real-time slotting decisions in high-throughput environments.
Market Restraints
- Capital intensity of cloud-native migration:Mid-market operators face prohibitive upfront costs for sensor deployment and platform licensing despite subscription models.
- Regulatory fragmentation:Divergent algorithmic accountability rules between EU AI Act requirements and OSHA warehouse safety standards create compliance engineering overhead.
- Technical debt in legacy WMS:Decades-old warehouse management architectures lack API compatibility with modern IoT sensor networks, forcing parallel system operation.
Strategic Opportunities
- Pharmaceutical cold chain corridors:FDA track-and-trace mandates intersect with ECHA substance registration requirements, creating demand for integrated environmental monitoring and batch record linkage.
- Maintenance service bundling:Software vendors can capture recurring revenue by wrapping predictive equipment servicing with platform subscriptions rather than standalone hardware sales.
- Convergence of digital twin and IoT platforms:Warehouse simulation models fed by live sensor streams enable scenario testing for labor allocation and slotting optimization.
Industry Challenges
- Interoperability gaps between ERP and WMS data pipelines:Multi-node inventory synchronization requires custom integration work that delays deployment timelines and inflates professional services costs.
- Cyber-physical security expertise scarcity:Operators struggle to hire engineers capable of securing both OT sensor networks and IT cloud platforms against coordinated attacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Distribution Center Market |
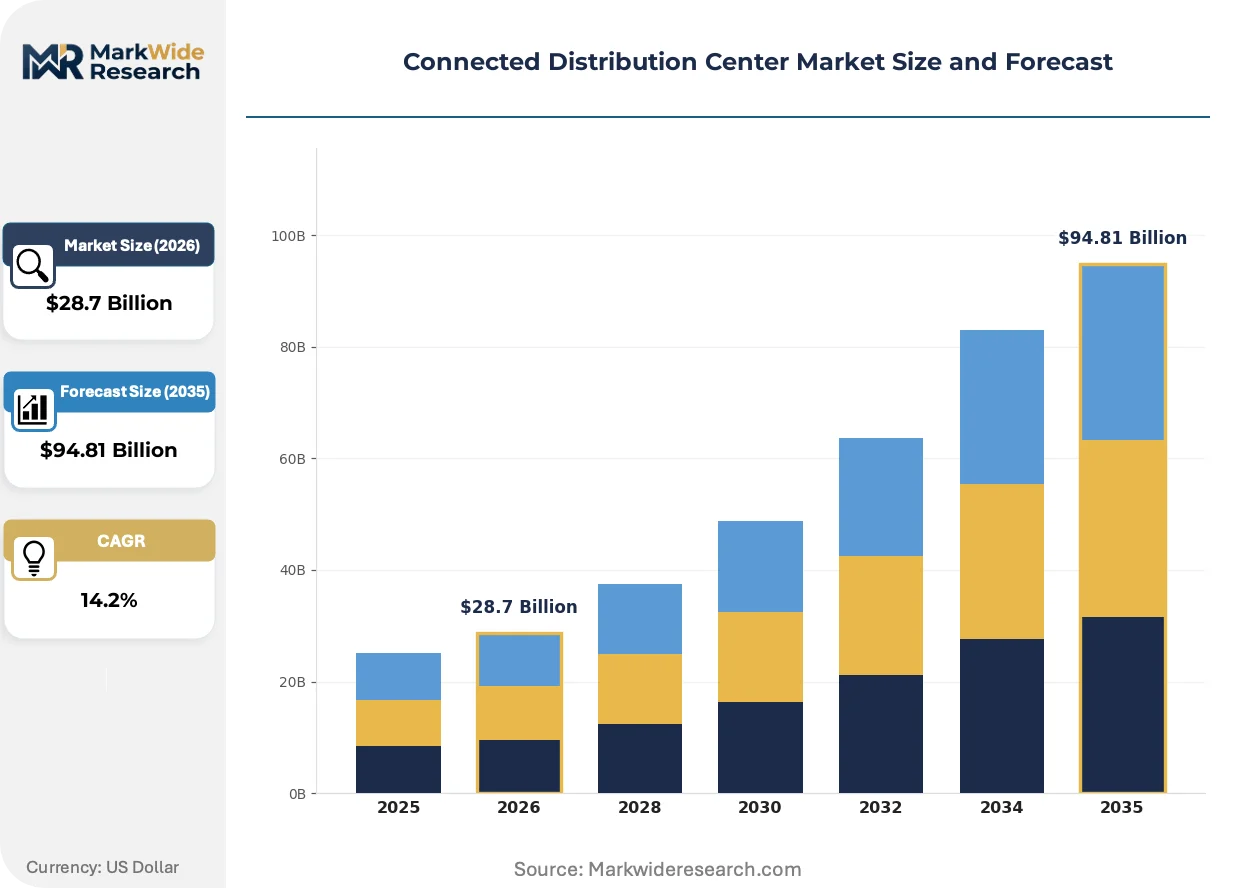
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Automation Systems, Inventory Management Software, Warehouse Management Systems End User: E-commerce, Retail, Third-party Logistics, Food & Beverage Service Type: Consulting, Implementation, Maintenance, Support Deployment: On-premise, Cloud-based, Hybrid, Edge Computing |
| Companies Covered | Cisco Systems, Inc., IBM Corporation, Honeywell International Inc, SAP SE, Oracle Corporation, Microsoft Corporation, Intel Corporation, Robert Bosch GmbH, AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Distribution Center Market Evolving Landscape
Real-time environmental monitoring is rewriting how pharmaceutical and chemical distributors architect their compliance infrastructure. Three distinct shifts are compressing deployment timelines and reshaping vendor selection criteria.
Digital twin simulation is rewriting warehouse design methodologies by enabling virtual commissioning of automated material handling equipment before physical installation. Pharmaceutical distributors in Germany are adopting these tools fastest to validate FDA-compliant temperature mapping without disrupting live operations. The technology compresses facility ramp-up timelines from months to weeks.
REACH decoupling requirements are forcing chemical distributors to rebuild inventory software architectures around substance-level traceability rather than SKU-level tracking. ECHA registration data must now link directly to storage location telemetry, creating demand for specialized middleware. European third-party logistics providers face the steepest compliance engineering burden.
Mid-market buyers are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. Third-party logistics providers in Germany specifically are rejecting sensor-hardware-only vendors in favor of bundled IoT-software-maintenance contracts. This preference shift disadvantages pure-play hardware manufacturers and rewards full-stack platform vendors with recurring revenue models.
Connected Distribution Center Market Segmentation
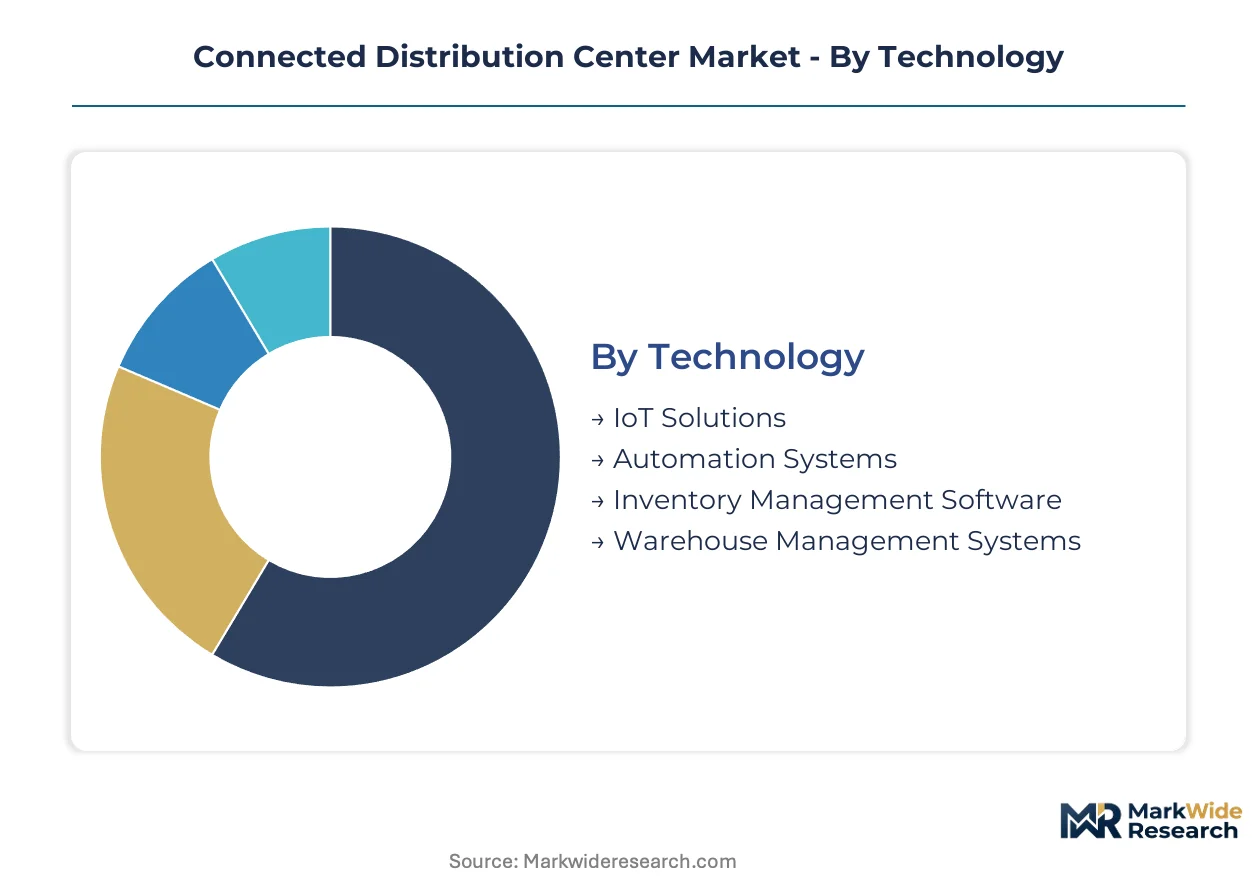
Segmentation in the Connected Distribution Center Market reveals how regulatory pressure and operational complexity concentrate spending differently across technology stacks and service models. Understanding these divisions helps operators align procurement decisions with compliance mandates and network architecture requirements.
Technology:
EU AI Act documentation requirements and FDA track-and-trace mandates impose distinct certification burdens: IoT Solutions and Warehouse Management Systems face algorithmic accountability audits, while Automation Systems must satisfy OSHA safety validation and CE marking protocols.
- IoT Solutions:Sensor networks capturing pallet-level telemetry, temperature, and location data in real time. Demand clusters in German pharmaceutical corridors around Stuttgart and Munich, where ECHA substance registration requirements intersect with environmental monitoring mandates.
- Warehouse Management Systems:Cloud-native platforms synchronizing inventory records across multi-node fulfillment networks. Third-party logistics providers in Germany prioritize these for EU AI Act compliance, replacing opaque legacy architectures with auditable decision logs.
- Automation Systems:Automated material handling equipment including conveyors, sorters, and robotic pickers. Mid-market operators defer adoption due to capital intensity despite OSHA safety standard alignment.
- Inventory Management Software:ERP-integrated modules tracking SKU-level and substance-level batch records. REACH decoupling requirements are forcing rebuilds of legacy architectures around ECHA data linkages.
Leading the category by volume: Warehouse Management Systems. Growing fastest: IoT Solutions.
End User:
Cost tier stratification separates capital-rich pharmaceutical distributors from margin-constrained food operators, with compliance engineering budgets determining technology penetration depth.
- E-commerce:Fulfillment networks demanding sub-second latency for same-day delivery windows. German industrial clusters anchor the steepest buildout of IoT-enabled distribution corridors.
- Third-party Logistics:Multi-tenant operators consolidating vendor relationships around bundled platform stacks. These mid-market buyers reject hardware-only vendors in favor of integrated IoT-software-maintenance contracts.
- Retail:Brick-and-mortar networks retrofitting existing facilities with edge computing hardware for real-time slotting decisions.
- Food & Beverage:Cold chain operators with limited budgets for cloud-native migration despite FDA track-and-trace exposure.
Expanding most quickly: Third-party Logistics. Capturing largest share: E-commerce.
Service Type:
Revenue model maturity separates one-time implementation fees from recurring maintenance streams, with vendors restructuring pricing to capture lifecycle value.
- Maintenance:Predictive equipment servicing bundled with platform subscriptions. Software vendors capture recurring revenue by wrapping hardware uptime guarantees into long-term contracts.
- Implementation:Sensor deployment, WMS configuration, and ERP integration requiring custom professional services. Interoperability gaps between data pipelines inflate timelines and costs.
- Consulting:Compliance engineering support for EU AI Act documentation and ECHA substance registration alignment.
- Support:Help desk and technical assistance for cloud-native platform operation.
Highest margin capture: Maintenance. Steepest expansion trajectory: Implementation.
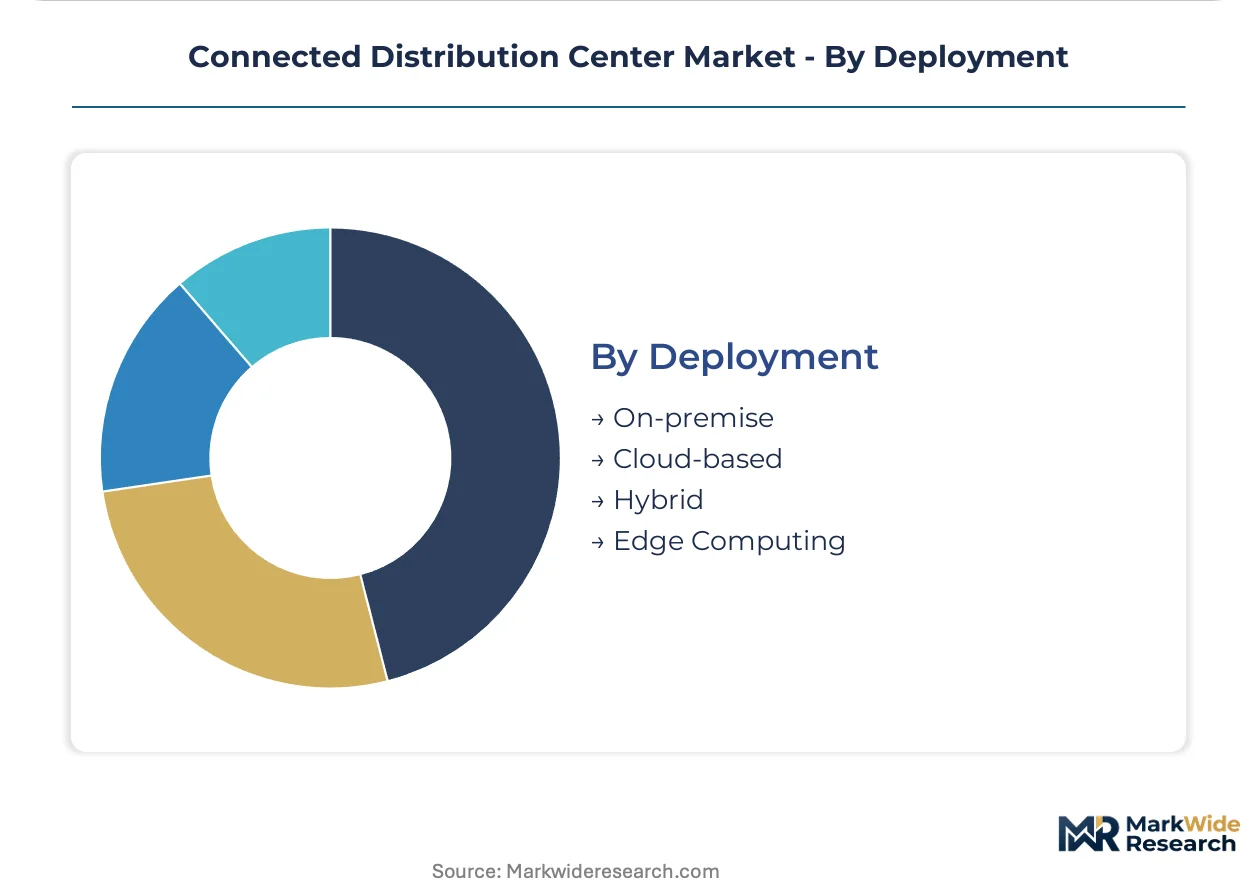
Deployment:
Supply concentration in cloud infrastructure favors subscription models, while edge architectures address bandwidth constraints in high-throughput environments.
- Cloud-based:Mid-market third-party logistics providers in Germany adopt these deployments fastest to avoid capital-intensive on-premise installations. Subscription licensing aligns with limited upfront budgets.
- Edge Computing:Pallet-level telemetry processing without cloud dependency reduces bandwidth costs. Robert Bosch GmbH specializes in hardware enabling real-time slotting decisions independent of network latency.
- Hybrid:Architectures splitting sensitive batch records on-premise while pushing analytics to cloud platforms.
- On-premise:Legacy installations retained by operators with technical debt in decades-old WMS architectures lacking API compatibility.
Gaining share fastest: Cloud-based. Dominant installed base: On-premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters concentrate demand for connected distribution infrastructure, with Stuttgart and Munich anchoring the densest buildout of IoT-enabled fulfillment networks. Regulatory pressure from the EU AI Act and ECHA substance registration requirements accelerates platform replacement cycles across European logistics corridors.
United States
FDA track-and-trace mandates and OSHA warehouse safety standards drive compliance spending among pharmaceutical and e-commerce operators. Third-party logistics providers in the Midwest industrial belt retrofit legacy facilities with cloud-native warehouse management systems. The Chicago-Milwaukee corridor anchors the fastest adoption of edge computing hardware for real-time slotting decisions.
Germany
EU AI Act algorithmic accountability requirements force replacement of opaque legacy automation with auditable platforms. ECHA REACH decoupling mandates intersect with inventory software architectures around Stuttgart and Munich. Baden-Württemberg's automotive supplier networks deploy pallet-level telemetry systems to synchronize just-in-sequence delivery windows.
China
NMPA pharmaceutical traceability rules and MIIT IoT standards reshape cold chain infrastructure investments. Yangtze River Delta fulfillment operators prioritize hybrid cloud-edge deployments to manage bandwidth constraints during peak e-commerce periods. Shanghai's free trade zone clusters demand for multi-tenant warehouse management platforms serving cross-border trade.
United Kingdom
Post-Brexit customs complexity drives demand for inventory software linking ERP systems to border clearance platforms. The Midlands logistics triangle concentrates investment in automated material handling equipment serving retail distribution networks. Birmingham-based third-party logistics providers consolidate vendor relationships around bundled IoT-software-maintenance contracts.
Japan
METI productivity targets and PMDA pharmaceutical distribution standards accelerate warehouse automation adoption. The Kanto region's aging workforce pressures operators toward autonomous material handling systems with predictive maintenance capabilities. Tokyo Bay industrial zones deploy digital twin simulation tools to compress facility commissioning timelines.
Connected Distribution Center Market Competitive Landscape
German industrial conglomerates anchor one tier; US software and networking specialists hold another. The vendor base organizes around three strategic archetypes: full-stack platform providers bundling hardware-software-maintenance, pure-play sensor hardware manufacturers, and enterprise software vendors extending ERP-to-warehouse data pipelines. Consolidation pressures favor integrated platform vendors with recurring revenue models over point-solution specialists. Strategic moves center on M&A to fill capability gaps and geographic expansion to capture EU AI Act-driven replacement demand.
Within the full-stack platform tier, Honeywell International Inc and Robert Bosch GmbH exemplify industrial conglomerates leveraging sensor portfolios and edge-computing hardware respectively. SAP SE occupies a position among enterprise software vendors extending ERP-native warehouse management capabilities. These three anchors represent distinct competitive vectors: environmental monitoring specialization, cloud-independent telemetry processing, and multi-node inventory synchronization infrastructure.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| IBM Corporation |
| Honeywell International Inc |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Intel Corporation |
| Robert Bosch GmbH |
| AT&T Inc. |
| Others |
Value Network & Pricing Analysis
Edge-computing engineers concentrated in Stuttgart and Munich command wage premiums that compress margins for mid-market third-party logistics providers, widening spreads between premium full-stack platform bundles and economy sensor-hardware-only tiers.
Pricing Analysis
Volume capture concentrates in subscription-based SaaS tiers while margin capture accrues to maintenance-bundled platforms. Pricing stratifies across premium, standard, and economy tiers based on EU AI Act certification level and after-sales service depth. Cost compression in the standard tier is intensifying because mid-market operators defer capital-intensive sensor deployment. Food and beverage operators exhibit the highest price sensitivity; pharmaceutical distributors in Germany show the least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale e-commerce buyer demand in Germany, while value-added distributors serve fragmented mid-market logistics providers across the United Kingdom and Japan. Component manufacturing concentrates in Germany, China, and the United States. Sensor hardware draws from semiconductor foundries in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for edge-computing chipsets amid export control tightening.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyber-physical security engineer scarcity props pricing for integrated platform vendors, constraining supply expansion for mid-market buyers seeking bundled IoT-software-maintenance contracts.
For Market Incumbents: Deploy predictive maintenance service bundling to lock in recurring revenue against pure-play sensor hardware competitors. Consolidate channel control through exclusive distribution agreements with Stuttgart and Munich industrial clusters. Backward integration into edge-computing chipset sourcing mitigates Taiwan supply exposure. For New Entrants and Emerging Players: Capture white-space in food and beverage cold chain corridors where FDA track-and-trace mandates intersect with limited cloud-native migration budgets. Target United Kingdom third-party logistics providers facing post-Brexit customs complexity. Lead with consulting-heavy implementation services to bypass incumbent maintenance lock-in. For Investors and Strategic Acquirers: Re-rating potential sits with full-stack platform vendors given EU AI Act-driven replacement cycles forcing legacy system obsolescence. Long-term viability favors vendors with captive edge-computing hardware capabilities and recurring revenue models exceeding sixty percent of total sales. Watch FDA track-and-trace enforcement intensity as inflection signal for pharmaceutical corridor spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-to-WMS data pipeline consolidation reduces professional services overhead for multi-node networks. |
| Acquisition of Specialist Firm | Edge-computing hardware targets fill capability gaps in cloud-independent telemetry processing. |
| Geographic Expansion | EU AI Act compliance engineering demand in Germany accelerates platform replacement timelines. |
| Strategic Partnership | Sensor-hardware-software bundling aligns with mid-market buyer preference for integrated contracts. |
| Product Launch | Digital twin simulation tools compress pharmaceutical facility commissioning from months to weeks. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone for market sizing. Primary interviews with warehouse operations directors, IoT platform engineers, third-party logistics procurement leads, and ECHA compliance consultants validated demand assumptions. Bottom-up sensor deployment counts and top-down logistics infrastructure spending estimates were triangulated to anchor volume projections.
Historical trendline analysis of cloud-native platform adoption rates informed growth trajectory modeling across the projection horizon. Segmentation dimensions included technology stack, deployment model, end-user vertical, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for EU AI Act implementation pacing and FDA track-and-trace enforcement intensity.
The model holds under stable regulatory implementation timelines; deviation in EU AI Act audit stringency or OSHA warehouse safety standard revision would shift replacement demand curves. Forecasts reflect documented assumptions regarding edge-computing cost decline rates and mid-market subscription adoption elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
UAE Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Data Center Rack Solutions Market