
 Domestic Sauna Heaters Market | 2026-2036
Domestic Sauna Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Domestic Sauna Heaters Market Insights
Stainless steel heating elements is realigning cost structures across the domestic sauna heaters industry as manufacturers phase out lower-grade alloys. Harvia leverages captive foundry capacity in Finland to control metallurgical quality from ingot to finished element. HUUM anchors its position through R&D intensity in smart control systems, while Amerec competes aggressively on North American distribution breadth and aftermarket parts availability.
Domestic sauna heaters are electromechanical or combustion devices engineered to raise enclosed cabin temperatures between 70°C and 100°C, utilizing resistive coils, infrared panels, or wood-fired stones to generate dry heat for residential wellness and therapeutic applications. Electric sauna heaters dominate installed base across urban and suburban dwellings where venting constraints limit combustion options, while infrared sauna heaters represent the fastest-expanding product category as consumers prioritize lower operating temperatures and reduced energy draw. Wood-burning sauna stoves retain structural importance in rural installations and heritage-conscious markets where off-grid operation and traditional löyly experience sustain premium positioning.
EU Ecodesign Directive and REACH compliance requirements shape material selection and thermal efficiency thresholds for products sold across member states, while US electrical safety standards under NEC and UL certification govern market access for imported units. Finland's national building codes and Sweden's Boverket regulations mandate specific clearances and ventilation parameters that directly influence heater form factor and installation type specifications. Stakeholders must monitor evolving carbon-border adjustments and tightening residential energy performance standards that will progressively favor electric and infrared configurations over solid-fuel alternatives.
Market Dynamics
EU Ecodesign Directive tightening on electric heating elements is compressing margins for conventional coil manufacturers while accelerating infrared panel adoption across Nordic residential installations.
Growth Catalysts
- EU Ecodesign efficiency mandates:Residential energy performance standards in Finland and Sweden now favor low-draw infrared configurations, pulling upgrade cycles forward.
- Wellness infrastructure investment:Home sauna installation rates in Minnesota and Michigan are climbing as cold-climate households prioritize thermal therapy spaces.
- Smart control integration:WiFi-enabled heater management systems are penetrating premium residential segments through mobile app connectivity and remote scheduling.
Market Restraints
- Nickel-chromium alloy cost volatility:Resistive coil manufacturers face margin pressure from fluctuating specialty metal feedstock prices.
- Ventilation constraint lock-in:Urban dwellings without chimney access remain structurally blocked from wood-burning stove adoption.
- REACH compliance friction:Ceramic insulation and coating material selection is narrowing as ECHA substance restrictions expand.
Strategic Opportunities
- German underpenetration:Home sauna density in Bavaria and Baden-Württemberg lags Nordic benchmarks by a factor of three.
- Apartment-compatible infrared:Far-infrared panel systems requiring no external venting are unlocking multi-unit dwelling penetration.
- US Inflation Reduction Act residential credits:Energy-efficient home improvement incentives are subsidizing electric heater retrofits in northern states.
Industry Challenges
- UL 875 certification timelines:North American electrical safety testing creates six-to-nine month product launch delays for European manufacturers.
- Legacy control system integration:Smart heater retrofits face compatibility failures with existing cabin thermostat architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domestic Sauna Heaters Market |
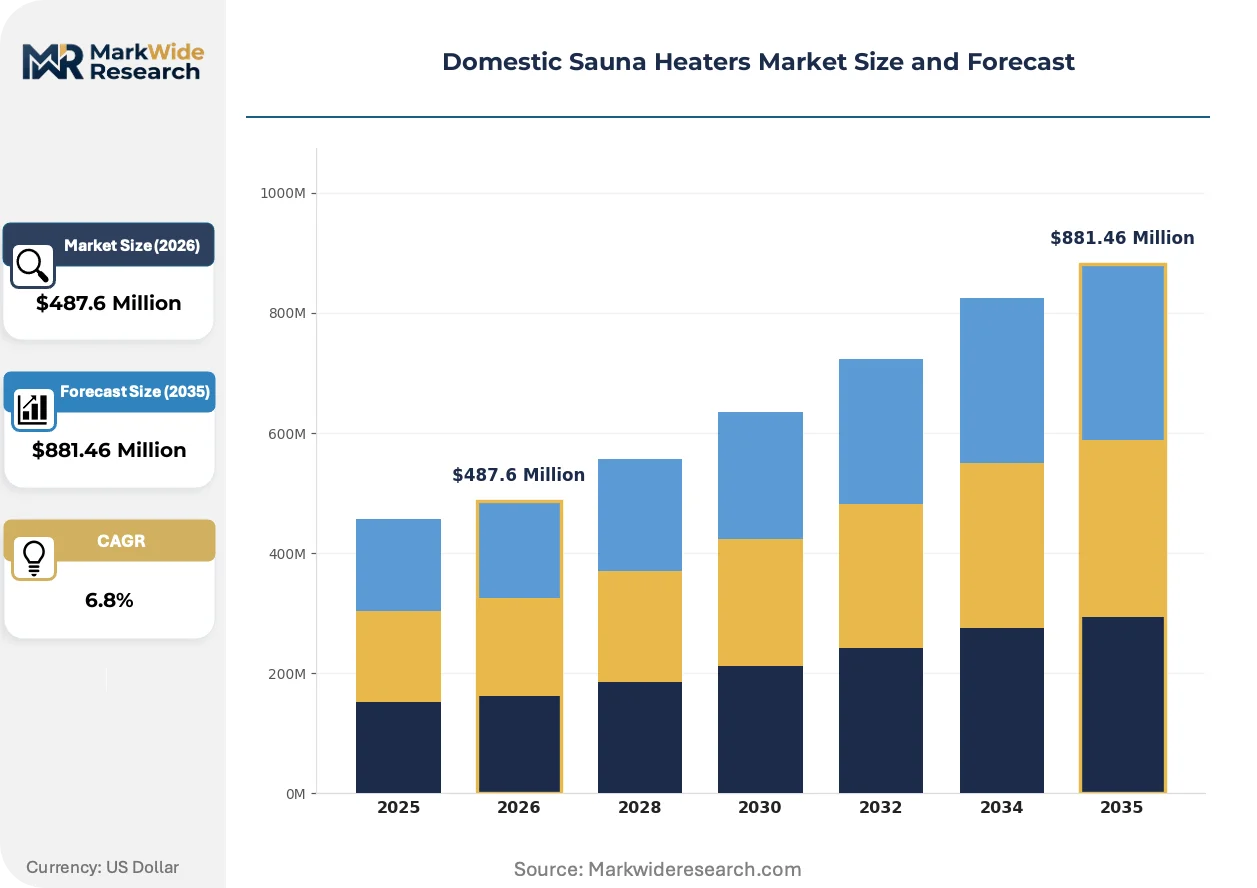
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Sauna Heater, Wood-Burning Sauna Stove, Infrared Sauna Heater, Pellet Stove Fuel Type: Electricity, Wood, Biofuel, Natural Gas Installation Type: Built-in, Portable, Wall-Mounted, Free Standing End User: Residential Users, Spa Facilities, Fitness Centers, Hotels |
| Companies Covered | Harvia, HUUM, Finlandia Sauna, Amerec, Finnleo, Tylo, EOS, SAWO, Helo Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domestic Sauna Heaters Market Trends and Innovations
Product development trajectories in domestic sauna heaters are converging on energy efficiency optimization and connected system architectures, with material science advances enabling thinner, faster-heating elements.
Carbon-ceramic composite heating panels is consolidating market share in residential infrared installations by delivering surface temperatures of 110°C at one-third the energy draw of conventional resistive coils. Urban apartment buyers in Stockholm and Oslo are specifying these panels for balcony-mounted cabin retrofits where electrical load limits are strict. The technology is consolidating supplier margins by eliminating the nickel-chromium supply chain entirely.
REACH Annex XIV substance restrictions are forcing reformulation of ceramic fiber insulation and high-temperature coatings used in electric heater construction. Manufacturers serving EU member states must now source aluminum-silicate alternatives or face market withdrawal. Finnish and Estonian producers with captive materials R&D are securing first-mover certification advantages under the revised ECHA guidelines.
Direct-to-consumer configuration tools are displacing traditional distributor-led specification processes for residential sauna builds. Online platforms now allow homeowners to input cabin dimensions and receive automated heater sizing recommendations with installation kit bundles. This channel shift is most pronounced in Colorado and Montana, where remote property owners prefer self-service procurement over contractor-mediated purchases.
Domestic Sauna Heaters Market Segmentation
Domestic sauna heater purchasing decisions pivot on fuel availability, installation constraints, and thermal experience preferences. Each segmentation axis reveals distinct margin structures and regulatory exposure profiles that shape manufacturer portfolio strategy.
Product Type:
Heating technology determines energy draw, temperature ceiling, and regulatory classification across residential installations.
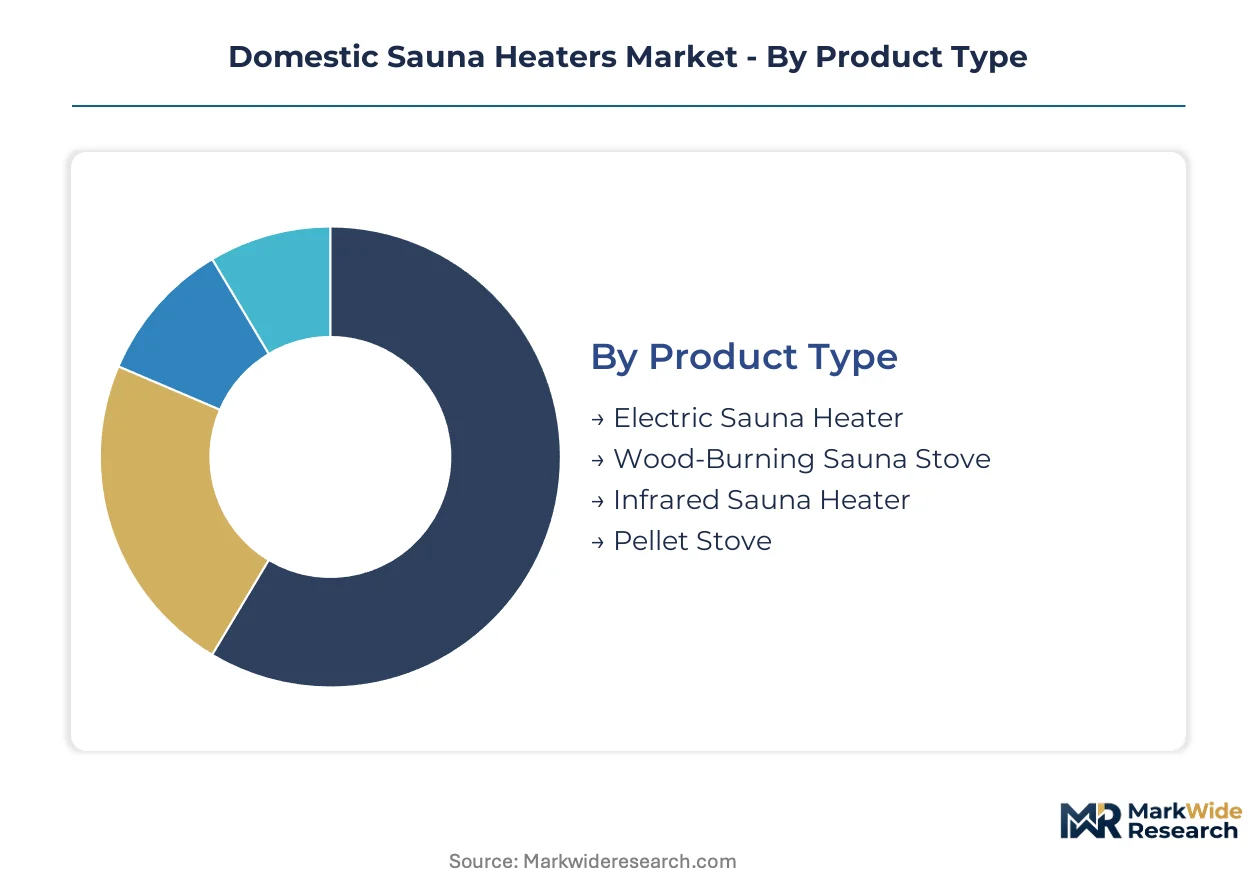
- Electric Sauna Heater:Resistive coil or stone-based systems drawing 6-9 kW for 70-100°C cabin temperatures. Demand concentrates in Finnish and Swedish urban housing where building codes restrict combustion appliances and grid reliability supports continuous draw.
- Infrared Sauna Heater:Carbon-ceramic or far-infrared panels operating at 40-60°C surface temperatures with 30% lower energy consumption than resistive equivalents. Climbing the fastest in Minneapolis and Denver apartment markets where ventilation infrastructure is absent and wellness budgets are expanding.
- Wood-Burning Sauna Stove:Cast iron or steel combustion chambers with stone baskets for löyly generation. Rural lake properties in Finland and Minnesota sustain demand where off-grid operation and traditional sauna ritual retain premium positioning.
- Pellet Stove:Automated biomass feed systems combining combustion intensity with programmable control. Limited penetration outside Austrian and German Alpine regions where pellet distribution networks and carbon-neutral building incentives align.
Mature deployment sits with electric sauna heaters. Newer deployment is concentrated in infrared sauna heaters.
Fuel Type:
Energy source selection locks in operating cost trajectories and carbon intensity profiles for the heater lifecycle.
- Electricity:Grid or renewable-sourced power enabling precise temperature modulation and smart control integration. Finnish households with district heating connections favor this option for operational simplicity and REACH compliance certainty.
- Wood:Cordwood or processed biomass delivering 8-12 hour heat cycles per fuel load. Demand persists in Swedish archipelago cabins and Michigan Upper Peninsula properties where firewood procurement is culturally embedded and grid access is unreliable.
- Biofuel:Pellet, briquette, or processed wood waste formulations with standardized moisture content and automated feed compatibility. German KfW building efficiency programs subsidize these configurations in Baden-Württemberg renovations.
- Natural Gas:Direct-fired combustion with continuous ignition systems. Restricted to North American rural properties with propane infrastructure where electric service upgrades are cost-prohibitive.
Established infrastructure favors electricity. Regulatory pressure and carbon pricing are accelerating biofuel substitution in EU member states.
Installation Type:
Mounting configuration determines spatial requirements, heat distribution patterns, and contractor involvement depth.
- Built-in:Recessed wall or bench-integrated heaters with concealed wiring and controlled airflow. Premium new construction in Oslo and Helsinki specifies these for minimalist cabin aesthetics and optimized stone capacity.
- Portable:Freestanding plug-in units with 2-4 kW draw for temporary or rental installations. Colorado ski vacation properties and Finnish summer cottages deploy these for seasonal flexibility without structural modification.
- Wall-Mounted:Vertical surface attachment with front-facing stone baskets and downward heat projection. Stockholm apartment retrofits favor this format for footprint efficiency and compliance with Boverket clearance mandates.
- Free Standing:Center-floor or corner-positioned units with 360-degree radiation patterns. Traditional Finnish smoke sauna conversions and heritage restorations in Karelia specify these for authentic löyly distribution.
Volume concentration aligns with wall-mounted configurations. Margin expansion is concentrated in built-in systems.
End User:
Customer category dictates specification complexity, service expectation, and procurement channel preference.
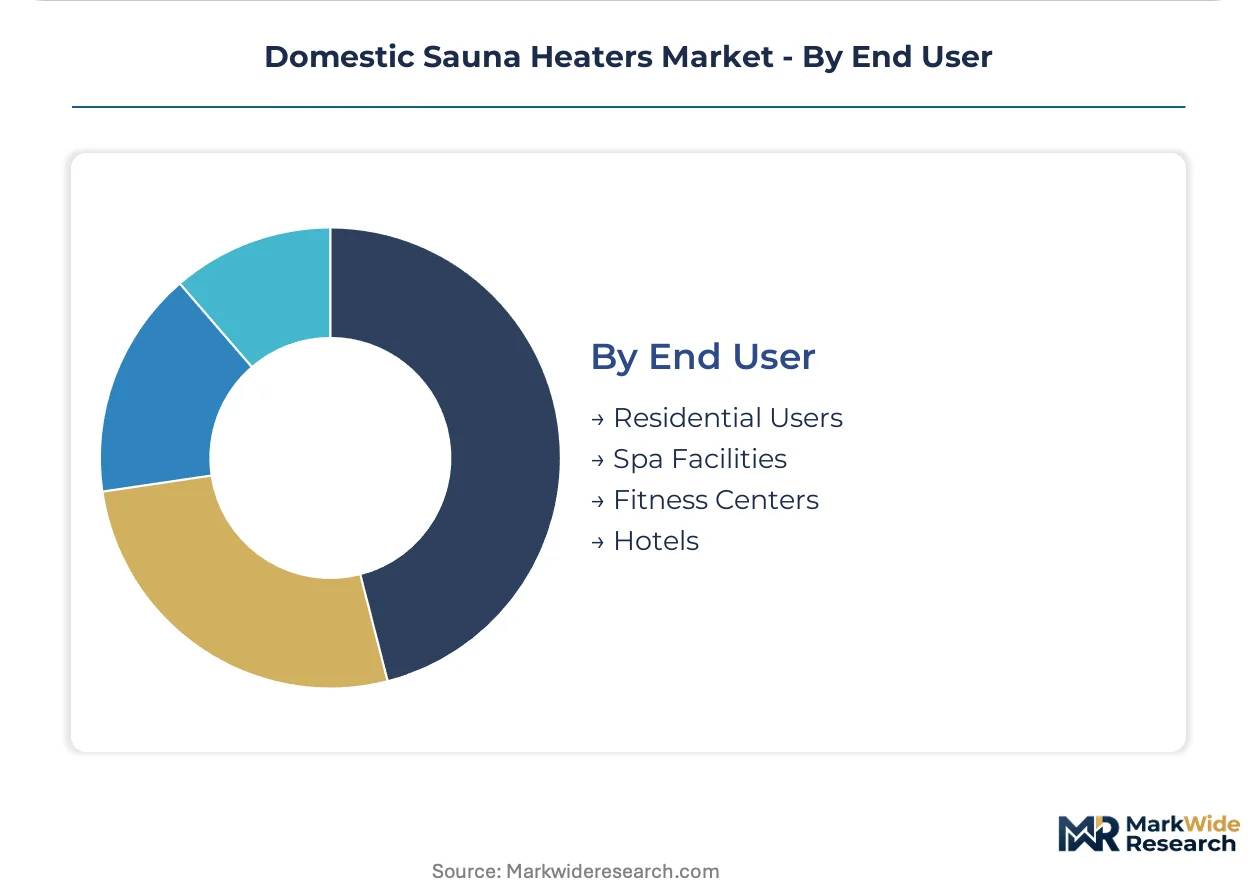
- Residential Users:Single-family homeowners and apartment dwellers purchasing 1-3 units per installation. Finnish and Minnesota households drive specification toward electric and infrared systems with WiFi control integration.
- Spa Facilities:Commercial wellness operators requiring 24/7 duty cycles and redundant heating capacity. Swedish thermal bath complexes in Stockholm and Gothenburg prioritize durability-rated electric heaters with modular element replacement.
- Fitness Centers:Gym chains integrating sauna as amenity for member retention. US operators in Chicago and Boston specify low-maintenance infrared cabins for post-workout recovery zones with minimal staffing overhead.
- Hotels:Hospitality properties balancing guest experience consistency with energy cost management. Alpine resorts in Bavaria and Tyrol deploy hybrid electric-wood systems to satisfy heritage aesthetics and operational reliability requirements.
Unit economics favor residential users by volume. Commercial segments concentrate replacement demand and aftermarket parts revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finland concentrates the highest home sauna installation density worldwide, with per-capita heater demand exceeding all other national markets by substantial margins. Cold-climate wellness culture in Nordic and North American households sustains replacement cycles and premium product uptake. Regulatory pressure on residential energy performance is accelerating technology transitions in established markets.
Finland
Finnish households maintain sauna access rates above 90 percent, driving continuous replacement demand for electric and wood-burning units. The country's national building codes mandate specific heater clearances and ventilation parameters that shape product form factors. Helsinki-based manufacturers leverage captive foundry capacity to control metallurgical quality from raw ingot through finished heating elements.
Sweden
Swedish archipelago cabins and urban apartments sustain dual demand tracks for traditional and infrared configurations. Boverket regulations enforce strict installation clearances that favor wall-mounted heater formats in Stockholm retrofits. Gothenburg thermal bath complexes concentrate commercial-grade electric heater procurement with modular element replacement requirements.
United States
Minnesota and Michigan households are climbing the home sauna installation rankings as cold-climate thermal therapy adoption spreads. The US Inflation Reduction Act residential energy credits are subsidizing electric heater retrofits in northern states. Colorado and Montana remote property owners are shifting toward direct-to-consumer configuration platforms for self-service procurement.
Germany
Home sauna density in Bavaria and Baden-Württemberg lags Nordic benchmarks by a factor of three, creating structural underpenetration opportunity. German KfW building efficiency programs subsidize pellet and biofuel configurations in Alpine renovations. The country's REACH Annex XIV enforcement is forcing ceramic fiber insulation reformulation among suppliers serving EU member states.
Canada
Ontario and Quebec lake properties sustain wood-burning stove demand where off-grid operation and traditional sauna ritual retain premium positioning. Health Canada electrical safety standards create certification timelines that delay European manufacturer market entry. British Columbia wellness infrastructure investment is accelerating infrared panel adoption in Vancouver apartment markets.
Domestic Sauna Heaters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage Nordic producers commanding premium positioning and Asian fabricators capturing volume tiers. The vendor base clusters around three strategic archetypes: vertically integrated metallurgical specialists, smart control technology developers, and regional distribution aggregators. M&A activity concentrates on captive foundry acquisitions and connected system platform rollups. Portfolio diversification into complementary cabin materials and ventilation systems is the second dominant competitive vector.
Within the heritage integrated tier, Harvia and HUUM exemplify contrasting strategic anchors. Harvia represents the captive metallurgy archetype through its Finland-based foundry operations controlling alloy quality from ingot to finished element. HUUM occupies the R&D-intensive position emphasizing smart control system development. Amerec anchors the North American distribution breadth archetype, competing through aftermarket parts availability and regional service density. These three patterns illustrate how geographic origin and structural choices map to defensible market positions.
| Leading Market Players |
|---|
| Harvia |
| HUUM |
| Finlandia Sauna |
| Amerec |
| Finnleo |
| Tylo |
| EOS |
| SAWO |
| Helo Ltd |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign efficiency mandates for electric heating elements are forcing manufacturers to absorb alloy cost volatility while maintaining price accessibility for residential retrofit buyers. This regulatory compression is reshaping sourcing strategies as Finnish and Estonian producers with captive metallurgical capacity gain pricing flexibility against import-dependent competitors.
Pricing Analysis
Volume concentration sits with standard-grade electric coil heaters sold through distributor networks, while margin expansion flows to infrared panel systems with integrated smart controls and REACH-compliant ceramic insulation. Three-tier pricing structure across premium, standard, and economy levels separates WiFi-enabled built-in systems from basic wall-mounted units and portable plug-in alternatives. Cost compression in the standard tier is intensifying because nickel-chromium alloy feedstock prices fluctuate with specialty metal markets. Apartment retrofit buyers in Stockholm and Oslo show highest price sensitivity, while heritage restoration projects in Finnish Karelia accept substantial premiums for authentic löyly experience.
Supply Chain Analysis
Regional distribution centers in Helsinki, Stockholm, and Minneapolis anchor hub-and-spoke patterns that deliver finished heaters to contractor networks and direct-to-consumer platforms within 48-72 hours. Manufacturing concentrates in Finland, Estonia, and China, with Finnish foundries controlling stainless steel element production and Chinese fabricators supplying carbon-ceramic infrared panels. Raw material dependencies center on nickel-chromium alloys for resistive coils, aluminum-silicate ceramic fiber for EU-compliant insulation, and carbon-ceramic composites for infrared surfaces. Single-source vulnerability in specialty alloy supply creates exposure for coil manufacturers without backward integration into metallurgical operations. Distribution runs through HVAC wholesaler networks in North America and dedicated sauna specialist channels in Nordic markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV substance restrictions and EU Ecodesign Directive compliance requirements have erected a cost-of-compliance barrier that favors incumbent producers with dedicated materials R&D and captive certification resources. New entrants face 12-18 month certification timelines and reformulation costs that established players have already amortized.
For Market Incumbents: Lock in metallurgical supply advantages by expanding captive foundry capacity or securing long-term alloy offtake agreements with Nordic suppliers. Carbon-ceramic infrared technology threatens to displace conventional coil manufacturing; incumbents must acquire or develop panel production capability before specialty metal dependencies become stranded assets. Vertical integration into smart control firmware development protects margin erosion from commoditized heating elements. For New Entrants and Emerging Players: WiFi-enabled control systems represent the most penetrable wedge for market entry, as legacy manufacturers lag in software integration and mobile app connectivity. German home sauna density lags Finnish benchmarks by a factor of three, creating white-space opportunity for apartment-compatible infrared systems requiring no external venting. Direct-to-consumer configuration platforms in Colorado and Montana demonstrate viable go-to-market angles that bypass traditional contractor-mediated distribution. For Investors and Strategic Acquirers: The window for entry favors vertically integrated metallurgical specialists with REACH certification already secured and foundry assets in Finland or Estonia. Long-term viability hinges on carbon-border adjustment exposure and progressive tightening of residential energy performance standards that will favor electric and infrared configurations. Watch for EU carbon-border adjustment implementation signals as the inflection indicator that will accelerate biofuel and solid-fuel heater displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Acquisition | Backward integration into stainless steel element production secures alloy quality control against REACH-driven material substitution. |
| Smart Control Platform Development | WiFi-enabled heater management systems with mobile app connectivity command premium positioning in Finnish and Swedish urban markets. |
| Carbon-Ceramic Panel Scale-Up | Infrared technology eliminates nickel-chromium supply chain exposure while meeting EU Ecodesign efficiency mandates. |
| Direct-to-Consumer Channel Launch | Online configuration tools displace distributor-led specification processes in Colorado and Montana remote property markets. |
| German Market Penetration Program | Apartment-compatible infrared systems address structural underpenetration in Bavaria and Baden-Württemberg wellness infrastructure. |
Research Methodology
Document review covered EU Ecodesign Directive implementation guidance, ECHA REACH Annex XIV substance restriction updates, and national building code amendments from Finland and Sweden, complemented by interviews with sauna heater manufacturing executives, HVAC distributor procurement managers, residential contractor networks, and ceramic materials R&D specialists. Secondary validation drew from customs trade data, SEC filings of publicly listed wellness equipment manufacturers, and district heating utility consumption reports. Bottom-up unit shipment estimates triangulated against top-down residential construction permit data and sauna installation rate surveys.
Cross-referencing historical replacement cycle patterns with expert panel input on smart control adoption trajectories informed the projection framework. Segmentation dimensions modeled include heating technology type, fuel source, installation configuration, and end-user category across the analysis window. CAGRs were derived from fitted growth curves applied to verified baseline estimates, with particular sensitivity to Inflation Reduction Act residential credit utilization in northern US states and KfW building efficiency program uptake in German Alpine regions.
Several conditions sit outside the modeled scope, including potential EU carbon-border adjustment rate changes, abrupt nickel-chromium alloy supply disruptions, and unanticipated revisions to UL 875 certification timelines. Forecasts reflect documented assumptions regarding regulatory stability and material cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Blankets Market
Household Items
Enameled Cookware Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Drain Cleaners Market
Household Items
Heated Towel Rail Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
North America Liquid Hand Soap Market
Household Items
Candle Air Fresheners Market
Household Items
Europe Cookware Market
Household Items
Coin-Operated Laundries Market
Household Items
Home Use Air Purifiers Market
Household Items
Desktop Air Purifier Market
Household Items
Latex Mattress Market
Household Items
US Flashlights Market
Household Items
Thermos Bottle Market