
 Replacement Sheets Market | 2026-2036
Replacement Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Replacement Sheets Market Analytics
REACH compliance is shifting the cost-of-entry calculus for European replacement sheet suppliers, forcing reformulation of chemical finishing agents and dye processes. Medline Industries LP leverages its vertically integrated U.S. manufacturing network to sustain cost advantages in bulk hospital contracts. Standard Textile Co., Inc. anchors its position through advanced reusable textile systems that reduce total cost of ownership for acute-care buyers. Elis SA competes across Europe with industrial laundry infrastructure that controls collection-to-delivery cycles.
Replacement sheets are woven or knitted textile products manufactured to specified dimensions for covering mattresses and pillows in healthcare, hospitality, and residential settings, typically constructed from cotton, polyester, or blended fibers with thread counts ranging from 180 to 400 for institutional durability. Their primary purpose is to provide a hygienic, replaceable barrier between sleeper and mattress while withstanding commercial laundering cycles exceeding 150 industrial washes. Cotton-based replacement sheets command the largest revenue share in healthcare channels due to breathability and patient comfort requirements, though polyester blends are gaining ground in long-term care facilities seeking faster drying times and extended replacement intervals. The fitted sheet segment generates premium pricing relative to flat configurations because elasticized construction demands specialized cutting and sewing operations that constrain supplier capacity.
The U.S. Food and Drug Administration classifies certain antimicrobial-treated replacement sheets as medical devices, subjecting manufacturers to quality system regulations that shape product development timelines and documentation burdens. The EU Medical Device Regulation and EPA antimicrobial pesticide registration requirements jointly determine which treated textiles gain market access in their respective jurisdictions. Procurement teams must monitor evolving state-level healthcare textile standards in California and New York, as these frequently prefigure broader national mandates.
Market Dynamics
EU MDR compliance deadlines are compressing supplier margins as healthcare buyers demand documented barrier-performance data across every production batch, forcing mid-tier manufacturers to either absorb certification costs or exit hospital contracts.
Growth Catalysts
- REACH chemical reformulation mandates:European suppliers investing in compliant dye processes are capturing contracts from competitors unable to meet ECHA substance restrictions, consolidating share among certified producers.
- Centralized laundry infrastructure:Hospital systems in the United States are consolidating vendor relationships around suppliers with captive industrial washing capacity, reducing procurement complexity.
- Antimicrobial textile classification:EPA pesticide registration requirements for treated sheets are creating a two-tier market where compliant products access acute-care channels.
Market Restraints
- Cotton price volatility:Egyptian and Pima cotton premiums fluctuate with Nile Basin water allocation disputes, squeezing margin on breathable healthcare-grade products.
- Supplier concentration in South Carolina:Three integrated weaving-laundering operations control bulk hospital contract fulfillment capacity, creating single-source vulnerability for national distributors.
- Polyester microfiber shedding limits:California's proposed textile microplastic standards threaten blended-fiber sheet acceptance in state-funded facilities.
Strategic Opportunities
- Long-term care automation:Robotic bed-changing systems in Japanese eldercare facilities create demand for precisely dimensioned, high-tensile-strength fitted sheets.
- EU Green Deal procurement rules:Public hospital tenders awarding points for circular-economy compliance favor suppliers with take-back and fiber-recovery programs.
- RFID-embedded inventory tracking:Convergence of textile RFID tags with hospital asset-management platforms enables usage-based billing models.
Industry Challenges
- Industrial sewing technician shortages:Elasticized fitted-sheet production requires specialized operators that vocational programs in the US Midwest no longer graduate at replacement rates.
- FDA 510(k) documentation timelines:Antimicrobial sheet reclassifications as medical devices extend product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Replacement Sheets Market |
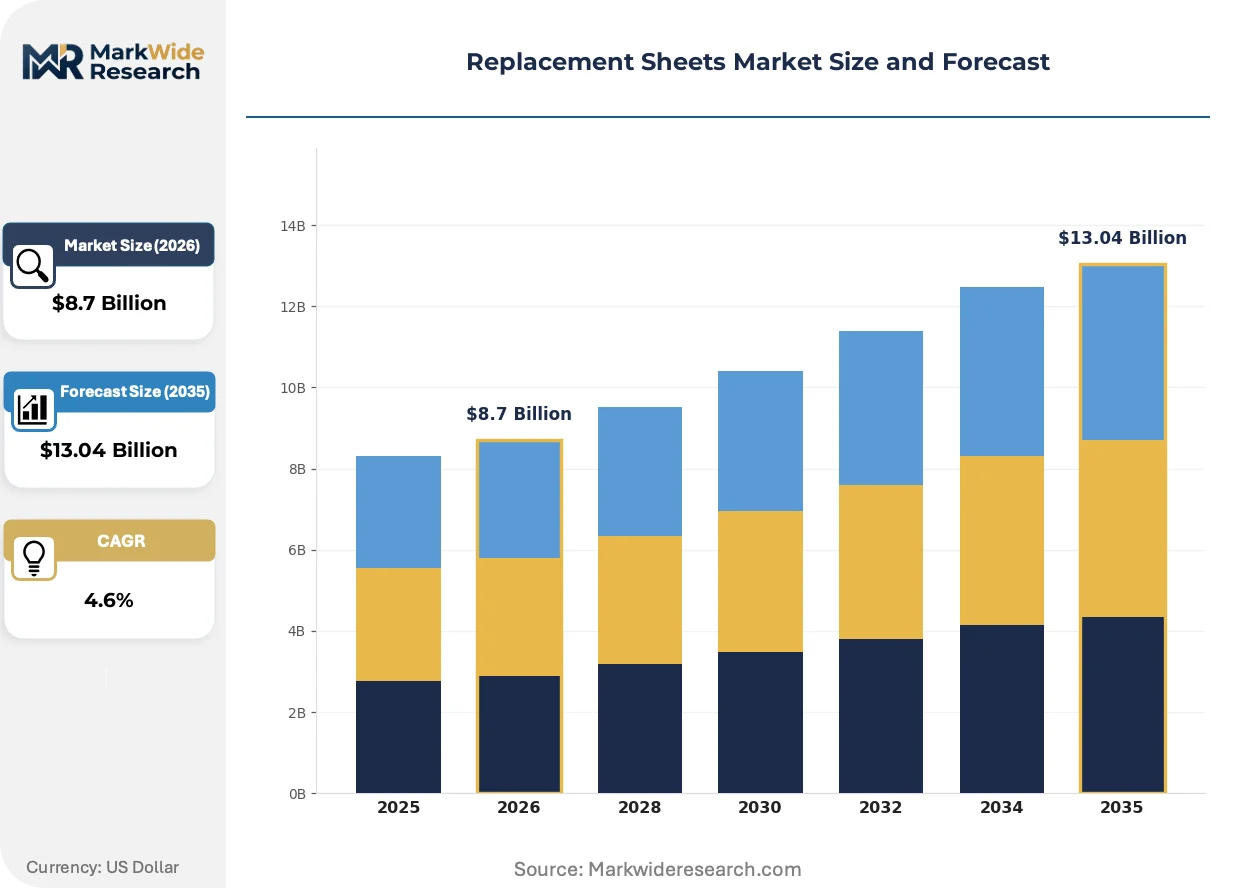
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Sheets, Fitted Sheets, Pillow Cases, Mattress Protectors Material: Cotton, Polyester, Linen, Bamboo Size: Single, Double, Queen, King Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Medline Industries LP, Standard Textile Co., Inc., Elis SA, Aramark Uniform Services, Tietex International Ltd., HoverTech International, EHOB Inc., Vendlet ApS, Arjo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Replacement Sheets Market Evolving Landscape
Replacement sheet manufacturing is bifurcating between premium reusable systems engineered for 200-plus wash cycles and disposable alternatives targeting isolation-room protocols, with technology choices increasingly dictated by total-cost-of-ownership modeling rather than upfront unit pricing.
Silver-ion and copper-infused fiber treatments are overtaking quaternary ammonium surface coatings as the preferred antimicrobial approach in acute-care settings. Hospital infection-control committees are specifying ionic fiber integration for ICU and oncology units, citing durability through thermal laundering. This transition is compressing demand for topical chemical finishes that degrade below therapeutic thresholds after 75-100 industrial washes.
EU Medical Device Regulation technical documentation requirements are reshaping supplier-customer relationships across European hospital systems. Manufacturers must now maintain post-market surveillance systems and risk-management files for barrier-performance claims, elevating compliance costs that favor larger integrated producers. German and French procurement consortiums are consolidating vendor lists to suppliers with notified-body certification, reducing qualified bidders by 40-60 percent in recent tenders.
Buying committees are consolidating linen procurement into multi-year enterprise agreements that bundle sheets, gowns, and surgical textiles under single-source contracts. Group purchasing organizations are displacing individual facility purchasing managers, centralizing specification authority at regional health-system headquarters. This concentration is most visible in the United States, where Catholic health networks and for-profit chains now negotiate three-to-five-year agreements covering 200-plus facilities.
Replacement Sheets Market Segmentation
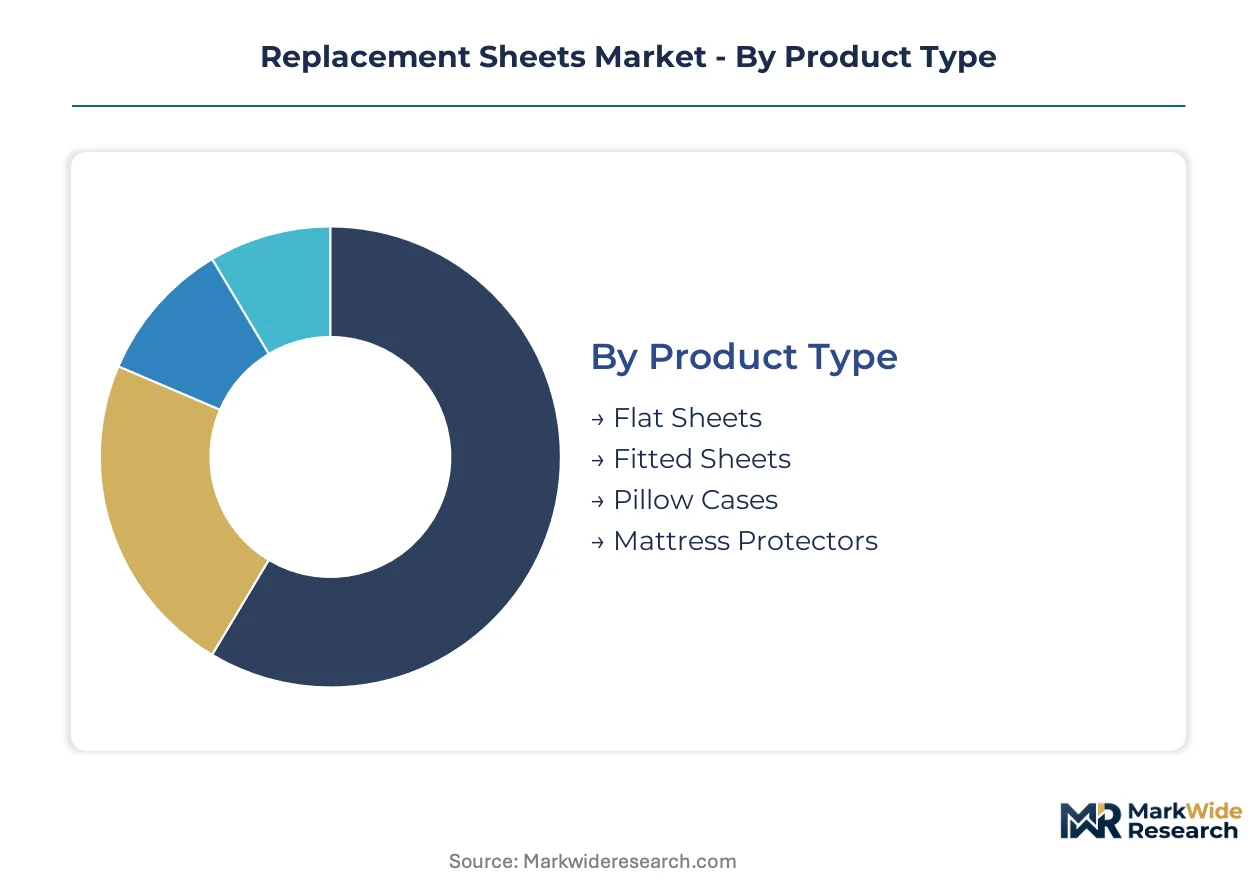
Replacement sheet procurement operates across distinct technical and commercial dimensions that determine durability specifications, laundering protocols, and total cost of ownership for institutional buyers. Segmentation reveals where premium engineering commands price premiums versus where commodity sourcing dominates purchasing decisions.
Product Type:
Standardization decreases and customization complexity increases across this spectrum, with elasticized constructions demanding specialized manufacturing capabilities that constrain supplier capacity.
- Fitted Sheets:Elasticized hems and corner pockets require precision cutting and industrial sewing operations that extend production cycles. Hospital systems in the United States pay premium contract rates for fitted configurations that withstand automated bed-changing equipment and thermal disinfection protocols.
- Flat Sheets:Rectangular constructions without elastic components allow faster throughput on automated cutting tables and simpler inventory management. Long-term care facilities across Europe favor flat sheets for manual bed-making workflows where staff training costs outweigh fitted-sheet convenience benefits.
- Pillow Cases:Envelope or tuck-flap closures vary by institutional laundering equipment compatibility.
- Mattress Protectors:Waterproof barrier laminates and zippered encasements serve isolation-room protocols in acute-care settings.
Leading the category by volume: Flat Sheets. Growing fastest: Fitted Sheets.
Material:
Cost tiers stratify sharply across fiber choices, with natural fibers commanding healthcare premiums and synthetics capturing operational efficiency-focused buyers.
- Cotton:Long-staple Egyptian and Pima varieties deliver breathability and patient comfort that ICU and oncology units specify in purchasing contracts. REACH-compliant dye processes for European hospital tenders have elevated processing costs for cotton-based products, consolidating procurement around certified suppliers with ECHA-registered chemical formulations.
- Polyester:Microfiber constructions dry faster and maintain dimensional stability through industrial laundering cycles exceeding 150 washes. Japanese eldercare robotics manufacturers specify high-tensile polyester blends for automated bed-changing systems that stress-test fabric strength.
- Linen:Flax-based fibers offer natural antimicrobial properties and superior moisture wicking for premium hospitality channels.
- Bamboo:Cellulose-derived rayon alternatives target sustainability-positioned procurement tenders with biodegradable fiber claims.
Cotton dominates healthcare procurement by revenue. Polyester blends are expanding most quickly in long-term care automation applications.
Size:
Volume concentration tracks bed frame standardization, with institutional specifications narrowing the effective SKU range despite nominal variety.
- Single:Standard dimensions serve pediatric wards, psychiatric facilities, and military barracks where individual bed frames predominate. German hospital procurement consortiums specify single-width fitted sheets for standardized ward configurations that optimize linen cart logistics.
- Double:Wider configurations accommodate bariatric patients and companion-bed arrangements in North American acute-care settings.
- Queen:Hospitality and residential channels drive demand outside institutional healthcare.
- King:Premium hospitality suites and luxury residential markets represent niche volume.
Single sizes lead institutional procurement by unit volume. Double sizes are gaining share fastest in bariatric care applications.
Distribution Channel:
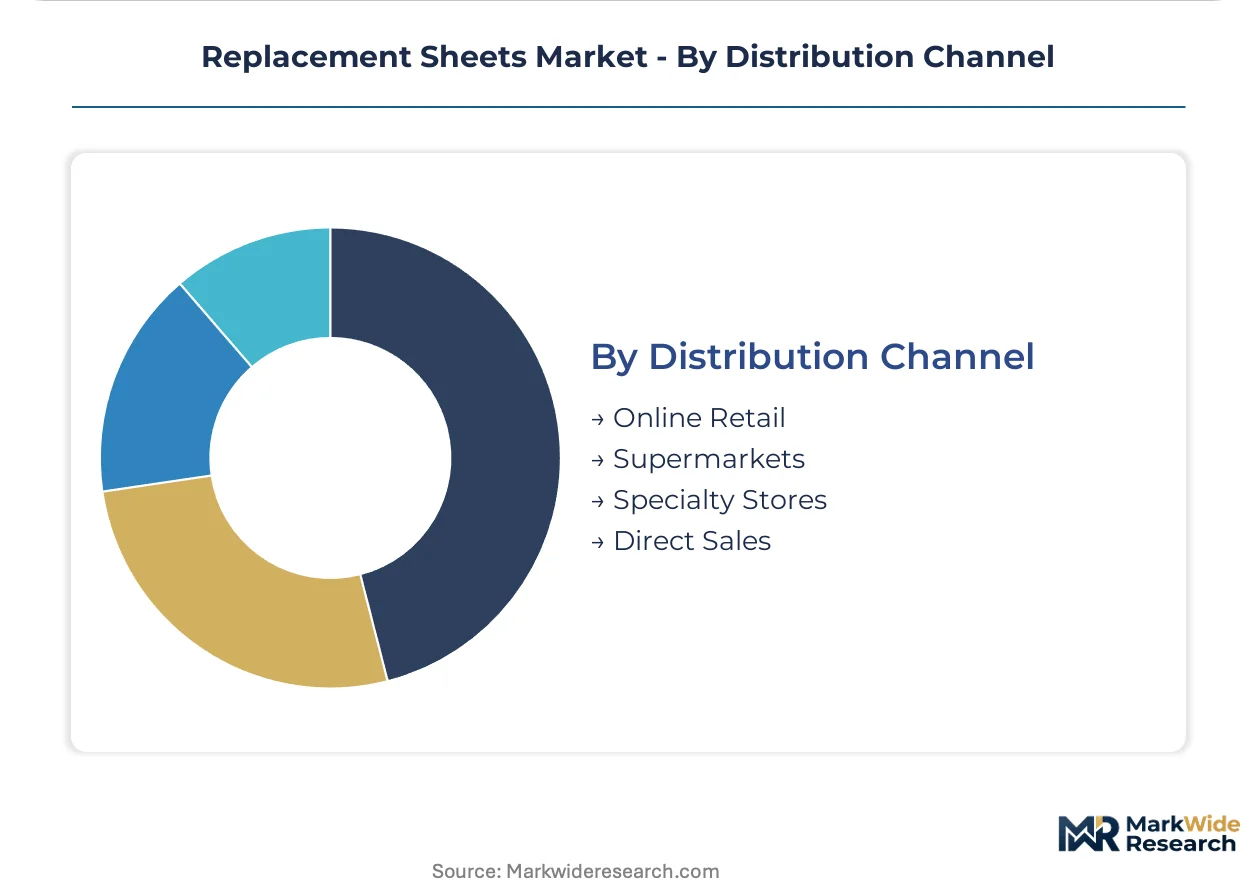
Customer type and order scale determine channel economics, with enterprise contracts displacing fragmented purchasing across healthcare systems.
- Direct Sales:National hospital systems negotiate multi-year enterprise agreements covering 200-plus facilities through dedicated account teams. Catholic health networks and for-profit chains in the United States consolidate specification authority at regional headquarters, bypassing traditional distribution intermediaries.
- Online Retail:E-commerce platforms serve smaller long-term care facilities and residential buyers with fragmented reorder patterns. California-based group purchasing organizations have developed digital procurement portals that aggregate demand from independent nursing homes.
- Supermarkets:Mass retail channels capture residential replacement demand with limited institutional penetration.
- Specialty Stores:Medical supply distributors serve outpatient clinics and home healthcare agencies with smaller order quantities.
Direct sales channels capture the largest contract value. Online retail platforms are climbing the fastest as mid-sized facilities digitize procurement workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States generate the largest contract value for replacement sheets, while European procurement consortiums drive regulatory compliance premiums. Demand concentrates where centralized laundry infrastructure and infection-control mandates intersect.
United States
Catholic health networks and for-profit chains negotiate enterprise agreements covering 200-plus facilities, consolidating specification authority at regional headquarters. FDA quality system regulations shape antimicrobial sheet development timelines for acute-care channels. South Carolina hosts three integrated weaving-laundering operations that control bulk hospital contract fulfillment capacity.
Germany
Hospital procurement consortiums specify single-width fitted sheets for standardized ward configurations that optimize linen cart logistics. EU Medical Device Regulation technical documentation requirements reduce qualified bidders by 40-60 percent in recent tenders. The Rhine-Ruhr industrial corridor anchors production of REACH-compliant dye processes for European hospital tenders.
France
Public hospital tenders awarding points for circular-economy compliance favor suppliers with take-back and fiber-recovery programs. ANSM and CNIL oversight intersect with EU MDR compliance for barrier-performance claims. The Lyon textile cluster concentrates industrial laundry infrastructure that controls collection-to-delivery cycles.
Japan
Robotic bed-changing systems in eldercare facilities create demand for precisely dimensioned, high-tensile-strength fitted sheets. METI industrial standards govern textile performance specifications for automated healthcare equipment. The Nagoya-Chubu region houses manufacturers specifying high-tensile polyester blends for stress-tested fabric strength.
United Kingdom
NHS procurement frameworks consolidate vendor relationships around suppliers with captive industrial washing capacity, reducing procurement complexity. MHRA alignment with EU MDR post-Brexit maintains barrier-performance documentation requirements. The Midlands textile manufacturing belt retains specialized industrial sewing capacity for elasticized fitted-sheet production.
Replacement Sheets Market Competitive Landscape
United States producers anchor one tier; European specialists hold compliance-driven positions. The vendor base separates into integrated manufacturing-laundry operators, regional textile converters, and antimicrobial technology licensors. Three strategic archetypes dominate: vertically integrated hospital contractors, industrial laundry service providers with captive textile supply, and premium reusable system engineers. Consolidation proceeds through multi-year enterprise agreements and notified-body certification barriers.
Within the integrated manufacturing tier, Medline Industries LP and Standard Textile Co., Inc. represent North American scale positions. Elis SA exemplifies the European industrial laundry infrastructure archetype. These three occupy positions where compliance documentation and captive capacity determine contract access.
| Leading Market Players |
|---|
| Medline Industries LP |
| Standard Textile Co., Inc. |
| Elis SA |
| Aramark Uniform Services |
| Tietex International Ltd. |
| HoverTech International |
| EHOB Inc. |
| Vendlet ApS |
| Arjo |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement rules gate both qualified supply and premium-tier pricing access, as public hospital tenders award circular-economy compliance points that disqualify suppliers lacking take-back infrastructure while commanding contract premiums for certified fiber-recovery programs. This sustainability mandate bifurcates the supplier base into certified premium-tier operators and price-competitive commodity producers excluded from institutional channels.
Pricing Analysis
Lead-time-driven pricing angles dominate contract negotiations, with hospital systems paying premiums for guaranteed 48-hour replenishment cycles while spot inventory clears at discounted rates through secondary distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and captive laundry capacity, with EU MDR-notified-body documentation commanding the top tier. Pricing pressure stems from REACH-compliant dye process investments that compress mid-tier margins. Long-term care facilities exhibit highest price sensitivity due to Medicaid reimbursement constraints, while acute-care systems prioritize barrier-performance guarantees over unit cost.
Supply Chain Analysis
Reverse-logistics flows for textile recovery and fiber regeneration are becoming cost centers rather than afterthoughts, as EU Green Deal compliance mandates documented collection-to-delivery cycles with take-back obligations. Manufacturing concentrates in the United States, Germany, and China, with South Carolina hosting three integrated weaving-laundering operations that anchor North American hospital contract fulfillment. Raw material dependencies center on Egyptian and Pima cotton, high-tenacity polyester filament, and silver-ion antimicrobial additives. Single-source vulnerability in South Carolina creates systemic risk for national distributors. Distribution runs through group purchasing organizations that have displaced individual facility purchasing managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play, as EU MDR compliance deadlines and REACH chemical reformulation mandates force mid-tier manufacturers to absorb certification costs or exit hospital contracts entirely.
For Market Incumbents: Anticipate regulatory escalation by securing notified-body certification ahead of EU MDR enforcement waves, while acquiring industrial sewing capacity in the US Midwest to address technician shortages threatening fitted-sheet production. Backward integration into REACH-compliant dye processes protects margin from ECHA substance restriction volatility. Channel control through captive laundry infrastructure locks in multi-year enterprise agreements with Catholic health networks. For New Entrants and Emerging Players: Launch via digital procurement portals targeting independent nursing homes in California and fragmented long-term care facilities across Southern Europe, segments underserved by consolidated GPO contracts. Japanese eldercare robotics integration represents the most penetrable white-space, with METI standards creating entry barriers that favor specialized high-tensile polyester engineering. White-label antimicrobial fiber treatment partnerships accelerate time-to-revenue without FDA 510(k) documentation burdens. For Investors and Strategic Acquirers: Consolidation of German hospital procurement consortium vendor lists by 40-60 percent is the leading indicator that notified-body certification scarcity will drive acquisition premiums for qualified European suppliers. The 5-10 year viability window favors industrial laundry service providers with captive textile supply and documented circular-economy compliance. Monitor California textile microplastic regulatory advancement as an inflection signal for polyester blend demand destruction in state-funded facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Notified-Body Certification Investment | EU MDR technical documentation requirements reduce qualified bidders by 40-60 percent in German and French tenders. |
| Captive Industrial Laundry Expansion | South Carolina's three integrated weaving-laundering operations control bulk hospital contract fulfillment capacity. |
| RFID-Embedded Inventory Tracking Integration | Convergence with hospital asset-management platforms enables usage-based billing models for enterprise agreements. |
| Silver-Ion Fiber Treatment Transition | Hospital infection-control committees specify ionic fiber integration for ICU durability through thermal laundering cycles. |
| EU Green Deal Take-Back Program Launch | Public hospital tenders award points for circular-economy compliance favoring fiber-recovery infrastructure. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and ECHA substance restriction registries underwrites the qualitative findings presented in this study. Primary interviews with hospital purchasing committee chairs, biomedical engineers, industrial laundry operations directors, and textile finishing chemists were combined with secondary validation from FDA 510(k) filings, EU MDR notified-body certification records, and CMS Medicare cost report data. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against healthcare textile expenditure flows anchored the market sizing framework.
Comparable-period anchoring to historical replacement cycle data and hospital bed inventory growth established the forecast baseline across the projection horizon. Segmentation dimensions modeled include product type, material composition, size specification, and distribution channel, with additional granularity on infection-control tier and automation compatibility. CAGRs were derived from regression analysis of procurement contract value trends and linen replacement program expansion rates. Industry-specific inputs incorporated REACH compliance cost pass-through elasticities and RFID adoption curves in hospital asset management.
Cotton price volatility from Nile Basin water allocation disputes, EU MDR enforcement timeline acceleration, and California microplastic regulatory advancement are the dominant revision risks to the forecast framework. Practitioners should monitor ECHA substance restriction list updates, German procurement consortium tender participation thresholds, and Japanese eldercare robotics deployment rates for early signals of demand trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Europe Cookware Market
Household Items
Smart Memory Foam Market
Household Items
Air Purifier Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Silicone Soap Mold Market
Household Items
Shower Caddies Market
Household Items
Water Purifier Market
Household Items
Shower Heads and Systems Market
Household Items
Remote Control Holder Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Acrylic Aquarium Market
Household Items
Facial Tissue Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Insulated Water Bottles Market
Household Items
Electric Shoe Dryer Market
Household Items
Industrial Floor Mats Market