
 Portable Iron Market | 2026-2036
Portable Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Iron Market Analysis
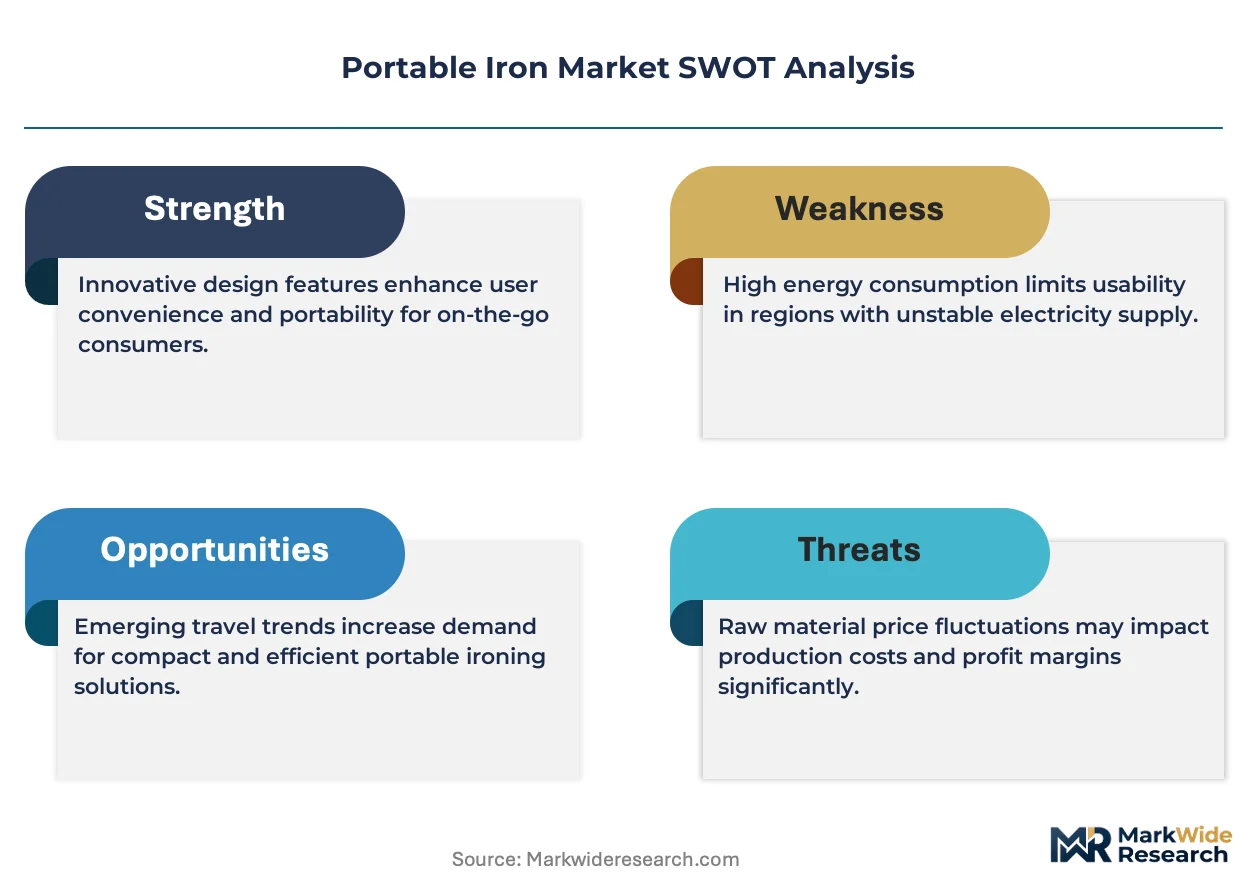
Asset-light leasing models for commercial laundry equipment is narrowing the capital barrier for mid-size hotels and salon chains seeking professional-grade pressing capability. Rowenta leverages its European manufacturing footprint to sustain premium positioning in ceramic-plate technology. Philips competes through broad retail distribution across multiple voltage standards. Sunbeam anchors the North American mass-market channel with standardized compact formats.
Portable irons are handheld electrical appliances that apply heated metal plates, typically reaching temperatures between 120°C and 220°C depending on fabric setting, to remove wrinkles from textiles through thermal conduction and optional steam injection. Their primary commercial purpose spans household garment care, hospitality guest services, and light industrial pressing where full-scale equipment proves impractical. Steam iron configurations command the largest revenue share due to consumer preference for dual-function moisture and heat delivery, while travel iron formats represent the fastest-expanding segment as remote work patterns extend business travel durations. Ceramic plate technology dominates the premium tier with even heat distribution, whereas stainless steel variants occupy the value-oriented commercial segment.
FDA oversight of electrical appliance safety standards in the United States combines with EU REACH compliance governing non-stick coating chemistries to shape product material selection and market access requirements. Ecodesign regulations progressively mandate standby power limits and recyclability thresholds that manufacturers must integrate into new platform development. Stakeholders should monitor evolving coating material restrictions and voltage standard harmonization as determinants of which product architectures achieve cross-border scale.
Market Dynamics
The EU Ecodesign Directive's tightening standby power limits and recyclability mandates are compressing product development cycles while forcing manufacturers to redesign thermal management systems and material sourcing strategies.
Growth Catalysts
- Commercial hospitality procurement:Mid-size hotel chains are expanding guest room amenity budgets to include compact steam units as competitive differentiation intensifies.
- REACH compliance maturation:Established coating chemistries under EU REACH are now clearing multi-year registration phases, reducing regulatory uncertainty for ceramic-plate suppliers.
- Remote work normalization:Extended business travel durations are elevating demand for dual-voltage travel formats across professional services sectors.
Market Restraints
- Copper and aluminum input volatility:Heating element raw materials face price instability from energy-intensive smelting operations concentrated in China.
- Single-source ceramic substrate dependency:Premium plate manufacturing clusters in Germany and Japan create geographic concentration risk for tier-one suppliers.
- Non-stick coating regulatory friction:PFAS restrictions under evolving EU and US state-level frameworks are forcing reformulation of legacy surface treatments.
Strategic Opportunities
- India BIS certification pathway:Formal adoption of IEC 60335-2-3 safety standards is opening organized retail channels for compliant imported brands.
- Salon and spa service integration:On-demand pressing as an add-on service creates new B2B volume for commercial-grade portable units.
- Asset-light leasing models:Equipment-as-a-service platforms are narrowing capital barriers for independent hospitality operators seeking professional-grade capability.
Industry Challenges
- Cross-voltage engineering complexity:Dual-voltage architectures require redundant safety certifications across 110-120V and 220-240V markets, extending time-to-revenue.
- Recyclability design integration:Meeting EU WEEE directive material recovery thresholds demands redesign of heating element housings and cord assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Iron Market |
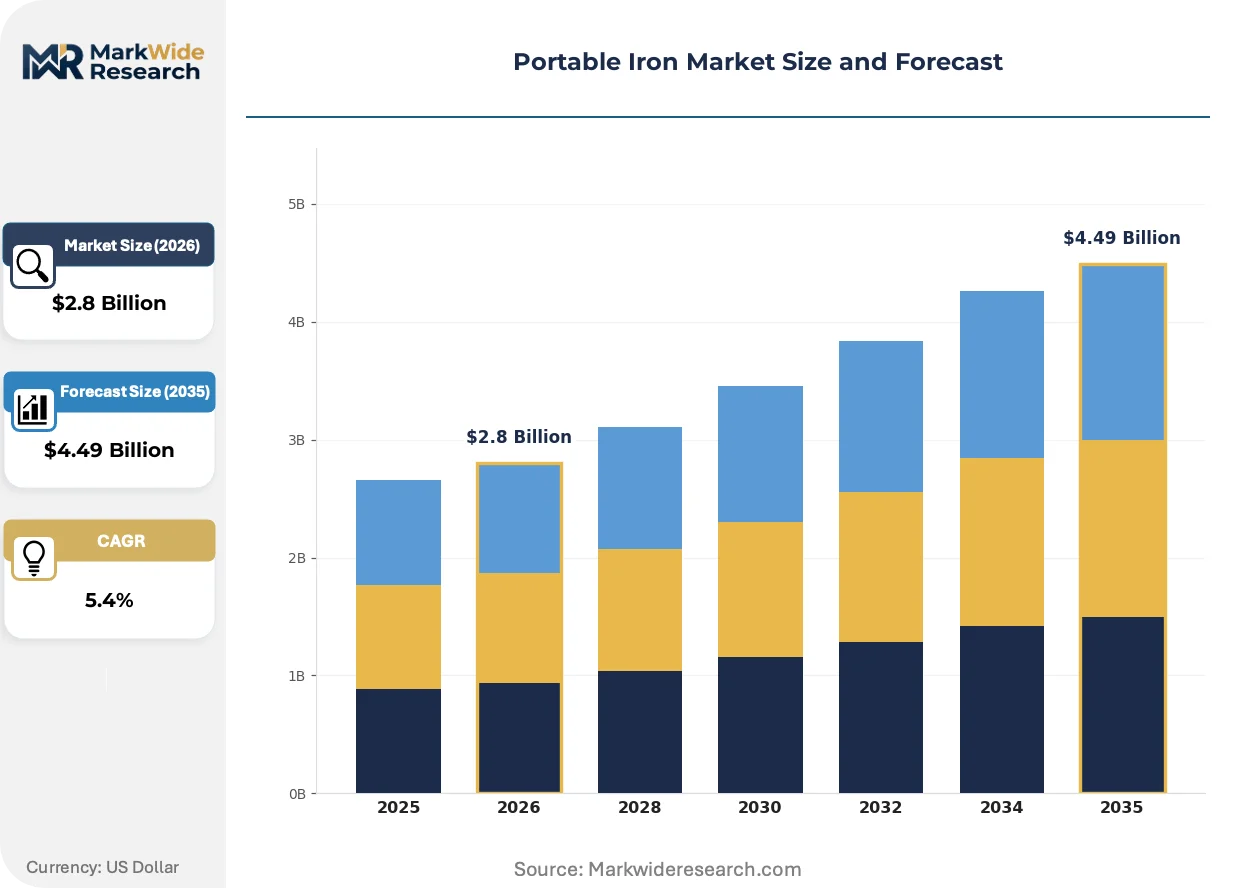
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Iron, Dry Iron, Cordless Iron, Travel Iron End User: Household, Hotels, Salons, Apparel Manufacturers Technology: Ceramic Plate, Stainless Steel Plate, Non-Stick Coated, Flexible Heat Size: Compact, Standard, Mini, Heavy Duty |
| Companies Covered | Rowenta, Braun, Philips, Sunbeam, Conair, Panasonic, Black+Decker, Electrolux, Tefal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Iron Market Emerging Trajectories
Ceramic heating technology, regulatory material restrictions, and procurement model experimentation are converging to reshape competitive positioning across price tiers and distribution channels.
Ceramic-coated aluminum plates are migrating from premium household segments into mid-tier commercial hospitality procurement. German and Japanese manufacturing facilities are scaling output to meet batch consistency requirements from hotel chain technical specifications. The technology is migrating from artisan garment care into standardized amenity programs, compressing margin structures for legacy stainless steel suppliers.
The EU Ecodesign Directive's standby power limits are forcing redesign of control circuitry and thermal cutoff systems. Manufacturers must integrate sub-1W idle consumption thresholds while maintaining rapid heat-up performance. Small appliance specialists in Italy and Spain are most affected, accelerating partnerships with semiconductor firms for smart power management modules.
Extended-stay hospitality formats are unbundling in-room pressing from traditional laundry services. Hotel operators in Germany and the Netherlands are piloting deposit-based portable iron lending programs, displacing fixed in-room inventory. Procurement teams are negotiating direct manufacturer relationships, bypassing traditional hospitality supply distributors.
Portable Iron Market Segmentation
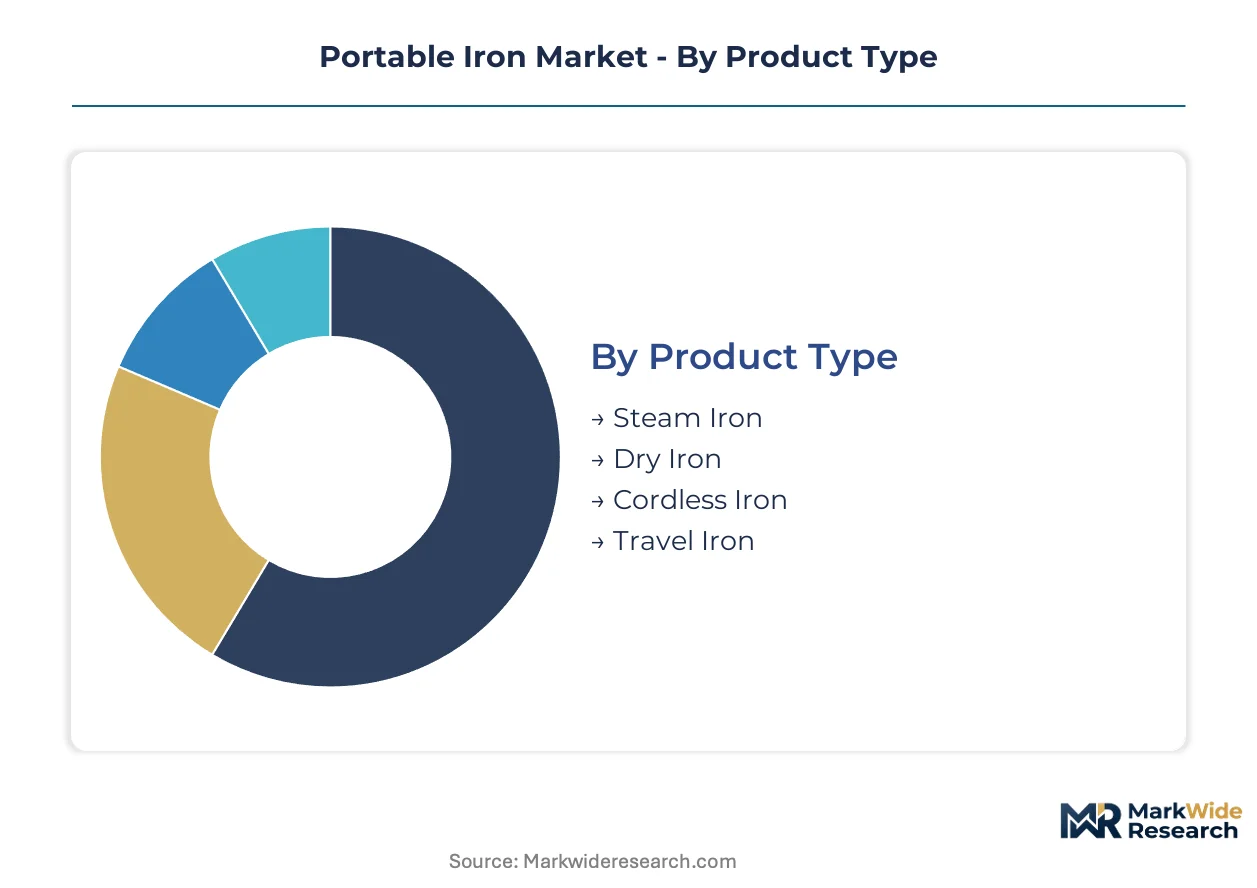
Portable iron segmentation reveals divergent service intensity across product architectures. Ceramic-plate units in hospitality settings demand rapid replacement parts availability, while travel formats prioritize warranty logistics over repair networks.
Product Type:
After-sales-service intensity varies sharply by heating architecture and water system complexity.
- Steam Iron:Dual-function units combine resistive heating elements with pressurized water reservoirs, requiring descaling protocols and seal replacement schedules. Demand concentrates in mid-size hotel chains across Germany and the Netherlands, where guest room amenity differentiation drives procurement of units with rapid heat-up capability.
- Travel Iron:Dual-voltage architectures with collapsible handles and compact reservoirs target extended-stay business travelers. These formats are expanding most quickly across professional services sectors as remote work patterns lengthen average trip durations.
- Dry Iron:Simpler thermal management without water systems reduces service call frequency for basic garment care.
- Cordless Iron:Battery-integrated designs introduce charging base reliability as a new failure mode for household segments.
By volume, Steam Iron leads. By growth pace, Travel Iron is ahead.
End User:
Cost tier stratification separates capital-intensive commercial procurement from price-sensitive household replacement cycles.
- Household:Individual consumers prioritize purchase price over lifecycle cost, driving volume through mass retail channels with standardized warranty terms.
- Hotels:Procurement teams negotiate direct manufacturer relationships for compact steam units, bypassing traditional hospitality distributors as extended-stay formats unbundle in-room pressing from laundry services.
- Salons:Commercial-grade portable units support on-demand pressing as an add-on service, creating B2B volume for equipment-as-a-service platforms.
- Apparel Manufacturers:Light industrial pressing where full-scale equipment proves impractical demands heavy-duty formats with rapid heat recovery.
By installed base, Household dominates. By procurement value per unit, Hotels command premium positioning.
Technology:
Margin structures diverge between premium ceramic substrates and value-oriented metallic plates.
- Ceramic Plate:Aluminum substrates with ceramic coatings deliver even heat distribution through semiconductor-controlled thermal management. German and Japanese manufacturing facilities scale output to meet batch consistency requirements from hotel chain technical specifications.
- Non-Stick Coated:Legacy PTFE-based surface treatments face reformulation pressure under evolving EU and US state-level PFAS restrictions, forcing material transitions during product platform refreshes.
- Stainless Steel Plate:Value-oriented commercial segments occupy this tier with simpler thermal conductivity and lower unit manufacturing cost.
- Flexible Heat:Emerging polymer-based heating elements enable novel form factors with reduced thermal mass.
By revenue concentration, Ceramic Plate sits at the top. By technology transition velocity, Non-Stick Coated faces the steepest regulatory pressure.
Size:
Supply concentration in German and Japanese ceramic substrate production shapes availability across dimensional categories.
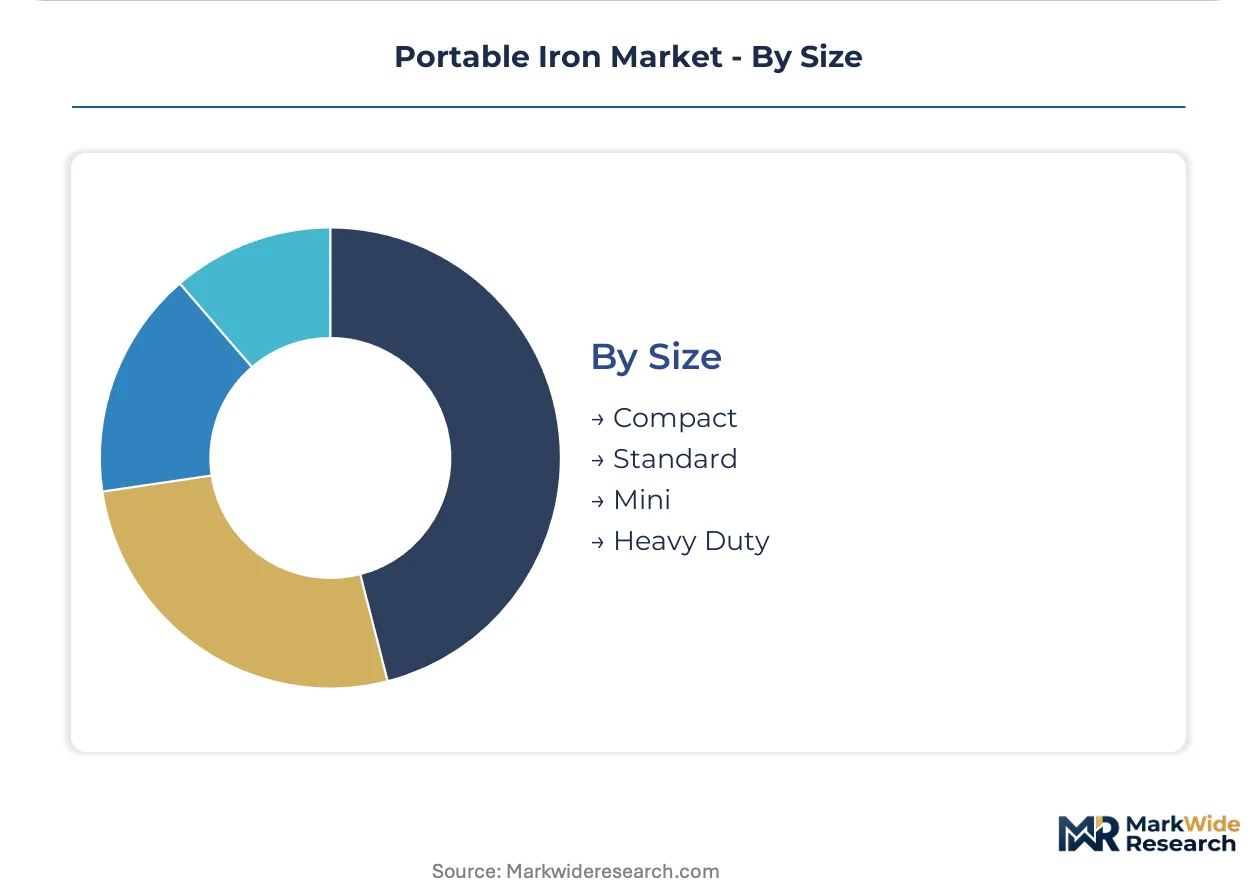
- Compact:Mid-tier formats balance portability with pressing surface area, migrating from artisan garment care into standardized hotel amenity programs.
- Standard:Full-size residential units dominate replacement demand through broad retail distribution.
- Mini:Ultra-portable formats for occasional travelers sacrifice pressing efficiency for packability.
- Heavy Duty:Extended pressing surfaces and enhanced thermal mass target salon and light industrial applications with continuous-use requirements.
By shipment volume, Standard leads. By procurement momentum in commercial channels, Compact is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in portable irons tilt toward manufacturing concentration in Germany and Japan against consumption gravity in the United States and China. Trade balances reflect ceramic substrate specialization versus mass-market assembly cost structures.
Germany
Premium appliance retail channels sustain procurement of ceramic-plate steam units for hospitality and household segments. The EU Ecodesign Directive enforces standby power limits below 1W and recyclability mandates under WEEE. Manufacturing clusters in Baden-Württemberg and North Rhine-Westphalia scale output to meet batch consistency requirements from hotel chain technical specifications.
United States
Mass-market distribution through big-box retail drives volume for compact and travel formats among extended-stay business travelers. FDA oversight of electrical appliance safety standards combines with state-level PFAS restrictions on non-stick coatings. Distribution gravity concentrates in the Midwest logistics corridor and California consumer electronics channels.
China
Domestic assembly capacity serves both export markets and rising middle-class household replacement cycles. GB standards under SAMR govern electrical safety and energy efficiency labeling for small appliances. Manufacturing concentrates in the Pearl River Delta and Yangtze River Delta with upstream dependency on imported ceramic substrates from Germany and Japan.
Japan
Precision ceramic substrate production supplies tier-one global OEMs with batch-controlled aluminum plate coatings. METI administers JIS standards for household electrical appliance safety and energy conservation. Industrial concentration in the Chubu region around Nagoya maintains specialized firing kiln capacity for hospitality-grade technical specifications.
India
Organized retail channel expansion creates procurement volume for dual-voltage travel formats and entry-level steam units. BIS certification adoption of IEC 60335-2-3 safety standards is opening import pathways for compliant brands. Distribution momentum clusters in Maharashtra and Gujarat where hospitality investment and residential real estate development concentrate demand.
Portable Iron Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in ceramic substrate and heating element supply. The vendor base organizes into three tiers: premium European manufacturers with captive ceramic technology, Asian-scale assemblers serving mass retail, and private-label distributors sourcing from contract manufacturers. Archetypes include integrated technology owners, component-dependent brand marketers, and regional fabrication specialists. Competitive moves center on direct procurement relationships with hospitality chains and semiconductor partnerships for smart power management integration.
Among European-based integrated manufacturers, Rowenta and Braun exemplify the premium-tier archetype with manufacturing footprints concentrated in Germany. Philips occupies a position bridging premium and mass-market distribution across multiple voltage standards. Sunbeam anchors the North American mass-market channel with standardized compact formats serving big-box retail. Panasonic represents the Asia-based diversified electronics conglomerate archetype with vertical integration into component supply and broad retail distribution.
| Leading Market Players |
|---|
| Rowenta |
| Braun |
| Philips |
| Sunbeam |
| Conair |
| Panasonic |
| Black+Decker |
| Electrolux |
| Tefal |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Japanese ceramic substrate firing kilns is elevating spot pricing for premium aluminum plate coatings while compressing margin structures for mid-tier steam iron assemblers in China and Southeast Asia. Procurement teams at German hotel chains are absorbing these cost pass-throughs through direct manufacturer relationships, whereas mass-market distributors in North America face pricing pressure from inventory carrying costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the portable iron market. Price differentiation rests on ceramic plate certification grade and hospitality procurement volume scale, with EU Ecodesign-compliant units commanding measurable premiums. Cost compression in the stainless steel tier is intensifying because of copper heating element volatility. Household consumers exhibit highest price sensitivity, while hotel procurement teams prioritize lifecycle cost over unit acquisition price.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for portable iron distributors. Manufacturing concentrates in the Pearl River Delta and Yangtze River Delta, drawing from German and Japanese ceramic substrates, Chinese copper wire, and Vietnamese plastic housings. Single-source dependency on Chubu-region firing kiln capacity creates geographic concentration vulnerability. Distribution runs through Midwest logistics corridors for North American mass retail and direct manufacturer relationships for European hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is emerging as extended-stay hospitality formats unbundle in-room pressing from traditional laundry services, creating niche procurement channels outside established distributor relationships.
For Market Incumbents: Build captive ceramic technology moats through backward integration into German substrate production or exclusive partnerships with Nagoya-area firing facilities. Defend against emerging equipment-as-a-service platforms by embedding predictive maintenance capabilities into steam unit control circuitry. Prioritize BIS certification investment to preempt competitor access to Indian organized retail channels. For New Entrants and Emerging Players: Pursue salon and spa service integration as the most penetrable commercial segment, where on-demand pressing as an add-on service creates B2B volume without competing against established hospitality supply relationships. Target Maharashtra and Gujarat distribution clusters where hospitality investment concentrates demand. Lead with dual-voltage travel formats featuring collapsible handle designs to differentiate from incumbent compact steam offerings. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ceramic substrate specialization and regulatory compliance burdens favor scaled platform integrators over component-dependent brand marketers. Acquisition target archetype: mid-tier European manufacturers with captive hospitality relationships but aging semiconductor partnerships. Monitor PFAS restriction implementation timelines as the signal indicating which coating reformulation investments will achieve regulatory clearance advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive supply from Baden-Württemberg facilities secures batch consistency for hospitality technical specifications. |
| Dual-Voltage Architecture Launch | Extended-stay business travel patterns elevate demand for collapsible-handle formats across professional services sectors. |
| BIS Certification Pathway Investment | IEC 60335-2-3 compliance opens organized retail channels in Maharashtra and Gujarat hospitality clusters. |
| Equipment-as-a-Service Platform | Deposit-based lending programs in German hotels displace fixed in-room inventory and narrow capital barriers. |
| Smart Power Management Partnership | Sub-1W standby compliance under EU Ecodesign requires semiconductor module integration with Italian and Spanish specialists. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, hospitality procurement databases, and SEC filings from listed appliance manufacturers. Primary interviews engaged procurement directors at mid-size hotel chains, category buyers at big-box retailers, aftermarket service heads at commercial laundry distributors, and technical R&D directors at ceramic substrate suppliers. Bottom-up shipment analysis triangulates against top-down spending estimates from hospitality amenity budget disclosures.
Forecast inputs include product type segmentation by steam, travel, dry, and cordless architectures; end-user stratification across household, hotel, salon, and apparel manufacturing segments; technology tiers spanning ceramic plate, non-stick coated, stainless steel, and flexible heat; and size categories from mini through heavy duty. CAGRs derive from regression analysis against historical procurement patterns and regulatory implementation timelines. Modeled variables incorporate EU Ecodesign standby power phase-in schedules and REACH coating chemistry registration status.
Sensitivities concentrate around ceramic substrate capacity utilization in Japan, PFAS restriction enforcement variance across EU member states, and BIS certification processing velocity in India. Forecasts reflect documented assumptions regarding hospitality capital expenditure cycles and business travel normalization patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Enameled Cookware Market
Household Items
Smart Shower Market
Household Items
United Kingdom Air Purifier Market
Household Items
Shower Heads and Systems Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Smart Air Purifier Market
Household Items
Global Buddhist Supplies Market
Household Items
Soap Tablet Market
Household Items
Electric Brooms Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Hands-Free Faucet Market
Household Items
Desktop Air Purifier Market
Household Items
Brush Cover Market
Household Items
Folded Tissues Market
Household Items
China Cookware Market
Household Items
Manual Bottle Opener Market