
 Countertop Market | 2026-2036
Countertop Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Market Intelligence
Aftermarket service revenue from countertop repair, refinishing, and edge-profile modification is reconfiguring margin distribution across the value chain. Wilsonart leverages its laminate manufacturing scale to control North American distribution channels. Cosentino SA anchors premium quartz positioning through vertically integrated slab production in Spain and fabrication partnerships across key metros. Cambria competes as a domestically sourced quartz specialist with captive supply chains in Minnesota.
A countertop is a horizontal work surface installed in kitchens, bathrooms, and commercial food-prep zones, typically fabricated from stone, engineered composites, or laminate substrates bonded to particleboard or plywood cores, with thicknesses ranging from 12 mm to 30 mm depending on load-bearing requirements. Its primary commercial purpose is to provide durable, hygienic, and aesthetically finished surfaces for food preparation, display, and utility tasks. Quartz surfaces now dominate new residential construction due to superior stain resistance and uniform patterning, while granite retains share in luxury renovation where natural variation commands premium positioning. The hospitality application segment shows structural acceleration as hotel chains standardize on honed and leathered finishes that mask wear in high-traffic environments.
The EPA enforces formaldehyde emission standards under TSCA Title VI that constrain laminate substrate sourcing and push fabricators toward low-emitting adhesives. California's Air Resources Board maintains stricter CARB Phase 2 thresholds that effectively set the national compliance baseline for countertop manufacturers selling into the US market. The ISO 14001 environmental management framework shapes supplier qualification protocols for large commercial contractors and hospitality procurement teams. Stakeholders must monitor evolving state-level PFAS restrictions that could impact sealant and resin formulations in engineered stone production.
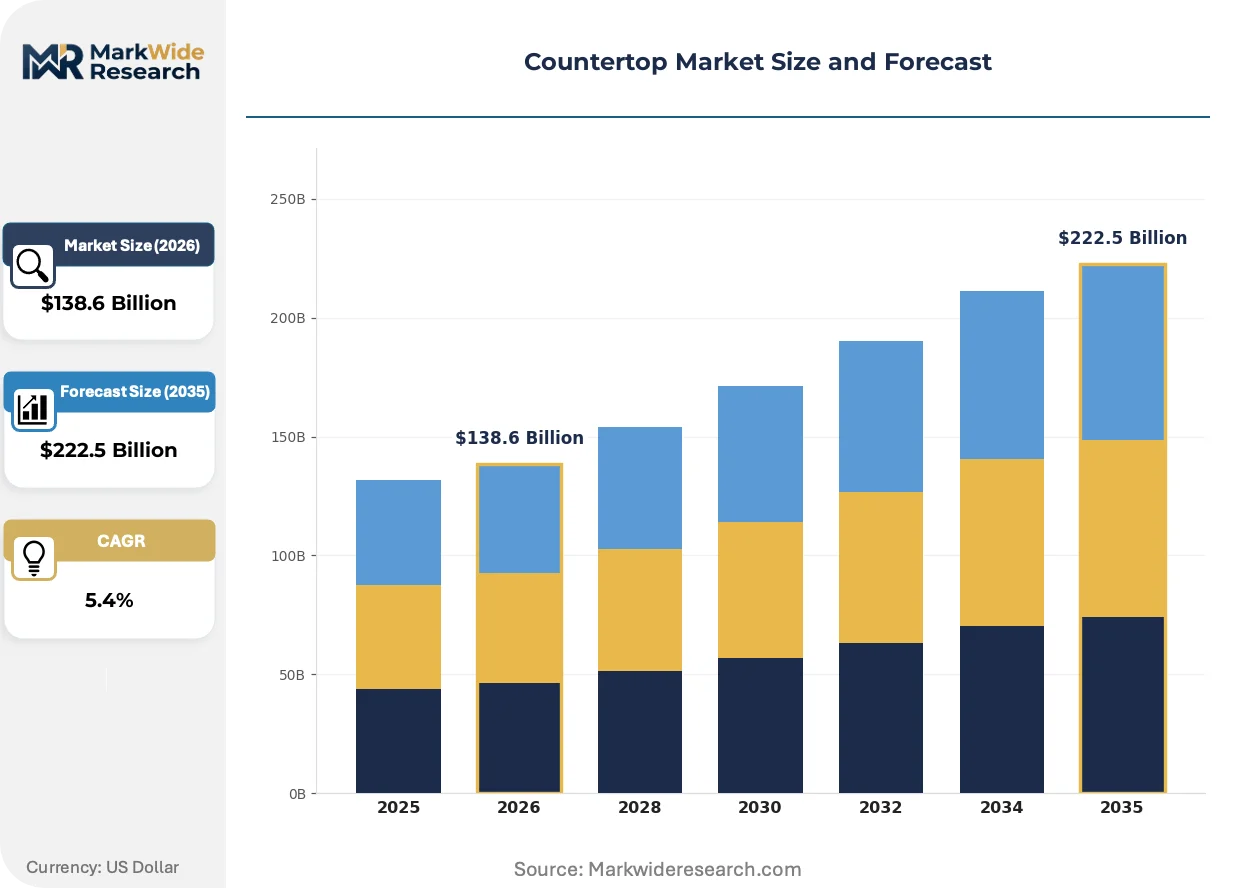
Market Dynamics
Residential kitchen renovation cycles are compressing replacement timelines while EPA formaldehyde emission standards under TSCA Title VI and California's CARB Phase 2 thresholds force substrate and adhesive reformulation across laminate and engineered stone supply chains.
Growth Catalysts
- Engineered Quartz Adoption:Superior stain resistance and pattern uniformity pull specification away from natural stone in multi-family residential construction across the United States.
- TSCA Title VI Compliance:EPA enforcement of formaldehyde emission limits accelerates low-emitting adhesive substitution and certified substrate sourcing by North American fabricators.
- Hospitality Standardization:Hotel chains deploy honed and leathered finishes that mask wear patterns, creating specification pull for textured surface treatments in high-traffic food-prep zones.
Market Restraints
- Resin Input Volatility:Petroleum-derived unsaturated polyester and epoxy resin prices fluctuate with crude benchmarks, compressing margin stability for engineered stone slab producers.
- Slab Production Concentration:Premium quartz manufacturing clusters in Spain and Italy create geographic supply risk for North American fabricators dependent on transoceanic slab shipment.
- Silicosis Exposure Limits:OSHA respirable crystalline silica permissible exposure standards constrain dry-cutting operations and force capital investment in wet-fabrication infrastructure.
Strategic Opportunities
- Brazil Middle-Class Housing:São Paulo and Rio de Janeiro metro expansion drives first-time homebuyer demand for affordable laminate and solid-surface countertops in new construction.
- Digital Templating Convergence:Laser measurement systems paired with CNC fabrication equipment reduce field error rates and enable just-in-time production for custom kitchen layouts.
- India Urban Kitchen Upgrade:Delhi and Mumbai renovation activity creates aftermarket demand for engineered stone replacement of traditional tile and concrete work surfaces.
Industry Challenges
- Skilled Fabricator Shortage:Complex edge profiling and seam matching require trained craftsmen; vocational pipeline gaps constrain installation capacity in high-growth metros.
- Multi-Certification Burden:NSF food-contact safety, Greenguard indoor air quality, and ISO 14001 environmental management audits create compliance timeline friction for mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Market |
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $222.5 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Granite, Marble, Quartz, Laminate Application: Residential, Commercial, Hospitality, Retail Finish Type: Polished, Honed, Leathered, Textured Size: Standard, Custom, Full Slab, Modular |
| Companies Covered | Wilsonart, Silestone, Cosentino SA, Hanwha, Arpa Industriale, Caesarstone, Formica, LOTTE ADVANCED, Cambria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Market Strategic Shifts & Innovations
Surface technology and regulatory compliance frameworks are converging to reshape material specification, fabrication methods, and channel economics across residential and commercial countertop deployment.
Digital templating software paired with automated cutting equipment is virtualizing the measurement-to-fabrication workflow. Kitchen remodel contractors in the United States adopt laser-guided field measurement at accelerating rates. This compression of design-to-installation timelines is virtualizing traditional hand-templating services and reducing slab waste rates.
California's Air Resources Board maintains CARB Phase 2 formaldehyde emission thresholds that exceed federal TSCA Title VI baselines. Manufacturers selling into the United States market treat California standards as the de facto national compliance floor. Laminate substrate suppliers reformulate resins and accelerate third-party certification to maintain specification eligibility.
Homeowner specification behavior now prioritizes certified low-emission surfaces over aesthetic differentiation alone. Big-box retail channels capture share from independent fabricator showrooms by bundling templating, fabrication, and installation into single-price offerings. This channel consolidation is most visible in United States suburban renovation markets where convenience outweighs customization demands.
Countertop Market Segmentation
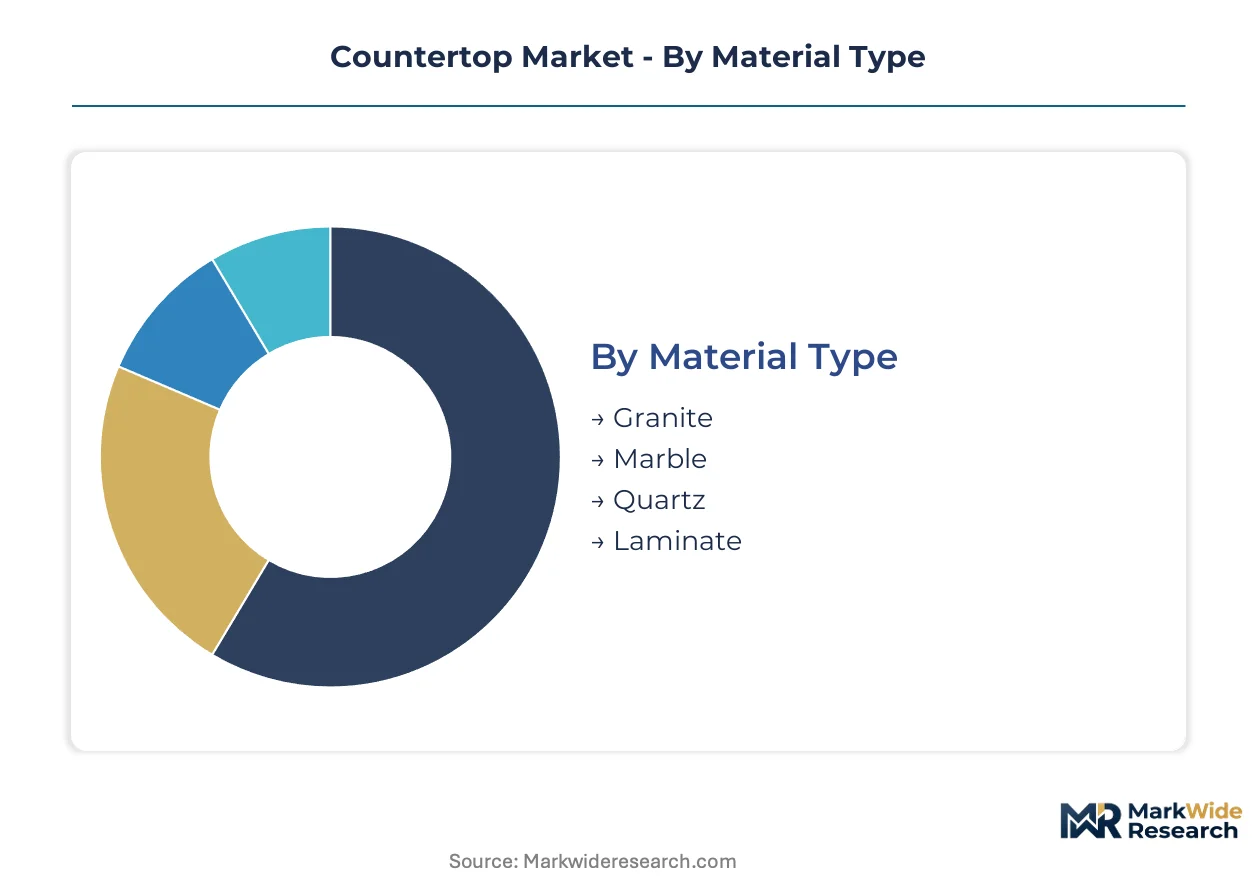
Countertop segmentation reveals divergent replacement cycles across materials and applications. Kitchen renovation timelines compress faster than commercial refresh schedules, while finish preferences shift with hospitality wear-masking requirements.
Material Type:
Quartz and laminate turn over fastest in residential renovation cycles, while granite and marble persist longer in luxury installations where natural variation justifies premium retention.
- Quartz:Engineered slabs combine crushed stone with polymer resins to deliver uniform patterning and superior stain resistance. Multi-family residential construction in the United States specifies quartz for consistency across unit counts, though petroleum-derived resin input costs create margin pressure for slab producers.
- Laminate:Decorative paper layers impregnated with melamine resin bond to particleboard or plywood cores. First-time homebuyer markets in Brazil favor laminate for cost efficiency in São Paulo metro expansion, yet EPA TSCA Title VI formaldehyde emission standards force substrate reformulation across North American supply chains.
- Granite:Igneous rock quarried in slab form retains specification in high-end residential renovation where natural veining commands aesthetic premium positioning.
- Marble:Metamorphic limestone with characteristic veining serves luxury bathroom vanity and pastry preparation surfaces where heat resistance and patina development are valued.
Laminate anchors the volume base while quartz gains share at the steepest rate.
Application:
Cost tiers separate residential mass-market deployment from commercial specification where durability certifications and warranty terms drive procurement decisions.
- Residential:Kitchen and bathroom surfaces in single-family and multi-family housing constitute the largest addressable volume. Indian urban renovation in Delhi and Mumbai displaces traditional tile and concrete with engineered stone upgrades.
- Commercial:Office pantry and institutional food-prep zones demand NSF food-contact safety certification and Greenguard indoor air quality compliance, creating multi-audit burden for mid-scale suppliers.
- Hospitality:Hotel chains standardize on honed and leathered finishes that mask wear patterns in high-traffic food-prep environments, pulling specification toward textured surface treatments.
- Retail:Display counters and service desks in consumer-facing environments prioritize scratch resistance and rapid replacement capability for visual merchandising refresh cycles.
Residential commands absolute volume while hospitality demonstrates the most rapid specification evolution.
Finish Type:
Surface texture maturity separates established polished dominance from emerging textured alternatives that address specific wear-concealment needs.
- Polished:High-gloss reflective surfaces remain standard for residential kitchen specification where light reflection and perceived cleanliness drive homeowner preference.
- Honed:Matte satin finish reduces glare and masks minor scratching in commercial and hospitality applications where maintenance visibility is a concern.
- Leathered:Textured treatment with subtle undulations conceals fingerprints and water spots, expanding fastest in hotel chain standardization for bathroom vanity deployment.
- Textured:Aggressive surface treatments including flamed and brushed patterns serve outdoor kitchen and heavy-use commercial environments where slip resistance complements aesthetic differentiation.
Polished retains volume leadership while leathered expands most quickly in hospitality procurement.
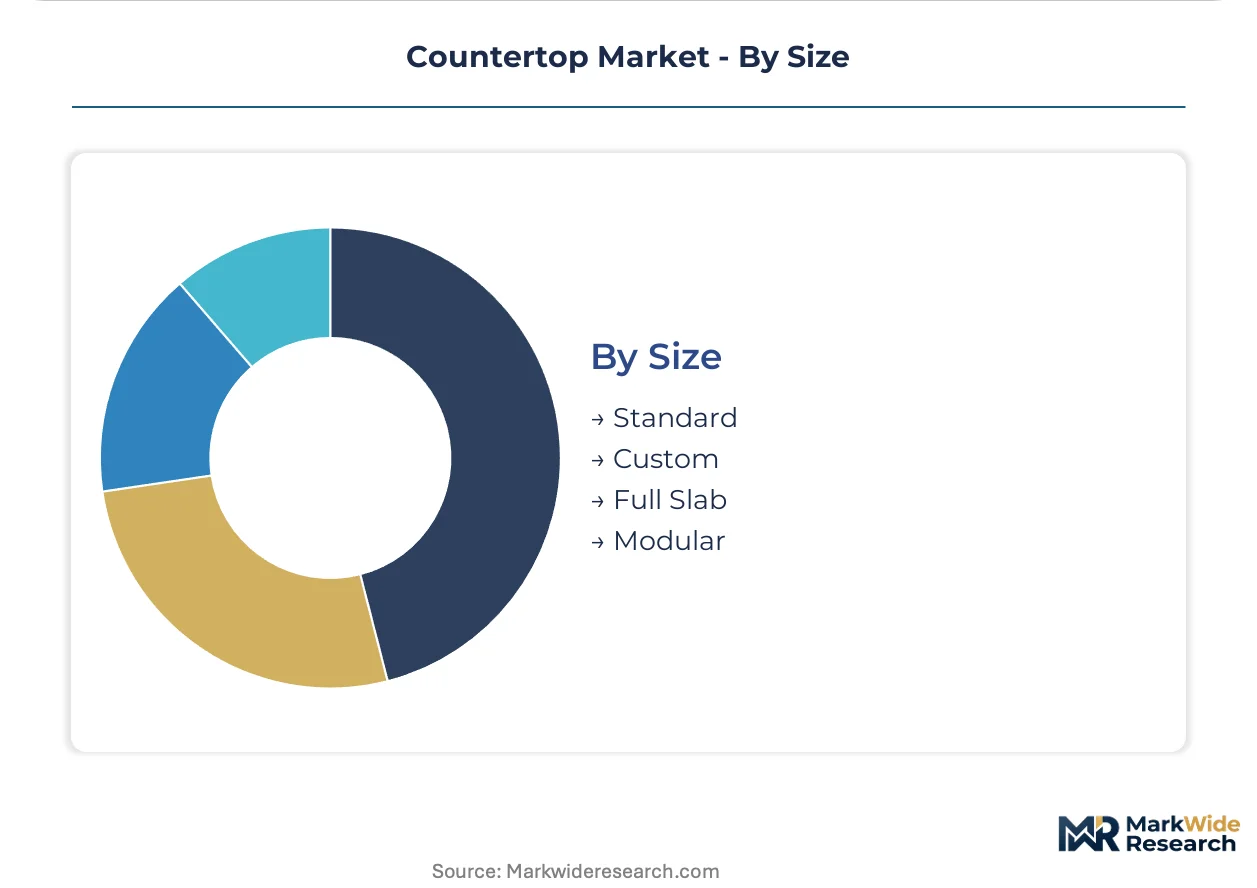
Size:
Supply concentration and margin distribution vary sharply between standardized modular formats and custom full-slab fabrication requiring digital templating investment.
- Standard:Pre-cut dimensions aligned with cabinet manufacturer specifications enable inventory efficiency for big-box retail channels bundling templating, fabrication, and installation.
- Custom:Laser-measured field dimensions paired with CNC fabrication reduce error rates and enable just-in-time production for complex kitchen layouts in United States suburban renovation markets.
- Full Slab:Uncut material sheets require skilled fabricator capacity for seam matching and edge profiling, constraining installation capacity where vocational pipeline gaps persist.
- Modular:Pre-fabricated sections with finished edges suit apartment renovation and commercial refresh projects where speed of installation outweighs seamless appearance.
Standard formats dominate volume throughput while custom sizing climbs fastest as digital templating adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize low-emission certification and rapid installation turnaround. Brazilian and Indian markets favor cost-efficient surfaces for first-time homebuyers. European specification emphasizes environmental compliance and design heritage.
United States
Residential renovation cycles compress replacement timelines across suburban markets. EPA TSCA Title VI formaldehyde emission standards and California CARB Phase 2 thresholds force substrate reformulation by laminate suppliers. Fabrication demand clusters in Minnesota, where captive quartz production serves Midwest distribution networks.
Brazil
São Paulo and Rio de Janeiro metro expansion drives first-time homebuyer demand for affordable laminate and solid-surface countertops. The country's national housing finance programs accelerate middle-class housing stock development. Fabrication capacity concentrates in southeastern industrial zones serving construction growth corridors.
China
Urban kitchen upgrades in tier-one cities displace traditional tile and concrete with engineered stone surfaces. GB standards for indoor air quality and construction material safety shape supplier qualification protocols. Manufacturing clusters in Guangdong and Fujian provinces supply domestic and export slab demand.
India
Delhi and Mumbai renovation activity creates aftermarket demand for engineered stone replacement of tile and concrete work surfaces. The Bureau of Indian Standards maintains certification requirements for construction materials in commercial and residential deployment. Fabrication demand concentrates in Maharashtra and Gujarat as urban housing stock modernizes.
Germany
Commercial and hospitality specification prioritizes Greenguard indoor air quality certification and ISO 14001 environmental management compliance. REACH regulations constrain resin formulations and adhesive chemistry in engineered stone production. Industrial fabrication capacity clusters in North Rhine-Westphalia and Bavaria serving central European distribution.
Countertop Market Key Industry Players
Capability concentration sits with vertically integrated slab producers; scale advantage sits with laminate manufacturers controlling North American distribution channels. The market structures around three archetypes: premium quartz specialists with captive supply chains, diversified surface material conglomerates, and regional fabrication networks. Competitive moves center on backward integration into resin and substrate production, plus digital templating partnerships that compress design-to-installation timelines.
Among Spain-based producers, Cosentino SA exemplifies premium-tier vertical integration through in-house slab production and metro fabrication partnerships. Wilsonart represents scale-driven laminate manufacturing with channel control across North American big-box retail. Cambria occupies a position as a domestically sourced quartz specialist with Minnesota-based captive supply chains.
| Leading Market Players |
|---|
| Wilsonart |
| Silestone |
| Cosentino SA |
| Hanwha |
| Arpa Industriale |
| Caesarstone |
| Formica |
| LOTTE ADVANCED |
| Cambria |
| Others |
Cost & Logistics Intelligence
Transatlantic container routes from Valencia and Livorno to US East Coast ports transmit slab freight volatility directly into landed cost spreads, compressing margin buffers for North American fabricators while amplifying price differentiation between captive-supply quartz specialists and import-dependent competitors.
Pricing Analysis
Long-term offtake contracts between Spanish slab producers and US fabrication networks anchor premium quartz pricing, while spot-market laminate transactions in Brazil respond to resin input swings. Certification grade separates Greenguard-compliant surfaces from uncertified alternatives, and brand premium widens between vertically integrated suppliers and regional fabricators. Cost compression in entry-level laminate intensifies as petroleum-derived substrate resins fluctuate with crude benchmarks. First-time homebuyers in São Paulo metro markets exhibit highest price sensitivity, whereas hospitality procurement teams in United States suburban renovation corridors prioritize rapid installation turnaround over unit cost.
Supply Chain Analysis
Extended payment terms from Spanish and Italian slab producers to North American distribution partners cushion working capital strain for mid-scale fabricators expanding wet-cutting capacity. Supply concentrates in Spain, Italy, and China for premium quartz slab production, while laminate substrate manufacturing clusters in Brazil and Southeast Asia. Raw material dependencies center on unsaturated polyester resin, crushed quartz aggregate, and formaldehyde-compliant particleboard cores. Single-source vulnerability from transoceanic slab shipment creates exposure to port congestion and customs inspection delays. Distribution runs through big-box retail channels bundling templating, fabrication, and installation in United States suburban markets, alongside independent fabricator showrooms serving custom kitchen renovation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital templating convergence with automated CNC fabrication is disrupting traditional hand-templating services, compressing design-to-installation timelines and reshaping competitive advantage toward technology-adopted suppliers.
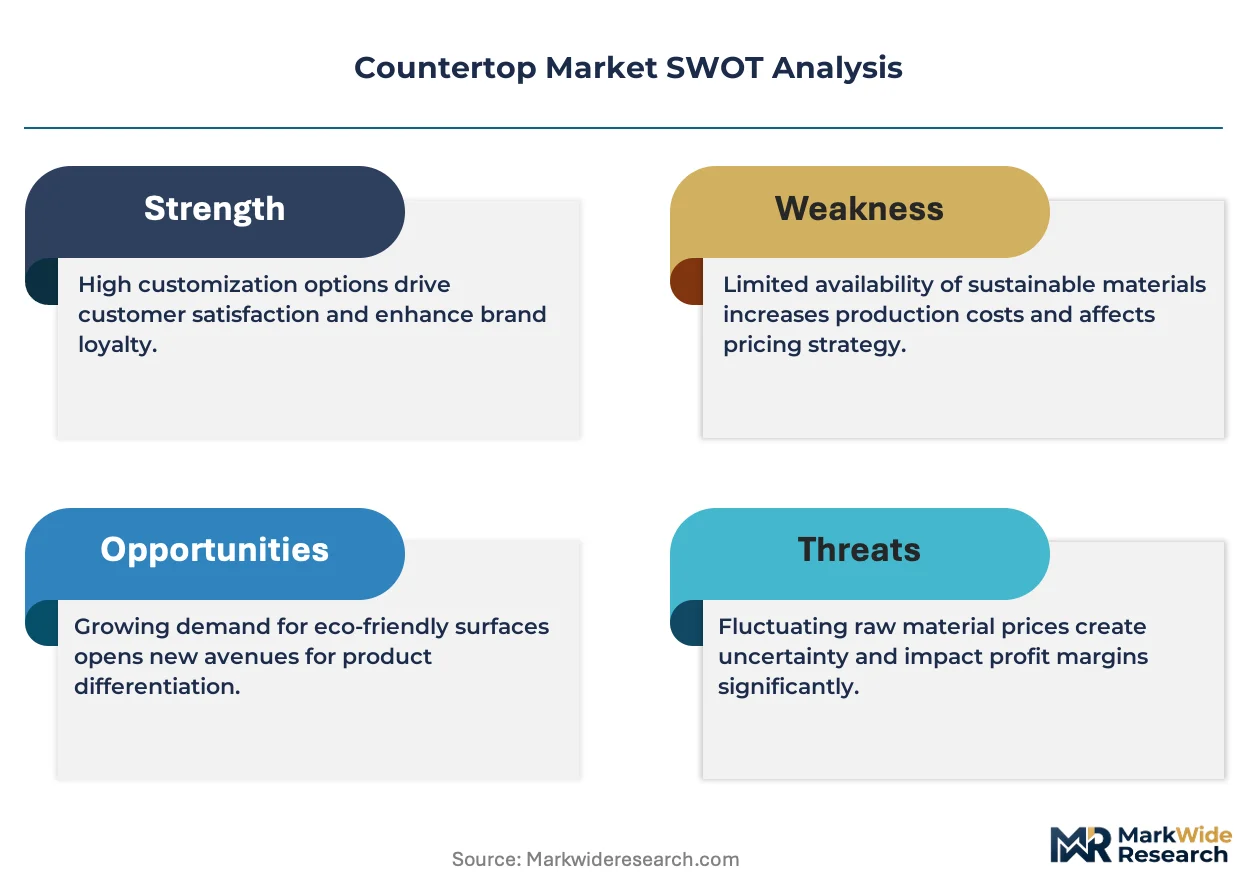
For Market Incumbents: Harden specification lock-in by embedding laser measurement systems within metro fabrication partnerships, countering independent templating services that threaten channel control. Deepen captive supply of low-emitting laminate substrates to preempt EPA TSCA Title VI enforcement acceleration. Certification investment in NSF food-contact and Greenguard indoor air quality tiers defends margin position against uncertified imports.
For New Entrants and Emerging Players: Build out digital templating service networks in India urban kitchen upgrade corridors, where Delhi and Mumbai renovation activity displaces traditional tile and concrete with engineered stone replacement. Target first-time homebuyer segments in Brazil middle-class housing expansion, where national housing finance programs accelerate affordable laminate demand. Partner with hospitality procurement teams on honed and leathered finish standardization to bypass incumbent polished-surface dominance.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building materials conglomerates with underoptimized countertop divisions lacking vertical slab supply. Long-term viability favors specialists with captive resin formulation capabilities and certified substrate sourcing. Watch OSHA respirable crystalline silica enforcement trajectory as inflection indicator for wet-fabrication infrastructure investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of unsaturated polyester buffers petroleum input volatility for engineered stone slab producers. |
| Digital Templating Network Expansion | Laser measurement systems paired with CNC equipment reduce field error rates in United States suburban renovation markets. |
| Low-Emitting Substrate Certification | EPA TSCA Title VI and California CARB Phase 2 compliance secures specification eligibility across North American distribution channels. |
| Hospitality Finish Standardization | Honed and leathered surface treatments mask wear patterns in high-traffic hotel food-prep environments. |
| Wet-Fabrication Infrastructure Investment | OSHA respirable crystalline silica compliance enables dry-cutting substitution without constraining installation capacity. |
Research Approach
A spread of perspectives from slab production executives, fabrication network operators, hospitality procurement directors, big-box retail category managers, and residential renovation contractors converged on the working assumptions driving volume and value estimates. Primary field engagement combined structured interviews with secondary validation against customs records, SEC filings from listed surface material producers, EPA enforcement disclosures, and CARB certification databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across material type, application, finish, and size dimensions.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with engineered quartz adoption rates, laminate substrate reformulation timelines, and hospitality standardization patterns serving as core segmentation variables. CAGRs derived from slope analysis of replacement cycle compression, regulatory compliance cost pass-through, and digital templating penetration curves. Industry-specific inputs included EPA formaldehyde emission enforcement intensity, OSHA silica exposure standard implementation pace, and Brazil national housing finance program disbursement trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated quartz specialists or big-box retail channel consolidators would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Facial Tissue Market
Household Items
North America Car Air Freshener Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
UK Digital Showers Market
Household Items
Sleeping Pillow Market
Household Items
Dishwashing Products Market
Household Items
Latex Mattress Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Europe Hand Dryers Market
Household Items
Insulated Tumblers Market
Household Items
Cutlery Steel Market
Household Items
Multi-Door Fridges Market
Household Items
Ultrasonic Diffusers Market
Household Items
Insulated Lunch Box Market
Household Items
Electric Clothes Drying Hanger Market