
 Powered Lawn Mowers Market | 2026-2036
Powered Lawn Mowers Market Size, Share, and Industry Trends Forecast 2026-2036
Powered Lawn Mowers Market Outlook
Direct-to-consumer e-commerce channels are rewriting how powered lawn mowers reach end users, with digital platforms capturing share from traditional dealer networks and big-box retail. Husqvarna Group leverages its robotic mower technology leadership to dominate connected outdoor equipment subscriptions. The Toro Company anchors its position through deep vertical integration into commercial-grade cutting systems for golf and sports turf. Deere & Company extends its precision agriculture expertise into autonomous mowing platforms for large-scale estate management.
A powered lawn mower is a motorized grass-cutting machine employing internal combustion engines, electric motors, or battery-driven systems to rotate blades at controlled speeds, typically generating cutting widths from sixteen to seventy-two inches and operating at blade tip velocities exceeding eighteen thousand feet per minute. Its primary commercial purpose is mechanized turf maintenance across residential lawns, commercial grounds, sports fields, and municipal green spaces. Battery-operated product types are capturing the fastest growth as lithium-ion energy density improvements and brushless motor efficiency gains reduce runtime anxiety and maintenance burdens. Rotary cutting technology sustains dominant volume share due to versatility across grass conditions and terrain types, while robotic cutting systems concentrate margin pools in premium residential and commercial landscaping services segments.
EPA Phase 3 emissions standards and California Air Resources Board small off-road engine rules are forcing gas-powered model redesigns and accelerating manufacturer investment in zero-emission platforms. EU F-Gas Regulation and CE machinery directives shape product compliance requirements for equipment sold across European member states. Stakeholders must monitor battery supply chain localization mandates and evolving carbon border adjustment mechanisms as determinants of competitive manufacturing location and market access.
Market Dynamics
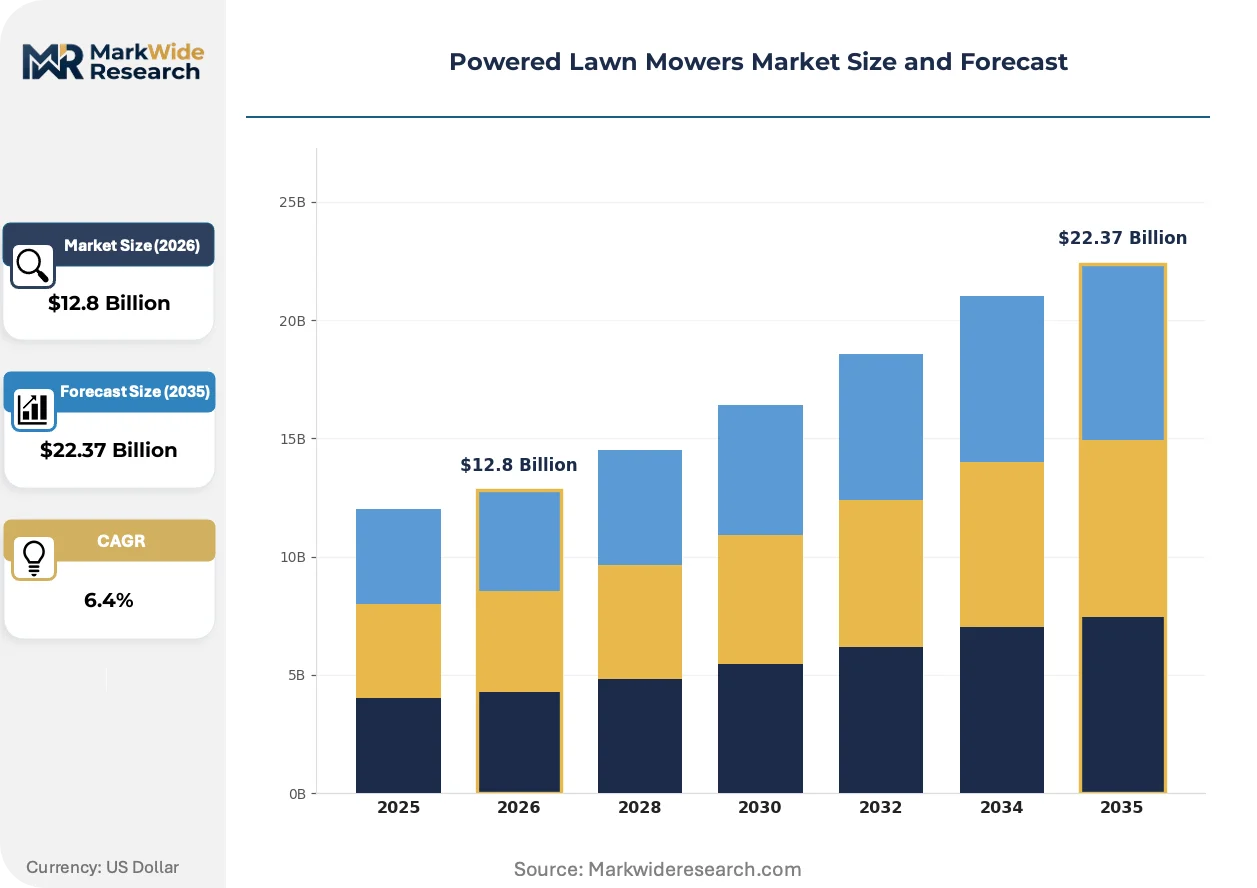
EPA Phase 3 emissions standards and EU F-Gas Regulation are forcing gas-powered model redesigns while lithium-ion battery platforms capture premium residential and commercial segments through runtime improvements and brushless motor efficiency gains.
Growth Catalysts
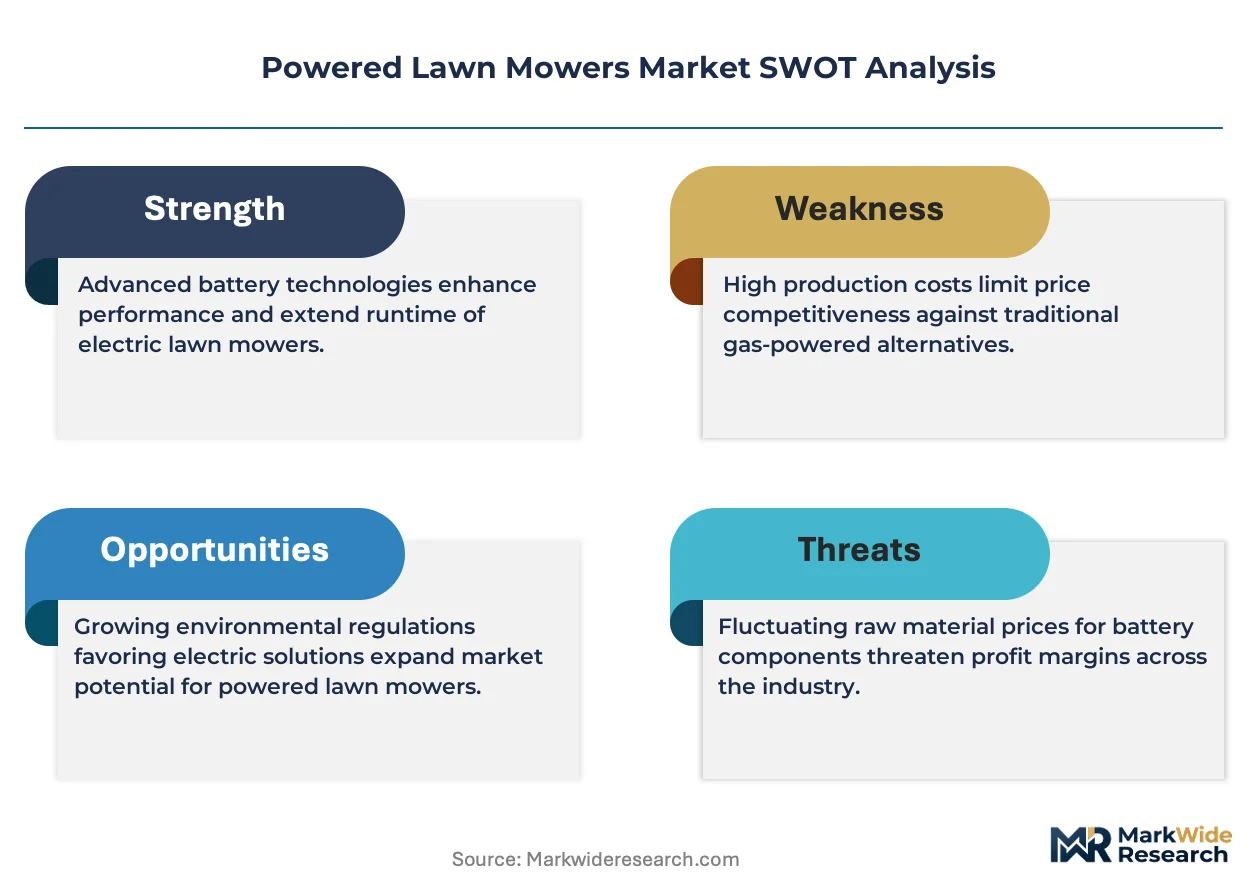
- EPA Phase 3 Standards:Tightening small off-road engine emissions rules in the United States are compelling manufacturers to accelerate zero-emission platform development and redirect R&D budgets toward battery-electric architectures.
- Landscaping Services Expansion:Commercial grounds maintenance contracts are multiplying across municipal parks, corporate campuses, and sports facilities, driving fleet replacement cycles toward connected, autonomous-capable equipment.
- Lithium-Ion Energy Density:Cell chemistry improvements are extending runtime per charge while reducing battery pack weight, eliminating historical performance gaps between cordless and gasoline rotary systems.
Market Restraints
- Raw Material Concentration:Cobalt and lithium processing capacity concentrates in Chinese refining facilities, exposing battery supply chains to geopolitical friction and export restriction risks.
- Small Engine Technical Limits:Thermal efficiency ceilings in compact internal combustion architectures prevent further emissions reductions without substantial cost increases or power trade-offs.
- Refrigerant Regulatory Friction:EU F-Gas Regulation compliance timelines for outdoor power equipment cooling systems are compressing product development windows and raising certification costs.
Strategic Opportunities
- Robotic Mower Subscriptions:Connected outdoor equipment service models are penetrating premium residential segments in Germany and Japan through automated perimeter mapping and weather-integrated scheduling.
- CE Machinery Directives:European Union harmonized safety standards are creating regulatory tailwinds for manufacturers with established compliance infrastructure to expand cross-border sales.
- Direct-to-Consumer E-Commerce:Digital platforms are displacing traditional dealer networks in the United States, enabling manufacturers to capture margin previously allocated to retail intermediaries.
Industry Challenges
- Battery Technician Scarcity:Servicing high-voltage lithium-ion platforms requires specialized electrical diagnostics training that existing small-engine repair networks lack.
- Autonomous Navigation Certification:ISO safety standards for robotic outdoor equipment collision avoidance are evolving faster than testing protocols, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powered Lawn Mowers Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Powered, Electric, Battery-Operated, Hybrid End User: Residential, Commercial, Landscaping Services, Municipalities Cutting Technology: Rotary, Reel, Hover, Robotic Size: Small, Medium, Large, Extra Large |
| Companies Covered | Husqvarna Group, The Toro Company, Deere & Company, Stanley Black & Decker, American Honda Motor Co., Inc., MTD Products, AriensCo, STIHL, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powered Lawn Mowers Market Strategic Shifts
Digital connectivity architectures are rewriting equipment ownership models while regulatory emissions frameworks accelerate powertrain transitions and procurement patterns fragment across channel types.
Telematics-enabled predictive maintenance is virtualizing traditional dealer service relationships. Golf course superintendents and municipal fleet managers are adopting cloud-connected cutting systems that transmit blade wear, battery health, and location data to centralized dashboards. This virtualization compresses aftermarket parts margins for independent repair shops while shifting recurring revenue toward manufacturer-controlled software subscriptions.
California Air Resources Board small off-road engine rules are eliminating gasoline-powered sales in the state's residential segments by 2024. Equipment manufacturers are reallocating California-compliant inventory to other states while accelerating battery platform production for West Coast markets. The commercial landscaping segment faces the steepest compliance cost increases as high-utilization fleets cannot absorb downtime from early-generation cordless runtime limitations.
Equipment-as-a-service contracting is displacing capital purchase models among multi-site facility managers. Corporate campus maintenance departments in Japan and Germany are bundling robotic mowing, seasonal blade replacement, and snow removal into fixed monthly fees. This shift concentrates buyer power with national facility management firms while forcing smaller landscaping contractors toward specialized terrain applications where autonomous systems underperform.
Powered Lawn Mowers Market Segmentation
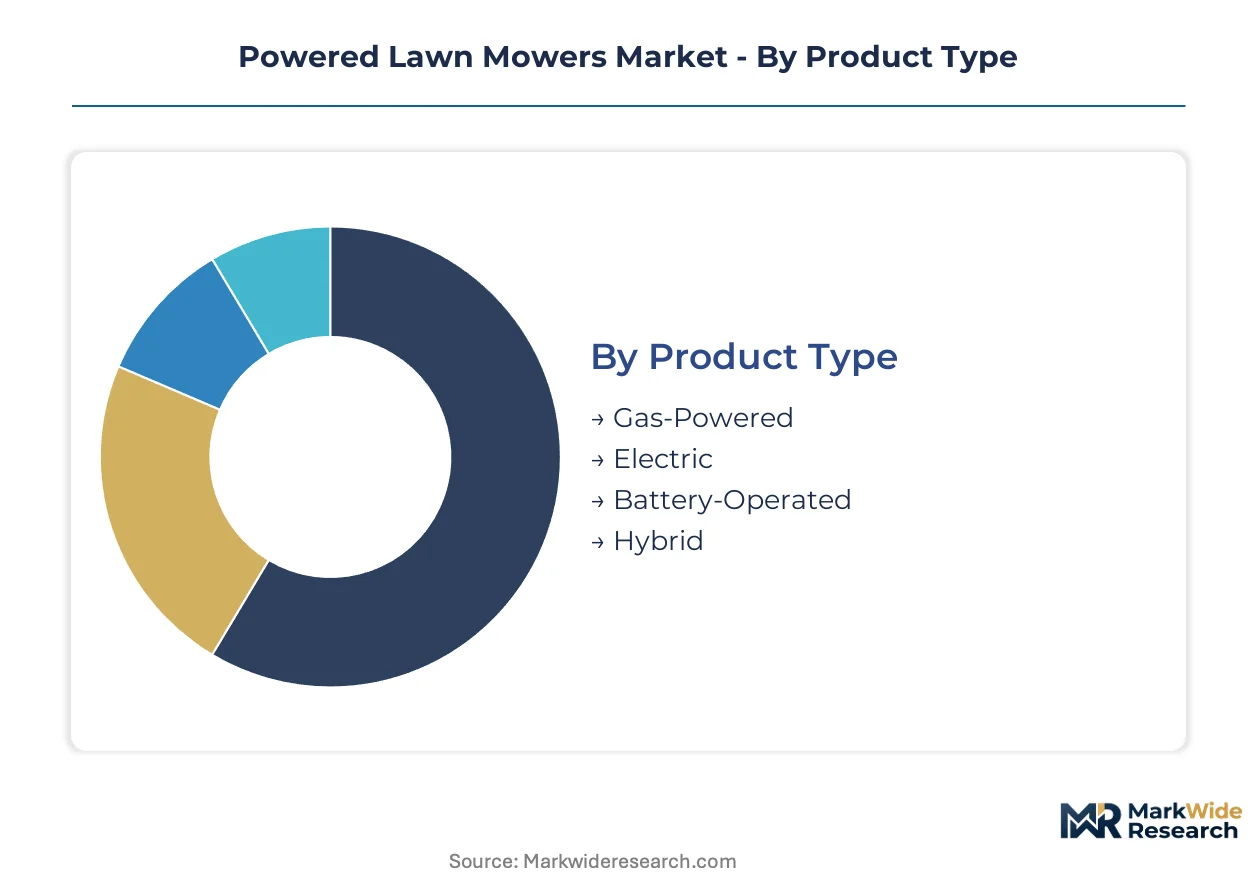
Segmentation in powered lawn mowers reveals how powertrain choices, user scale, and cutting mechanics fragment procurement patterns across residential estates and professional grounds maintenance operations. Understanding these divides exposes where battery platforms displace legacy combustion systems and where autonomous systems capture premium service contracts.
Product Type:
Powertrain selection spans combustion legacy systems, grid-tethered electric, cordless battery platforms, and emerging hybrid architectures that blend fuel flexibility with electric efficiency.
- Gas-Powered:Internal combustion engines utilizing gasoline deliver sustained torque for dense turf and extended runtime without recharge cycles. Demand concentrates in commercial landscaping fleets across the United States where high daily utilization exceeds current battery endurance, though EPA Phase 3 compliance costs are compressing margins and accelerating fleet transition timelines.
- Battery-Operated:Lithium-ion cell packs paired with brushless DC motors generate blade tip velocities matching gasoline equivalents while eliminating exhaust emissions and reducing noise pollution. Residential demand clusters in Germany and Japan as municipal noise ordinances tighten and carbon-conscious consumers prioritize zero-emission maintenance, with landscaping services firms piloting cordless platforms for mid-scale corporate campus contracts.
- Electric:Corded AC motor systems deliver uninterrupted power for small residential plots where outlet proximity eliminates runtime constraints. These units dominate entry-level price tiers in established suburban markets with reliable grid infrastructure.
- Hybrid:Dual-mode architectures switch between gasoline generation and battery drive to optimize fuel consumption across variable terrain. Early adoption centers on large estate management in California where CARB regulations restrict pure gasoline operation.
The dominant share belongs to Gas-Powered equipment, while Battery-Operated platforms are closing the gap fastest.
End User:
Customer scale determines equipment specification intensity, from homeowner convenience priorities through municipal procurement compliance requirements.
- Residential:Individual property owners prioritize storage footprint, noise reduction, and ease of operation over cutting width maximization. Battery platforms are displacing gasoline in premium suburban segments across the United States as direct-to-consumer e-commerce channels reduce search friction and price transparency improves.
- Commercial:Corporate facility managers and multi-site property owners demand fleet telematics, predictive maintenance contracts, and standardized equipment pools to reduce total cost of ownership. Equipment-as-a-service subscriptions are penetrating this segment in Japan through bundled seasonal maintenance and autonomous capability upgrades.
- Landscaping Services:Professional grounds maintenance contractors operate equipment across multiple client sites with high daily utilization rates. These firms face the steepest compliance cost increases from emissions regulations while early cordless adopters struggle with technician training gaps for high-voltage diagnostics.
- Municipalities:City parks departments and public works agencies procure through formal tender processes with lifecycle cost evaluation and emissions compliance mandates. European Union Green Deal procurement guidelines are redirecting capital allocation toward zero-emission platforms in Germany and France.
Residential volume leads absolute unit sales, though Commercial end users generate superior margin capture through service bundling and connectivity subscriptions.
Cutting Technology:
Mechanical cutting approaches range from high-speed rotary systems through precision reel architectures to autonomous navigation platforms.
- Rotary:Horizontal spinning blades mounted on vertical spindles cut grass through impact shear at tip velocities exceeding eighteen thousand feet per minute. This technology sustains dominant volume share due to versatility across grass conditions, terrain irregularities, and debris tolerance in municipal and commercial applications.
- Robotic:Autonomous perimeter-mapped systems navigate complex lawn geometries through GPS, boundary wire, or vision-based localization without human operation. Premium residential demand concentrates in Germany through Husqvarna's connected equipment subscriptions, while ISO safety standard evolution for collision avoidance continues delaying product launches.
- Reel:Cylindrical helical blades scissor grass against stationary bed knives for precise cutting without tearing, preserving turf health for golf and sports field applications. These systems command premium pricing in professional sports turf maintenance where cut quality directly affects play surface performance.
- Hover:Air-cushion platforms float above turf on downward thrust, enabling maneuverability on slopes and uneven terrain where wheeled systems lose traction. Niche adoption persists in steep-gradient residential properties and coastal dune maintenance where ground pressure damage must be minimized.
Rotary systems anchor volume leadership through operational flexibility, while Robotic platforms exhibit the steepest expansion trajectory in premium segments.
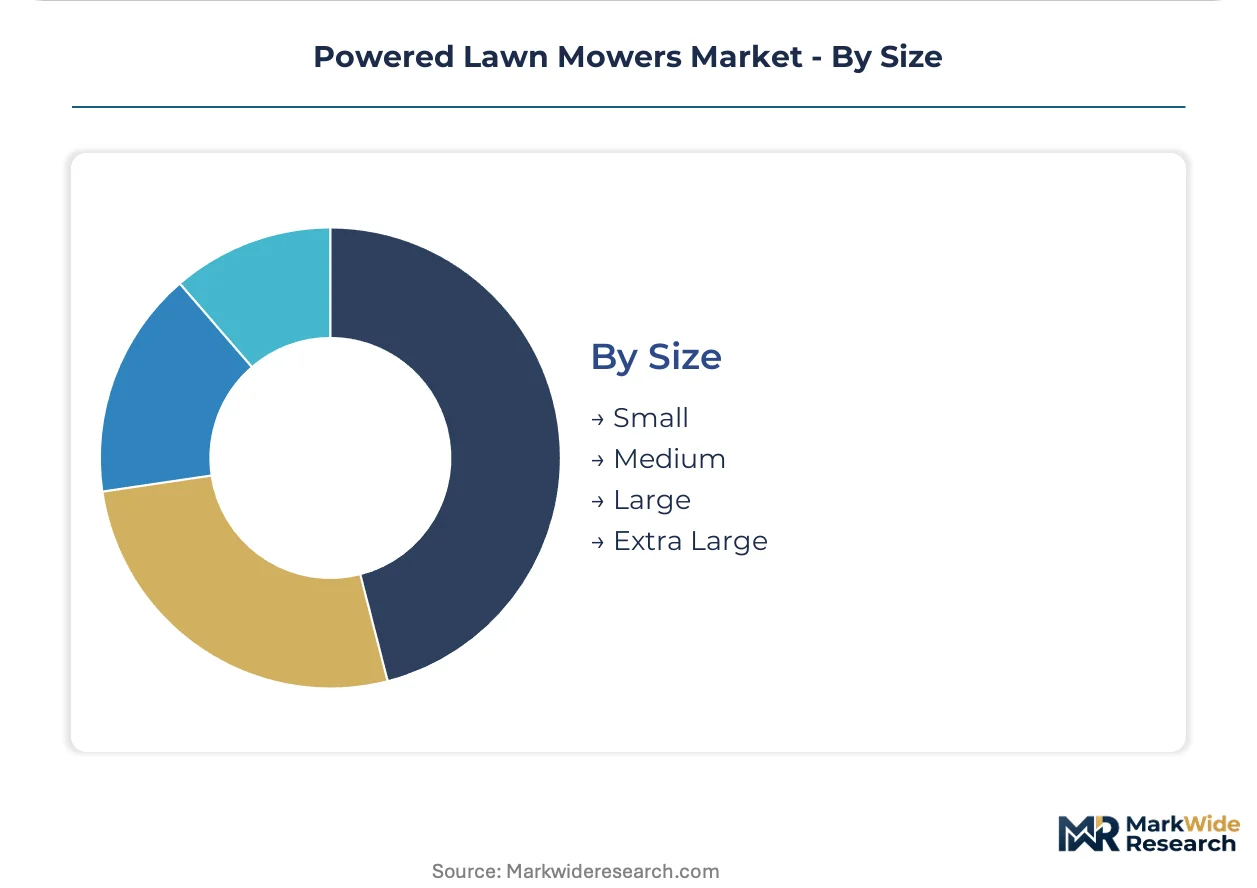
Size:
Cutting deck dimensions scale from compact sixteen-inch residential units through seventy-two-inch commercial zero-turn systems.
- Small:Cutting widths below twenty inches suit urban row houses and compact suburban lots where storage constraints dominate specification. Battery platforms have achieved near-complete penetration in this tier across Japanese metropolitan markets.
- Medium:Twenty to thirty-inch decks balance maneuverability with productivity for standard residential plots and small commercial grounds. This segment experiences the most intense price competition as Chinese manufacturing scales and direct-to-consumer channels displace dealer networks.
- Large:Thirty to fifty-inch systems serve estate properties, sports fields, and mid-scale commercial campuses where operator efficiency outweighs capital cost sensitivity. Landscaping services firms in the United States are consolidating fleet procurement in this tier to standardize maintenance protocols.
- Extra Large:Decks exceeding fifty inches require zero-turn or ride-on configurations for golf courses, municipal parks, and airport turf management. Deere & Company anchors this segment through precision agriculture expertise extended into autonomous mowing platforms for large-scale estate management.
Medium size configurations generate the highest absolute unit volume, though Extra Large systems deliver superior revenue per unit through technology integration and autonomous capability premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 standards and California Air Resources Board rules are forcing gas-powered model redesigns across the United States, while EU F-Gas Regulation and Green Deal procurement guidelines redirect European capital toward zero-emission platforms.
United States
Commercial landscaping fleets in Florida and Texas drive sustained gas-powered demand where high daily utilization exceeds battery endurance. CARB small off-road engine rules eliminate gasoline-powered residential sales in California by 2024, reallocating compliant inventory to other states. Georgia-based fleet operators consolidate procurement around medium-size zero-turn systems for standardized maintenance protocols.
Germany
Premium residential segments in Bavaria and Baden-Württemberg concentrate battery-operated demand as municipal noise ordinances tighten. EU F-Gas Regulation compliance timelines compress product development windows for cooling system redesigns. Stuttgart industrial clusters host precision manufacturing for robotic mower navigation systems and brushless motor assemblies.
Japan
Metropolitan Tokyo and Osaka markets achieve near-complete battery platform penetration in small cutting-width tiers. METI efficiency standards accelerate lithium-ion energy density improvements for cordless runtime extension. Nagoya-area engineering centers develop autonomous perimeter-mapping algorithms for weather-integrated scheduling subscriptions.
China
Domestic manufacturing scales concentrate in Zhejiang and Jiangsu provinces for medium-size deck exports to North American and European markets. MEE emissions monitoring and dual carbon goals pressure domestic producers toward electrification. Ningbo industrial zones supply brushless DC motors and lithium cell pack assemblies to multinational OEMs.
United Kingdom
Southeast England estate management drives demand for large and extra-large cutting systems with autonomous capability upgrades. CE machinery directives and post-Brexit UKCA marking requirements create compliance complexity for cross-border equipment sales. Midlands manufacturing corridors produce precision reel cutting systems for sports turf export markets.
Powered Lawn Mowers Market Competitive Environment
Specialist outdoor power equipment manufacturers and diversified industrial conglomerates split the market along technology-integration fault lines. Consolidation pressures concentrate around connected equipment subscriptions and autonomous navigation platforms. Three archetypes dominate: precision-engineering heritage brands, diversified tool conglomerates with battery platform leverage, and agricultural machinery giants extending precision farming expertise. Competitive moves center on robotic mower subscription service rollouts and battery supply chain backward integration.
Within the precision-engineering tier, Husqvarna Group and STIHL represent heritage archetypes with established European compliance infrastructure. The Toro Company and Deere & Company anchor North American positions through commercial-grade cutting system specialization and large-scale estate management platforms. Stanley Black & Decker exemplifies diversified conglomerate strategy, leveraging cordless power tool battery ecosystems across residential segments. These five entities collectively demonstrate how geographic origin and corporate structure shape competitive positioning without mandating identical capability investments.
| Leading Market Players |
|---|
| Husqvarna Group |
| The Toro Company |
| Deere & Company |
| Stanley Black & Decker |
| American Honda Motor Co., Inc. |
| MTD Products |
| AriensCo |
| STIHL |
| Kubota Corporation |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu provinces anchor lithium-ion cell pack and brushless motor manufacturing capacity, concentrating upstream pricing power among Chinese refiners while downstream OEMs face margin compression from cobalt and lithium processing bottlenecks.
Pricing Analysis
North American and European markets exhibit substantial price spreads for equivalent cutting-width specifications, with battery-operated platforms commanding premium positioning over gas-powered alternatives driven by EPA Phase 3 compliance costs and EU F-Gas Regulation certification tiers. Three-tier pricing structure across premium robotic subscriptions, standard cordless units, and economy corded systems separates buyer segments by connectivity features and autonomous capability. Pricing pressure stems from raw material volatility in lithium supply chains, with landscaping services firms showing highest price sensitivity due to fleet-scale procurement volumes and compressed maintenance margins.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Ningbo-based motor suppliers have become standard for multinational OEMs sourcing brushless DC assemblies, tightening working capital requirements for smaller manufacturers. Production draws from China, South Korea, and Japan for lithium cell chemistry, with cobalt concentrate dependencies creating single-source vulnerability around Congolese mining operations. Distribution runs through direct-to-consumer e-commerce platforms displacing traditional dealer networks in the United States, while big-box retail retains volume share in suburban residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national facility management firms bundling equipment-as-a-service contracts, fragmenting procurement influence away from independent landscaping contractors toward consolidated multi-site operators.
For Market Incumbents: Harden battery supply chain resilience through backward integration into lithium cell pack assembly or captive offtake agreements with Korean and Japanese chemistry suppliers. Defend service revenue pools by accelerating telematics-enabled predictive maintenance subscriptions before ISO safety standards for autonomous navigation finalize testing protocols. For New Entrants and Emerging Players: Pursue white-space opportunity in medium-size battery-operated platforms for European municipal procurement, where EU Green Deal guidelines redirect capital toward zero-emission platforms but established OEMs lack localized compliance infrastructure. Target Germany's premium residential robotic subscriptions through perimeter-mapping software partnerships with Stuttgart engineering clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected equipment subscription providers with established cloud-platform infrastructure and autonomous capability roadmaps. Long-term viability across the analysis window favors acquisition targets with in-house brushless motor design and battery management system expertise. Watch lithium supply chain localization mandates as the critical inflection signal for competitive manufacturing location decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Enables cross-product lithium-ion ecosystem leverage from residential mowers through commercial utility vehicles. |
| Robotic Subscription Service Launch | Captures recurring revenue from German and Japanese premium residential segments through weather-integrated scheduling. |
| Backward Integration into Motor Manufacturing | Reduces dependency on Ningbo suppliers for brushless DC assemblies and compresses procurement lead times. |
| Direct-to-Consumer Channel Expansion | Displaces dealer margin capture in United States residential segments through digital platform ownership. |
| Autonomous Navigation Certification Investment | Accelerates ISO compliance timelines for collision avoidance systems ahead of evolving safety standards. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with landscaping services fleet managers, municipal procurement officers, golf course superintendents, and battery platform engineering leads; alongside secondary validation through EPA emissions filings, EU F-Gas Regulation compliance databases, customs trade records for outdoor power equipment, and SEC 10-K disclosures from listed OEMs. Bottom-up unit economics triangulated against top-down market sizing across powertrain, end-user, cutting technology, and size dimensions.
Forecast inputs considered lithium-ion energy density improvement curves, CARB regulatory phase-out timelines, and landscaping services contract growth patterns across the projection horizon. Segmentation modeling spanned powertrain architecture, customer scale, cutting mechanics, and deck size tiers. CAGRs derived from regression analysis against historical replacement cycle data and fleet electrification adoption slopes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese manufacturing conglomerates or battery chemistry specialists would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Laptop Tables Market
Household Items
Global Rimless Toilets Market
Household Items
India POU Water Purifiers Market
Household Items
Shower Heads and Systems Market
Household Items
Smart Pool Skimmer Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Hand Dryer Market
Household Items
South Korea Cookware Market
Household Items
United Kingdom Air Purifier Market
Household Items
Aromatherapy Diffuser Market
Household Items
Portable Vacuum Cleaner Market
Household Items
Water Purifier Bottle Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Laundry Detergent Sheets Market
Household Items
Electric Hedge Trimmer Market
Household Items
Sleeping Pillow Market