
 Hangers Market | 2026-2036
Hangers Market Size, Share, and Industry Trends Forecast 2026-2036
Hangers Market Foresight
EU Green Deal packaging waste targets is expanding demand for recycled-content and biodegradable hanger materials across European apparel retail. National Hanger Company leverages its domestic manufacturing footprint to supply major U.S. department stores with certified recycled-plastic lines. Mainetti Group anchors global volume through vertical integration into rPET flake processing and regional molding plants across Italy, Vietnam, and the United States.
A hanger is a formed support device, typically constructed from wire, plastic, wood, or molded pulp, designed to suspend garments for display, storage, or transport while preserving textile structure and minimizing creasing. Plastic hangers dominate unit volume due to low per-unit cost and color customization for retail branding, though this segment faces margin compression from resin price volatility and extended producer responsibility fees in jurisdictions with packaging levies. Wooden hangers command premium positioning in hotel and boutique apparel applications where tactile quality and FSC chain-of-custody certification support brand storytelling and per-unit pricing power.
FDA regulations govern food-contact recycled content in molded pulp hangers entering U.S. retail supply chains, while ECHA REACH restrictions on phthalate plasticizers constrain additive formulations in European-sold polymer hangers. California's SB 54 and the EU Packaging and Packaging Waste Regulation both mandate recycled-content thresholds and end-of-life collection infrastructure, forcing brands to requalify suppliers against compliance timelines. Stakeholders must monitor evolving state-level extended producer responsibility enactments and polymer traceability requirements to avoid supply disqualification.
Market Dynamics
Extended producer responsibility laws are forcing apparel brands to requalify hanger suppliers against recycled-content thresholds and circularity certification timelines, compressing procurement cycles and fragmenting vendor pools.
Growth Catalysts
- California SB 54 compliance mandates:Apparel retailers must certify supply chain circularity for packaging and display accessories, accelerating demand for rPET and FSC-certified wooden alternatives.
- EU Green Deal packaging waste targets:National recycling quotas and biodegradable material incentives are expanding procurement specifications across European department store chains.
- Zhejiang manufacturing cluster scale:Concentrated injection molding capacity enables rapid color customization and volume responsiveness for seasonal fashion launches.
Market Restraints
- Resin price volatility:Virgin and recycled polymer input costs fluctuate with crude oil and rPET flake availability, compressing margins on plastic hanger lines.
- Single-source geography risk:China's dominance in wire forming and plastic injection molding creates vulnerability to port congestion, energy rationing, or trade policy shifts.
- REACH phthalate restrictions:ECHA limitations on plasticizer formulations constrain additive options for European-sold polymer hangers, raising reformulation costs.
Strategic Opportunities
- India apparel retail expansion:Domestic fashion chains and quick-commerce platforms remain underpenetrated by certified sustainable hanger suppliers, creating first-mover positioning.
- Molded pulp food-contact applications:FDA-compliant fiber-based hangers are converging with grocery and mass-market retail private-label programs seeking plastic elimination.
- Direct-to-brand digital procurement:B2B platforms enabling specification upload, certification verification, and transparent carbon accounting are displacing traditional distributor relationships.
Industry Challenges
- Auditor capacity constraints:FSC chain-of-custody and rPET mass-balance certification backlogs delay supplier qualification, extending go-to-market timelines for sustainable lines.
- Legacy ERP integration friction:Real-time carbon accounting and circularity tracking modules require middleware development that mid-tier manufacturers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hangers Market |
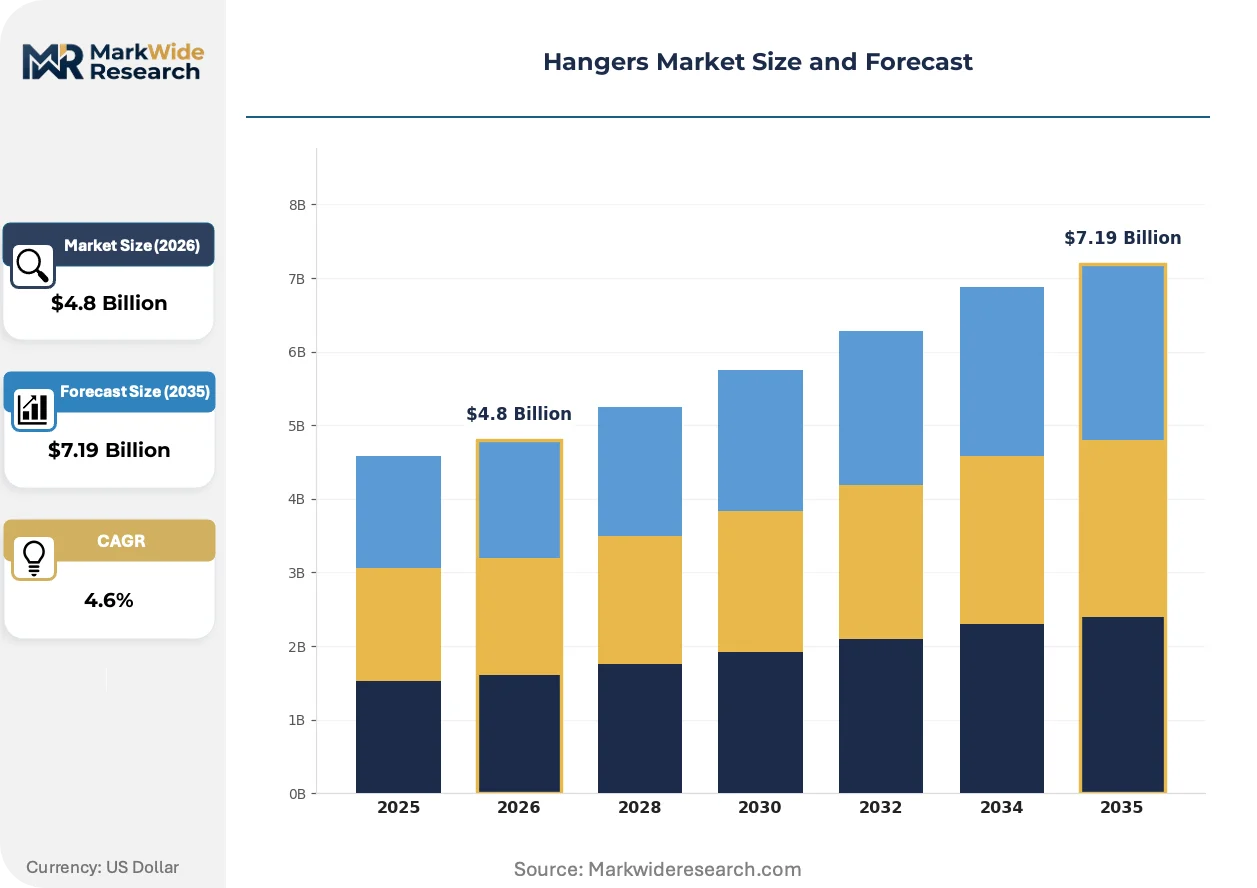
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Plastic, Metal, Wooden, Velvet Design: Standard, Clip, Children's, Swivel End User: Retail, Residential, Commercial, Hotels Application: Clothing, Accessories, Footwear, Others |
| Companies Covered | National Hanger Company, Henry Hanger Company, Mainetti Group, Sourcing Solutions International, American Hanger and Fixture Corporation, MAWA GmbH, Eisho Co., Ltd., Braiform (Tam Hangers), M & B Hangers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hangers Market Shifts & Advancements
Material traceability systems and automated molding technologies are compressing production lead times while regulatory pressure accelerates format substitution away from virgin plastic and wire constructions.
Near-infrared sorting and blockchain-based mass-balance verification is converging with rPET flake processing to enable closed-loop hanger production with auditable recycled-content claims. Tier-one apparel brands are mandating these systems for supplier qualification. The technology is converging with procurement specifications to create tiered supplier pools based on verification depth rather than unit cost alone.
REACH restrictions on phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are constraining additive formulations and mandating collection infrastructure investments. European-sold polymer hangers now face reformulation timelines and end-of-life fee structures that virgin-wire alternatives avoid. Boutique and hotel segments are responding by accelerating FSC-certified wooden hanger adoption to preempt compliance complexity.
Buyer concentration among omnichannel apparel retailers is compressing switching cycles and unbundling after-sales service from product supply. Large chains now demand dedicated inventory positions, same-day specification changes, and take-back programs as standard terms. This pattern is most visible in Germany and France where centralized procurement functions have eliminated regional distributor tiers.
Hangers Market Segmentation
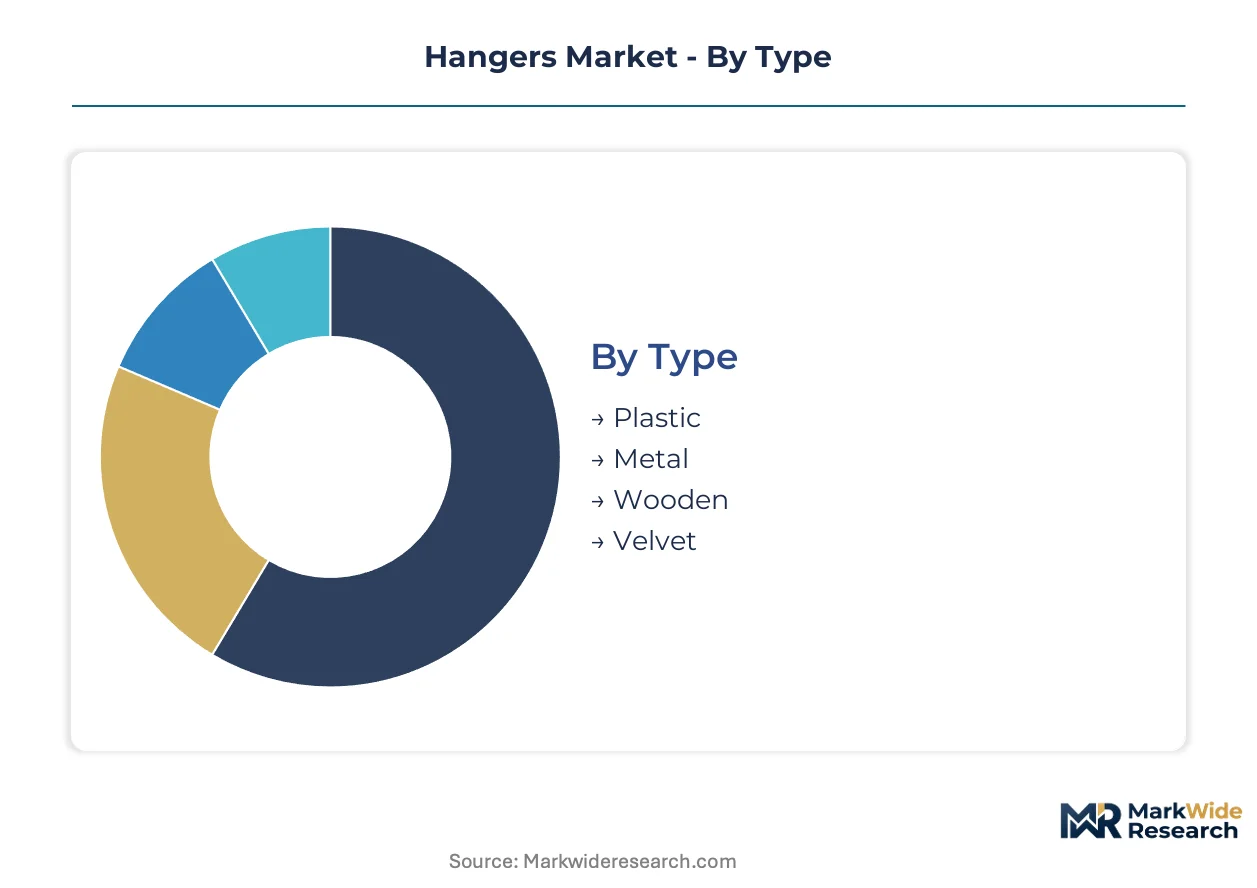
Hanger procurement specifications diverge sharply across retail, hospitality, and residential channels, with material composition and design format determining compliance eligibility and unit economics. Understanding these segment boundaries enables suppliers to align certification investments with buyer procurement workflows.
Type:
Material chemistry dictates circularity compliance thresholds and end-of-life fee exposure under extended producer responsibility frameworks.
- Plastic:Injection-molded polymer dominates unit volume through low per-unit cost and color-matching capability for retail branding. Resin price volatility and California SB 54 compliance mandates are compressing margins and accelerating rPET qualification requirements across U.S. apparel chains.
- Metal:Wire-formed steel and aluminum constructions retain cost advantage in dry-cleaning and rental apparel logistics. China's Zhejiang province concentrates wire drawing and coating capacity, creating single-source geography risk for North American and European buyers.
- Wooden:FSC-certified hardwood commands premium positioning in boutique and hotel applications where tactile quality supports brand storytelling.
- Velvet:Flocked polymer coatings reduce slippage for delicate garments in specialty retail and residential closet systems.
Plastic leads on scale; wooden leads on momentum.
Design:
Functional geometry determines inventory velocity and seasonal responsiveness for fashion retail supply chains.
- Standard:Contoured shoulder form supports baseline apparel display across mass-market and mid-tier retail. Zhejiang molding clusters enable rapid color changeovers for seasonal collection launches.
- Clip:Adjustable gripping mechanisms accommodate pants, skirts, and coordinated sets in unified merchandising displays. EU Green Deal packaging targets are expanding clip-hanger demand as retailers consolidate garment presentation formats.
- Children's:Scaled-down proportions match juvenile apparel dimensions in specialty retail and direct-to-consumer subscription boxes.
- Swivel:Rotating hook hardware facilitates dynamic display configurations in high-traffic retail environments.
Standard formats dominate procurement volume; clip designs are climbing the fastest.
End User:
Buyer concentration and specification authority vary dramatically across channel types, reshaping vendor qualification requirements.
- Retail:Omnichannel apparel chains and department stores drive bulk procurement with mandated recycled-content thresholds and take-back program requirements. Germany and France have eliminated regional distributor tiers through centralized procurement functions.
- Residential:Mass-market and premium closet system sales through home improvement retailers and direct-to-consumer platforms. California SB 54 circularity mandates are beginning to penetrate residential channel specifications.
- Commercial:Uniform services, costume rental operations, and theatrical wardrobe management prioritize durability and traceability over aesthetic customization.
- Hotels:Boutique and luxury hospitality segments are accelerating FSC-certified wooden hanger adoption to preempt EU packaging compliance complexity and support sustainability narrative.
Retail commands procurement scale; hotels show steepest expansion trajectory.
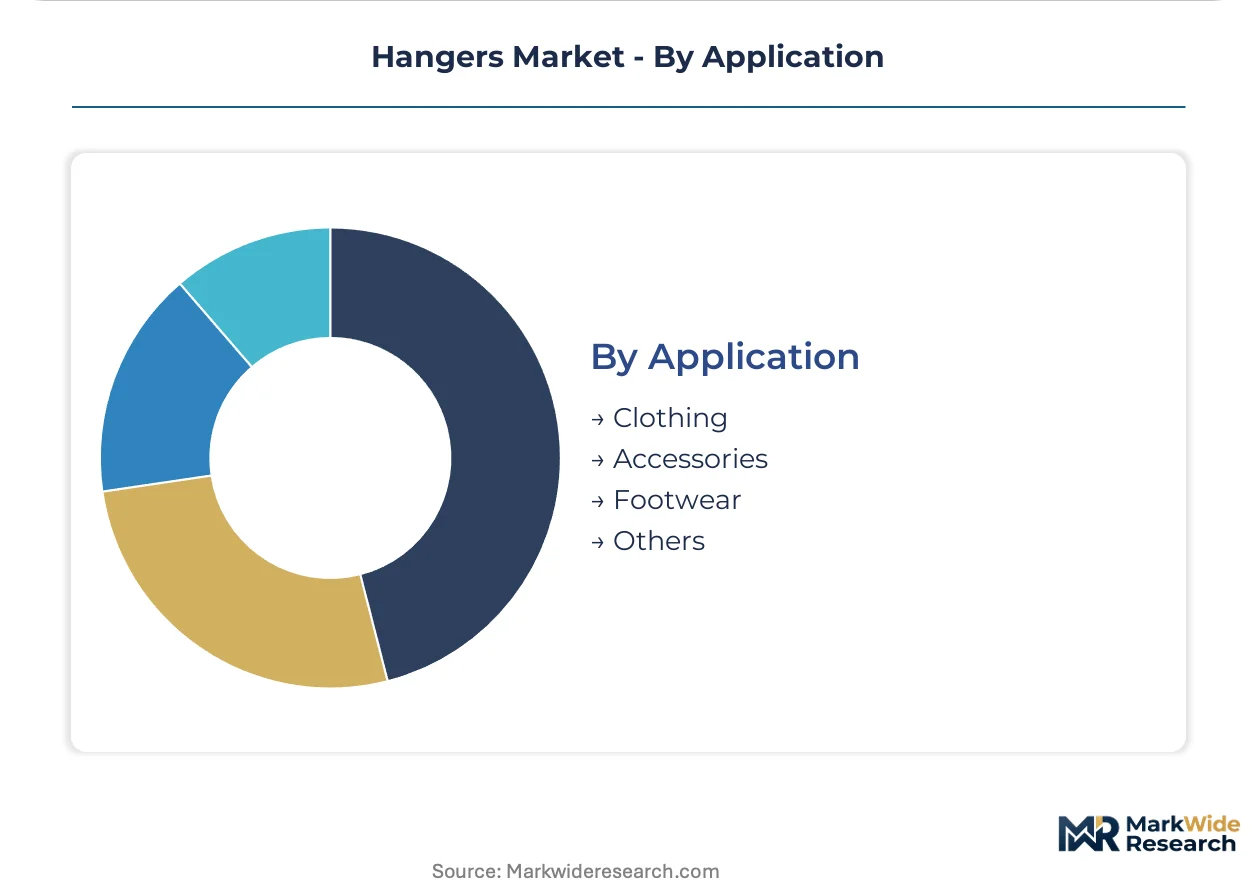
Application:
Garment category determines load-bearing requirements and surface protection specifications for hanger selection.
- Clothing:Shirts, dresses, coats, and suiting represent core demand volume across all end-user channels. REACH phthalate restrictions constrain polymer formulations for European-sold clothing hangers.
- Accessories:Belts, scarves, and jewelry require specialized hook and bar configurations in specialty retail environments.
- Footwear:Suspended display and storage formats for athletic and fashion shoes in retail and residential settings.
- Others:Niche applications including textile art, archival preservation, and industrial protective equipment.
Clothing anchors absolute demand; accessories are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hanger manufacturing originated in wire-forming workshops across the American Midwest during the early twentieth century, then migrated to injection molding clusters in post-war Europe and Asia. Today's production geography reflects this layered industrial history, with regulatory pressure now reshaping regional competitive positions.
United States
Department store chains and fast-fashion retailers drive specification changes toward recycled-plastic and FSC-certified wooden formats. California's SB 54 extended producer responsibility law mandates circularity certification for packaging and display accessories, forcing brands to requalify suppliers against compliance timelines. Domestic manufacturers in South Carolina and Georgia leverage regional molding capacity to serve East Coast retail distribution centers.
Germany
Centralized procurement functions at omnichannel apparel chains have eliminated regional distributor tiers, compressing vendor qualification cycles. ECHA REACH restrictions on phthalate plasticizers constrain additive formulations for polymer hangers, raising reformulation costs. The Rhine-Ruhr industrial corridor hosts specialized molding operations serving private-label programs for mass-market retailers.
China
Zhejiang province concentrates global wire forming and plastic injection molding capacity, enabling rapid color customization for seasonal fashion launches. Dual carbon goals under MEE oversight are pressuring manufacturers to shift energy sources and document carbon intensity. Ningbo and Wenzhou anchor export-oriented production for North American and European buyers.
Italy
Boutique fashion houses and luxury hospitality segments accelerate FSC-certified wooden hanger adoption to support brand storytelling and preempt EU packaging compliance complexity. EU Green Deal packaging waste targets expand procurement specifications for biodegradable materials. Tuscany and Lombardy host specialized wood finishing operations with chain-of-custody certification.
India
Domestic apparel retail chains and quick-commerce platforms remain underpenetrated by certified sustainable hanger suppliers, creating first-mover positioning opportunities. BIS standards for recycled content are beginning to shape procurement specifications for organized retail. Maharashtra and Gujarat host emerging injection molding capacity serving both domestic and export markets.
Hangers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers and specification houses across the hanger market. The vendor base separates into three tiers: integrated manufacturers with captive resin processing and molding operations; regional fabricators serving single-country retail chains; and trading houses that source from Zhejiang clusters for private-label programs. Dominant competitive moves include geographic expansion into underpenetrated retail markets and portfolio diversification into certified sustainable materials to meet EPR compliance timelines.
Among vertically integrated specialists, Mainetti Group exemplifies the scale-driven archetype with upstream control over rPET flake processing and regional molding plants. National Hanger Company and Henry Hanger Company represent the domestic-manufacturing archetype, leveraging regional footprint to supply major department stores with certified recycled-plastic lines. MAWA GmbH occupies a position within the European premium segment, while Eisho Co., Ltd. and Braiform anchor the Asia-Pacific supply base for global retail chains.
| Leading Market Players |
|---|
| National Hanger Company |
| Henry Hanger Company |
| Mainetti Group |
| Sourcing Solutions International |
| American Hanger and Fixture Corporation |
| MAWA GmbH |
| Eisho Co., Ltd. |
| Braiform (Tam Hangers) |
| M & B Hangers |
| Others |
Supply & Pricing Matrix
Omnichannel apparel retailers in Germany and France command consolidated procurement functions that extract volume-based discounts and compress payment terms, anchoring hanger pricing in contract-based long-term offtake structures rather than spot markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified wooden hangers from rPET lines and virgin-plastic commodity grades. Price differentiation hinges on certification tier and volume scale, with boutique hotel chains absorbing premium positioning while mass-market retailers squeeze standard-tier margins. Cost compression in virgin-plastic grades is intensifying because resin price volatility and California SB 54 compliance fees erode supplier margins. Mass-market retail chains exhibit highest price sensitivity; luxury hospitality segments demonstrate lowest.
Supply Chain Analysis
FSC chain-of-custody and rPET mass-balance certification backlogs now gate supplier qualification timelines, forcing buyers to pre-qualify vendors months ahead of seasonal launches. Manufacturing concentrates in China, Italy, and Vietnam, with Zhejiang province anchoring global injection molding capacity. Raw material flows draw from petrochemical resin, recycled PET flake, and FSC-certified hardwood. Single-source geography risk in China's wire-forming clusters threatens supply continuity during port congestion or energy rationing. Distribution runs through centralized procurement functions at major retail chains, displacing regional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where California SB 54 and EU Packaging and Packaging Waste Regulation mandates create accelerating demand for certified circular supply chains.
For Market Incumbents: To counter margin compression from resin volatility and extended producer responsibility fees, backward integration into rPET flake processing secures input cost stability. Captive molding capacity in South Carolina or Georgia insulates against Zhejiang supply disruptions and satisfies domestic content preferences among East Coast retail distribution centers. For New Entrants and Emerging Players: Capture first-mover positioning in India's underpenetrated organized retail sector where BIS recycled-content standards are beginning to shape procurement specifications. Quick-commerce platforms and domestic fashion chains lack certified sustainable hanger suppliers, creating entry pathways through digital B2B procurement platforms with transparent carbon accounting modules. For Investors and Strategic Acquirers: Apparel retail chains with centralized procurement functions are the most active acquirer in this space, seeking captive supply security ahead of compliance deadlines. Vertically integrated manufacturers with upstream rPET processing and regional molding footprints represent prime acquisition targets. Monitor auditor capacity backlogs for FSC and mass-balance certification as the inflection signal—clearing delays indicate supplier qualification velocity and sustainable line rollout potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Processing | Captive flake supply insulates Mainetti Group from resin price volatility and EPR fee exposure. |
| Regional Molding Footprint Expansion | Domestic plants in South Carolina and Georgia position National Hanger Company for California SB 54 compliance timelines. |
| FSC Chain-of-Custody Certification Investment | Wooden hanger lines from Tuscan and Lombardy operations preempt EU packaging waste regulation complexity for Italian fashion houses. |
| Digital B2B Procurement Platform Launch | Specification upload and carbon accounting modules displace traditional distributor relationships in German and French centralized procurement functions. |
| Molded Pulp Food-Contact Line Development | FDA-compliant fiber-based formats converge with grocery private-label programs seeking plastic elimination in U.S. mass-market retail. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with apparel procurement directors, sustainability compliance officers, injection molding plant managers, and FSC certification auditors alongside secondary validation. Trade data from customs records, SEC filings of listed suppliers, ECHA REACH restriction updates, and California SB 54 implementation guidance informed volume and pricing benchmarks. Bottom-up hanger production estimates triangulated against top-down apparel retail display accessory spending.
Historical reference periods anchored volume and value trajectories across the projection horizon, with analytical frameworks modeling material type, design format, end-user channel, and application segment. CAGRs derived from segment-level growth rate convergence and input cost elasticity assumptions. Forecast inputs incorporated rPET flake availability curves, EPR fee schedule implementations, and auditor capacity expansion timelines.
Underlying measurement precision varies by segment; plastic and metal hanger volumes carry tighter precision than emerging molded pulp categories due to established trade reporting. Forecasts reflect assumptions about regulatory enforcement intensity and certification backlog resolution. A model refresh is warranted upon material change in extended producer responsibility enactment timelines or auditor capacity allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bagless Vacuum Cleaner Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Dishwashing Products Market
Household Items
Portable Iron Market
Household Items
Domestic Sauna Heaters Market
Household Items
Dosage Spoon Market
Household Items
Europe Digital Showers Market
Household Items
Acrylic Aquarium Market
Household Items
Powered Lawn Mowers Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Smart Air Purifier Market
Household Items
Air Care Market
Household Items
Enameled Cookware Market
Household Items
Cast Iron Cookware Market
Household Items
Kitchen Towel Market
Household Items
Middle East and Africa Air Purifier Market