
 Mosquito Trap Market | 2026-2036
Mosquito Trap Market Size, Share, and Industry Trends Forecast 2026-2036
Mosquito Trap Market Analysis
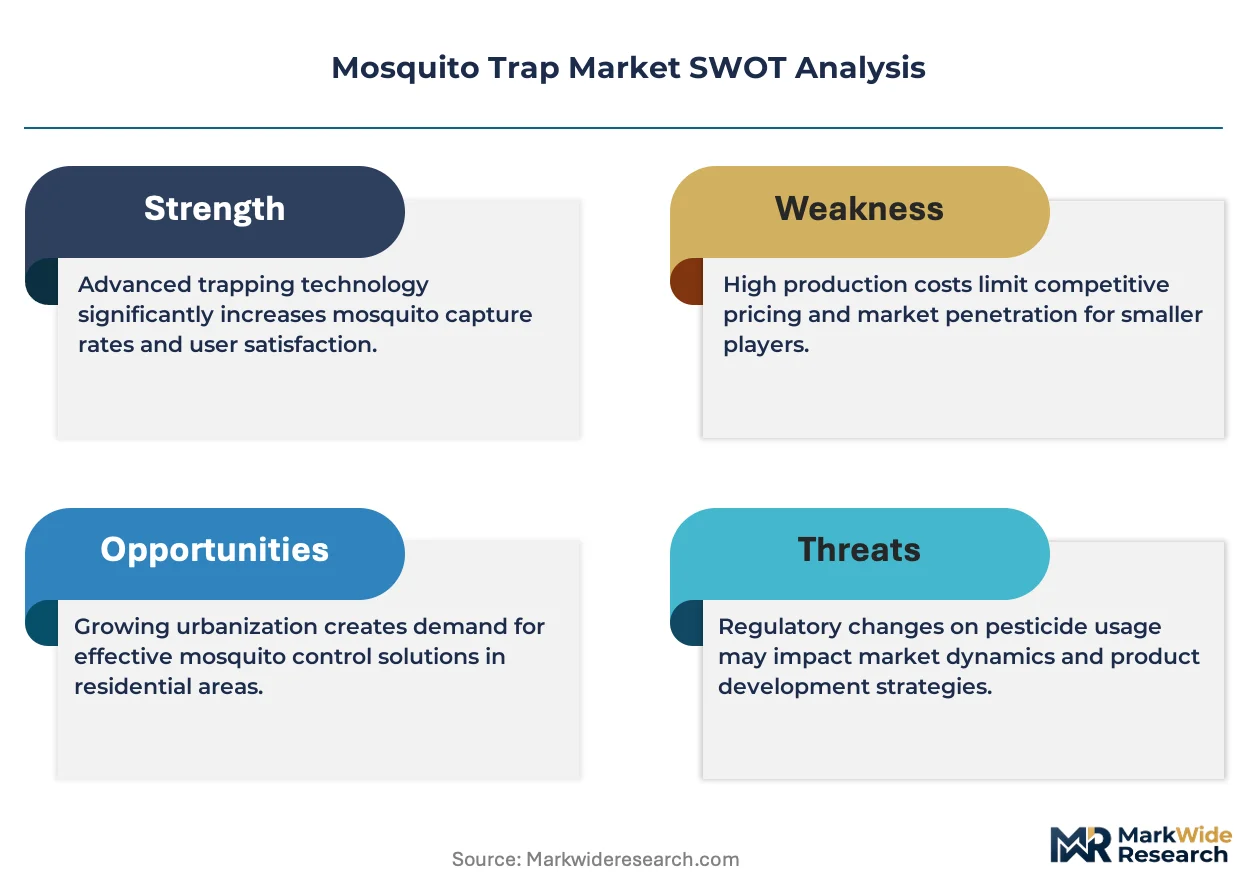
Subscription-based filter replacement and seasonal maintenance programs is recalibrating how manufacturers monetize hardware deployments. Biogents AG leverages its German engineering heritage to sustain premium positioning in CO2 trap technology. DynaTrap anchors North American retail channels through mass-market distribution partnerships. Rentokil Initial plc competes across integrated pest management contracts by bundling trap monitoring with service technician visits.
A mosquito trap is an electromechanical or passive capture device engineered with UV-LED arrays, fan suction mechanisms, or adhesive surfaces rated for specific insect size exclusion, designed to reduce vector populations in controlled perimeters. The primary commercial purpose centers on interrupting disease transmission cycles while minimizing pesticide application intensity. CO2 traps command the highest unit economics in agricultural and public health end user segments where precision targeting justifies operational expenditure. Light-based technology dominates residential application volumes due to lower consumer price thresholds and plug-and-play deployment. Chemical attractants represent the fastest-growing technology category as synthetic lure formulations improve species specificity beyond broad-spectrum UV approaches.
The EPA regulates pesticide device claims under FIFRA, requiring efficacy substantiation that shapes product labeling and interstate commerce eligibility. ISO 23668 establishes performance benchmarking for mosquito trapping equipment, influencing procurement specifications by WHO-affiliated vector control programs. The EU Biocidal Products Regulation constrains chemical attractant compositions entering European markets, compelling reformulation investments from manufacturers serving that geography. Stakeholders must monitor evolving resistance patterns in target vector species and align R&D portfolios with regulatory trajectories that favor non-chemical intervention modalities.
Market Dynamics
Vector control agencies are pivoting procurement toward precision-targeting systems as insecticide resistance renders broad-spectrum fogging economically unviable and environmentally contested.
Growth Catalysts
- Urban dengue containment mandates:Brazil's municipal health departments are deploying CO2-based traps in favela clusters to interrupt Aedes aegypti transmission cycles.
- FIFRA registration pathway evolution:The EPA's streamlined pesticide device claims process is accelerating interstate commerce eligibility for chemical attractant manufacturers.
- Photocatalytic oxidation maturation:Titanium dioxide coatings paired with UV-LED arrays are achieving species-specific capture rates that justify agricultural deployment economics.
Market Restraints
- CO2 cartridge supply concentration:Food-grade compressed carbon dioxide sourcing clusters among industrial gas suppliers in Germany and the United States, exposing procurement to input cost volatility.
- EU Biocidal Products Regulation compliance friction:ECHA's substance evaluation timelines extend 18-36 months for novel synthetic lures, delaying European market entry.
- Passive trap performance ceiling:Adhesive surface technologies cannot match electromechanical systems in capture efficiency, capping their addressable market to price-sensitive residential segments.
Strategic Opportunities
- Subscription filter replacement models:Seasonal maintenance programs are creating recurring revenue streams that decouple manufacturer profitability from hardware replacement cycles.
- WHO prequalification alignment:ISO 23668 certification is unlocking vector control program tenders in sub-Saharan African nations previously served by donor-funded bed net distributions.
- Smart home integration convergence:WiFi-enabled trap monitoring is unifying with residential IoT ecosystems, enabling predictive maintenance alerts and usage-based service pricing.
Industry Challenges
- Entomological expertise scarcity:Field validation of trap efficacy requires trained vector biologists, a skill set concentrated in academic and public health institutions rather than commercial R&D departments.
- Legacy mosquito coil substitution resistance:Low-cost pyrethroid coils retain consumer habit formation in Southeast Asian markets, complicating premium electromechanical trap penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosquito Trap Market |
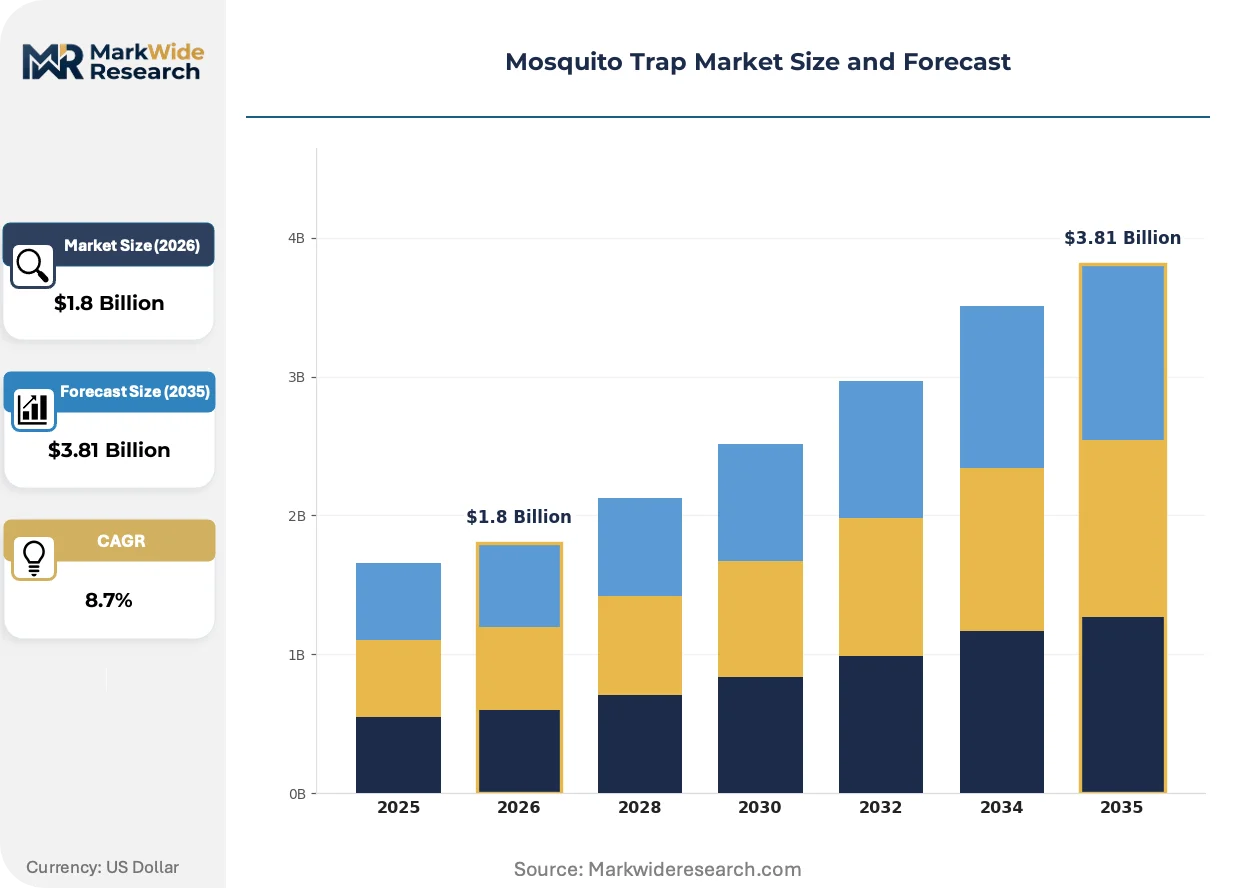
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Traps, Baited Traps, CO2 Traps, Sticky Traps End User: Residential, Commercial, Agricultural, Public Health Technology: Ultrasonic, Light-Based, Trap Design, Chemical Attractants Application: Outdoor, Indoor, Agricultural Fields, Industrial Sites |
| Companies Covered | Biogents AG, Aspectek, Woodstream Corporation, Flowtron Outdoor Products, Catchmaster, Rentokil Initial plc, DynaTrap, MosquitoNix Franchise LLC, Thermacell Repellents Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosquito Trap Market Emerging Trajectories
Hardware-software convergence is redefining competitive differentiation as connected monitoring capabilities become baseline procurement requirements rather than premium features.
Electrostatic precipitation is unifying with fan-suction mechanisms in next-generation agricultural traps. Large-scale greenhouse operators in the Netherlands are piloting these hybrid systems to reduce pollinator bycatch. This convergence is compressing the performance gap between precision CO2 systems and lower-cost UV alternatives.
REACH authorization requirements for isobutanol-based attractants are forcing reformulation investments across European supply chains. Manufacturers serving EU member states must submit full substance dossiers to ECHA by 2026 deadlines. Chemical attractant specialists are responding by accelerating biobased lure development to circumvent authorization bottlenecks.
Integrated pest management bundling is displacing standalone trap sales in commercial contracts. Facility management providers across Australian urban centers are consolidating vendor relationships, demanding trap monitoring dashboards alongside service technician dispatch protocols. This consolidation favors providers with captive service networks over pure hardware manufacturers.
Mosquito Trap Market Segmentation
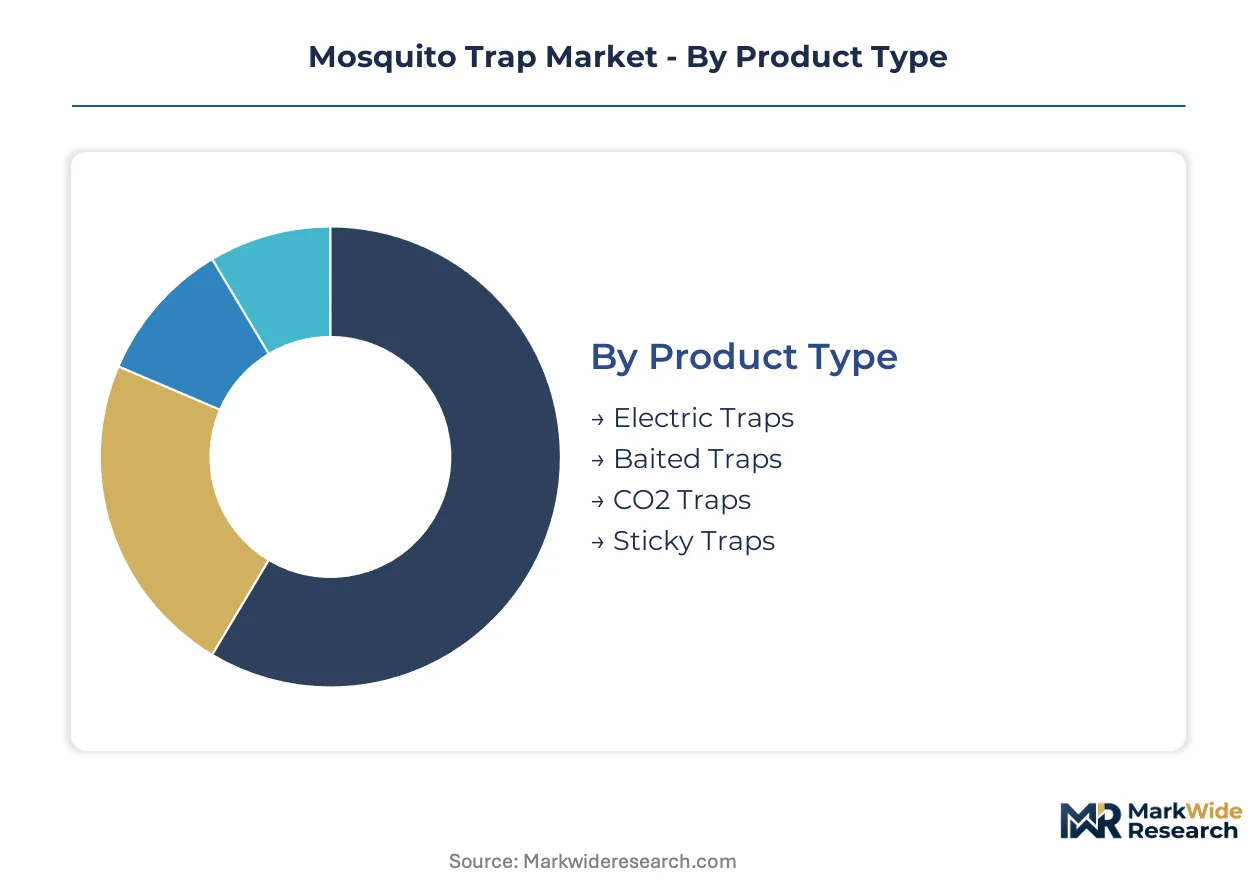
Mosquito trap manufacturers calibrate R&D investments and distribution strategies against distinct performance requirements across product architectures, deployment environments, and vector control objectives. Segmentation clarity enables suppliers to align pricing architecture with procurement budgets that vary by an order of magnitude between residential consumers and public health agencies.
Product Type:
Standardized plug-and-play units dominate mass retail channels while precision-engineered systems command agricultural and institutional tenders requiring field-validated efficacy documentation.
- CO2 Traps:Precision systems deploy food-grade compressed carbon dioxide to mimic human respiration, achieving species-specific capture rates for Aedes aegypti and Anopheles vectors. Brazilian municipal health departments concentrate procurement in favela clusters where dengue containment mandates justify operational expenditure premiums.
- Electric Traps:Fan-suction electromechanical architectures paired with UV-LED arrays or photocatalytic oxidation surfaces. North American retail channels move the highest unit volumes as homeowners prioritize plug-and-play deployment for backyard perimeter protection.
- Baited Traps:Synthetic lure formulations targeting specific mosquito species through olfactory pathway activation. REACH authorization timelines for isobutanol-based attractants constrain European supply chain configurations.
- Sticky Traps:Passive adhesive surface technologies rated for insect size exclusion. Price-sensitive residential segments in Southeast Asia sustain demand despite capture efficiency limitations against electromechanical alternatives.
Leading the category by volume: Electric Traps. Expanding most quickly: CO2 Traps.
End User:
Procurement sophistication and total cost of ownership calculations diverge sharply between individual consumers and institutional vector control programs.
- Public Health:Government vector control agencies deploy precision-targeting systems as insecticide resistance renders broad-spectrum fogging economically unviable. WHO-affiliated programs specify ISO 23668 certification for equipment tenders.
- Residential:Individual homeowners prioritize lower price thresholds and aesthetic integration with outdoor living spaces. Subscription filter replacement models are recalibrating manufacturer profitability through recurring revenue streams.
- Commercial:Facility management providers demand trap monitoring dashboards alongside service technician dispatch protocols. Australian urban centers exhibit vendor consolidation toward integrated pest management bundling.
- Agricultural:Large-scale greenhouse operators pilot hybrid electrostatic precipitation systems to reduce pollinator bycatch. The Netherlands leads precision agriculture adoption for vector management in controlled-environment food production.
Capturing highest unit margins: Public Health. Scaling fastest through subscription attachment: Residential.
Technology:
Maturity curves separate established illumination approaches from emerging synthetic lure formulations facing regulatory evaluation bottlenecks.
- Chemical Attractants:Synthetic lure development accelerates biobased alternatives to circumvent ECHA authorization delays. Species specificity improvements justify premium positioning against broad-spectrum UV approaches.
- Light-Based:UV-LED array technologies paired with titanium dioxide coatings achieve photocatalytic oxidation for CO2 generation. Dutch greenhouse operators validate agricultural deployment economics through reduced chemical intervention.
- Trap Design:Physical capture architectures encompassing fan suction, adhesive surfaces, and electrostatic precipitation. Hybrid configurations compress performance gaps between precision CO2 systems and lower-cost alternatives.
- Ultrasonic:High-frequency sound emission devices with limited peer-reviewed efficacy documentation. Consumer habit formation sustains niche positioning despite entomological skepticism.
Highest installed base: Light-Based. Steepest expansion trajectory: Chemical Attractants.
Application:
Environmental exposure conditions and vector density patterns dictate hardware durability specifications and maintenance interval requirements.
- Outdoor:Residential perimeter installations represent the primary adoption vector as homeowners prioritize vector-borne disease prevention. Weatherproofing ratings and battery autonomy specifications differentiate competitive offerings.
- Agricultural Fields:Large-scale deployment across row crops and protected cultivation requires ruggedized enclosures and extended-range CO2 cartridge capacity. Precision targeting justifies higher capital expenditure through reduced pesticide application intensity.
- Indoor:Bedroom and living space deployment emphasizes noise suppression and aesthetic minimalism. Lower capture area requirements enable compact form factors with reduced power consumption.
- Industrial Sites:Manufacturing and logistics facilities integrate trap monitoring with building management systems. WiFi-enabled predictive maintenance alerts unify with residential IoT ecosystem convergence.
Driving hardware unit volumes: Outdoor. Concentrating precision technology investment: Agricultural Fields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States where precision CO2 cartridge fabrication and electromechanical engineering capabilities cluster. Consumption spreads across tropical and subtropical zones where vector-borne disease burdens drive procurement intensity.
United States
Residential backyard installations and municipal vector control programs sustain dual demand channels. The EPA's FIFRA registration pathway evolution accelerates interstate commerce eligibility for chemical attractant systems. Dallas-Fort Worth metroplex municipalities deploy precision-targeting traps as insecticide resistance renders broad-spectrum fogging economically unviable.
Brazil
Urban dengue containment mandates concentrate procurement in favela clusters and municipal health departments. ANVISA coordinates with public health agencies on CO2-based trap deployment standards for Aedes aegypti suppression. São Paulo state health departments lead national adoption through integrated vector management tenders.
Germany
Food-grade compressed carbon dioxide sourcing clusters among industrial gas suppliers serving precision trap manufacturers. ECHA's REACH authorization timelines for isobutanol-based attractants extend 18-36 months, delaying novel synthetic lure market entry. Bavarian engineering firms anchor CO2 trap technology development for agricultural and public health export markets.
Australia
Facility management providers consolidate vendor relationships toward integrated pest management bundling across urban centers. The country's national pesticide regulator evaluates trap efficacy claims under state-level agricultural chemical frameworks. Sydney and Melbourne metropolitan councils pilot WiFi-enabled trap monitoring with building management system integration.
Netherlands
Large-scale greenhouse operators pilot hybrid electrostatic precipitation systems to reduce pollinator bycatch in controlled-environment food production. The EU Biocidal Products Regulation constrains chemical attractant compositions entering European markets. Wageningen agricultural research clusters validate photocatalytic oxidation deployment economics for precision agriculture vector management.
Mosquito Trap Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the mosquito trap industry. The vendor base separates into three strategic tiers: precision-engineered CO2 system specialists, mass-market electromechanical manufacturers, and integrated pest management service bundlers. Consolidation pressures favor providers with captive service networks over pure hardware manufacturers. Dominant competitive moves include subscription-based filter replacement model adoption and ISO 23668 certification alignment for WHO-affiliated tender access.
Within the precision-engineered tier, Biogents AG occupies a position anchored in German engineering heritage for CO2 trap technology. DynaTrap exemplifies mass-market retail channel penetration through North American distribution partnerships. Rentokil Initial plc represents the integrated service bundling archetype, competing across pest management contracts that combine trap monitoring with technician dispatch protocols.
| Leading Market Players |
|---|
| Biogents AG |
| Aspectek |
| Woodstream Corporation |
| Flowtron Outdoor Products |
| Catchmaster |
| Rentokil Initial plc |
| DynaTrap |
| MosquitoNix Franchise LLC |
| Thermacell Repellents Inc. |
| Others |
Supply Flow & Price Mechanics
Food-grade compressed carbon dioxide price indices cascade through mosquito trap manufacturing tiers, compressing margins in precision CO2 systems while UV-LED electromechanical alternatives capture price-sensitive residential volume through component standardization.
Pricing Analysis
Margin tightening in premium CO2 trap tiers reflects cartridge input cost volatility and concentrated industrial gas supplier bargaining power. Three-tier pricing structure across precision-engineered, mid-range electromechanical, and economy adhesive systems stratifies by ISO 23668 certification status and field-validated efficacy documentation. Cost-down pressure on economy sticky traps accelerates because Southeast Asian pyrethroid coil substitution resistance caps premium penetration. Public health agencies exhibit lowest price sensitivity due to operational expenditure justification through disease burden reduction, while individual homeowners prioritize plug-and-play affordability thresholds.
Supply Chain Analysis
ANVISA domestic-content guidelines for Brazilian municipal procurement are reshaping final-assembly localization requirements for CO2 trap manufacturers serving Latin American vector control programs. Component sourcing concentrates in Germany for precision-engineered CO2 systems, the United States for UV-LED electromechanical assemblies, and China for adhesive surface materials. Raw material dependencies center on titanium dioxide coatings for photocatalytic oxidation, food-grade compressed carbon dioxide cartridges, and synthetic isobutanol-based attractant formulations. Single-source vulnerability in industrial gas supply exposes manufacturers to input cost volatility. Distribution runs through North American mass retail channels for residential electromechanical units and WHO-affiliated tender networks for precision public health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into CO2 cartridge fabrication and captive service network expansion define the vertical-integration race reshaping competitive positioning in mosquito trap manufacturing.
For Market Incumbents: Lock in ISO 23668 certification alignment to defend WHO-affiliated tender access against emerging precision-engineered competitors from German engineering clusters. Deepen backward integration into food-grade compressed carbon dioxide sourcing to offset industrial gas supplier concentration risk. Expand subscription filter replacement model penetration to decouple profitability from hardware replacement cycles. For New Entrants and Emerging Players: Begin with WiFi-enabled trap monitoring white space in Australian facility management bundling contracts where vendor consolidation favors integrated service providers over pure hardware manufacturers. Target agricultural greenhouse operators in the Netherlands piloting hybrid electrostatic precipitation systems with biobased lure development partnerships circumventing ECHA authorization bottlenecks. Pursue direct-to-installer channel strategies bypassing mass retail margin compression. For Investors and Strategic Acquirers: The window for entry favors precision CO2 system specialists with ANVISA-registered Brazilian municipal supply relationships and established field validation protocols. Long-term viability hinges on regulatory trajectory alignment toward non-chemical intervention modalities and subscription revenue attachment rates. Monitor ECHA REACH authorization timeline compression for novel synthetic lures as inflection indicator for chemical attractant category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 23668 Certification Investment | WHO prequalification unlocks sub-Saharan African vector control tenders previously served by donor-funded bed net distributions. |
| Biobased Lure Development Partnership | ECHA REACH authorization delays for isobutanol-based attractants accelerate reformulation investment in European supply chains. |
| Subscription Filter Replacement Model | Seasonal maintenance programs create recurring revenue streams decoupling manufacturer profitability from hardware replacement cycles. |
| WiFi-Enabled Monitoring Integration | Predictive maintenance alerts unify with residential IoT ecosystems enabling usage-based service pricing in Australian urban centers. |
| Backward Integration into CO2 Cartridge Fabrication | Food-grade compressed carbon dioxide sourcing concentration in Germany and the United States exposes procurement to input cost volatility. |
Methodological Framework
Independent corroboration across vector control program procurement officers, electromechanical engineering directors at precision trap manufacturers, EPA pesticide device registration specialists, and ECHA biocidal products evaluators underwrites the qualitative findings. Primary interviews with Brazilian ANVISA coordination officials, Dutch greenhouse operations managers, and North American retail channel category buyers combined with secondary validation from EPA FIFRA registration databases, ISO 23668 certification records, and WHO vector control equipment prequalification listings. Bottom-up segment sizing and top-down market triangulation anchored the analytical framework.
Comparable-period anchoring to historical EPA registration pathway evolution and ECHA authorization timeline patterns shaped the projection horizon across the analysis window. Segmentation dimensions modeled encompass product architecture precision tiers, end-user procurement sophistication levels, technology maturity curves, and application environmental exposure conditions. CAGRs derived from unit shipment trajectories and average selling price movements incorporating CO2 cartridge replacement frequency assumptions and subscription attachment rate progression in residential channels.
Underlying measurement precision varies by segment; public health agency tender volumes and ISO 23668 certification counts carry tighter precision than consumer retail sell-through estimates. Forecasts reflect assumptions around regulatory trajectory acceleration, insecticide resistance progression patterns, and smart home ecosystem convergence velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Japan Faucets Market
Household Items
Portable Showers Market
Household Items
Toilet Deodorant Market
Household Items
Global Electric Scissors Market
Household Items
Mirror Holder Market
Household Items
Soap Tablet Market
Household Items
Beach Towel Market
Household Items
Water Purifier Bottle Market
Household Items
North America Liquid Hand Soap Market
Household Items
China Cookware Market
Household Items
North America Glassware Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Wax Removal Aids Market
Household Items
Household Scales Market
Household Items
Nebulizing Diffuser Market
Household Items
Shoe Shine Machine Market