
 Stainless Steel Water Bottles Market | 2026-2036
Stainless Steel Water Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Water Bottles Market Analytics
Asset-light direct-to-consumer leasing and subscription refill models are fragmenting capital requirements across the stainless steel water bottle supply chain. Tiger Corporation leverages vertical integration in Japanese manufacturing to sustain premium positioning. Thermos L.L.C. anchors North American distribution through deep sporting goods channel relationships. Zojirushi Corporation differentiates through advanced vacuum insulation technology leadership.
A stainless steel water bottle is a reusable beverage container fabricated from food-grade austenitic steel alloys, typically 18/8 chromium-nickel composition, employing electropolishing and vacuum insulation fabrication to maintain liquid temperature and resist corrosion. Its primary commercial purpose is to replace single-use plastic bottles in hydration applications across consumer, institutional, and outdoor recreation settings. Insulated product types command the dominant margin pool due to vacuum-sealed construction complexity and premium pricing power. The 32 oz and 40 oz size segments capture accelerating demand from fitness enthusiasts and extended outdoor activity users. Online retailers represent the fastest-growing distribution channel as brand-owned digital storefronts displace traditional wholesale dependency.
The FDA governs food-contact material safety for stainless steel bottles sold in the United States, while the EPA enforces restrictions on heavy metal content through toxic substance regulations. REACH compliance within Europe mandates rigorous chemical safety documentation for chromium and nickel alloy components, elevating compliance costs for exporters. China's SAMR enforces GB standards for food-contact metals, shaping manufacturing specifications for the dominant production base. Stakeholders must monitor evolving extended producer responsibility frameworks and plastic reduction mandates that could accelerate stainless steel substitution or impose new circularity obligations on material recovery.
Market Dynamics
Regulatory bans on Bisphenol A under REACH and US state-level prohibitions are structurally accelerating substitution from polycarbonate alternatives, while China's concentrated stainless steel manufacturing base shapes global supply availability and cost curves.
Growth Catalysts
- Fitness enthusiast demand:Gym culture expansion and outdoor recreation participation are pulling 32 oz and 40 oz insulated bottle formats into mainstream hydration routines.
- REACH chemical safety mandates:European restrictions on bisphenol A and phthalates in food-contact materials are eliminating competing polymer bottle options from shelf space.
- Electropolishing process advancement:Surface treatment refinements in Chinese manufacturing clusters are improving corrosion resistance and extending product replacement cycles.
Market Restraints
- Nickel price volatility:Austenitic 18/8 chromium-nickel alloy input costs fluctuate with Indonesian and Philippine mining supply disruptions.
- Guangdong-Zhejiang supply concentration:Over 70% of global fabrication capacity sits within 200 kilometers of Shenzhen, creating single-point failure exposure.
- Vacuum insulation technical ceiling:Heat retention performance gains have plateaued against thermodynamic limits, constraining premium pricing justification.
Strategic Opportunities
- Indian domestic health consciousness:Rising middle-class awareness of plastic contamination risks in tier-2 and tier-3 cities offers first-mover positioning.
- Brand-owned digital storefronts:Direct-to-consumer channels are bypassing traditional sporting goods wholesale dependency and capturing margin expansion.
- Extended producer responsibility frameworks:EU circular economy mandates on material recovery are creating closed-loop refurbishment service revenue streams.
Industry Challenges
- Vacuum seal technician scarcity:Skilled operators for double-wall evacuation processes command wage premiums that compress assembly line margins.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and GB standard compliance testing extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Water Bottles Market |
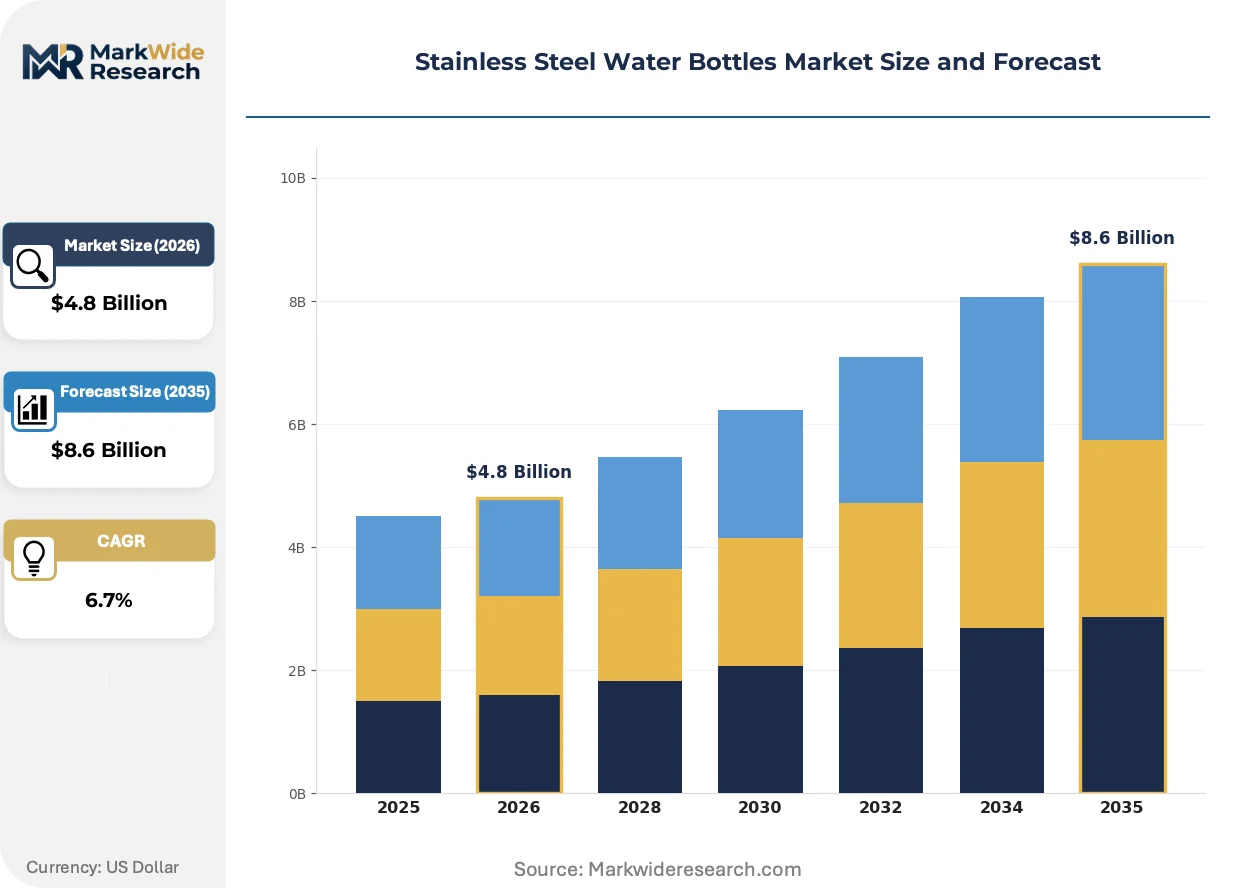
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated, Non-Insulated, Sports, Custom End User: Fitness Enthusiasts, Travelers, Students, Professionals Size: 16 oz, 24 oz, 32 oz, 40 oz Distribution Channel: Online Retailers, Sporting Goods Stores, Supermarkets, Specialty Shops |
| Companies Covered | Klean Kanteen, Inc., Tiger Corporation, Thermos L.L.C., Bulletin Brands, Inc., BRITA GmbH, Zojirushi Corporation, Sigg Switzerland AG, Cool Gear International, LLC., YETI COOLERS, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Water Bottles Market Evolving Landscape
Digital integration of supply chain tracking and consumer-facing temperature monitoring is compressing quality assurance cycles and reshaping brand trust mechanisms in premium hydration products.
Smart bottle technology embedding NFC chips and Bluetooth temperature sensors is digitizing consumption pattern analytics for fitness app partnerships. Wellness platforms and corporate wellness programs are piloting these connected formats at 15-20% price premiums. Real-time hydration tracking is digitizing the traditional water bottle from passive container to data-generating health device.
REACH SVHC candidate list expansion is forcing reformulation of decorative powder coatings and external finishes on colored bottles. ECHA's 2024-2025 substance evaluation roadmap is accelerating supplier audits for chromium VI content in electroplated accents. European importers are shifting procurement toward certified 304-grade bare stainless finishes to preempt authorization barriers.
Subscription refill and leasing models are unbundling ownership from access in institutional and corporate settings. Facility management buyers are replacing capital purchases with per-employee hydration service contracts. This procurement evolution is most visible in North American tech campus and healthcare facility deployments.
Stainless Steel Water Bottles Market Segmentation
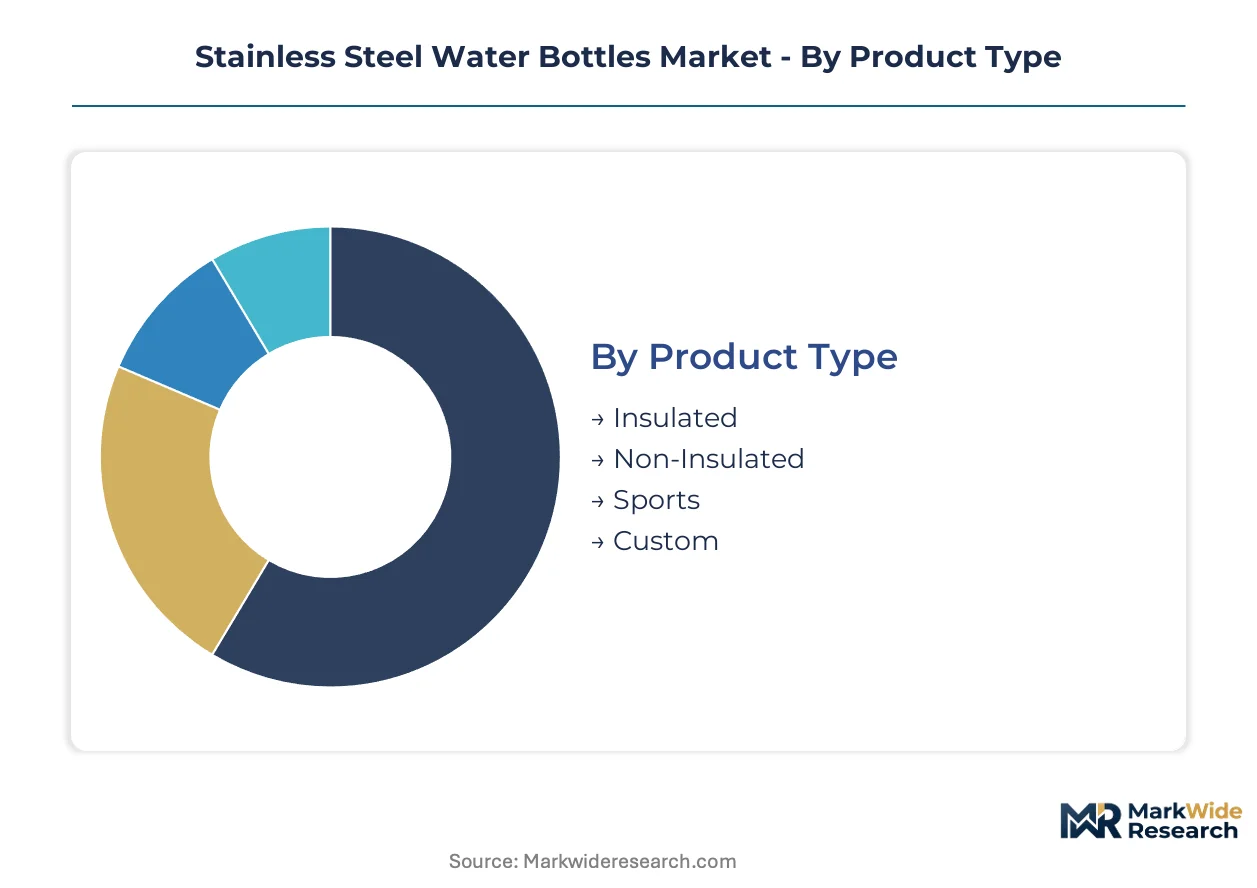
Segmentation in stainless steel water bottles reveals how vacuum insulation complexity, fitness-driven sizing preferences, and channel digitization fragment revenue pools across distinct technical and commercial boundaries. Understanding these divides exposes where margin concentrates and where substitution risk looms.
Product Type:
Mature vacuum-sealed formats dominate commercial value, while emerging smart-integrated variants test premium elasticity.
- Insulated:Double-wall vacuum construction using 304-grade austenitic steel achieves thermal retention through electropolished internal surfaces and copper-plated inner walls. Fitness enthusiasts and outdoor recreation users in China and the United States concentrate demand here, drawn by 12-24 hour temperature maintenance that justifies 3-4x pricing over basic alternatives. REACH-compliant bare finishes are displacing coated variants in European procurement.
- Non-Insulated:Single-wall 18/8 construction prioritizes weight reduction and cost efficiency for institutional bulk purchasing. Schools and corporate catering programs in India represent the strongest demand concentration, though nickel price volatility compresses tender margins.
- Sports:Ergonomic grip geometry and integrated straw lids target high-mobility use cases. Narrower diameter profiles accommodate bicycle bottle cages and treadmill holsters.
- Custom:Laser-etched branding and powder-coated Pantone matching serve corporate gifting and event merchandise channels. Extended producer responsibility mandates in Europe are elevating refurbishment service attachments.
Insulated handles the majority of throughput; Custom is the fastest mover on share.
End User:
Volume scales with institutional procurement, while margin concentrates in health-conscious individual purchasers.
- Fitness Enthusiasts:32 oz and 40 oz insulated formats dominate gym bag and hiking pack inventory, with hydration tracking app integrations emerging as a loyalty mechanism. North American sporting goods retailers and Chinese direct-to-consumer platforms capture this demand.
- Travelers:Collapsible and nesting designs address TSA liquid restrictions and luggage space constraints. Airport retail and travel gear specialists stock these formats.
- Students:Price-sensitive demand favors 16 oz and 24 oz non-insulated options with durability guarantees against drops and dents.
- Professionals:Minimalist aesthetics and desk-friendly footprints align with corporate wellness program specifications. Leasing models are penetrating tech campus deployments.
Fitness Enthusiasts handles the majority of throughput; Professionals is climbing the fastest on share.
Size:
Capacity preferences stratify across activity duration and portability trade-offs.
- 32 oz:The dominant format for gym culture and day-hiking applications, balancing hydration volume against pack weight. Chinese manufacturing clusters optimize line efficiency around this specification.
- 40 oz:Extended outdoor activity and high-output athletic use drive demand for maximum capacity without jug-scale bulk. Premium vacuum insulation commands strongest pricing power here.
- 16 oz:Compact portability suits handbag and briefcase carriage for urban commuting.
- 24 oz:Mid-range versatility serves school and office environments with moderate consumption patterns.
32 oz handles the majority of throughput; 40 oz is expanding most quickly on share.
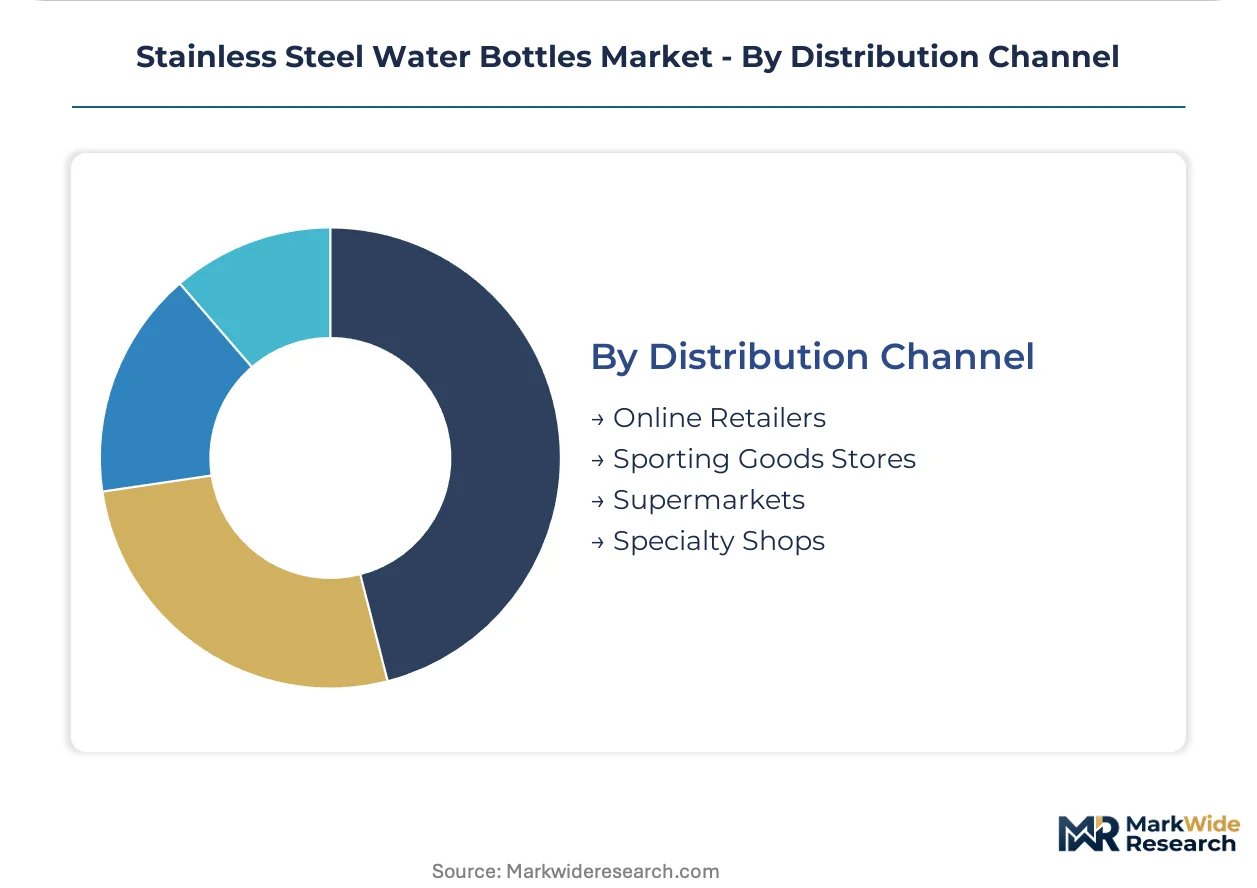
Distribution Channel:
Channel economics diverge sharply between inventory-heavy retail and asset-light digital fulfillment.
- Online Retailers:Brand-owned storefronts and marketplace presence bypass wholesale margin stacking, enabling subscription and personalization services. FDA and REACH documentation transparency builds conversion in premium tiers.
- Sporting Goods Stores:Dick's Sporting Goods and REI-equivalent chains anchor North American insulated bottle placement, with seasonal floor space allocations tied to outdoor recreation calendars.
- Supermarkets:Impulse-driven placement of entry-level non-insulated formats competes on shelf price against private label alternatives.
- Specialty Shops:Outdoor gear boutiques and zero-waste retailers curate premium assortments with repair and refill service attachments.
Online Retailers handles the majority of throughput; Specialty Shops is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and health-conscious consumers drive demand concentration across major economies, with regulatory bans on plastic alternatives accelerating stainless steel adoption in urban centers and outdoor recreation corridors.
United States
Gym culture expansion and corporate wellness programs pull 32 oz and 40 oz insulated formats into mainstream procurement. State-level Bisphenol A prohibitions under California and New York statutes eliminate polycarbonate competition. Manufacturing specification influence flows from Guangdong province exporters through Los Angeles and Long Beach port clusters.
China
Domestic health consciousness and outdoor recreation participation create dual demand engines for premium vacuum-insulated products. SAMR enforcement of GB standards for food-contact metals shapes fabrication protocols across the sector. Zhejiang and Guangdong manufacturing belts concentrate over seventy percent of global capacity within Shenzhen's industrial radius.
Germany
REACH SVHC compliance mandates and extended producer responsibility frameworks elevate refurbishment service economics. ECHA substance evaluation roadmaps accelerate supplier audits for chromium VI content in decorative finishes. Bavarian and North Rhine-Westphalian distributors anchor European wholesale channels for bare 304-grade stainless assortments.
Japan
Advanced vacuum insulation technology leadership and precision manufacturing traditions sustain premium export positioning. METI industrial standards and JIS certification requirements filter market entry for foreign competitors. Osaka and Nagoya industrial corridors host vertically integrated producers with captive electropolishing capabilities.
India
Tier-2 and tier-3 city middle-class awareness of plastic contamination risks opens first-mover positioning for insulated bottle entrants. FSSAI food-contact safety notifications and BIS quality mandates shape import specifications. Maharashtra and Gujarat trading hubs concentrate distribution infrastructure for domestic brand penetration.
Stainless Steel Water Bottles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands dominant share. The competitive map organizes around three archetypes: vertically integrated manufacturers with captive steel processing, brand-marketing specialists leveraging outsourced fabrication, and direct-to-consumer digital natives unbundling traditional wholesale structures. Capacity expansion and strategic channel partnerships constitute the dominant competitive moves, with players securing sporting goods retail placement or building subscription-based institutional contracts.
Within the premium-tier vector, Tiger Corporation and Zojirushi Corporation occupy positions exemplifying Japanese precision manufacturing heritage, while Thermos L.L.C. anchors North American distribution relationships. These entities represent archetypes of technology-led insulation performance and deep retail channel anchoring respectively, illustrating how geographic manufacturing traditions translate into differentiated market positioning without requiring scale dominance.
| Leading Market Players |
|---|
| Klean Kanteen, Inc. |
| Tiger Corporation |
| Thermos L.L.C. |
| Bulletin Brands, Inc. |
| BRITA GmbH |
| Zojirushi Corporation |
| Sigg Switzerland AG |
| Cool Gear International, LLC. |
| YETI COOLERS, LLC. |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang manufacturing clusters concentrate over seventy percent of global fabrication capacity within two hundred kilometers of Shenzhen, anchoring margin pools in vacuum insulation tiers where electropolishing complexity and copper-plated inner wall construction justify sustained premiums over commodity single-wall alternatives.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA-grade and REACH-compliant bare 304-grade stainless finishes commanding substantial premiums over uncertified coated variants. Three-tier pricing structure across premium, standard, and economy levels reflects insulation performance, surface treatment grade, and channel positioning. Cost compression in non-insulated tiers is intensifying because Indonesian and Philippine nickel supply disruptions feed directly into 18/8 alloy input volatility. Institutional buyers in Indian schools and corporate catering programs exhibit highest price sensitivity, while fitness enthusiasts in North America and China demonstrate lowest sensitivity due to app-integrated loyalty mechanisms.
Supply Chain Analysis
Export-control scrutiny on advanced vacuum insulation equipment limits technology transfer to emerging manufacturing bases, preserving performance advantages for Japanese and Chinese incumbents with captive electropolishing capabilities. Supply draws from China, Japan, and South Korea for precision-formed austenitic steel components and vacuum pump systems. Raw material dependencies center on Indonesian nickel ore, chromium from South African mining operations, and copper for thermal retention plating. Single-source vulnerability concentrates in Guangdong-Zhejiang fabrication corridors where skilled vacuum seal technicians command wage premiums. Distribution runs through Los Angeles and Long Beach port clusters into North American sporting goods retail, with direct-to-consumer digital storefronts bypassing wholesale margin stacking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
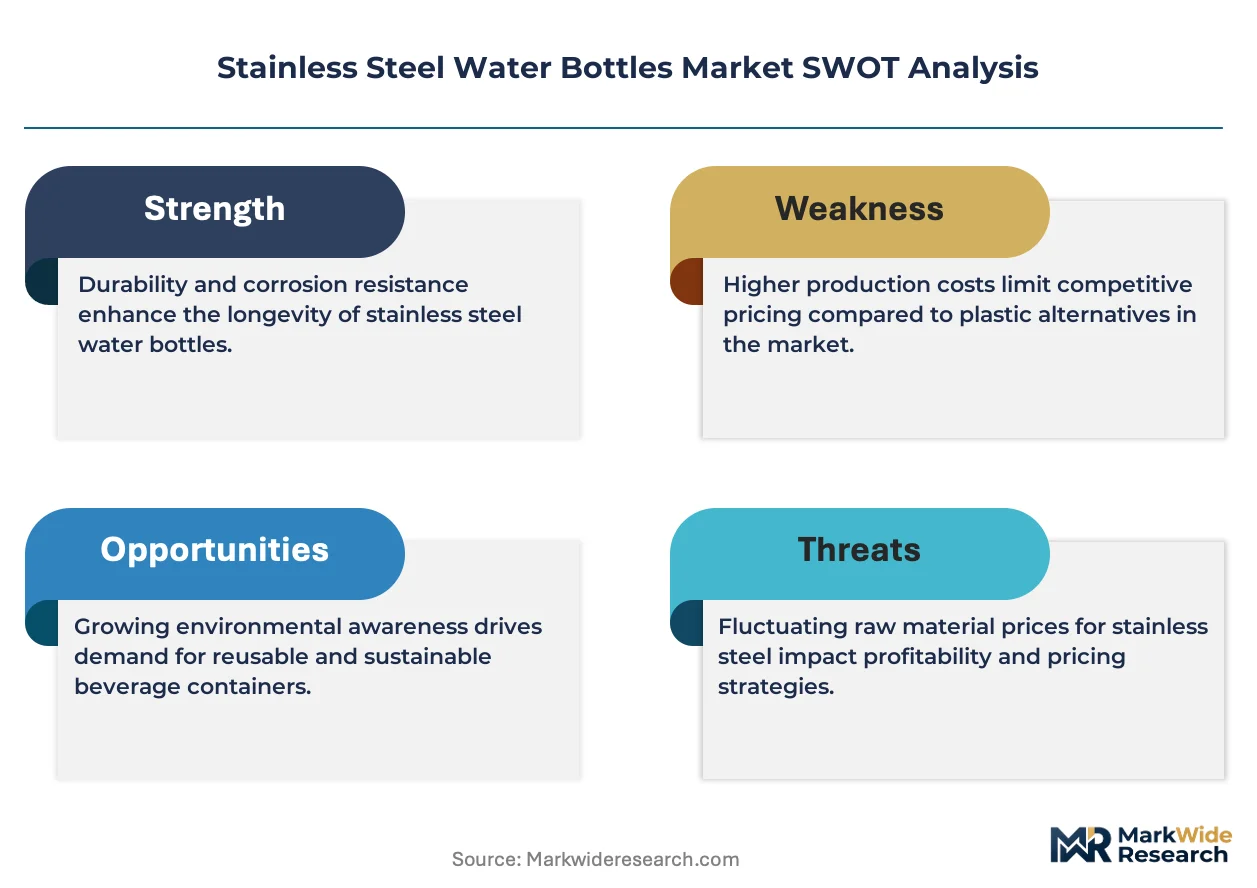
The stainless steel water bottle market offers defensive moats through regulatory entrenchment, as multi-jurisdiction certification timelines extending eight to fourteen months create switching costs that protect incumbent positioning against rapid competitive entry.
For Market Incumbents: Harden certification护城河 by accelerating REACH SVHC pre-compliance audits and securing FDA master file documentation ahead of ECHA substance evaluation roadmaps. Deepen backward integration into captive electropolishing capacity to offset vacuum seal technician wage premiums compressing assembly margins. Threat exposure concentrates in direct-to-consumer digital natives unbundling wholesale dependency through subscription hydration service contracts. For New Entrants and Emerging Players: Establish a beachhead in Indian tier-2 and tier-3 cities where FSSAI notification compliance remains uneven and first-mover positioning in insulated bottles faces limited domestic competition. Target corporate wellness program procurement in North American tech campuses where leasing models are displacing capital purchases. Go-to-market angle should emphasize refurbishment service attachments anticipating EU extended producer responsibility mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed brand-marketing specialists lacking captive manufacturing, presenting roll-up opportunities for vertically integrated Asian producers seeking North American channel control. Long-term viability hinges on durability of fitness app partnership ecosystems and smart bottle data monetization. Signal to watch is adoption velocity of NFC-embedded temperature monitoring formats in corporate wellness pilot programs.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Brand-owned digital storefronts bypass Dick's Sporting Goods and REI wholesale margin stacking. |
| Sustainability Repositioning | REACH-compliant bare 304-grade finishes preempt ECHA authorization barriers in European procurement. |
| Premium Tier Introduction | Smart bottle integrations with hydration tracking apps capture 15-20% price premiums in fitness segments. |
| Distribution Channel Expansion | Specialty zero-waste retailers enable repair and refill service attachments in urban corridors. |
| Backward Integration | In-house electropolishing capabilities reduce dependency on Guangdong surface treatment clusters. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with stainless steel bottle procurement managers at North American sporting goods retailers, supply planners at Chinese manufacturing clusters, and sustainability officers at European distributors; alongside secondary validation through SAMR GB standard filings, ECHA REACH substance databases, FDA food-contact material registrations, and customs trade records. Bottom-up triangulation against top-down category sizing ensured segment-level coherence.
Forecast inputs span insulation technology tier, end-user fitness intensity, distribution channel digitization, and regional regulatory enforcement stringency across the projection horizon. CAGRs emerged from elasticity modeling against nickel price volatility scenarios and vacuum insulation penetration curves. Industry-specific inputs include electropolishing capacity utilization rates and smart bottle app partnership formation velocity.
Stress conditions across Indonesian nickel supply disruptions, REACH SVHC list expansion timing, and vacuum seal technician wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume current FDA, SAMR, and ECHA enforcement trajectories. Material shifts in extended producer responsibility mandate scope or Bisphenol A prohibition acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
North America Glassware Market
Household Items
Bagless Vacuum Cleaner Market
Household Items
Wax Removal Aids Market
Household Items
US Digital Showers Market
Household Items
Shoe Dryer Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
Smart Fork Market
Household Items
Aquarium Hydrometers Market
Household Items
Barbecue Grill Market
Household Items
Japan Faucets Market
Household Items
Air Purifier Market
Household Items
Middle East Handheld Vacuum Cleaner Market
Household Items
Robot Mops Market
Household Items
Toilet Paper Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Canada Digital Showers Market